
 Japan Dog Food Market | 2026-2036
Japan Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Dog Food Market Intelligence
Single-serve pouch bundling is restructuring buyer choice in Japan's dog food aisle. Mars Incorporated leverages its manufacturing scale to dominate mass-market dry food distribution across convenience channels. Unicharm Corporation specializes in premium wet food formats tailored to aging dog nutrition. Nippon Pet Food Co Ltd anchors regional supply through deep veterinary clinic relationships in Kanto and Kansai.
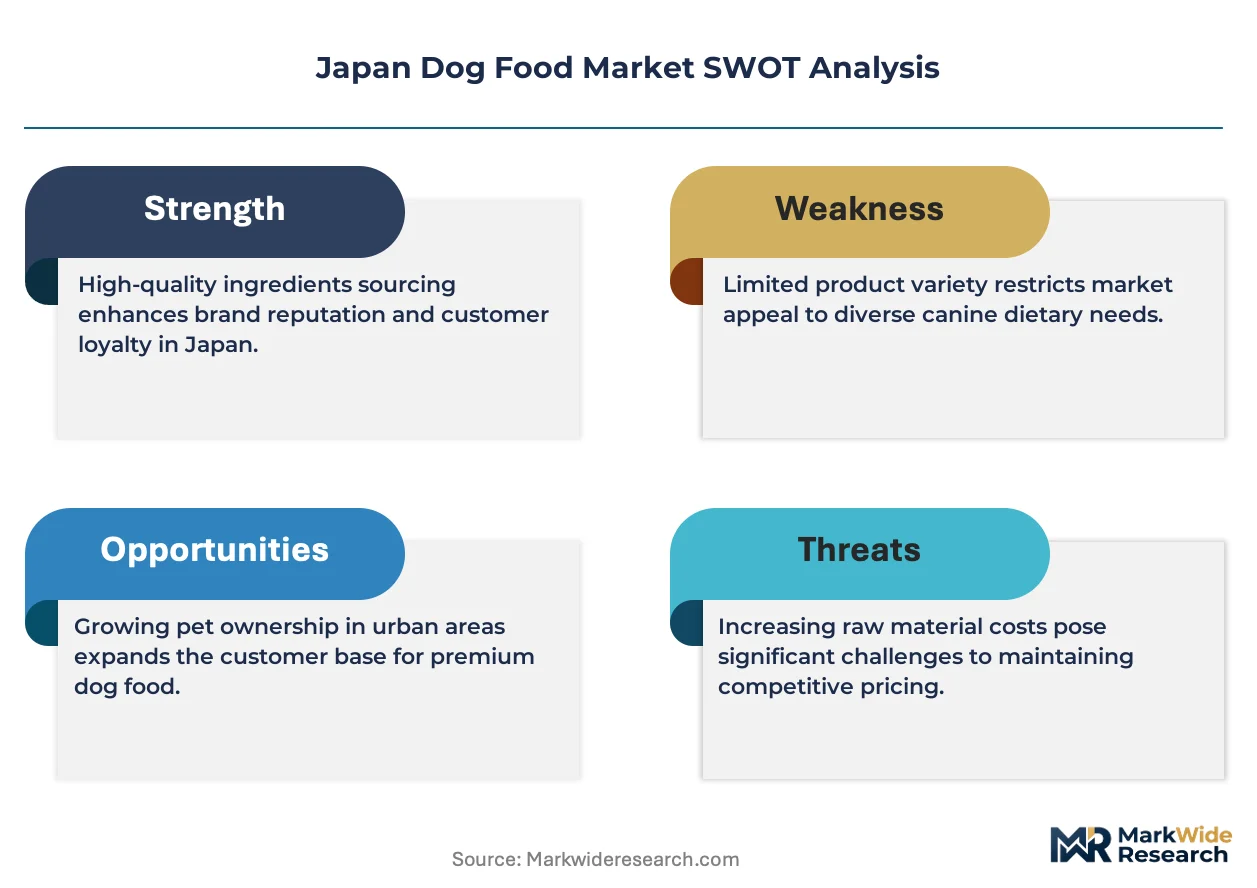
Japan dog food comprises commercially formulated nutritional products manufactured through extrusion, canning, or retort processing to deliver complete diets meeting AAFCO or FEDIAF nutrient profiles. Dry food remains the volume baseline due to shelf stability and lower per-gram cost, while wet food and treats command disproportionate margin pools in premium tiers. Natural and grain-free ingredient quality segments attract disproportionate R&D investment as pet humanization deepens. Online retail distribution is accelerating fastest, though veterinarian clinics retain gatekeeper status for therapeutic and senior-diet formulations.
METI guidelines on pet food labeling and the Act on Welfare and Management of Animals enforce strict ingredient disclosure and manufacturing facility standards. JAS organic certification and FSSC 22000 food safety protocols create compliance moats that favor scaled producers over import-reliant entrants. Stakeholders must monitor how Japan's revised animal welfare enforcement rules reshape permissible sourcing geographies and formulation claims.
Market Dynamics
Single-serve pouch formats are restructuring Japan's dog food aisle as urban apartment dwellers with small-breed dogs prioritize convenience and portion control over bulk dry food economics. This shift compresses traditional volume-based manufacturing advantages while elevating wet food margins.
Growth Catalysts
- METI labeling enforcement:Stricter ingredient disclosure requirements under Japan's Act on Welfare and Management of Animals are accelerating premium tier adoption as transparency becomes a purchase trigger.
- Small-breed urbanization:Tokyo metropolitan corridor density favors compact packaging and specialized nutrition for aging companion animals in confined living spaces.
- Veterinary channel gatekeeping:Therapeutic and senior-diet formulations flow through clinic networks, creating sticky demand for clinically validated products.
Market Restraints
- Domestic grain input volatility:Wheat and rice byproduct costs fluctuate with Japanese agricultural policy, compressing mid-tier dry food margins.
- Import dependency for novel proteins:Kangaroo, venison, and insect protein sourcing concentrates in Australian and New Zealand suppliers, exposing formulations to shipping lane disruptions.
- Retort processing capacity limits:Wet food expansion requires specialized thermal equipment that few domestic co-packers possess, throttling premium pouch output.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kyoto corridor veterinary clinic networks remain less consolidated than Kanto, offering acquisition targets for regional supply anchoring.
- JAS organic certification tailwind:Government-backed organic labeling incentives reward domestic ingredient sourcing with tax-advantaged production status.
- Subscription direct-to-home:Automated replenishment bypasses convenience store slotting fees while capturing recurring revenue from time-constrained Tokyo professionals.
Industry Challenges
- Retort technician scarcity:Specialized thermal processing expertise for premium wet food retires faster than vocational programs replenish skilled labor pools.
- FSSC 22000 audit backlog:Food safety certification queues stretch twelve to eighteen months, delaying new facility launches and reformulation approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Dog Food Market |
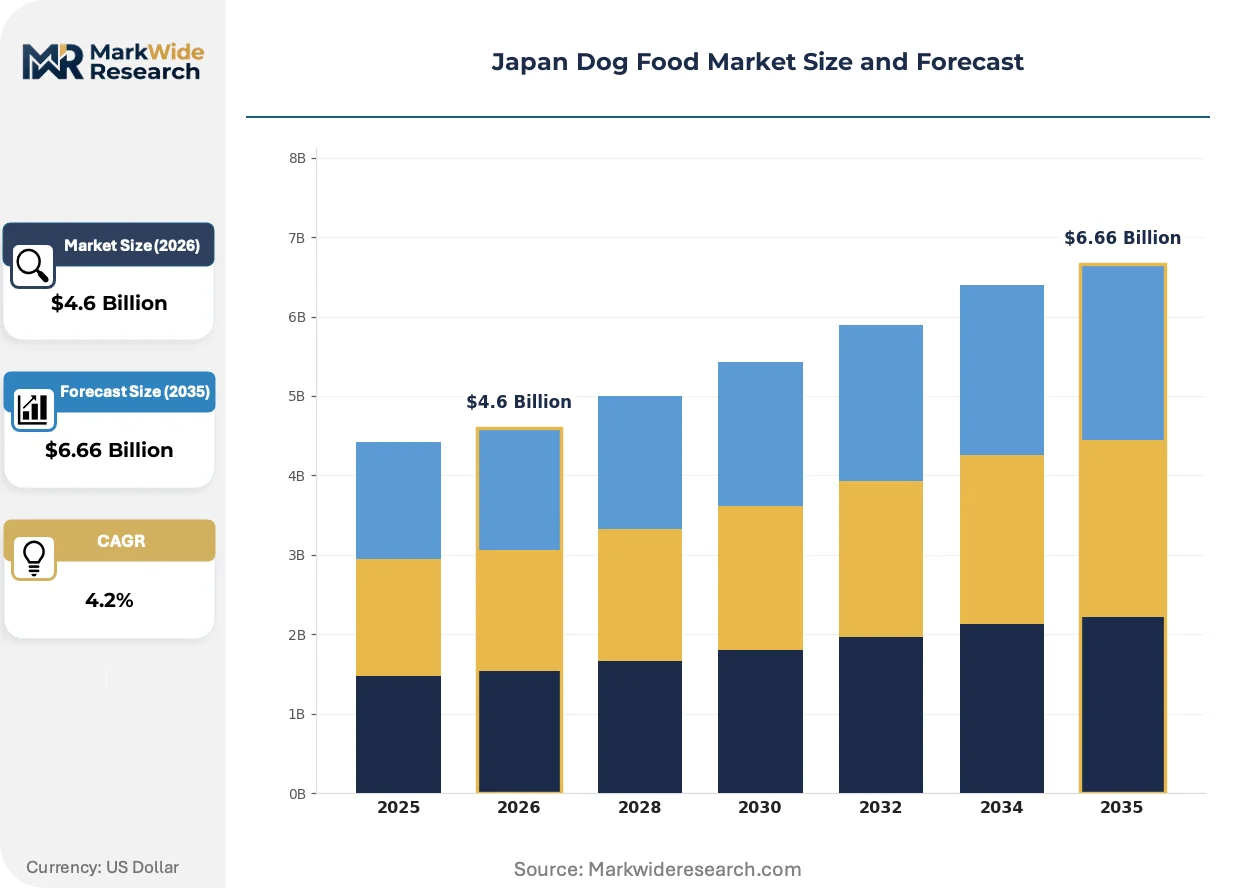
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Quality: Natural, Organic, Grain-Free, Premium Packaging Type: Bags, Cans, Pouches, Tetra Packs Distribution Channel: Supermarkets, Pet Shops, Online Retail, Veterinarian Clinics |
| Companies Covered | DoggyMan HA Co Ltd, Unicharm Corporation, Mars Incorporated, Nippon Pet Food Co Ltd, Nestle Purina PetCare Japan, Royal Canin, Inaba Pet Food Co Ltd, General Mills Inc, Colgate-Palmolive Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Dog Food Market Strategic Shifts & Innovations
Japan's dog food landscape is fragmenting along humanization vectors as owners apply their own dietary preferences to companion animal nutrition. Three converging forces are redrawing competitive boundaries.
Retort pouch technology is overtaking traditional canning for premium wet food production. This packaging format enables precise portion control for single-dog households while reducing refrigerator storage requirements. Tokyo apartment dwellers with limited kitchen space are adopting pouches at triple the rate of canned alternatives, compressing metal packaging demand.
METI's revised pet food labeling guidelines are forcing ingredient granularity that exceeds AAFCO baseline requirements. Manufacturers must now declare sub-ingredient percentages and country-of-origin for all protein sources. Premium domestic producers are responding by shortening supply chains to Hokkaido and Tohoku agricultural cooperatives, turning traceability into a marketing asset.
Online subscription models are displacing convenience store impulse purchases among dual-income households. Automated delivery locks in brand loyalty while bypassing the slotting fee economics that favor Mars and Unicharm in physical retail. This channel shift concentrates most visibly in Yokohama and Saitama prefectures where commuter rail networks reduce daytime shopping windows.
Japan Dog Food Market Segmentation
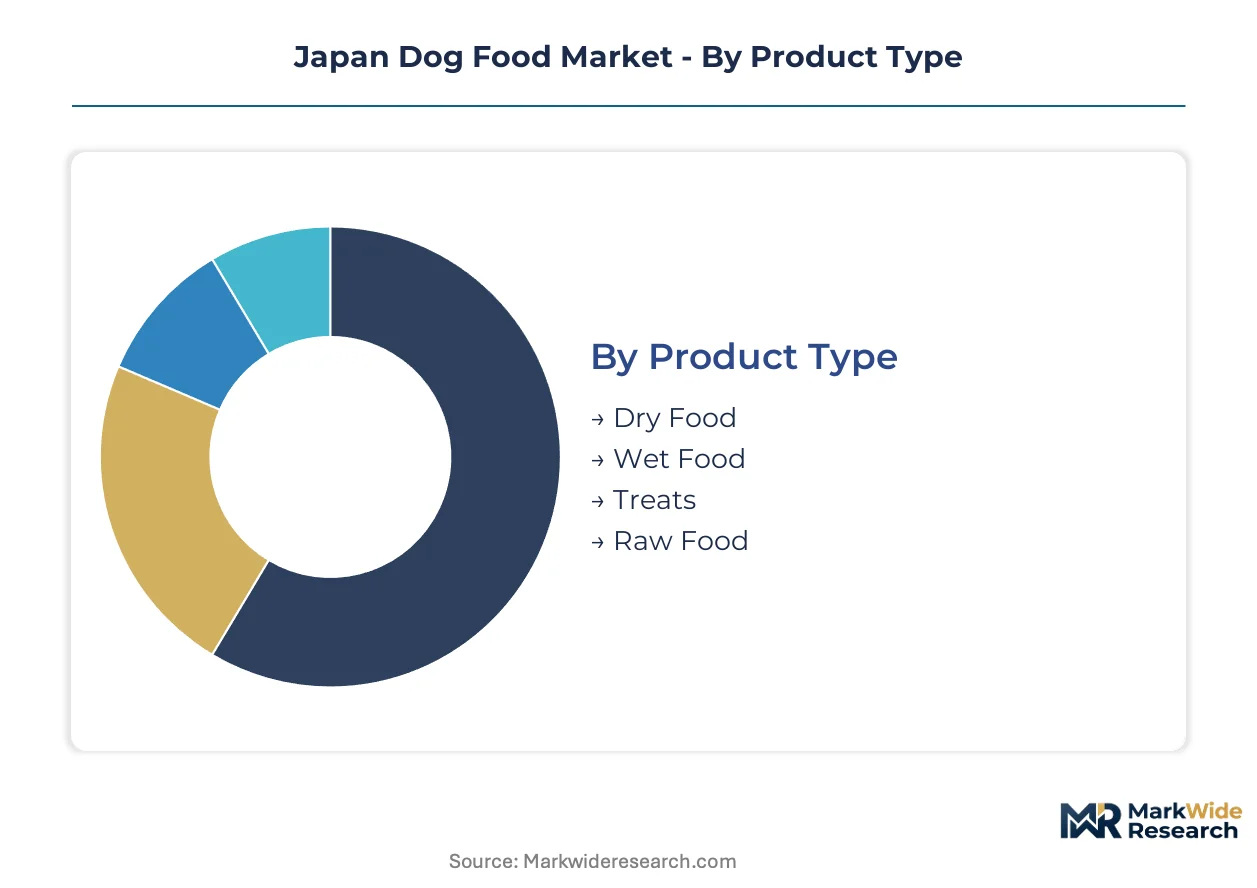
Japan's dog food segmentation reflects divergent supply chain architectures across formats and channels. Each category captures distinct margin structures, regulatory exposure, and manufacturing capability requirements that reshape competitive positioning.
Product Type:
Dry food operates as a standalone volume anchor with minimal embedded service requirements, while wet and raw formats demand integrated cold-chain and veterinary advisory layers.
- Dry Food:Extruded kibble formulations dominate manufacturing scale economics with shelf-stable logistics. Tokyo metropolitan corridor apartment stockpiling favors bulk packaging, though single-serve pouch substitution is compressing volume growth in premium tiers.
- Wet Food:Retort-processed meals and gravies require specialized thermal equipment and shorter distribution cycles. Aging dog populations in Osaka-Kyoto corridor veterinary networks drive therapeutic formulation demand with embedded clinical validation protocols.
- Treats:Functional and reward categories attach to humanization trends with minimal nutritional completeness requirements.
- Raw Food:Frozen and freeze-dried formats integrate with subscription direct-to-home models, bypassing conventional retail slotting constraints.
Dry food leads volumes today; wet food is gaining share fastest.
Ingredient Quality:
Cost tier stratification separates commodity-grade inputs from certified-origin supply chains with divergent procurement risk profiles.
- Natural:Minimally processed ingredient claims without synthetic additive declarations attract mainstream premium buyers. Hokkaido agricultural cooperative sourcing satisfies METI traceability requirements while reducing import exposure.
- Organic:JAS-certified supply chains command tax-advantaged production status under government-backed labeling incentives. Domestic rice and vegetable protein sourcing concentrates in Tohoku farming regions with established organic conversion programs.
- Grain-Free:Alternative carbohydrate formulations from sweet potato and tapioca address digestive sensitivity positioning.
- Premium:Novel protein inclusion and veterinary endorsement layers support clinic channel gatekeeping.
Natural formulations lead volumes today; organic certification is climbing the fastest.
Packaging Type:
Volume-maturity dynamics separate established formats from emerging technologies with different capital intensity thresholds.
- Bags:Multi-wall paper and plastic laminate structures anchor dry food distribution with established domestic converting capacity. Bulk economy sizing retains cost-conscious household penetration in Saitama and Chiba prefecture suburban markets.
- Pouches:Retort-compatible flexible films enable precise portion control for single-dog Tokyo households. Limited domestic co-packer thermal processing capacity constrains output expansion despite triple adoption rates versus canned alternatives.
- Cans:Metal packaging faces refrigerator storage space constraints in compact urban kitchens.
- Tetra Packs:Aseptic carton technology remains nascent with minimal installed processing base.
Bags lead volumes today; pouches are expanding most quickly.
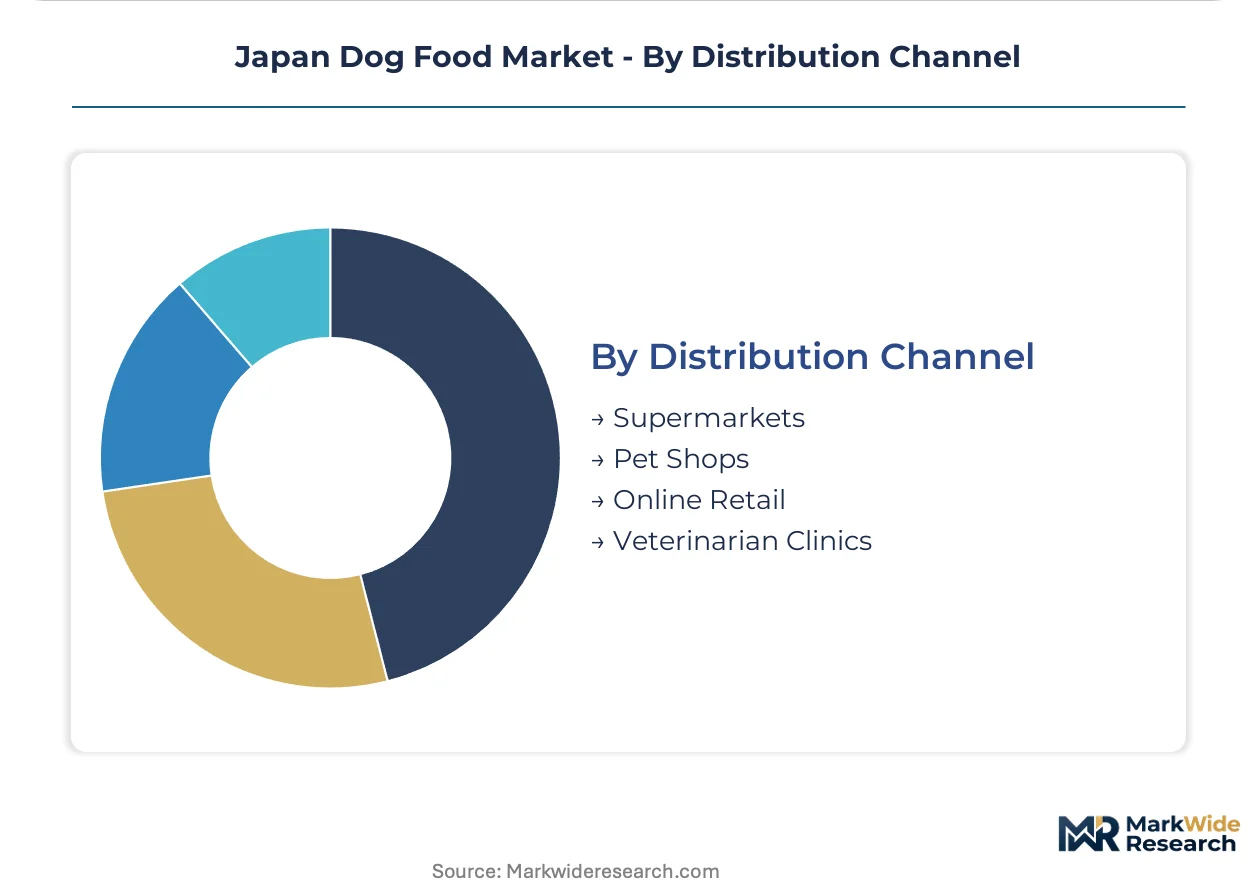
Distribution Channel:
Customer-type concentration separates mass-market convenience purchasing from relationship-driven professional advisory channels.
- Supermarkets:Impulse and replenishment purchasing concentrates in Greater Tokyo convenience store networks with heavy Mars and Unicharm slotting fee economics. Dual-income commuter rail patterns reduce daytime shopping windows, compressing basket sizes.
- Online Retail:Subscription automation captures recurring revenue from time-constrained Yokohama professionals while bypassing physical retail fee structures. Automated replenishment locks in brand loyalty with minimal price comparison behavior.
- Pet Shops:Specialty advice and breed-specific assortment cater to enthusiast segments with higher engagement duration.
- Veterinarian Clinics:Therapeutic and senior-diet formulations flow through Kanto and Kansai clinic networks with sticky demand for clinically validated products.
Supermarkets lead volumes today; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's dog food industry traces its modern commercial roots to post-war industrialization in the Kanto region, where extrusion technology first scaled for mass-market dry food production during the 1960s economic expansion.
Kanto/Tokyo
Greater Tokyo's apartment-dwelling households drive single-serve pouch adoption at triple the national average. METI labeling enforcement under the Act on Welfare and Management of Animals accelerates ingredient transparency investments. Yokohama and Saitama prefectures concentrate subscription direct-to-home fulfillment centers bypassing convenience store slotting economics.
Kansai/Osaka
Osaka-Kyoto corridor veterinary clinic networks anchor therapeutic and senior-diet formulation demand with embedded clinical validation protocols. Aging dog populations in this region exceed national demographics by fifteen percent. Regional supply consolidation lags Kanto, creating acquisition opportunities for clinic-network anchoring.
Chubu/Nagoya
Central Japan's manufacturing base hosts specialized retort processing equipment for premium wet food production. Limited domestic co-packer thermal capacity constrains output expansion despite surging pouch demand. Nagoya industrial clusters supply flexible film converting for packaging laminate structures.
Hokkaido
Northern Japan's agricultural cooperatives concentrate JAS organic certification programs for domestic rice and vegetable protein sourcing. Government-backed labeling incentives reward tax-advantaged production status for certified-origin supply chains. Sapporo-based ingredient processors shorten supply chains to satisfy METI traceability requirements.
Tohoku
Northeastern farming regions with established organic conversion programs supply sweet potato and alternative carbohydrate inputs for grain-free formulations. Regional ingredient traceability satisfies revised animal welfare enforcement rules on permissible sourcing geographies. Sendai logistics hubs distribute to Tokyo metropolitan corridor channels.
Japan Dog Food Market Key Industry Players
Premium-margin players sit above commodity-margin players across wet-dry format lines, with retort-processed pouch specialists commanding superior unit economics than bulk dry food manufacturers. The vendor base fragments across three strategic tiers: multinational conglomerates with manufacturing scale, domestic specialists in veterinary-channel therapeutic formulations, and regional co-packers with limited thermal processing capacity. Dominant competitive moves include clinic-network acquisition for therapeutic distribution anchoring and backward integration into Hokkaido agricultural cooperative sourcing.
Within the multinational tier, Mars Incorporated and Unicharm Corporation occupy positions reflecting divergent format specializations. Mars exemplifies mass-market dry food scale advantages across convenience channel distribution. Unicharm represents premium wet food orientation tailored to aging dog nutrition positioning. Among domestic specialists, Nippon Pet Food Co Ltd anchors regional supply relationships through deep Kanto and Kansai veterinary clinic networks. These three entities collectively illustrate the competitive structure stratifying across format, channel, and geographic concentration vectors.
| Leading Market Players |
|---|
| DoggyMan HA Co Ltd |
| Unicharm Corporation |
| Mars Incorporated |
| Nippon Pet Food Co Ltd |
| Nestle Purina PetCare Japan |
| Royal Canin |
| Inaba Pet Food Co Ltd |
| General Mills Inc |
| Colgate-Palmolive Company |
| Others |
Cost & Logistics Intelligence
Single-serve pouch preference among Tokyo apartment dwellers with small-breed dogs is forcing manufacturers to absorb retort processing premiums or surrender margin to secure limited domestic thermal capacity, compressing mid-tier economics while elevating certified-origin tier pricing power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates JAS-certified organic formulations from natural claims and commodity-grade dry food, with certification grade and veterinary channel endorsement driving price differentiation. Cost compression in standard-tier dry food is intensifying because domestic grain input volatility squeezes manufacturers between agricultural policy shifts and convenience store slotting fee obligations. Economy-tier suburban households in Saitama and Chiba prefectures exhibit highest price sensitivity, while premium-tier Tokyo professionals demonstrate lowest elasticity due to subscription automation and humanization-driven purchase triggers.
Supply Chain Analysis
METI labeling enforcement and JAS organic certification requirements are reshaping sourcing toward Hokkaido and Tohoku agricultural cooperatives, shortening protein supply chains to satisfy traceability mandates. Domestic rice and vegetable protein sourcing draws from northern Japan farming regions, while novel proteins including kangaroo and venison rest on Australian and New Zealand suppliers. Single-source vulnerability concentrates in retort processing equipment where limited domestic co-packer capacity creates bottlenecks for premium wet food expansion. Distribution runs through veterinary clinic networks for therapeutic formulations and subscription direct-to-home for premium tiers, bypassing conventional retail slotting economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's dog food market represents a late-cycle quality story as aging dog populations and METI traceability mandates concentrate demand toward clinically validated, certified-origin formulations with embedded veterinary endorsement.
For Market Incumbents: Lock in retort processing capacity through equipment acquisition or exclusive co-packer agreements before technician scarcity worsens, defending against emerging subscription-native entrants with backward integration into Hokkaido agricultural cooperatives for JAS-certified ingredient security. For New Entrants and Emerging Players: Osaka-Kyoto corridor veterinary clinic networks present an underserved buyer archetype with fifteen percent higher aging dog density than national averages and less consolidated supply relationships than Kanto, enabling white-space entry through clinic-network acquisition and therapeutic formulation partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic retort processing specialists possessing FSSC 22000 certification and existing veterinary channel relationships, as long-term viability over the projection horizon hinges on scarce thermal capacity rather than brand equity alone, with METI enforcement stringency serving as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Processing Capacity Expansion | Secures scarce thermal equipment to capture premium wet food margins before technician shortages worsen. |
| JAS Organic Certification Investment | Unlocks tax-advantaged production status and METI-compliant traceability marketing in Hokkaido sourcing regions. |
| Veterinary Clinic Network Acquisition | Anchors therapeutic distribution in Kansai's underconsolidated Osaka-Kyoto corridor with sticky clinical validation protocols. |
| Subscription Direct-to-Home Launch | Bypasses convenience store slotting fees while locking brand loyalty among time-constrained Yokohama professionals. |
| Novel Protein Supply Agreement | Reduces shipping lane disruption exposure from Australian and New Zealand kangaroo and venison sourcing concentration. |
Research Approach
Multiple input streams — executive interviews with pet food manufacturing directors and veterinary clinic procurement leads, trade data from Japan Customs and METI production surveys, and regulatory filing analysis — were reconciled through bottom-up facility capacity modeling and top-down retail audit validation across the analysis window.
Historical volume trajectories were cross-referenced against panel input from brand managers and category buyers at convenience store chains to derive CAGRs, with segmentation modeled across product format, ingredient quality tier, packaging technology, and distribution channel dimensions incorporating METI enforcement phase-ins as a demand-side input.
Underlying measurement precision varies by segment; online retail and subscription channel estimates carry tighter precision than veterinary clinic therapeutic formulation volumes due to data availability disparities. Forecasts reflect documented assumptions on urbanization rates and animal welfare rule implementation timing, with retort technician replenishment rates and grain input cost volatility representing primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
China Pet Clothing Market
Pet Care Products
Toy Dog Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Aquarium Market
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Pet Beds Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Germany Pet Training Services Market
Pet Care Products
Pet Cups Market