
 Smart Memory Foam Market | 2026-2036
Smart Memory Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Memory Foam Market Analysis
Asset-light leasing models for premium sleep systems are reshaping competitive entry barriers in the smart memory foam sector. Tempur Sealy International leverages its vertical manufacturing footprint to sustain margin control across North American distribution. Sleep Number Corporation differentiates through adjustable air-foam hybrid platforms that anchor its direct-to-consumer channel dominance. Purple Innovation specializes in hyper-elastic polymer grids that compete against traditional viscoelastic formulations.
Smart memory foam denotes viscoelastic polyurethane formulations integrated with sensor arrays, phase-change materials, or thermo-active polymers that modulate firmness, temperature, or pressure distribution in response to body heat and movement. Manufacturing employs open-cell gas-injection processes with density gradients between 40-80 kg/m³ to achieve calibrated slow-recovery mechanics for spinal alignment and pressure redistribution. Mattresses command the dominant value share as consumers prioritize integrated sleep-tracking hardware within foundation layers. Healthcare applications represent the fastest-expanding demand pool as hospitals and long-term care facilities adopt pressure-ulcer prevention protocols. Distribution through B2B channels captures concentrated margin pools from hospitality procurement contracts and institutional healthcare tenders.
FDA Class II medical device oversight governs therapeutic mattress claims in the United States, while EU MDR and REACH compliance shape material safety and biocompatibility standards for European market access. EPA VOC emissions regulations for polyurethane foam production constrain manufacturing site locations and capital deployment decisions. Stakeholders must monitor evolving interoperability standards between embedded sleep sensors and health data platforms to preserve product relevance as regulatory frameworks for digital health devices mature.
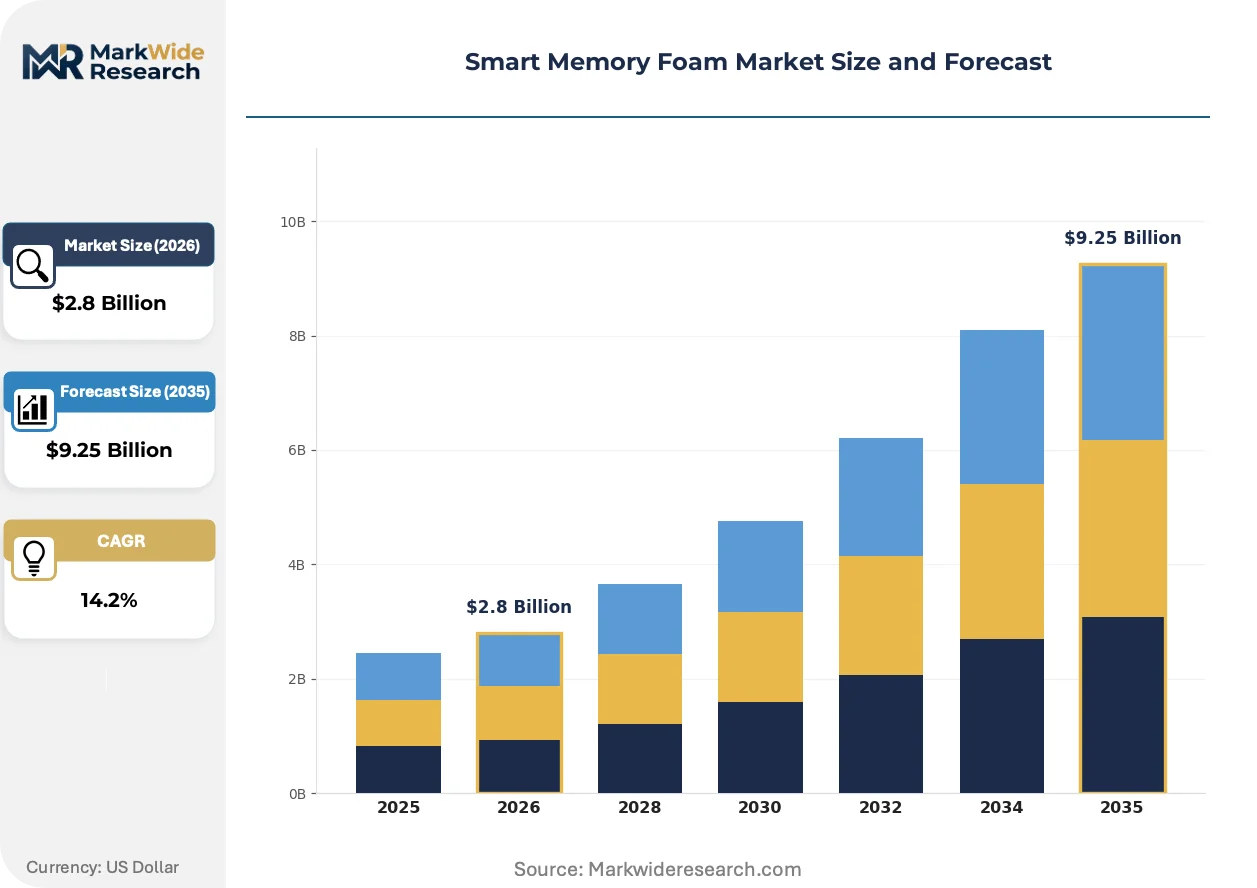
Market Dynamics
Sensor-embedded foam architectures are compressing mattress replacement cycles as consumers treat sleep systems as connected wellness hardware rather than passive furniture. This hardware-software convergence is redrawing competitive boundaries between traditional foam manufacturers and digital health platforms.
Growth Catalysts
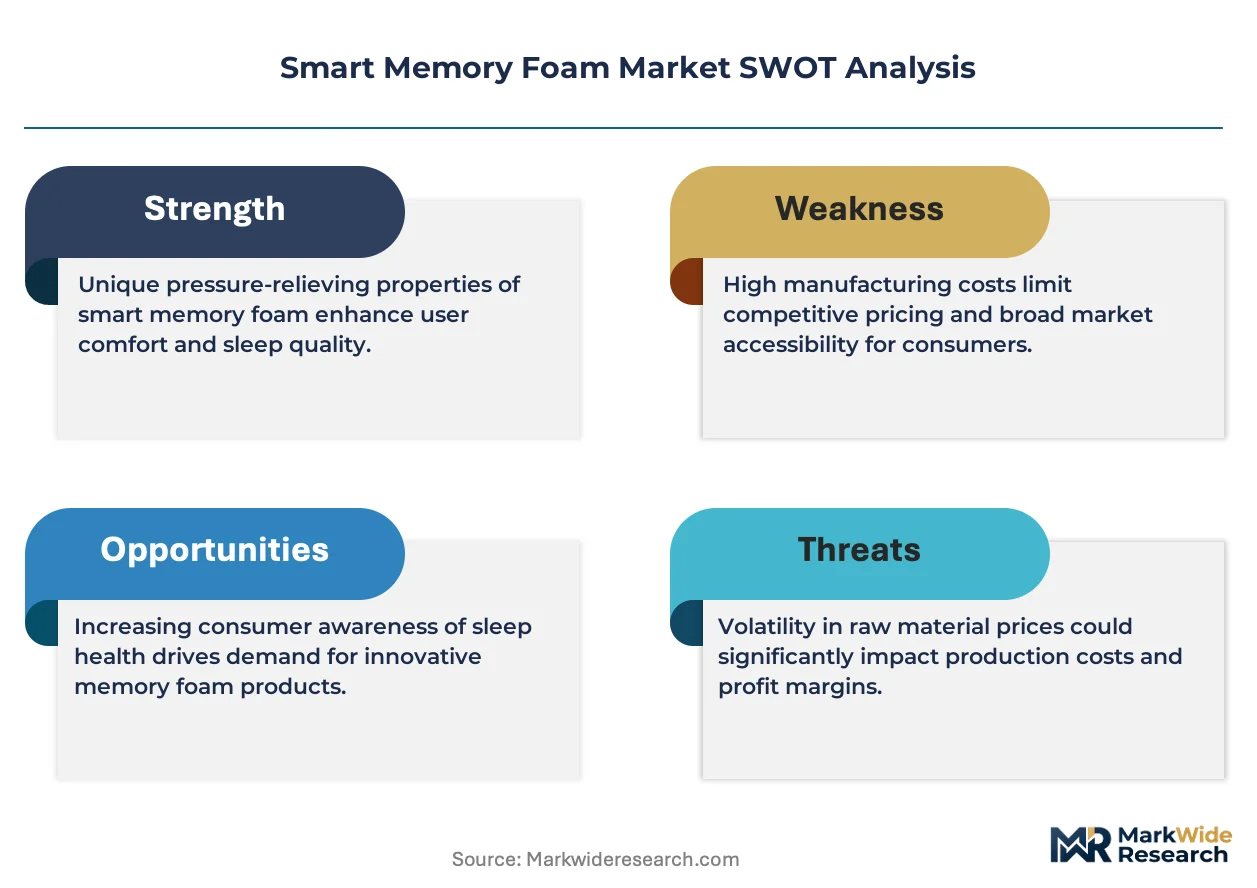
- EU Medical Device Regulation pressure-ulcer protocols:Healthcare facilities across Germany, France, and the Netherlands are mandating pressure-relief surfaces in long-term care wards. This clinical procurement wave is pulling thermo-responsive polymer formulations into institutional tender specifications.
- Toluene diisocyanate price stabilization:Key input chemistry for viscoelastic polyurethane has settled after 2022 volatility. Foam converters in Belgium and Italy are restoring margin visibility and expanding open-cell gas-injection capacity.
- Phase-change material integration:Microencapsulated paraffin wax additives from specialty chemical suppliers are enabling active temperature modulation. Residential buyers in the United States are prioritizing these thermo-active layers over conventional gel-infused alternatives.
Market Restraints
- Polyether polyol supply concentration:Three petrochemical complexes in the US Gulf Coast and Rotterdam harbor control over 60% of specialized feedstock for slow-recovery foam. Any force majeure event cascades through converter pricing within 90 days.
- FDA Class II device pathway friction:Therapeutic mattress claims require 510(k) clearance with clinical validation timelines stretching 18-24 months. This regulatory drag limits hardware startups from entering medical-grade segments.
- Adjustable air-bladder substitution:Sleep Number Corporation's air-foam hybrid platforms capture wellness-oriented buyers seeking firmness customization without foam heat retention. This alternative technology constrains pure memory foam premium pricing power.
Strategic Opportunities
- B2B hospitality procurement consolidation:Marriott International and Hilton Worldwide are centralizing mattress specifications across property portfolios. Direct contracts with foam manufacturers are displacing fragmented distributor relationships.
- Interoperability with Apple Health and Garmin Connect:Sleep sensor data streams are converging with established wellness platforms. Foam-embedded accelerometers and pressure mapping arrays that sync natively command 40% retail price premiums over closed-system alternatives.
- India PLI scheme for advanced materials:Domestic manufacturing incentives are attracting Evonik Industries and BASF to establish thermo-responsive polymer compounding facilities near Pune and Ahmedabad. Local production will serve price-sensitive Asian residential demand.
Industry Challenges
- Embedded firmware validation cycles:Sleep-tracking sensor arrays require IEC 62304 medical device software compliance. Engineering teams with dual expertise in polyurethane rheology and FDA digital health pathways command scarcity premiums that compress R&D budgets.
- REACH SVHC candidate list expansion:Evolving European Chemicals Agency restrictions on flame retardant additives force continuous formulation reformulation. Each substance substitution triggers 12-18 month re-certification timelines for existing product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Memory Foam Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mattresses, Pillows, Mattress Toppers, Cushions Application: Residential, Commercial, Healthcare, Automotive Distribution Channel: Online Retail, Offline Retail, Direct Sales, B2B End User: Consumers, Healthcare Facilities, Hotels, Corporate Offices |
| Companies Covered | Tempur Sealy International, Inc., Serta Simmons Bedding, LLC, Sleep Number Corporation, Kingsdown, Inc., Foam Factory, Inc., Restonic Mattress, Dorel Industries, Purple Innovation, LLC, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Memory Foam Market Emerging Trajectories
Material science breakthroughs and data architecture standards are converging to transform foam from passive cushioning into responsive wellness infrastructure. Three developments are compressing development timelines and expanding addressable use cases.
Machine learning inference at the edge is digitizing pressure distribution analysis. Embedded microcontrollers in foundation layers now process sleep-stage classification locally without cloud dependency. Hospitals in Massachusetts and California are piloting these systems for fall-risk prediction in geriatric wards. The technology is digitizing how clinical facilities justify capital expenditure on sleep surfaces through measurable outcome metrics rather than comfort claims.
EPA VOC emissions regulations for polyurethane foam production are constraining manufacturing site locations. The 2024 National Emission Standards for Hazardous Air Pollutants updates impose stricter methylene chloride and TDI capture requirements. Producers are responding by consolidating operations into fewer, larger facilities with advanced scrubber systems rather than distributed smaller plants. This regulatory compression favors capital-heavy incumbents over regional converters.
Direct-to-consumer subscription models are displacing traditional retail mattress replacement cycles. Casper Sleep and Purple Innovation have trained United States buyers to expect 100-night trial periods and seamless return logistics. This behavioral shift is forcing wholesale-dependent brands to build captive last-mile delivery infrastructure. The transformation is most visible in coastal metropolitan markets where apartment dwellers prioritize convenience over in-store testing.
Smart Memory Foam Market Segmentation
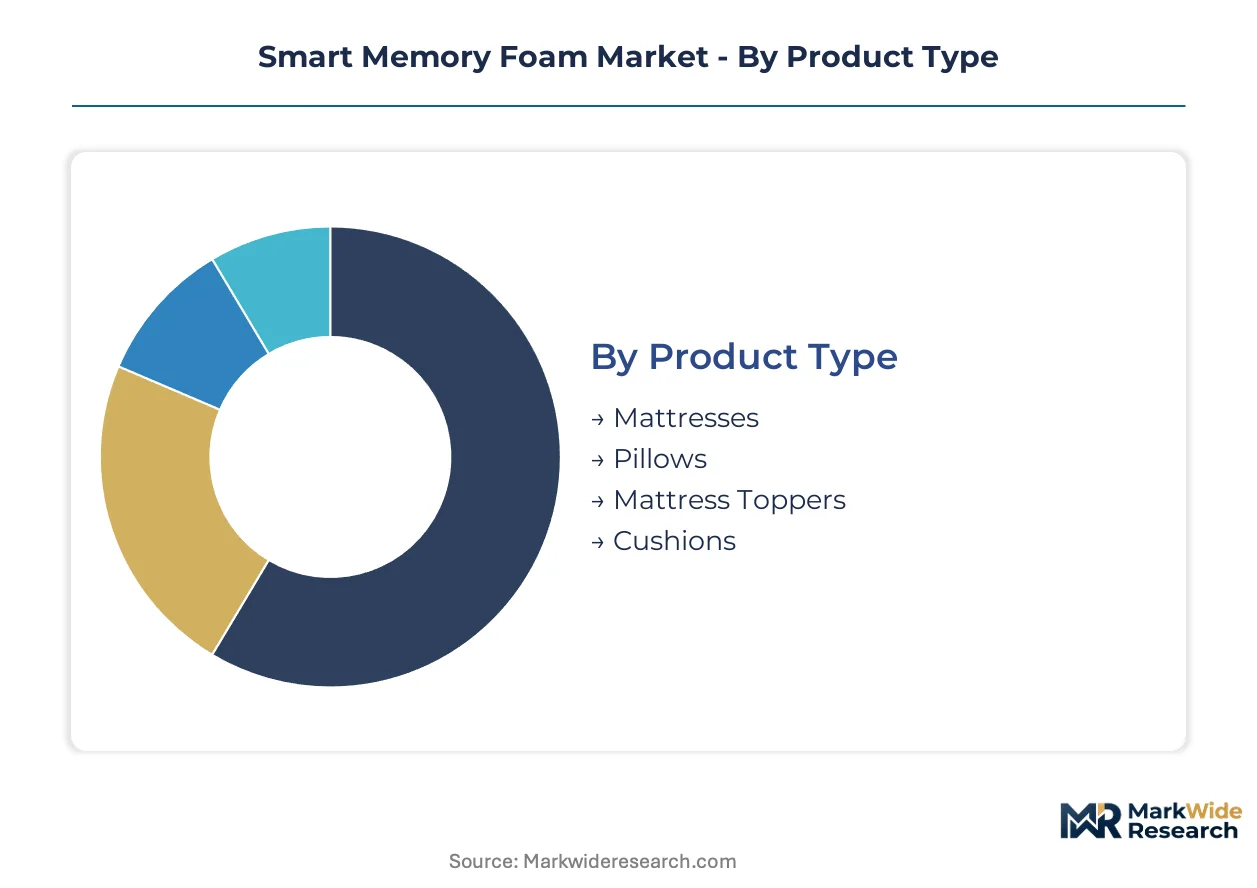
Smart memory foam markets fragment across product architectures, use environments, and procurement pathways. Each segmentation dimension reveals distinct margin structures, regulatory exposure, and technology integration requirements that shape competitive positioning.
Product Type:
Mature mattress platforms anchor revenue concentration while emerging accessories capture wellness-oriented replacement demand.
- Mattresses:Full-platform systems integrate sensor arrays, phase-change layers, and zoned density gradients between 40-80 kg/m³. United States residential buyers prioritize these for sleep-tracking hardware embedded in foundation layers, driving premium positioning over conventional foam alternatives.
- Pillows:Contoured viscoelastic designs with thermo-responsive polymer cores adapt neck support through body heat modulation. Demand concentrates in direct-to-consumer channels where trial periods and return logistics determine purchase conversion.
- Mattress Toppers:Retrofit solutions extend existing sleep surface lifecycles without full replacement investment.
- Cushions:Pressure-relief seating applications serve automotive and office ergonomic retrofit markets.
Mattresses handle the majority of throughput; pillows are expanding most quickly on share as consumers prioritize modular wellness upgrades.
Application:
Cost tier stratification separates premium integrated systems from commodity comfort replacements across residential and institutional deployments.
- Residential:Direct-to-consumer brands compete for mattress replacement cycles through subscription logistics and 100-night trial structures. United States coastal metropolitan markets show highest conversion for sensor-embedded platforms with Apple Health and Garmin Connect interoperability.
- Healthcare:Pressure-ulcer prevention protocols under EU MDR requirements are pulling thermo-responsive polymer formulations into institutional tender specifications across German and French long-term care facilities.
- Commercial:Hospitality procurement contracts with Marriott International and Hilton Worldwide are centralizing mattress specifications across property portfolios.
- Automotive:Ergonomic seating integration targets premium vehicle segments with climate-controlled foam architectures.
Residential captures the dominant value pool; healthcare is gaining share fastest through regulatory-mandated clinical procurement waves.
Distribution Channel:
Customer type determines channel economics, with institutional buyers demanding B2B contract structures and residential buyers prioritizing convenience logistics.
- Online Retail:Casper Sleep and Purple Innovation have trained United States buyers to expect seamless return logistics and compressed shipping formats. This channel commands highest margin capture for brands with captive last-mile infrastructure.
- B2B:Concentrated margin pools flow from hospitality procurement contracts and institutional healthcare tenders requiring EU MDR compliance documentation and REACH material safety certifications.
- Offline Retail:Traditional furniture and mattress showrooms retain relevance for tactile evaluation-dependent buyers in suburban markets.
- Direct Sales:Sleep Number Corporation leverages this channel for adjustable air-foam hybrid platform demonstrations in owned retail locations.
Online retail processes the highest transaction velocity; B2B shows the steepest expansion trajectory through hospitality portfolio consolidation.
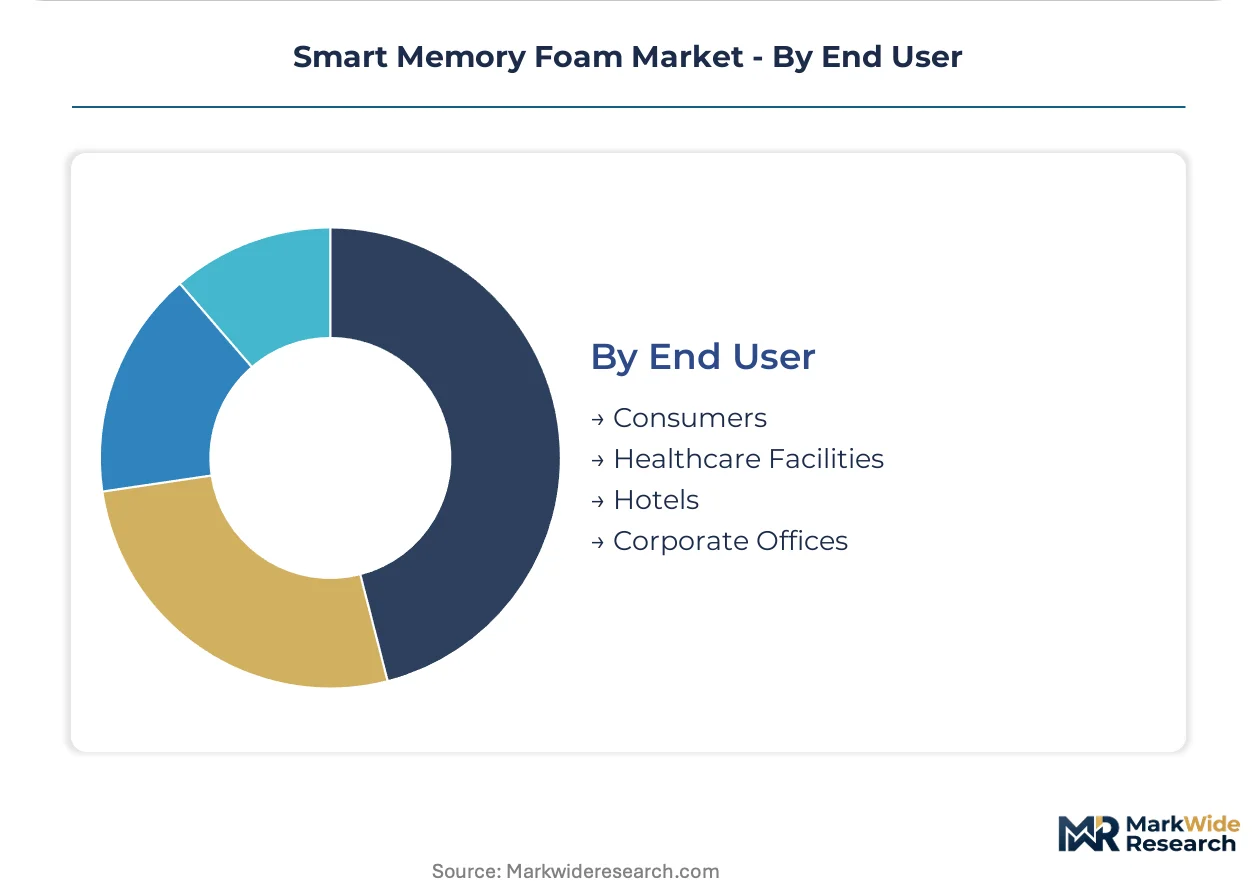
End User:
Volume concentration sits with individual consumers, while margin expansion follows healthcare facilities with outcome-based procurement justification.
- Consumers:Individual buyers in United States residential upgrade segments prioritize thermo-active layers over conventional gel-infused alternatives, with phase-change material integration driving purchase decisions.
- Healthcare Facilities:Hospitals and long-term care wards in Massachusetts and California pilot embedded sensor arrays for fall-risk prediction in geriatric populations, digitizing capital expenditure justification through measurable outcome metrics.
- Hotels:Centralized procurement specifications across property portfolios are displacing fragmented distributor relationships.
- Corporate Offices:Ergonomic seating retrofits serve wellness-program workplace investments with lower per-unit technology integration than residential platforms.
Consumers drive absolute transaction volume; healthcare facilities are climbing the fastest on value contribution through regulatory-mandated technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential upgrade buyers in the United States concentrate absolute transaction value, while healthcare procurement protocols in Germany and regulatory manufacturing incentives in India are redrawing production geography. Channel economics split between direct-to-consumer logistics dominance in coastal metropolitan markets and institutional tender specifications across European long-term care networks.
United States
Coastal metropolitan buyers in New York, Los Angeles, and San Francisco prioritize sensor-embedded mattresses with Apple Health and Garmin Connect interoperability. FDA Class II medical device oversight governs therapeutic claims for pressure-relief surfaces in Massachusetts and California hospital pilots. Boston-area geriatric wards are deploying embedded accelerometers for fall-risk prediction, digitizing capital expenditure justification through measurable patient outcomes.
Germany
Healthcare facilities across Bavaria and North Rhine-Westphalia are expanding procurement of pressure-relief mattresses under EU Medical Device Regulation requirements. ECHA REACH compliance shapes material safety certifications for polyurethane foam formulations entering institutional tenders. Evonik Industries anchors thermo-responsive polymer production in Marl Chemical Park, supplying temperature-adaptive foam architectures to domestic converter networks.
India
Price-sensitive residential demand in Maharashtra and Gujarat is attracting advanced materials manufacturing under the PLI scheme for specialty chemicals. BIS standards govern polyurethane foam density and durability claims for domestic mattress brands. Pune and Ahmedabad industrial corridors are hosting thermo-responsive polymer compounding facilities from multinational chemical suppliers to serve Asian residential upgrade cycles.
China
MIIT standards for smart home device interoperability are pressuring foam-embedded sensor arrays to adopt unified data protocols for domestic platform integration. NMPA oversight applies to therapeutic mattress claims in hospital procurement channels. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces concentrate open-cell gas-injection capacity for slow-recovery foam exports.
United Kingdom
London and Southeast England direct-to-consumer brands compete for mattress replacement cycles through compressed shipping logistics and extended trial periods. UKCA marking requirements post-Brexit maintain alignment with EU MDR for pressure-ulcer prevention surfaces in NHS long-term care wards. Midlands industrial zones retain polyurethane converter capacity serving both domestic retail and European export channels.
Smart Memory Foam Market Vendor Landscape
Channel-controlling players compete with product-specialist players for margin capture across divergent distribution economics. Consolidation pressure concentrates around brands with captive last-mile infrastructure and institutional tender compliance capabilities. Three archetypes dominate: vertically integrated foam manufacturers with sensor integration capabilities, direct-to-consumer platforms with subscription logistics, and specialty chemical suppliers with thermo-responsive polymer IP. Competitive moves center on backward integration into polyurethane feedstock and strategic partnerships for health data platform interoperability.
Within the vertically integrated tier, Tempur Sealy International, Inc. and Serta Simmons Bedding, LLC occupy positions defined by manufacturing scale and North American distribution density. Sleep Number Corporation exemplifies the channel-control archetype through owned retail locations and adjustable platform differentiation. Purple Innovation, LLC represents product-specialist positioning with polymer grid architectures competing against conventional viscoelastic formulations. Evonik Industries AG anchors the materials-science supplier tier from its German base, licensing thermo-responsive formulations across converter networks.
| Leading Market Players |
|---|
| Tempur Sealy International, Inc. |
| Serta Simmons Bedding, LLC |
| Sleep Number Corporation |
| Kingsdown, Inc. |
| Foam Factory, Inc. |
| Restonic Mattress |
| Dorel Industries |
| Purple Innovation, LLC |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge freight corridors anchor polyurethane feedstock logistics, with toluene diisocyanate indexation clauses in Belgian and Italian converter contracts transmitting Gulf Coast petrochemical volatility into European mattress pricing tiers. This freight-cost pass-through mechanism concentrates margin pressure on mid-tier foam manufacturers lacking backward integration into polyether polyol production.
Pricing Analysis
Cost-plus contracts with toluene diisocyanate indexation dominate B2B procurement between chemical suppliers and foam converters. Pricing stratifies across premium sensor-embedded platforms, standard thermo-responsive formulations, and economy-grade open-cell alternatives, with FDA Class II certification and Apple Health interoperability commanding substantial premiums. Cost compression in standard-grade segments is intensifying as Sleep Number Corporation's air-foam hybrids constrain pure memory foam pricing power. Residential direct-to-consumer buyers show highest price sensitivity, while EU MDR-compliant healthcare tenders absorb premium positioning with limited elasticity.
Supply Chain Analysis
Supply-chain finance facilities from Dutch petrochemical traders extend 90-120 day payment terms to Belgian and Italian foam converters, easing working capital strain during feedstock price volatility. Manufacturing concentrates in Germany, the United States, and China, with specialized polyether polyol production anchored in the US Gulf Coast and Rotterdam harbor zones. Raw material dependencies center on toluene diisocyanate, polyether polyols, and microencapsulated phase-change additives. Single-source vulnerability in Gulf Coast petrochemical complexes poses structural risk. Distribution runs through direct-to-consumer compressed-shipping logistics and institutional B2B tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart memory foam is crossing into platform economics as sleep sensor data streams achieve native interoperability with Apple Health and Garmin Connect ecosystems, transforming product margins from hardware transactions to recurring wellness data relationships.
For Market Incumbents: Harden sensor-embedded platform differentiation through exclusive interoperability partnerships with established health data ecosystems, insulating against Sleep Number Corporation's adjustable air-bladder substitution threat. Deepen backward integration into thermo-responsive polymer compounding to restore margin visibility amid toluene diisocyanate volatility. Prioritize EU MDR certification investment to capture German and French healthcare procurement waves. For New Entrants and Emerging Players: Build out white-space positions in India PLI scheme manufacturing zones near Pune and Ahmedabad, where domestic production incentives and price-sensitive residential demand create penetrable entry points. Target modular pillow and mattress topper accessories as lower-capital alternatives to full-platform mattresses. Deploy direct-to-consumer trial logistics as the primary go-to-market angle. For Investors and Strategic Acquirers: Sensor-integrated foam converters with captive health data platform partnerships represent the most defensible acquisition archetype for long-term viability through the wellness-hardware convergence. Watch FDA digital health guidance evolution as the critical inflection signal for medical-grade segment expansion. Platform economics rather than commodity foam manufacturing will determine sustained value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Health Data Platform Integration | Native Apple Health and Garmin Connect interoperability commands 40% retail price premiums over closed-system alternatives. |
| EU MDR Certification Investment | Pressure-ulcer prevention protocol compliance unlocks German and French long-term care institutional tender participation. |
| Backward Integration into Polymer Compounding | In-house thermo-responsive formulation production restores margin control amid Gulf Coast feedstock concentration risks. |
| Direct-to-Consumer Logistics Infrastructure | Captive last-mile delivery networks displace wholesale-dependent competitors in coastal metropolitan residential markets. |
| India PLI Scheme Manufacturing Footprint | Domestic advanced materials production under BIS standards serves price-sensitive Asian residential upgrade demand. |
Methodological Framework
A standing panel of foam manufacturing plant managers, healthcare procurement officers at German and French long-term care facilities, direct-to-consumer brand supply chain directors, and thermo-responsive polymer R&D leads provided ongoing calibration across the study. Primary interview intelligence combined with secondary validation from EPA VOC emissions filings, EU MDR compliance databases, SEC 10-K disclosures from listed mattress manufacturers, and customs trade data for polyurethane feedstock imports. Bottom-up converter capacity modeling and top-down residential replacement cycle analysis were triangulated for demand estimation.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling across product architecture, application environment, distribution channel, and end-user procurement type. CAGRs derived from weighted regression of historical replacement cycle compression and sensor-embedded platform penetration curves. Forecast inputs incorporated toluene diisocyanate price stabilization assumptions and EU MDR procurement mandate implementation timelines.
Stress conditions across feedstock supply disruption, FDA digital health regulatory acceleration, and adjustable air-bladder substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding interoperability standard adoption and healthcare facility capital expenditure prioritization. Macroeconomic contraction, REACH SVHC list expansion, or breakthrough solid-state sleep surface technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Window Rain Guards Market
Household Items
Global Laptop Tables Market
Household Items
Mirror Holder Market
Household Items
Tablet Tissue Paper Market
Household Items
Shoe Dryer Market
Household Items
Mosquito Lamps Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
Cups and Pots Market
Household Items
Insulated Water Bottles Market
Household Items
Garbage Disposals Market
Household Items
Can Opener Market
Household Items
Commercial Lawnmower Market
Household Items
Europe Digital Showers Market
Household Items
Car Air Freshener Market
Household Items
North America Liquid Hand Soap Market
Household Items
Global Electric Scissors Market