
 Europe Electric Cordless Lawn and Garden Tools Market | 2026-2036
Europe Electric Cordless Lawn and Garden Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Cordless Lawn and Garden Tools Market Intelligence
Germany is reconfiguring its manufacturing footprint for cordless outdoor power equipment through expanded battery assembly and motor production clusters. Husqvarna Group leverages its Nordic engineering heritage to dominate professional-grade chainsaw and robotic mower development. Robert Bosch GmbH anchors the European homeowner segment with integrated battery platforms that span multiple garden applications. Makita Corporation competes through sustained investment in high-torque brushless motor architectures tailored to continental voltage standards.
Europe electric cordless lawn and garden tools comprise battery-powered mechanized equipment utilizing DC motor drives and rechargeable electrochemical cells, typically operating at 18V to 80V depending on tool class, designed to perform turf cutting, vegetation management, and debris clearance without tethered power or internal combustion. Lawn mowers generate the largest revenue pool within the product type dimension, though leaf blowers exhibit the steepest adoption curve among professional landscapers seeking noise-compliant alternatives. Lithium-ion battery technology has displaced nickel-cadmium across all premium and mid-tier positioning, while lead-acid persists only in entry-price homeowner segments with limited runtime requirements.
EU Green Deal carbon neutrality targets, F-Gas Regulation restrictions on fluorinated greenhouse gases, and CE marking requirements under the Machinery Directive collectively mandate reduced acoustic emissions and elimination of gasoline particulate output in outdoor power equipment sold across member states. ECHA chemical substance restrictions further constrain legacy battery chemistries and lubricant formulations used in tool maintenance. Stakeholders must monitor evolving national transpositions of EU battery passport regulations and anticipate how extended producer responsibility frameworks will reshape aftermarket service economics and replacement cycle timing.
Market Dynamics
Municipal noise ordinances and EU Green Deal carbon neutrality mandates are forcing professional landscapers across France, Germany, and the Netherlands to retire gasoline-powered fleets ahead of natural replacement cycles, compressing demand into cordless platforms.
Growth Catalysts
- F-Gas Regulation phase-down:Fluorinated greenhouse gas restrictions under EU law are eliminating maintenance pathways for legacy gas-powered equipment, accelerating fleet turnover toward battery alternatives.
- Professional landscaping services:Commercial gardening contractors in Germany and Scandinavia are expanding cordless equipment orders to comply with municipal emissions limits and acoustic thresholds in urban maintenance contracts.
- Lithium-ion cell chemistry:Energy density improvements in nickel-manganese-cobalt formulations are extending runtime per charge, enabling cordless tools to substitute for gasoline in previously underserved high-torque applications.
Market Restraints
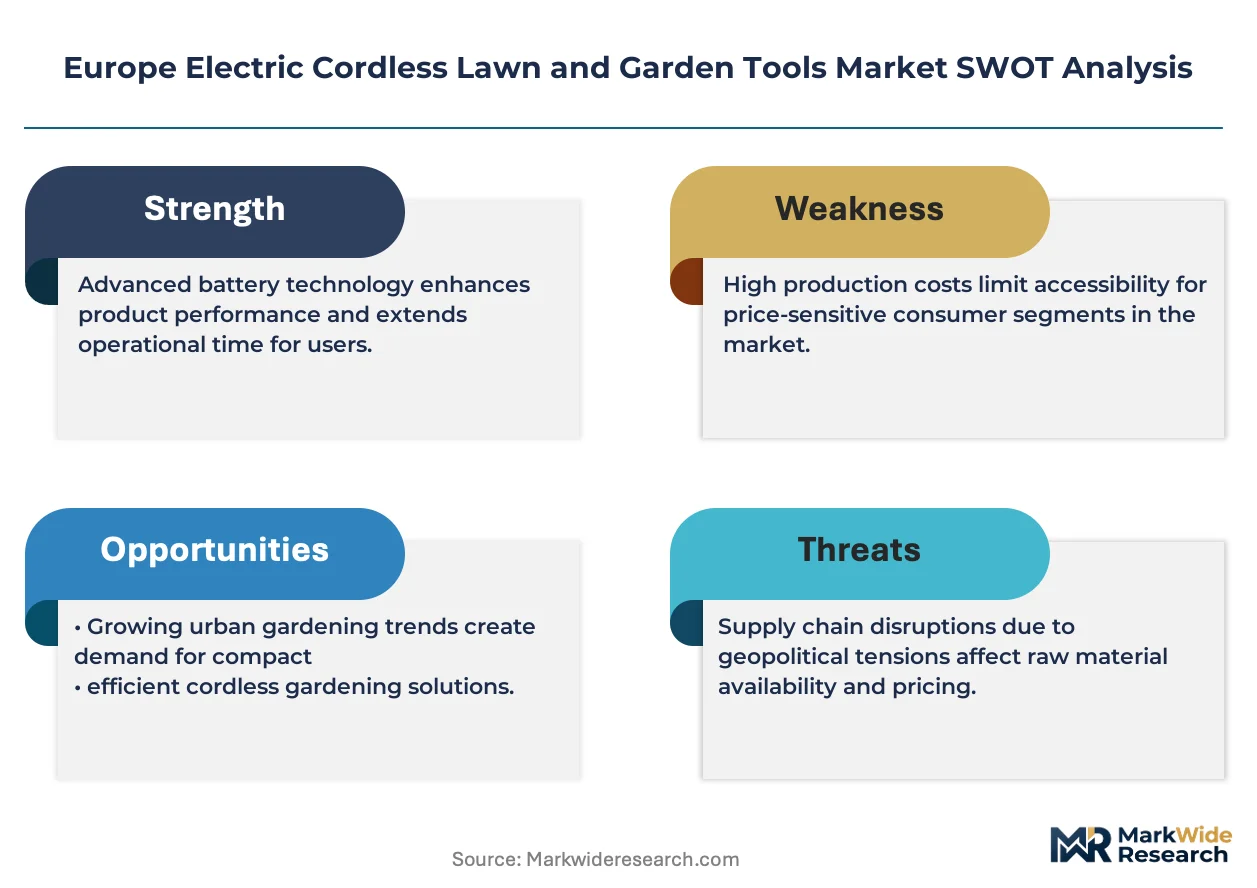
- Battery raw material concentration:Cathode precursor processing and cell assembly capacity clusters in East Asia create supply vulnerability for European tool manufacturers dependent on imported lithium-ion packs.
- CE marking compliance costs:Machinery Directive conformity assessment and acoustic testing requirements impose fixed certification burdens that disproportionately burden mid-tier equipment producers.
- Lead-acid persistence in entry segments:Price-sensitive homeowner purchases in Southern and Eastern Europe continue selecting heavier, shorter-runtime battery chemistries, fragmenting platform standardization.
Strategic Opportunities
- Scandinavian park maintenance:Sweden, Norway, and Denmark operate extensive public green space networks with strict environmental procurement criteria, creating concentrated demand for professional-grade robotic mowers and brushless chainsaws.
- Battery passport alignment:EU battery passport regulations mandating digital lifecycle tracking will favor manufacturers with integrated cell-to-tool traceability systems, creating compliance-based differentiation.
- Brushless motor-IoT convergence:Integration of torque-sensing algorithms with cloud-connected fleet management platforms enables usage-based service contracts for municipal equipment pools.
Industry Challenges
- Power electronics engineering scarcity:Continental European tool manufacturers face recruitment constraints for motor control firmware developers and thermal management specialists as automotive and industrial sectors compete for equivalent talent.
- Extended producer responsibility compliance:National transpositions of EU waste framework directives are creating heterogeneous collection and recycling obligations across member states, complicating aftermarket service network design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Cordless Lawn and Garden Tools Market |
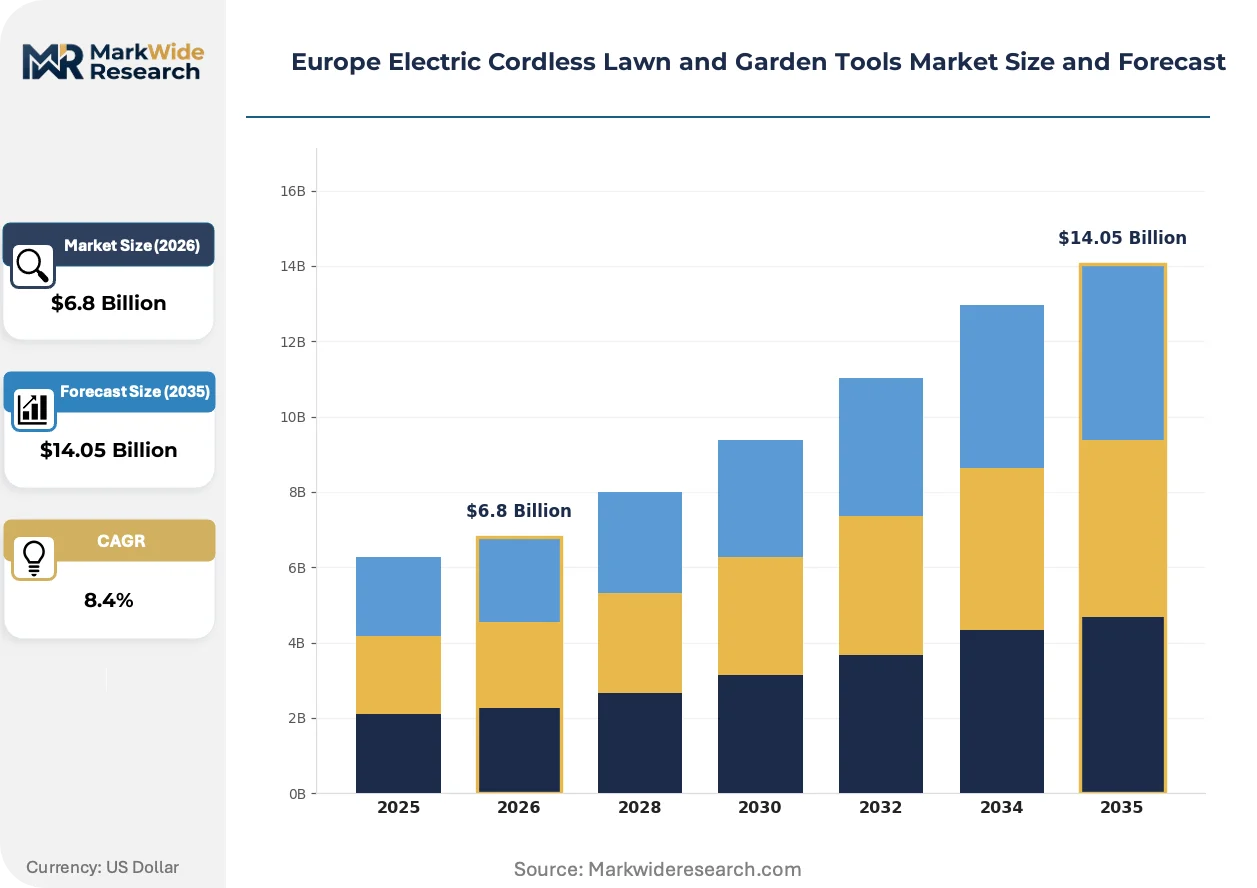
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lawn Mowers, Hedge Trimmers, Leaf Blowers, Chainsaws Battery Technology: Lithium-Ion, Nickel-Cadmium, Lead-Acid, Others End User: Homeowners, Landscapers, Golf Courses, Parks Distribution Channel: Online Retail, Home Improvement Stores, Specialty Shops, Direct Sales |
| Companies Covered | Deere & Company, Makita Corporation, Husqvarna Group, Techtronic Industries Co. Ltd., Stanley Black & Decker Inc., Robert Bosch GmbH, ANDREAS STIHL AG & Co. KG, AriensCo., The Toro Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Cordless Lawn and Garden Tools Market Strategic Shifts & Innovations
Brushless DC motor architectures and smart battery management systems are compressing the performance gap between cordless and gasoline platforms, while regulatory pressure and procurement digitization are rewriting how equipment fleets are specified and financed.
High-torque brushless motor platforms operating at 56V to 80V are rendering obsolete the runtime and power limitations that previously confined cordless tools to homeowner applications. Professional landscaping contractors in Germany and the Netherlands are now specifying these systems for commercial-grade vegetation management. The technology is enabling municipal procurement departments to mandate cordless alternatives without operational compromise.
The EU Green Deal's 2050 carbon neutrality target and F-Gas Regulation restrictions are binding constraints on outdoor power equipment sold across member states. CE marking requirements under the Machinery Directive now incorporate acoustic emission thresholds that gasoline engines struggle to satisfy. France's national transposition of extended producer responsibility frameworks is accelerating replacement cycle compression in the commercial segment.
Rental and subscription-based equipment access models are displacing outright purchase in municipal and commercial landscaping operations. Fleet management platforms that integrate usage telemetry with predictive maintenance scheduling are capturing procurement decisions in Germany's federal state maintenance contracts. This behavioral shift is most visible in Scandinavia, where public sector green procurement criteria prioritize total cost of ownership over capital expenditure minimization.
Europe Electric Cordless Lawn and Garden Tools Market Segmentation
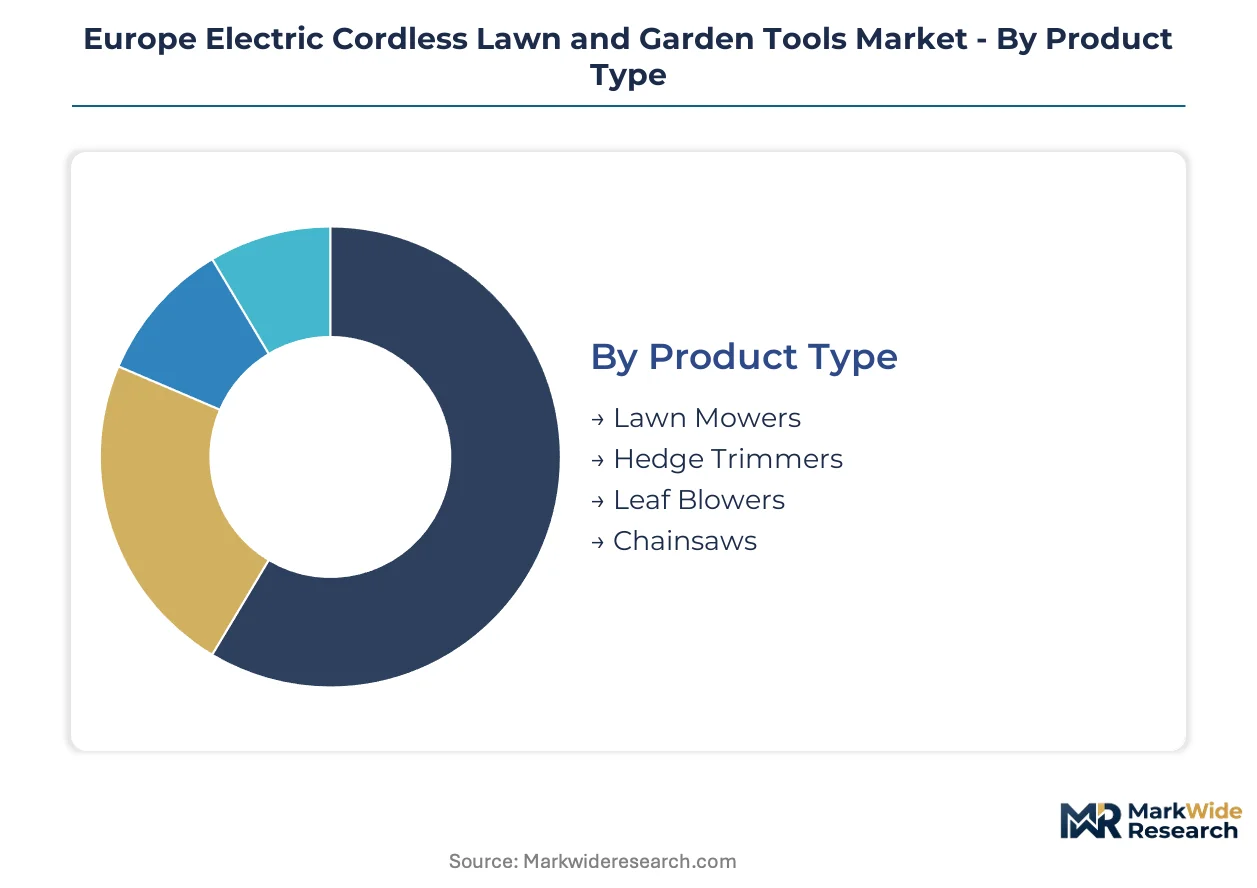
Segmentation in the Europe Electric Cordless Lawn and Garden Tools Market reveals how voltage platform standardization, battery chemistry migration, and procurement channel digitization are fragmenting competitive positioning across price-performance tiers. Understanding these dimensions exposes where margin concentration and technology leadership align.
Product Type:
Application intensity and torque requirements determine which cordless platforms can substitute for gasoline equipment in professional settings versus homeowner maintenance routines.
- Lawn Mowers:Self-propelled and robotic variants operating at 40V to 80V dominate revenue pools, with German commercial gardening contractors specifying these for municipal maintenance contracts under EU Green Deal procurement rules. Battery deck width and runtime per charge determine whether units qualify for professional fleet deployment versus residential weekend use.
- Leaf Blowers:Handheld and backpack configurations exhibit the steepest adoption curve among Dutch and French landscapers seeking noise-compliant alternatives to two-stroke engines under municipal acoustic ordinances. Professional-grade units now match gasoline airflow velocity at 56V operating platforms.
- Hedge Trimmers:Articulating and fixed-blade cordless variants serve precision trimming in Scandinavian park maintenance operations with strict environmental procurement criteria.
- Chainsaws:Brushless motor architectures at 80V deliver felling and bucking capability for forestry contractors in Sweden and Finland replacing legacy gasoline inventory.
Lawn mowers command the established base. The steepest expansion runs through leaf blowers.
Battery Technology:
Chemistry selection dictates energy density, cycle life, and compliance posture under evolving EU substance restrictions and extended producer responsibility frameworks.
- Lithium-Ion:Nickel-manganese-cobalt formulations have displaced competing chemistries across premium and mid-tier positioning, with energy density improvements extending runtime for high-torque applications previously reserved for gasoline. ECHA chemical substance restrictions and forthcoming battery passport mandates favor manufacturers with integrated cell-to-tool traceability systems.
- Lead-Acid:Heavier, shorter-runtime batteries persist only in entry-price homeowner segments across Southern and Eastern Europe where price sensitivity overrides performance requirements, fragmenting platform standardization for multi-tool battery compatibility.
- Nickel-Cadmium:Legacy chemistry now confined to replacement battery sales for aging tool inventories as REACH restrictions and waste framework directives accelerate phase-out.
- Others:Solid-state and sodium-ion experimental platforms attract R&D investment from Nordic engineering clusters seeking next-generation thermal stability and supply chain decoupling from cobalt supply concentration.
Lithium-ion anchors installed capacity. The technology transition gaining share fastest centers on solid-state development pipelines.
End User:
Customer type determines purchasing cadence, fleet standardization requirements, and sensitivity to total cost of ownership versus capital expenditure minimization.
- Landscapers:Commercial gardening contractors in Germany and the Netherlands are expanding cordless equipment orders to comply with municipal emissions limits and acoustic thresholds in urban maintenance contracts, with fleet management platforms integrating usage telemetry capturing procurement decisions.
- Parks:Municipal and federal state maintenance operations across Scandinavia prioritize environmental procurement criteria and total cost of ownership calculations, creating concentrated demand for robotic mowers and professional-grade brushless systems.
- Homeowners:Weekend maintenance routines in suburban France and Benelux markets drive seasonal replacement cycles, with integrated battery platforms spanning multiple garden applications reducing total system cost.
- Golf Courses:Turf management operations require precision cutting and extended daily runtime, with superintendents specifying commercial-grade cordless mowers for fairway maintenance in noise-sensitive locations.
Landscapers represent the volume anchor. Parks operations are climbing the fastest as public sector green procurement criteria harden.
Distribution Channel:
Channel selection reflects customer sophistication, platform compatibility requirements, and the shift from outright purchase toward subscription-based equipment access models.
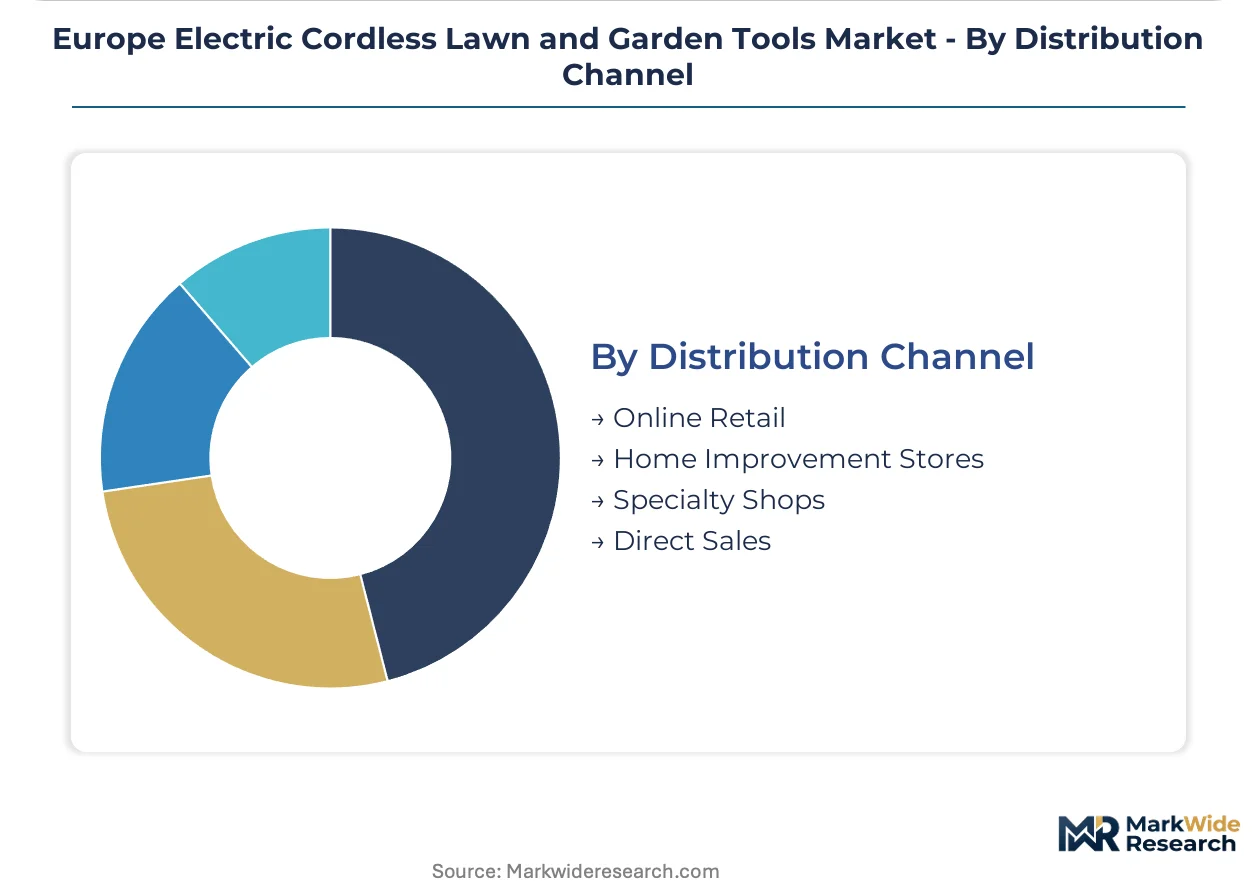
- Home Improvement Stores:Mass retail networks in Germany and France anchor homeowner segment volume, with seasonal promotional cycles and multi-tool battery platform bundling driving attachment sales.
- Online Retail:E-commerce platforms capture specification-sensitive professional buyers comparing torque ratings and runtime data, with direct-to-merchant inventory models reducing working capital requirements for mid-tier manufacturers.
- Specialty Shops:Independent dealers maintain service relationships with commercial landscaping contractors requiring immediate parts availability and warranty claim processing for fleet uptime.
- Direct Sales:Manufacturer field organizations secure municipal and federal state maintenance contracts in Scandinavia through usage-based service contracts and predictive maintenance scheduling integration.
Home improvement stores retain the volume base. The steepest channel expansion runs through online retail as specification transparency and procurement digitization advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's electrified freight rail network underwrites Germany's distribution dominance for cordless outdoor power equipment across Northern Europe. This infrastructure connects battery assembly clusters in Stuttgart and Munich to Benelux port terminals serving Scandinavian markets.
Germany
Commercial gardening contractors in Bavaria and Baden-Württemberg are retiring gasoline fleets ahead of schedule to comply with municipal noise ordinances in Munich and Stuttgart. The EU Green Deal's carbon neutrality mandates bind federal state procurement departments to specify battery-powered alternatives for park maintenance contracts. Husqvarna and Robert Bosch anchor manufacturing and R&D activity in Stuttgart's engineering corridor.
Netherlands
Professional landscapers in the Randstad conurbation face the continent's strictest urban acoustic thresholds, forcing rapid cordless adoption for vegetation management in Amsterdam and Rotterdam municipal contracts. CE marking requirements under the Machinery Directive incorporate noise emission standards that gasoline equipment cannot satisfy. Eindhoven's high-voltage electronics cluster supplies motor control systems to tool assemblers.
France
Île-de-France's extended producer responsibility framework accelerates replacement cycles for commercial landscaping fleets serving Parisian park networks. The F-Gas Regulation eliminates maintenance pathways for legacy gas-powered equipment, compressing demand into battery platforms. Auvergne-Rhône-Alpes hosts precision motor manufacturing for brushless architectures.
Sweden
Forestry contractors in Västra Götaland and Stockholm County specify 80V brushless chainsaws to replace gasoline inventory under national carbon reduction procurement criteria. ECHA chemical substance restrictions constrain lubricant formulations used in tool maintenance. Husqvarna's Nordic engineering heritage centers on Jonköping's development cluster for professional-grade equipment.
United Kingdom
Landscaping services in Greater London and the Southeast confront tightening emissions standards for urban maintenance contracts, redirecting fleet investment toward cordless platforms. The UK's transposition of EU battery passport regulations mandates digital lifecycle tracking for imported equipment. Midlands manufacturing retains motor winding and assembly capacity for domestic tool producers.
Europe Electric Cordless Lawn and Garden Tools Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying battery management systems and brushless motor controllers. The vendor base concentrates around five integrated equipment manufacturers with established distribution networks across German and Benelux retail channels. Three strategic archetypes dominate: Nordic engineering heritage players, diversified industrial conglomerates with battery platform strategies, and Japanese precision motor specialists. Competitive moves center on backward integration into cell assembly partnerships and geographic expansion through Scandinavian municipal procurement channels.
Within the diversified industrial tier, Robert Bosch GmbH and Stanley Black & Decker Inc. exemplify platform integrators leveraging cross-application battery compatibility. Husqvarna Group anchors the Nordic engineering heritage archetype with professional-grade specialization. Makita Corporation occupies the precision motor specialist position, reflecting sustained investment in high-torque brushless architectures.
| Leading Market Players |
|---|
| Deere & Company |
| Makita Corporation |
| Husqvarna Group |
| Techtronic Industries Co. Ltd. |
| Stanley Black & Decker Inc. |
| Robert Bosch GmbH |
| ANDREAS STIHL AG & Co. KG |
| AriensCo. |
| The Toro Company |
| Others |
Cost & Logistics Intelligence
East Asian cathode precursor processing clusters tether European tool manufacturers to imported lithium-ion pack pricing, concentrating margin capture with cell assemblers while OEMs compete on battery platform integration and aftermarket service attach rates.
Pricing Analysis
EU Green Deal carbon neutrality mandates dictate the pricing tier structure across the European cordless equipment landscape. Three-tier pricing structure across premium, standard, and economy levels segments buyers by runtime requirements and torque specifications, with CE marking compliance costs and acoustic certification tiers driving price differentiation. Cost compression in mid-tier segments is intensifying because battery raw material volatility feeds through to pack costs. Homeowners in Southern and Eastern Europe exhibit highest price sensitivity, while Scandinavian municipal procurement departments prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for cordless tool manufacturers. Cell assembly capacity concentrates in China, South Korea, and Japan, with nickel-manganese-cobalt cathode materials and rare-earth permanent magnets representing critical input dependencies. Single-source vulnerability persists for high-voltage motor controllers sourced from Eindhoven's electronics cluster. Distribution runs through Rhine-Alpine freight rail corridors connecting Stuttgart assembly plants to Benelux port terminals serving Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based equipment access models and predictive maintenance service contracts are expanding faster than hardware unit sales, creating recurring revenue pools that offset margin pressure on cordless tool platforms.
For Market Incumbents: Entrench platform dominance through backward integration into cell assembly partnerships and captive battery management system production. Solid-state chemistry R&D pipelines in Nordic engineering clusters represent the primary technology threat. Certification investment in EU battery passport traceability systems secures compliance-based differentiation against mid-tier competitors lacking integrated cell-to-tool visibility.
For New Entrants and Emerging Players: Mid-market commercial landscaping contractors in France and the Netherlands represent the most penetrable entry point, with fleet standardization gaps among regionally fragmented service providers creating white-space opportunity. Robotic mower aftermarket service networks in Scandinavian park maintenance operations remain underserved by incumbent coverage models. Direct-to-contractor online retail channels bypass established dealer relationships and reduce customer acquisition costs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European tool manufacturers lacking integrated battery platform strategies. Five-to-ten year viability hinges on cell chemistry transition execution and municipal procurement digitization capture. Watch for inflection signals in extended producer responsibility framework harmonization across EU member states, which would compress replacement cycles and concentrate fleet turnover timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Passport Compliance Investment | EU battery passport mandates favor manufacturers with integrated cell-to-tool traceability systems. |
| Brushless Motor-IoT Platform Integration | Torque-sensing algorithms with cloud-connected fleet management enable usage-based municipal contracts. |
| Scandinavian Municipal Procurement Channel Expansion | Sweden, Norway, and Denmark public green space networks concentrate demand for professional-grade equipment. |
| Solid-State Battery R&D Partnership | Nordic engineering clusters target thermal stability and cobalt supply decoupling in next-generation platforms. |
| Predictive Maintenance Service Contract Launch | Telemetry-integrated scheduling captures procurement decisions in German federal state maintenance contracts. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial landscaping fleet managers, municipal procurement officers, battery platform engineers, and aftermarket service directors. Secondary validation drew from EU battery passport regulatory filings, ECHA chemical substance restriction updates, Machinery Directive CE marking databases, and customs trade flow records for lithium-ion cell imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the European cordless equipment installed base.
Calibration against historical replacement cycle data and municipal contract award patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, battery chemistry tier, end-user archetype, and voltage platform standardization, with procurement channel digitization serving as an industry-specific overlay. CAGRs were derived from regression analysis of fleet turnover rates against regulatory compliance deadlines, incorporating F-Gas Regulation phase-down timelines and national noise ordinance implementation schedules as forecast inputs.
Practitioners should monitor battery raw material price volatility and EU member state transposition timing for extended producer responsibility frameworks for early signals of forecast deviation. Material shifts in cell chemistry cost curves or Machinery Directive acoustic threshold tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Europe Handheld Fans Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Global Wet Vacuum Cleaner Market
Household Items
Smart Drying Racks Market
Household Items
Electric Mop Market
Household Items
Household Scales Market
Household Items
Candle Jar Market
Household Items
Electric Tealight Candles Market
Household Items
Sanitary Napkin Vending Machine Market
Household Items
Hydration Containers Market
Household Items
China Cookware Market
Household Items
Disposable Napkins Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Infrared Sauna Heaters Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Underwear Disinfection Dryers Market