
 Smart Desk Lamp Market | 2026-2036
Smart Desk Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Desk Lamp Market Insights
Modular lamp ecosystems that pair adjustable arms with swappable base units and clip-on accessories is rebalancing how buyers evaluate lifetime value against upfront spend. Philips Hue leverages its proprietary Zigbee mesh protocol to sustain a sticky smart home ecosystem. BenQ anchors the premium productivity segment with screen-bar configurations that reduce monitor glare. Govee competes aggressively on app connectivity and RGB customization for younger demographics.
A smart desk lamp is a task-oriented luminaire integrating solid-state LED emitters, microprocessor-driven dimming circuits, and wireless communication modules to deliver adjustable correlated color temperature and illuminance levels for focused work. LED product types dominate unit economics due to semiconductor cost curves and lumen-per-watt efficiency gains above 150 lm/W. Voice control features are expanding fastest among home office and freelancer end users who prioritize hands-free operation during video calls. App connectivity concentrates margin pools through recurring firmware updates and ecosystem lock-in, while halogen variants face structural decline from regulatory phase-outs.
The EU F-Gas Regulation and REACH chemical restrictions constrain refrigerants and hazardous substances in manufacturing processes, while CE marking mandates electromagnetic compatibility testing for Wi-Fi and Bluetooth-enabled units. The US FCC governs radio frequency emissions from wireless control modules, and California Title 20 imposes standby power limits that shape circuit design choices. Stakeholders must monitor how fragmented national efficiency standards affect platform development costs and determine whether regional SKU customization or global baseline compliance delivers superior returns.
Market Dynamics
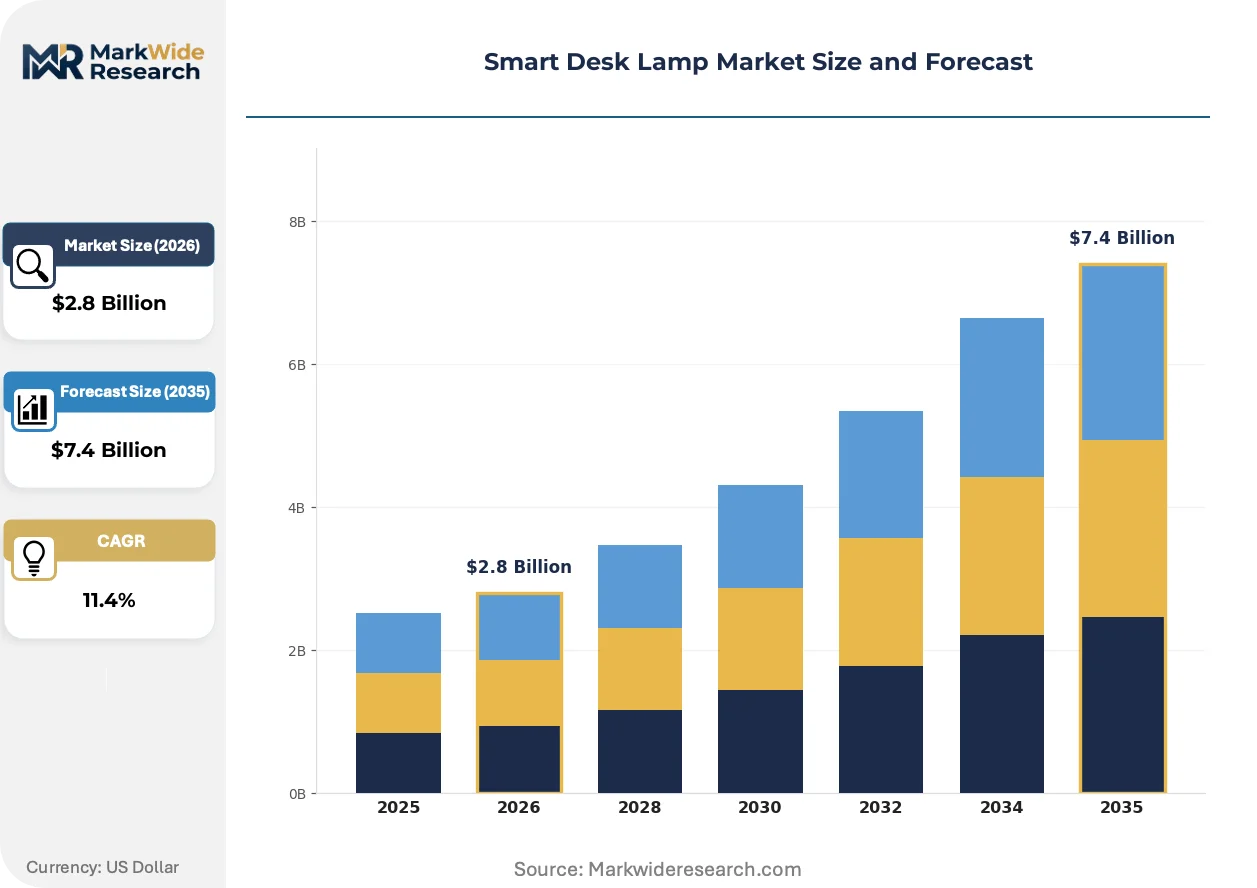
Remote work permanence is restructuring demand composition across residential and commercial channels, compressing replacement cycles while elevating specifications for circadian lighting and video-call optimized illumination.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency benchmarks are phasing out legacy halogen inventory and accelerating LED retrofit demand across member states.
- Home office segment:Freelancers and distributed enterprise workers are prioritizing task-appropriate CCT adjustability above price sensitivity.
- Shenzhen-Dongguan cluster:Concentrated semiconductor packaging and wireless module manufacturing is compressing BOM costs for smart-enabled units.
Market Restraints
- Chip supply volatility:Microcontroller and Bluetooth SoC lead times remain extended, constraining production planning for tier-two assemblers.
- REACH chemical restrictions:Compliance testing for hazardous substance thresholds adds fixed cost layers to EU-bound shipments.
- Halogen substitution ceiling:Incandescent phase-outs have already captured easy conversion volume, narrowing the remaining addressable base.
Strategic Opportunities
- India residential:Urban middle-class expansion and unreliable grid infrastructure create pull for battery-backed smart lamps with app scheduling.
- Li-Fi convergence:Visible light communication integration with desk lamps offers untapped positioning for secure, high-bandwidth office networks.
- D2C channel expansion:Direct-to-consumer platforms bypass traditional lighting retail markups and capture first-party usage data.
Industry Challenges
- Firmware engineering talent:Shortage of embedded systems developers with wireless stack expertise is elongating product development timelines.
- Multi-protocol certification:Simultaneous FCC, CE, and MIC testing for Zigbee, Wi-Fi, and Matter compatibility extends time-to-revenue by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Desk Lamp Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Halogen, Incandescent Feature: Dimming, Color Changing, Voice Control, App Connectivity End User: Home Office, Corporate, Education, Freelancers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Dyson, Lumi, Philips Hue, Oyen, GOI, Govee, Honeywell, Hifree, BenQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Desk Lamp Market Trends and Innovations
Illumination hardware is converging with wellness and productivity software, transforming lamps from passive fixtures into data-capturing workplace infrastructure. This integration is redefining value capture and vendor stickiness.
Matter protocol adoption is unifying previously fragmented smart home ecosystems. Home office buyers are migrating toward cross-platform compatibility that eliminates hub proliferation. This convergence is compressing vendor lock-in advantages and elevating interoperability as a primary selection criterion.
California Title 20 standby power limits are forcing circuit redesigns for always-connected units. Manufacturers are stripping vampire draw from Wi-Fi modules or implementing aggressive sleep states. Premium SKUs targeting the US West Coast are shipping with hardware kill switches to guarantee compliance.
Subscription-tier feature unlocking is displacing perpetual-license firmware. Buyers in North America and Western Europe encounter paywalled circadian algorithms and usage analytics. This model concentrates recurring revenue with ecosystem incumbents while fragmenting the installed base into tiered experience levels.
Smart Desk Lamp Market Segmentation
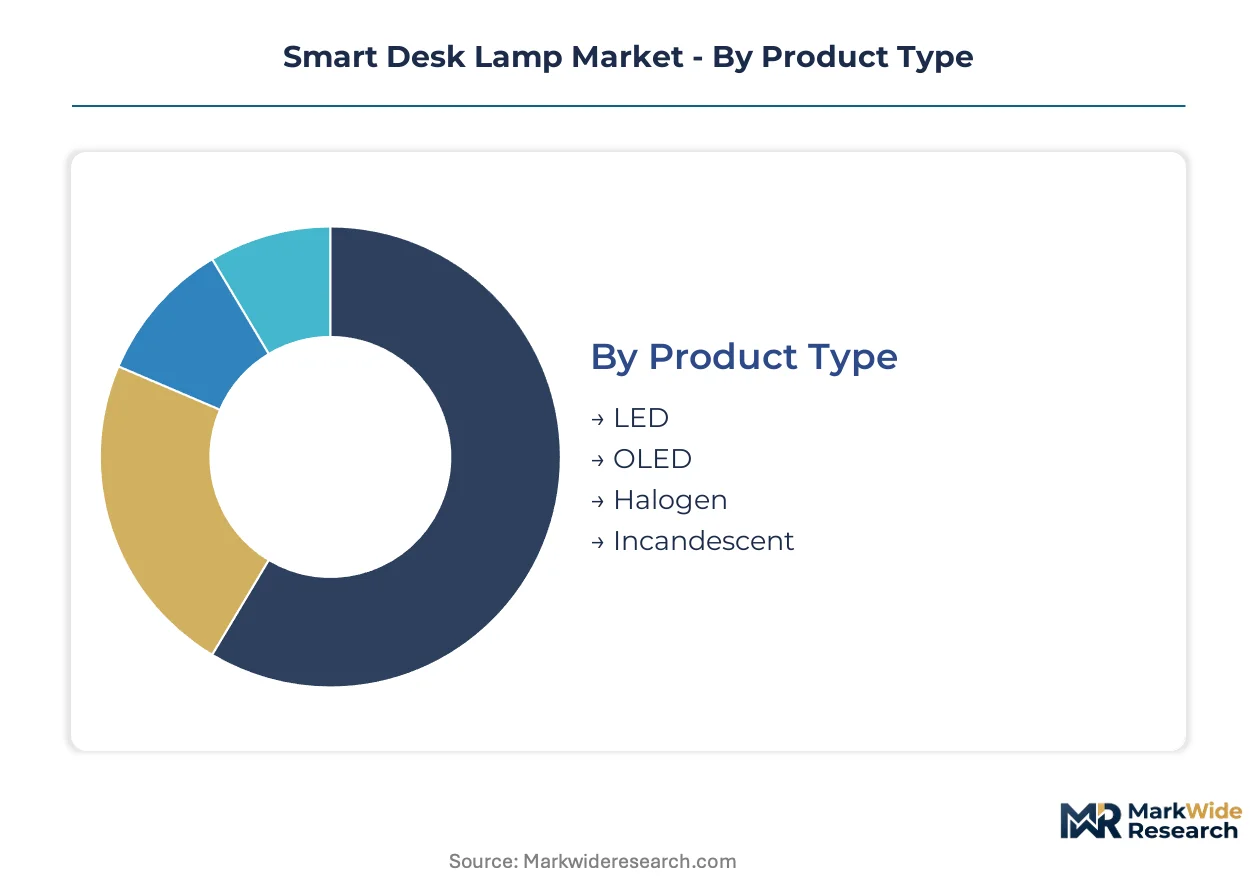
Smart desk lamp purchasing decisions fragment across technical specifications, connectivity ecosystems, and workspace typologies. Manufacturers configure SKU portfolios around these axes to capture margin pools in premium productivity hardware versus mass-market ambient lighting. Each segmentation dimension carries distinct supply chain implications for component sourcing and certification burdens.
Product Type:
Shenzhen-Dongguan semiconductor packaging clusters concentrate LED die and driver manufacturing, compressing BOM costs for solid-state luminaires while constraining OLED panel availability through limited vapor deposition capacity.
- LED:Solid-state emitters delivering 150+ lm/W efficacy through GaN-on-sapphire chip architectures. Demand concentrates in home office deployments across Germany and the United States where EU Ecodesign Directive efficiency mandates and California Title 20 standby limits drive retrofit cycles. Semiconductor cost curves continue eroding price premiums against legacy sources.
- OLED:Thin-film organic electroluminescent panels enabling uniform surface illumination without point-source glare. Premium workspace installations in Japan and South Korea adopt these units for color rendering index values above 95, though limited manufacturing scale at LG Display and Samsung SDI constrains volume expansion.
- Halogen:Tungsten-halogen capsules facing structural phase-out under EU Ecodesign Directive minimum efficiency requirements.
- Incandescent:Residual demand persists in price-sensitive emerging markets with weak enforcement of efficiency regulations.
Today's leader: LED. Tomorrow's challenger: OLED.
Feature:
Cost tier stratification separates basic dimming circuits from full-stack wireless ecosystems, with firmware development amortization driving 3-4x hardware margin spreads between entry and flagship SKUs.
- Voice Control:Hands-free operation through embedded microphone arrays and natural language processing coprocessors. Freelancers and distributed enterprise workers in the United States prioritize Alexa and Google Assistant integration during video-conferencing workflows. FCC Part 15 certification for 2.4 GHz transceivers adds fixed compliance overhead.
- App Connectivity:Bluetooth Low Energy and Wi-Fi modules enabling smartphone-based scheduling, circadian rhythm programming, and usage analytics. North American and Western European buyers accept subscription paywalls for advanced algorithmic features. Ecosystem lock-in through proprietary cloud backends concentrates recurring revenue with incumbents.
- Dimming:Phase-cut or PWM-based illuminance adjustment through physical dial or capacitive interface.
- Color Changing:RGB or tunable white LED arrays adjusting correlated color temperature across 2700K-6500K ranges.
Voice control commands the premium tier. App connectivity is climbing the fastest toward standard inclusion.
End User:
Application context determines specification intensity, with corporate procurement emphasizing uniformity and warranty terms while individual purchasers prioritize aesthetic customization.
- Home Office:Residential workspace installations requiring circadian-optimized CCT scheduling and low-flicker output for screen-based tasks. Demand accelerates in suburban United States and United Kingdom markets where remote work permanence sustains dedicated workspace investment. Video-call optimized illumination with minimal shadow casting dominates feature prioritization.
- Freelancers:Independent contractors purchasing task lighting as capital equipment. This segment in India and Brazil exhibits acute price sensitivity paired with demand for battery backup functionality addressing grid reliability gaps. Direct-to-consumer channels capture disproportionate share through social media discovery.
- Corporate:Standardized deployments across enterprise real estate portfolios with centralized procurement.
- Education:Institutional purchasing for libraries, dormitories, and learning commons with extended warranty requirements.
Home office defines current volume leadership. Freelancers represent the steepest expansion trajectory.
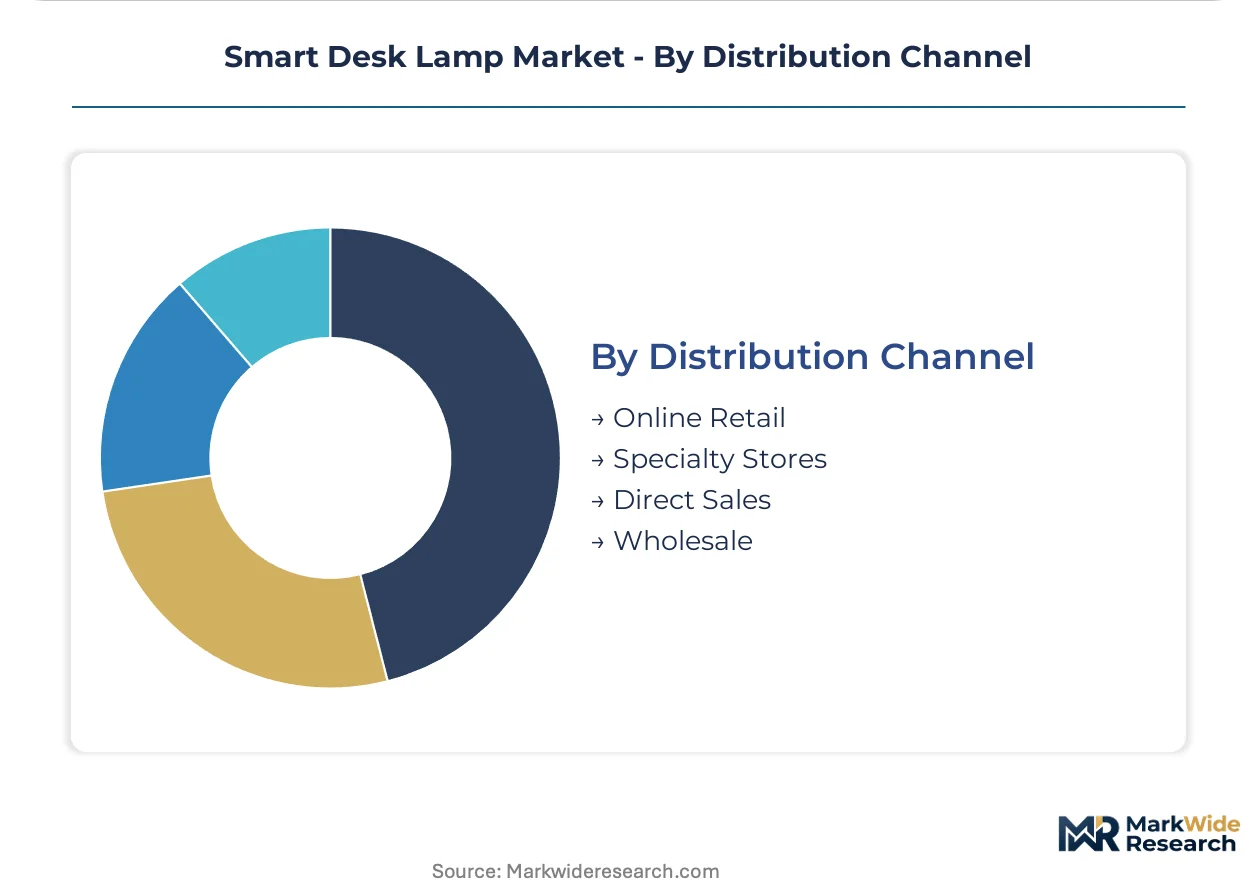
Distribution Channel:
Customer type and geography dictate channel economics, with online retail capturing data-rich relationships while wholesale maintains infrastructure access in underpenetrated regions.
- Online Retail:Amazon, Tmall, and direct-to-consumer brand storefronts enabling first-party usage data capture and bypass of traditional lighting retail markups. United States and Chinese buyers exhibit highest comfort with sight-unseen luminaire purchases when reviews and return policies are transparent. Logistics networks in the Pearl River Delta support 48-hour fulfillment to domestic addresses.
- Specialty Stores:Dedicated lighting showrooms and home office furniture retailers permitting tactile evaluation of articulation mechanics and material finish. German and Japanese consumers demonstrate persistent preference for in-person assessment of color temperature accuracy before commitment.
- Direct Sales:Manufacturer-owned channels for enterprise and institutional contracts with customized specification.
- Wholesale:Electrical distributor networks serving contractor and builder specification in commercial construction.
Online retail holds dominant share. Specialty stores defend positioning in premium tactile evaluation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart desk lamp manufacturing originated in Japanese precision electronics clusters during the 1990s LED transition, then migrated to Pearl River Delta contract assemblers by 2005 as semiconductor packaging costs collapsed.
China
Shenzhen and Dongguan house vertically integrated LED die fabrication, driver IC packaging, and wireless module assembly. MIIT enforces GB standards for electromagnetic compatibility and energy efficiency labeling. The Pearl River Delta corridor ships finished units to North American and European distributors within 72 hours through Nansha and Yantian port infrastructure.
United States
Remote work permanence in suburban markets drives replacement of task lighting with circadian-optimized units. FCC Part 15 governs 2.4 GHz transceiver emissions from Wi-Fi and Zigbee modules. California's Title 20 standby power regulations force circuit redesigns for always-connected lamps targeting West Coast retail channels.
Germany
EU Ecodesign Directive minimum efficiency benchmarks accelerate halogen phase-out across residential and commercial installations. ECHA REACH compliance testing adds fixed cost layers to hazardous substance documentation. Bavarian industrial buyers prioritize ergonomic evaluation through Munich and Nuremberg specialty lighting showrooms before procurement commitment.
Japan
Premium workspace installations in Tokyo and Osaka adopt OLED panels for color rendering index values above 95. METI administers JIS standards for luminaire safety and electromagnetic compatibility. LG Display and Samsung SDI manufacturing constraints limit domestic volume expansion despite technical preference for surface illumination.
India
Urban middle-class expansion in Mumbai and Bengaluru creates demand for battery-backed smart lamps addressing grid reliability gaps. BIS certification mandates safety testing for electrical and electronic goods. Direct-to-consumer platforms capture disproportionate freelancer segment share through Instagram and YouTube discovery algorithms.
Smart Desk Lamp Market Competitive Landscape
The competitive structure tilts toward ecosystem incumbents with proprietary wireless protocols and app backends. Three tiers separate premium hardware specialists from mass-market connectivity vendors and private-label contract assemblers. Strategic differentiation concentrates on firmware subscription tiers and cross-platform Matter compatibility. Dominant competitive moves include direct-to-consumer channel bypass of traditional retail markups and vertical integration into semiconductor driver sourcing.
Among premium-tier hardware architects, Dyson and BenQ occupy positions emphasizing industrial design and screen-optimized illumination. Philips Hue exemplifies ecosystem lock-in through proprietary Zigbee mesh infrastructure. Govee represents aggressive app-centric positioning targeting younger demographics with RGB customization and aggressive price points.
| Leading Market Players |
|---|
| Dyson |
| Lumi |
| Philips Hue |
| Oyen |
| GOI |
| Govee |
| Honeywell |
| Hifree |
| BenQ |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in the Pearl River Delta anchor component supply and exercise pricing discipline through captive LED packaging facilities. Their ownership structure enables long-term capacity planning without quarterly earnings pressure, compressing BOM costs while sustaining margin pools against contract assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and ecosystem lock-in intensity. CE-marked and Matter-certified units command 40-60% premiums over uncertified alternatives in German and US channels. Cost compression in the economy tier is intensifying because Shenzhen contract manufacturers are absorbing microcontroller price volatility to defend volume share. Freelancers in India and Brazil exhibit acute price sensitivity, while corporate procurement in Japan prioritizes warranty terms and color rendering performance above unit cost.
Supply Chain Analysis
GaN-on-sapphire LED die supply rests on Taiwanese and Chinese semiconductor foundries with limited alternative sourcing. Bluetooth SoC and Wi-Fi module production concentrates in China, South Korea, and Taiwan, creating single-source vulnerability for tier-two assemblers without direct foundry relationships. Logistics chokepoints at Nansha and Yantian ports expose EU-bound shipments to seasonal congestion. Distribution runs through Amazon and Tmall storefronts for direct-to-consumer fulfillment, while specialty lighting retailers in Germany and Japan maintain tactile evaluation infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart desk lamp market functions as a stable compounder underpinned by persistent remote work infrastructure investment. Circadian lighting specifications and video-call optimization requirements sustain replacement cycles beyond commodity lighting patterns.
For Market Incumbents: Deepen proprietary protocol ecosystems through Matter compatibility certification to neutralize hub proliferation threats from cross-platform entrants. Acquire embedded firmware engineering talent in Taiwan and South Korea to compress development timelines threatened by wireless stack expertise scarcity. Invest in backward integration into LED driver IC design to defend margin pools against semiconductor cost volatility.
For New Entrants and Emerging Players: The mid-tier price gap between Philips Hue premium positioning and Govee economy aggression creates white-space for app-centric specialists with native circadian algorithms. Target freelancer segments in India and Brazil through Instagram and YouTube discovery channels with battery-backed SKUs addressing grid reliability gaps. Pursue D2C launch strategy to bypass traditional lighting retail markups and capture first-party usage data for feature development.
For Investors and Strategic Acquirers: Consumer electronics conglomerates with smart home platform ambitions are the most active acquirer in this space, seeking firmware subscription revenue streams and ecosystem lock-in mechanics. Mid-cap specialists with captive Shenzhen manufacturing and proprietary app backends represent prime acquisition targets. Watch microcontroller lead time normalization as an inflection indicator for tier-two assembler margin recovery and competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-platform compatibility eliminates hub proliferation and reduces vendor lock-in advantages for Zigbee incumbents. |
| Backward Integration into Driver ICs | Captive semiconductor sourcing insulates margin pools from Bluetooth SoC lead time volatility in Shenzhen. |
| Direct-to-Consumer Channel Expansion | Amazon and Tmall storefronts bypass specialty retailer markups while capturing usage analytics for firmware roadmaps. |
| Subscription Feature Unlocking | Recurring revenue from paywalled circadian algorithms concentrates value capture with ecosystem incumbents. |
| Battery-Backed SKU Development | Grid reliability gaps in Mumbai and Bengaluru create defensible positioning against pure AC-powered competitors. |
Research Methodology
Multiple input streams — primary interviews with lighting product managers, semiconductor procurement leads, and smart home platform engineers; secondary validation through FCC Part 15 filings, EU Ecodesign Directive compliance databases, and SEC 10-K disclosures from listed electronics conglomerates; plus customs trade data from the Pearl River Delta — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation by connectivity protocol, end-user archetype, and regional regulatory cluster. CAGRs were derived from unit shipment trajectories and average selling price erosion curves, incorporating LED efficacy improvement rates and wireless module cost decline assumptions as industry-specific forecast inputs.
Caveats apply where semiconductor supply volatility or REACH compliance cost inflation could materially shift the outlook. Forecasts reflect assumptions about remote work permanence and Matter adoption velocity. A small set of named triggers — microcontroller lead times, EU Ecodesign Directive enforcement intensity, and Li-Fi convergence timelines — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
Kids Desk Lamp Market