
 United States Electric Fireplace Market | 2026-2036
United States Electric Fireplace Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Fireplace Market Insights
UL 127 certification for electric heating appliances is bifurcating the vendor landscape into qualified OEMs and peripheral assemblers. Glen Dimplex Group leverages its captive manufacturing footprint across North American facilities to sustain cost discipline on wall-mounted lines. Twin Star Home anchors its position through exclusive retail partnerships with big-box distributors. Napoleon differentiates via proprietary flame simulation technology that commands premium positioning in the custom installation channel.
United States electric fireplaces are self-contained heating appliances utilizing LED flame projection, ceramic heating elements, and fan-forced convection rated between 4,000 and 9,000 BTU, designed for zone heating and ambient visual display without venting or combustion byproducts. The residential end user segment dominates volume as single-family homeowners prioritize plug-in and retrofit solutions for basement and accessory dwelling unit conversions. Wall-mounted product types capture disproportionate margin share in urban infill projects where floor space commands premium valuation, while freestanding units compete on portability and seasonal repositioning flexibility.
EPA emissions guidelines for wood-burning appliances and evolving DOE energy conservation standards for electric heaters shape product development roadmaps and testing protocols. OSHA workplace safety regulations influence commercial hospitality specifications for flame-effect installations in restaurants and hotels. State-level building codes in California and Massachusetts mandate increasingly stringent electrical efficiency thresholds that filter into national product line architectures. Stakeholders must monitor how municipal electrification ordinances and utility rebate programs reshape specification criteria across regional construction markets.
Market Dynamics
Municipal electrification ordinances in California and New York are compressing traditional combustion fireplace installations while state utility commissions across Texas and Florida accelerate rebate programs for efficient electric alternatives. This regulatory divergence is bifurcating specification patterns between coastal restriction zones and Sun Belt expansion markets.
Growth Catalysts
- California Title 24 building efficiency standards:Municipal fire codes in Los Angeles and San Francisco now prohibit new wood-burning installations in multi-family developments, redirecting developer specifications toward UL 127-certified electric systems.
- Texas utility commission rebate structures:CenterPoint Energy and Oncor Electric Delivery offer point-of-sale incentives for ENERGY STAR-rated zone heating appliances, shortening replacement cycles in Houston and Dallas metro construction.
- LED flame projection maturation:Advances in holographic depth mapping and randomized flicker algorithms now replicate combustion aesthetics without venting infrastructure, satisfying hospitality designers in Miami and Orlando hotel renovations.
Market Restraints
- Ceramic heating element supply concentration:Domestic sourcing of alumina substrates and molybdenum disilicide heating coils clusters in Ohio and Pennsylvania manufacturing corridors, exposing assemblers to regional logistics disruptions.
- Copper and rare-earth magnet cost volatility:Fan motor assemblies and power management components face input price pressure from commodity market swings, compressing margin on entry-level freestanding units.
- Natural gas infrastructure lock-in:Existing pipeline networks and vented fireplace retrofits in Northeastern single-family housing stock create substitution friction against all-electric conversion campaigns.
Strategic Opportunities
- Accessory dwelling unit proliferation:California state law preempting local zoning restrictions on backyard cottage construction creates specification pull for compact wall-mounted units in Bay Area and Los Angeles infill projects.
- Smart home integration convergence:Voice-activated temperature control and occupancy-sensing automation are merging with electric fireplace controls, opening premium positioning through Matter protocol compatibility.
- Florida coastal humidity corrosion:Salt-air degradation of traditional metal firebox installations in Tampa and Naples markets accelerates replacement demand for sealed electronic systems with marine-grade enclosures.
Industry Challenges
- UL 127 certification timeline compression:Testing laboratory backlog for heating appliance safety validation extends product launch windows, forcing OEMs to sequence regional rollouts rather than national simultaneous release.
- Cross-platform smart home protocol fragmentation:Integration engineering resources must support simultaneous development for Amazon Alexa, Google Home, Apple HomeKit, and Samsung SmartThings ecosystems without standardization convergence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Fireplace Market |
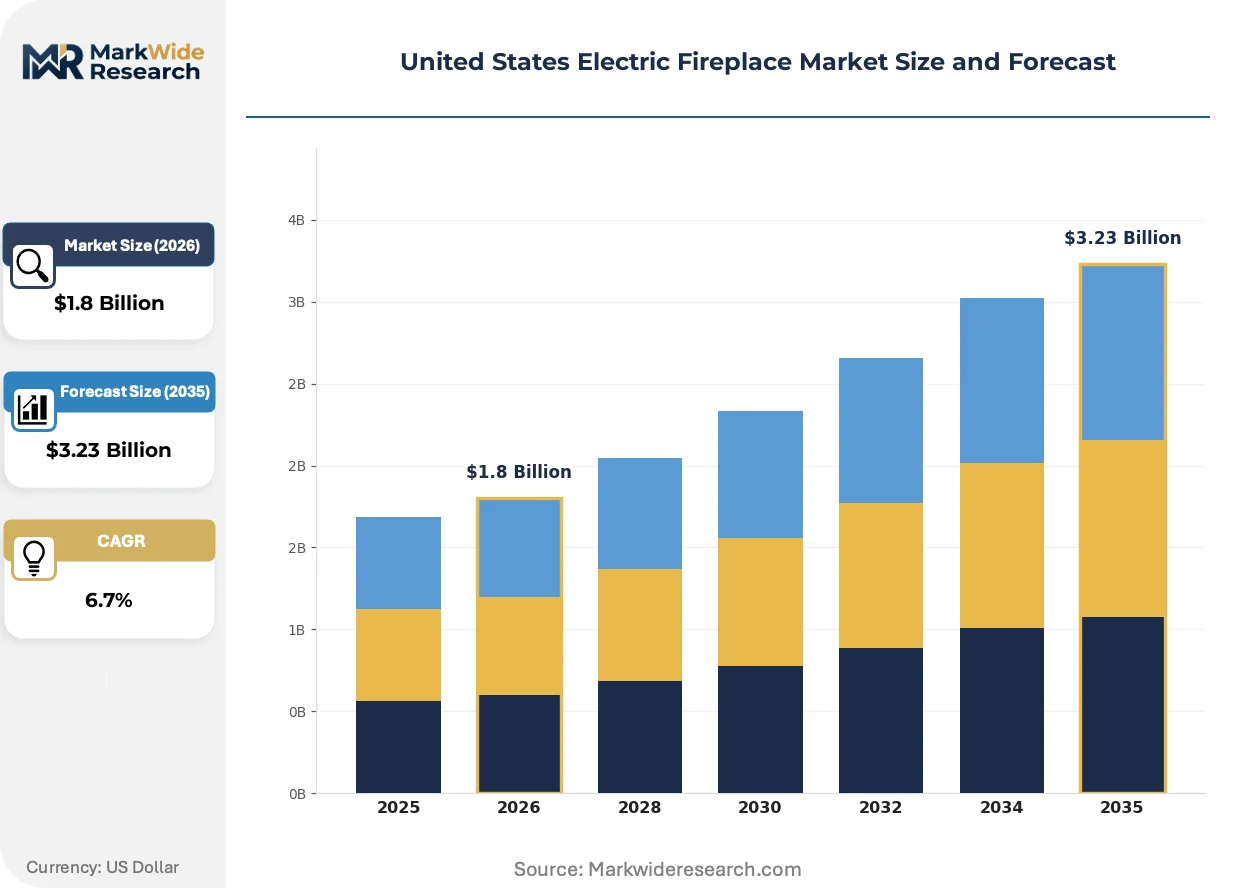
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Freestanding, Inserts, Portable End User: Residential, Commercial, Hospitality, Retail Design Style: Modern, Traditional, Rustic, Contemporary Installation Type: Built-In, Plug-In, Retrofit, Custom |
| Companies Covered | Glen Dimplex Group, Twin Star Home, Napoleon, Hearth & Home Technologies, Empire Comfort Systems, Amantii Electric Fireplaces, Touchstone Home Products, GHP Group, Modern Flames, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Fireplace Market Trends and Innovations
Product architecture is splitting between premium custom-installation systems with proprietary flame simulation and mass-market plug-in units competing on distribution density. This divergence reflects diverging buyer sophistication between design-build contractors and big-box retail consumers.
Holographic flame depth technology is fragmenting the visual performance tier previously dominated by LED screen projection. High-end residential designers in Scottsdale and Austin are specifying units with layered light-field displays that create parallax-adjustable flame perception. This specification pull is compressing margin on conventional two-dimensional screen systems and forcing mid-tier OEMs to license depth-simulation patents or retreat to price-driven portability positioning.
Massachusetts stretch energy code adoption is mandating all-electric readiness in new construction permits issued in Boston, Cambridge, and Somerville jurisdictions. DOE energy conservation standards for electric resistance heating are simultaneously tightening test procedure requirements for standby power consumption. Builders in these municipalities are pre-wiring fireplace locations for electric units regardless of immediate specification, creating embedded future demand that gas-line rough-ins previously captured.
Builder procurement consolidation is compressing vendor access to new construction specification channels. National multi-family developers in Atlanta and Phoenix are centralizing appliance selection through preferred supplier agreements with direct-ship logistics, bypassing traditional distributor markup. Regional electric fireplace OEMs without national account management infrastructure are losing specification access to vertically integrated HVAC conglomerates with bundled mechanical-electrical packages.
United States Electric Fireplace Market Segmentation
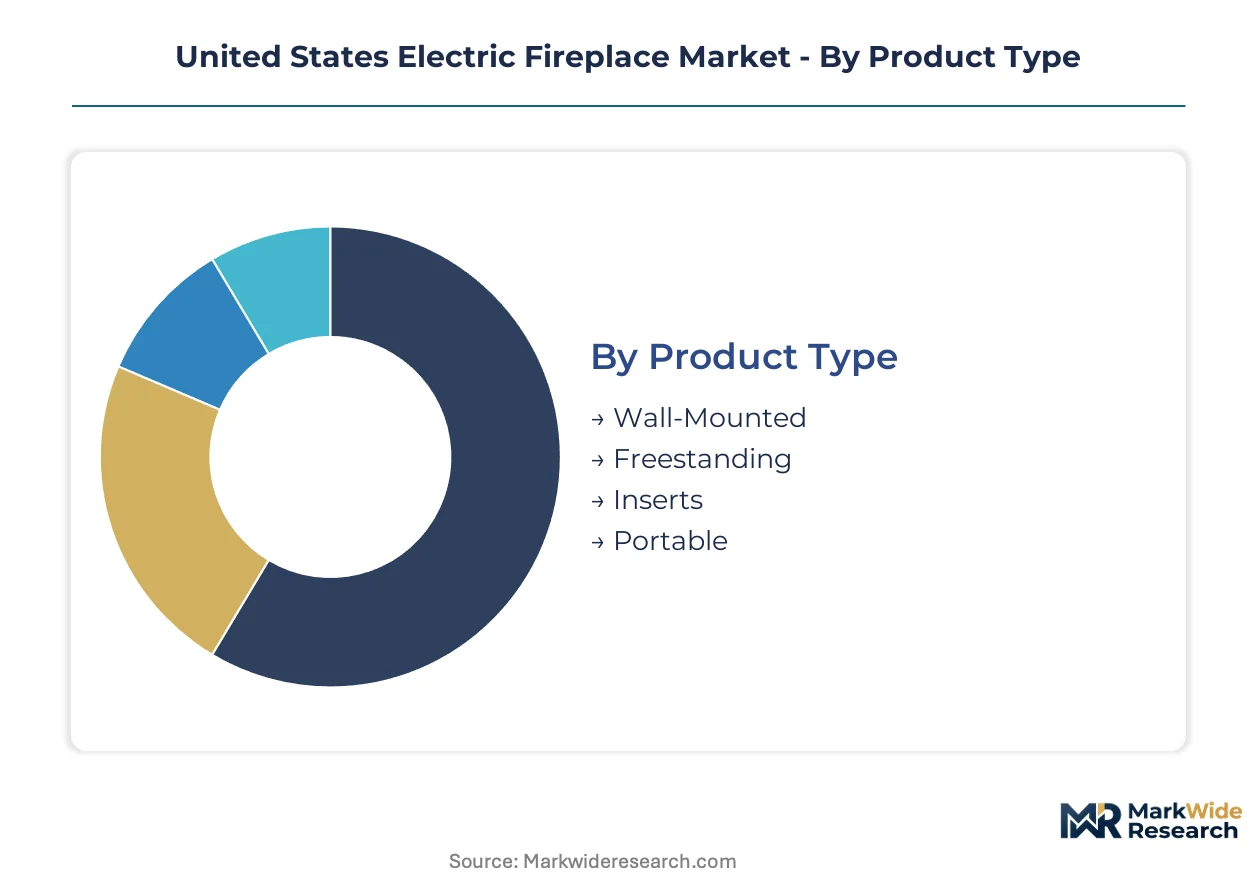
Electric fireplace specification patterns diverge sharply across installation contexts and buyer sophistication levels. Understanding these segment boundaries clarifies why wall-mounted units command premium positioning in urban infill while freestanding alternatives compete on seasonal flexibility in suburban retrofit markets.
Product Type:
Domestic manufacturing concentrates on wall-mounted and freestanding categories, while insert and portable lines draw heavily from Asian component sourcing.
- Wall-Mounted:These units integrate LED flame projection with ceramic heating elements into flat-panel enclosures designed for permanent stud-mount installation. Demand concentrates in California Bay Area and Manhattan multi-family conversions where floor space valuation exceeds heating capacity considerations. Title 24 all-electric readiness mandates in these municipalities accelerate specification for new construction rough-ins.
- Freestanding:Self-contained cabinets with castor mobility or fixed-base positioning utilize fan-forced convection rated between 4,000 and 9,000 BTU without venting requirements. Texas and Florida Sun Belt markets favor these for seasonal repositioning between living zones and accessory dwelling units. CenterPoint Energy and Oncor rebate structures shorten replacement cycles in Houston and Dallas metro areas.
- Inserts:Designed for existing masonry firebox retrofit, these units seal combustion openings with electronic flame display and resistive heating elements.
- Portable:Compact plug-in units with integrated carry handles serve temporary heating needs in rental properties and seasonal residences.
Wall-mounted holds the largest share; momentum sits with freestanding.
End User:
Cost tier stratification separates premium hospitality specifications from mass-market residential procurement through distribution channel divergence.
- Residential:Single-family homeowners in Northeastern and Midwestern markets prioritize zone heating for basement conversions and accessory dwelling units. Massachusetts stretch energy code adoption in Boston, Cambridge, and Somerville mandates all-electric readiness in new construction permits, embedding future electric fireplace demand regardless of immediate specification.
- Commercial:Office building lobby installations and corporate amenity spaces specify UL 127-certified units for visual warmth without combustion liability. OSHA workplace safety regulations influence flame-effect installations in multi-tenant properties.
- Hospitality:Hotels in Miami and Orlando renovation cycles specify holographic depth-mapping systems for lobby and suite ambiance. LED flame projection maturation satisfies designers seeking combustion aesthetics without venting infrastructure or maintenance protocols.
- Retail:Showroom and customer experience spaces utilize electric fireplaces for brand atmosphere creation in furniture and home goods sectors.
Residential dominates absolute volume; hospitality delivers the steepest expansion trajectory.
Design Style:
Application context determines style specification, with modern and contemporary lines aligning to new construction while traditional and rustic serve replacement markets.
- Modern:Minimalist enclosures with glass fronts and linear flame beds align to Scandinavian-influenced interior architecture. These specifications concentrate in Seattle, Portland, and Austin new construction where design-build contractors coordinate fireplace selection with whole-home aesthetic systems.
- Traditional:Mantel-surround configurations replicate colonial and Victorian fireplace proportions for heritage property renovation. Northeastern single-family housing stock with existing pipeline networks creates substitution friction against all-electric conversion campaigns.
- Rustic:Barn wood, stone veneer, and forged-metal detailing serve mountain resort and vacation property markets in Colorado and Utah.
- Contemporary:Transitional styling bridges modern and traditional elements for suburban infill projects seeking broad buyer appeal.
Modern holds the largest share; contemporary is gaining share fastest.
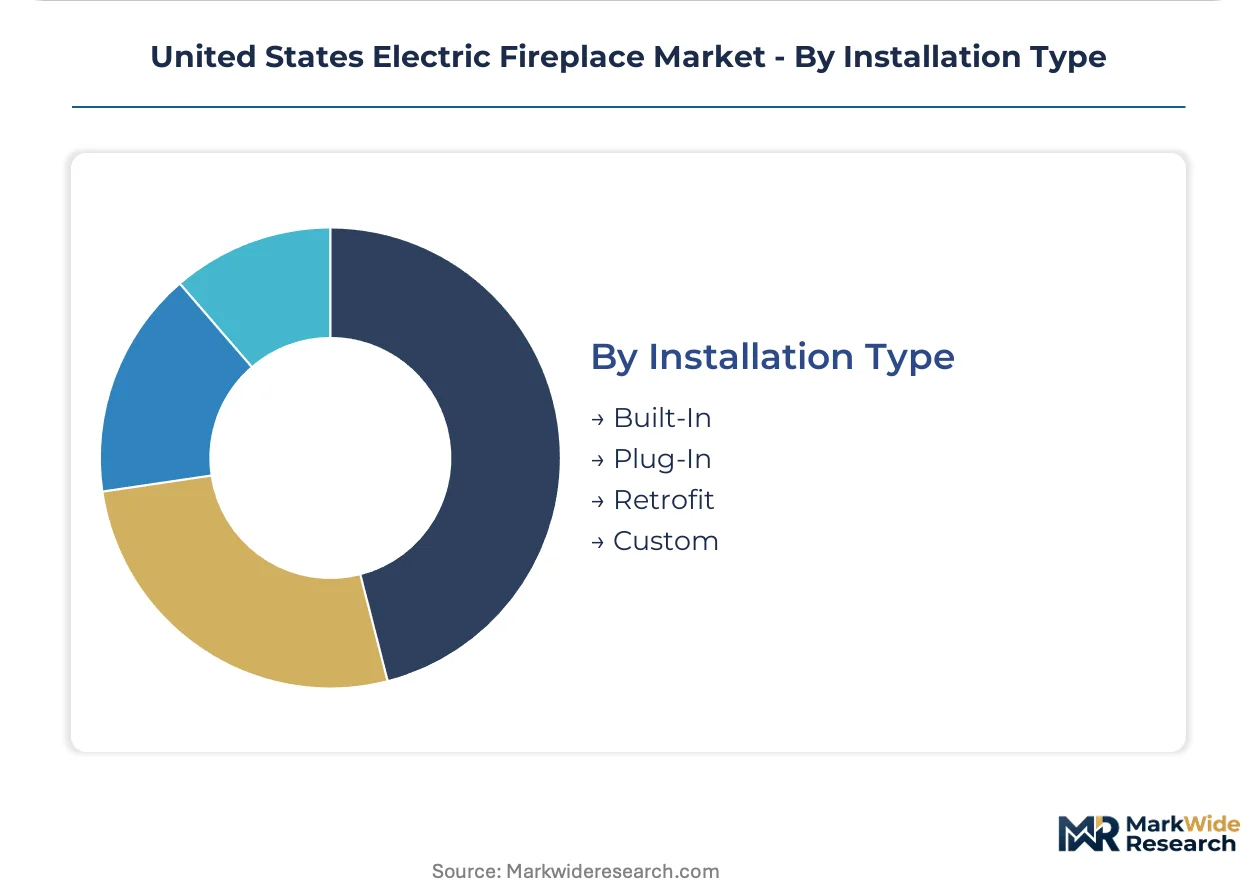
Installation Type:
Customer type bifurcation separates professional channel built-in and custom work from consumer-direct plug-in and retrofit alternatives.
- Built-In:Permanent rough-in installations with dedicated electrical circuits and finished surround integration. National multi-family developers in Atlanta and Phoenix centralize procurement through preferred supplier agreements with direct-ship logistics, bypassing traditional distributor markup for these specifications.
- Plug-In:Consumer-installable units operating on standard 120V outlets without modification. Big-box retail density and seasonal promotional cycles drive volume in this accessible tier.
- Retrofit:Masonry firebox conversion utilizing existing chimney structures for electronic insert mounting. Florida coastal humidity corrosion accelerates replacement demand as salt-air degradation damages traditional metal firebox installations.
- Custom:Architect-specified systems with proprietary flame simulation technology and site-fabricated enclosures. These command premium positioning in Scottsdale and Austin residential design.
Plug-in holds the largest share; built-in is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-family residential developers and hospitality operators concentrate demand across distinct climate zones, with regulatory divergence between coastal restriction markets and Sun Belt expansion corridors reshaping specification patterns.
California
Bay Area and Los Angeles infill projects drive wall-mounted unit specifications as Title 24 all-electric readiness mandates prohibit new wood-burning installations in multi-family developments. Municipal fire codes in San Francisco and Los Angeles redirect developer procurement toward UL 127-certified electric systems. Sacramento-area accessory dwelling unit proliferation creates embedded demand for compact heating solutions in backyard cottage construction.
Texas
Houston and Dallas metro construction outpaces national averages as single-family homeowners prioritize zone heating for basement conversions and seasonal repositioning. CenterPoint Energy and Oncor Electric Delivery point-of-sale rebates for ENERGY STAR-rated appliances shorten replacement cycles. Austin design-build contractors coordinate modern linear fireplace selection with whole-home Scandinavian-influenced aesthetic systems.
Florida
Tampa and Naples markets accelerate replacement demand as salt-air corrosion degrades traditional metal firebox installations, favoring sealed electronic systems with marine-grade enclosures. Miami and Orlando hotel renovation cycles specify holographic depth-mapping systems for lobby ambiance without venting infrastructure. State utility commission incentives align with coastal humidity challenges to displace combustion alternatives.
New York
Manhattan multi-family conversions prioritize wall-mounted units where floor space valuation exceeds heating capacity considerations. Municipal electrification ordinances in New York City compress traditional combustion fireplace installations in new construction permits. Upstate single-family housing stock with existing natural gas pipeline networks creates substitution friction against all-electric conversion campaigns.
Massachusetts
Boston, Cambridge, and Somerville stretch energy code adoption mandates all-electric readiness in new construction permits, embedding future electric fireplace demand regardless of immediate specification. Builders pre-wire fireplace locations for electric units as DOE energy conservation standards tighten standby power consumption test procedures. Regional procurement consolidation through preferred supplier agreements bypasses traditional distributor markup channels.
United States Electric Fireplace Market Competitive Landscape
Player mix skews toward diversified heating appliance conglomerates with captive manufacturing footprints and specialty electric fireplace OEMs competing on flame simulation differentiation. The vendor base separates into three strategic archetypes: vertically integrated HVAC conglomerates bundling mechanical-electrical packages, mid-tier assemblers licensing proprietary visual technology, and regional fabricators serving retrofit replacement channels. Dominant competitive moves include national account management infrastructure buildout for multi-family developer access and patent licensing arrangements for holographic depth-mapping systems.
Within the diversified conglomerate tier, Glen Dimplex Group anchors North American manufacturing presence across multiple facilities, while Twin Star Home exemplifies retail-centric distribution architecture through big-box channel concentration. Napoleon occupies a position on the premium technology vector, representing proprietary flame simulation specialization for custom installation markets. These three entities collectively illustrate the competitive divergence between cost discipline, distribution density, and visual performance premiumization.
| Leading Market Players |
|---|
| Glen Dimplex Group |
| Twin Star Home |
| Napoleon |
| Hearth & Home Technologies |
| Empire Comfort Systems |
| Amantii Electric Fireplaces |
| Touchstone Home Products |
| GHP Group |
| Modern Flames |
| Others |
Pricing and Supply Chain Analysis
Ninety-day ceramic heating element lead times from Ohio and Pennsylvania manufacturing corridors concentrate procurement leverage among vertically integrated OEMs while compressing margin buffers for peripheral assemblers. This inventory pressure feeds directly into pricing power asymmetries across wall-mounted and freestanding product tiers.
Pricing Analysis
Cost-plus contracts indexed to copper and rare-earth magnet commodity exchanges dominate fan motor assembly procurement. Pricing stratifies across premium, standard, and economy tiers based on UL 127 certification status and flame simulation technology depth. Cost compression in entry-level freestanding units is intensifying because of input price volatility, with big-box retail channels exhibiting highest price sensitivity and custom installation hospitality buyers showing lowest.
Supply Chain Analysis
Sixty-day inventory cycles for alumina substrates and molybdenum disilicide heating coils expose assemblers to regional logistics disruptions. Domestic sourcing draws from Ohio, Pennsylvania, and Tennessee manufacturing corridors for ceramic elements, while LED flame projection modules and holographic depth-mapping components source from China and South Korea. Single-source vulnerability concentrates in marine-grade enclosure supply for Florida coastal markets. Distribution runs through big-box retail density for plug-in units and direct-ship logistics for multi-family developer specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between coastal restriction zones and Sun Belt expansion markets fragments specification patterns, creating white-space opportunities for specialized entrants. Municipal electrification ordinances and utility rebate program asymmetries generate niche positioning possibilities across geographic and product-type dimensions.
For Market Incumbents: Compound channel control through exclusive retail partnerships and captive manufacturing footprint expansion. Invest in UL 127 certification pipeline acceleration to compress testing laboratory backlog disadvantages. Counter holographic depth-mapping patent licensing costs through backward integration into flame simulation R&D. For New Entrants and Emerging Players: Anchor in Florida coastal replacement demand for marine-grade sealed electronic systems, where salt-air corrosion accelerates combustion firebox displacement. Target Texas and Florida utility rebate program participation for ENERGY STAR-rated freestanding unit penetration. Pursue voice-activated Matter protocol compatibility as smart home integration differentiation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across holographic depth-mapping technology licensing, reducing barrier thresholds for visual performance tier entry. Acquisition targets with proprietary flame simulation patents and national account management infrastructure for multi-family developer access offer strongest positioning. Watch for UL 127 certification timeline compression as inflection signal for testing laboratory capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Holographic Depth-Mapping Patent Licensing | Secures visual performance tier positioning for Scottsdale and Austin custom installation markets. |
| UL 127 Certification Acceleration | Compresses product launch windows against testing laboratory backlog constraints. |
| Marine-Grade Enclosure Development | Captures Florida coastal replacement demand from salt-air degraded metal fireboxes. |
| Matter Protocol Integration | Opens premium positioning through voice-activated smart home ecosystem convergence. |
| Direct-Ship Logistics Buildout | Bypasses distributor markup for national multi-family developer preferred supplier agreements. |
Research Methodology
Operator-level perspectives from electric fireplace product managers, multi-family developer procurement directors, hospitality design-build contractors, and big-box retail category buyers anchored the qualitative base. Primary interview insights combined with secondary validation from EPA emissions guideline filings, DOE energy conservation standard dockets, state utility commission rebate program documentation, and UL certification registry data. Bottom-up unit shipment analysis triangulated against top-down construction permit and electrification ordinance tracking.
Sensitivity analysis across copper price volatility bands, ceramic heating element lead-time scenarios, and rebate program participation rates informed projection robustness. Segmentation dimensions modeled include product type, end user, design style, and installation type across the analysis window. CAGRs derived from regression against new construction permit trajectories and replacement cycle compression factors, with Title 24 all-electric readiness mandates and CenterPoint Energy rebate structures as key forecast inputs.
Material uncertainties — municipal electrification ordinance adoption timing, ceramic substrate supply disruptions, and smart home protocol standardization convergence — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or commodity price inflection. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
Kids Desk Lamp Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
Landscape Lighting Market