
 Candle Holder Market | 2026-2036
Candle Holder Market Size, Share, and Industry Trends Forecast 2026-2036
Candle Holder Market Analysis
Premium-grade artisan craftsmanship is unwinding across the candle holder landscape as consumers trade up from mass-produced alternatives. Lowe's Companies, Inc. leverages its private-label portfolio to dominate mid-tier home improvement channels. Ingka Holding B.V. anchors Scandinavian design positioning through its IKEA retail network. Walmart Inc. competes on volume scale with seasonal rotating collections that occupy big-box floor space.
A candle holder is a freestanding or suspended receptacle engineered to secure a candle, typically fabricated from heat-resistant glass, cast metal, glazed ceramic, or finished wood, with specifications governing thermal stability, base diameter tolerance, and flame clearance height; its commercial purpose spans ambient illumination, ceremonial function, and interior décor accentuation. Metal and glass material segments lead volume due to durability and refractive aesthetic properties, while ceramic commands margin pools among artisan and gift channels. Rustic and modern style categories capture divergent demand streams, with vintage styling sustaining collector-oriented niche positioning.
REACH in the European Union governs chemical composition of metal alloys and surface coatings, while the Consumer Product Safety Commission in the United States enforces flame stability and tip-resistance standards for tabletop designs. China's GB standards specify heat tolerance thresholds for glassware exported through manufacturing clusters. Stakeholders must monitor evolving material compliance thresholds and channel fragmentation between direct-to-consumer platforms and specialty retail as decisive variables for portfolio allocation.
Market Dynamics
REACH compliance in the European Union is forcing material substitutions across metal and glass finishing processes, compressing supplier margins while elevating certification costs for artisan producers competing against mass-market imports.
Growth Catalysts
- Hospitality procurement expansion:Hotels and restaurants in Germany and the United States are scaling decorative lighting budgets, creating dedicated SKU lines for ambient dining environments.
- ECHA substance restrictions:Lead-free alloy mandates under REACH are accelerating investment in compliant casting technologies among European metalworkers.
- Artisan channel premiumization:Consumer willingness to pay for hand-finished ceramic and wood pieces is consolidating demand around verified craft provenance labels.
Market Restraints
- Aluminum and brass input volatility:Base metal price swings squeeze foundry margins and complicate long-term contract pricing with retail distributors.
- Single-source glass dependency:Specialty borosilicate production concentrates in Chinese manufacturing clusters, exposing importers to shipping disruption and tariff exposure.
- LED ambient lighting substitution:Battery-operated flameless alternatives capture seasonal gift volume previously allocated to traditional holders.
Strategic Opportunities
- Indian urban middle-class penetration:Tier-1 and Tier-2 cities show nascent demand for decorative home accessories as apartment living normalizes.
- EU Green Deal circularity incentives:Recycled glass and reclaimed metal certification programs offer margin premiums and preferential retail placement.
- Direct-to-consumer platform expansion:Social commerce and live-streaming sales channels bypass wholesale markups for established artisan brands.
Industry Challenges
- Master craftsperson attrition:Traditional metal casting and hand-blowing techniques face generational transfer gaps as younger workers migrate to digital manufacturing.
- Multi-jurisdiction certification lag:Simultaneous compliance with REACH, CPSC flame stability rules, and China's GB heat tolerance standards extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candle Holder Market |
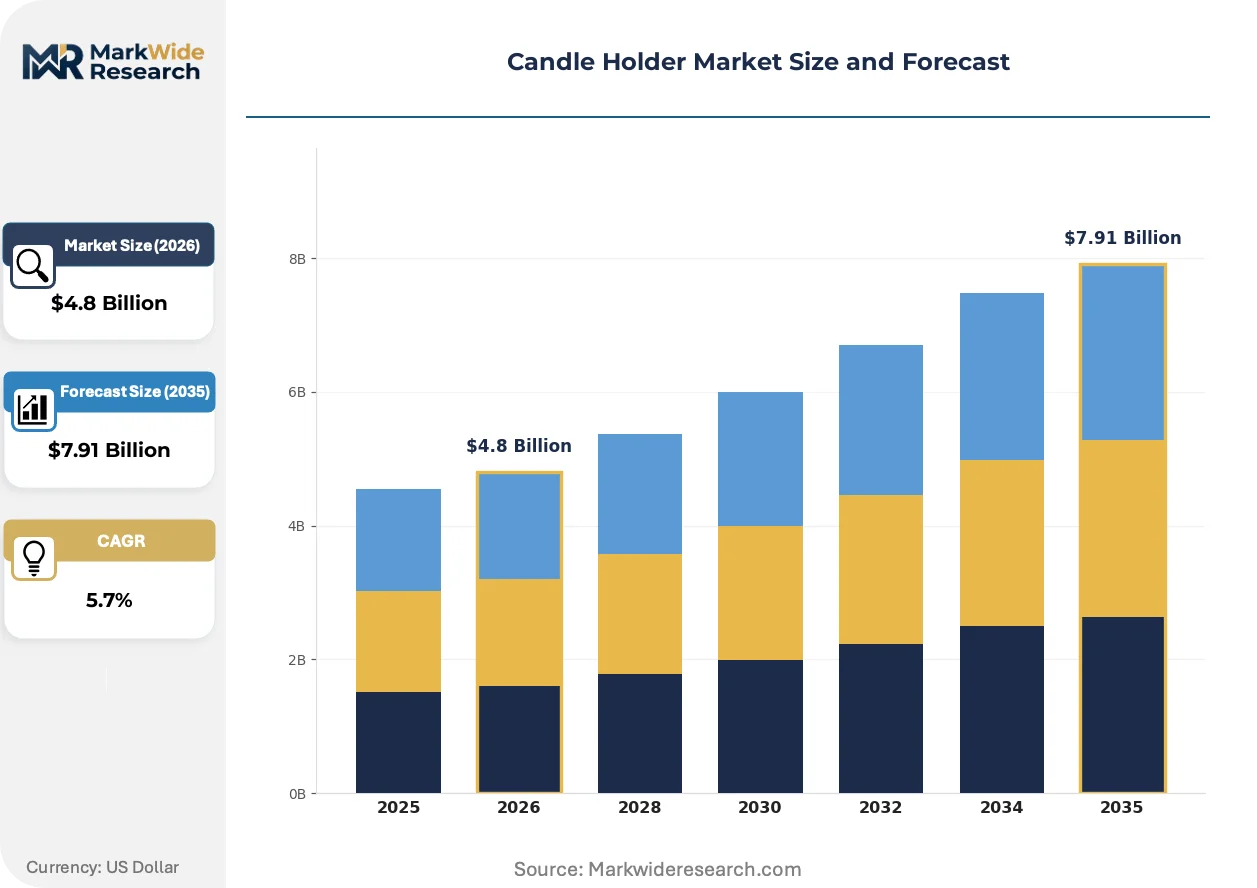
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tea Light Holders, Votive Holders, Pillar Holders, Hanging Holders Material: Glass, Metal, Ceramic, Wood Size: Small, Medium, Large, Extra Large Style: Modern, Rustic, Vintage, Minimalist |
| Companies Covered | Lowe's Companies, Inc., Ingka Holding B.V., Walmart Inc., The TJX Companies, Inc., Target Corporation, Amazon.com, Inc., Newell Brands, Inc., Party City Holdco Inc., The Home Depot, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candle Holder Market Emerging Trajectories
Material science advances and regulatory stringency are converging to reshape production economics, with thermal performance and chemical safety now co-equal design constraints rather than afterthoughts.
Encapsulated LED candle technology is miniaturizing flame simulation components to fit within standard taper and pillar holder geometries. Hospitality buyers in the United States are specifying these hybrid designs for venue insurance compliance. The form factor convergence is compressing the traditional distinction between decorative holder and active luminaire categories.
REACH Annex XVII nickel release restrictions are mandating alternative plating chemistries for metal finishes. European manufacturers are migrating toward ceramic-based coating systems that eliminate allergen exposure risks. Gift channel retailers in Germany and France are demanding batch-level compliance documentation to support product liability defenses.
Subscription-based home décor curation is displacing seasonal big-box purchasing among urban consumers. Millennial and Gen-Z households in the United States and United Kingdom are prioritizing discovery and rotation over accumulation. Direct-to-consumer brands are capturing this behavioral shift through limited-edition artisan collaborations and flexible exchange policies.
Candle Holder Market Segmentation
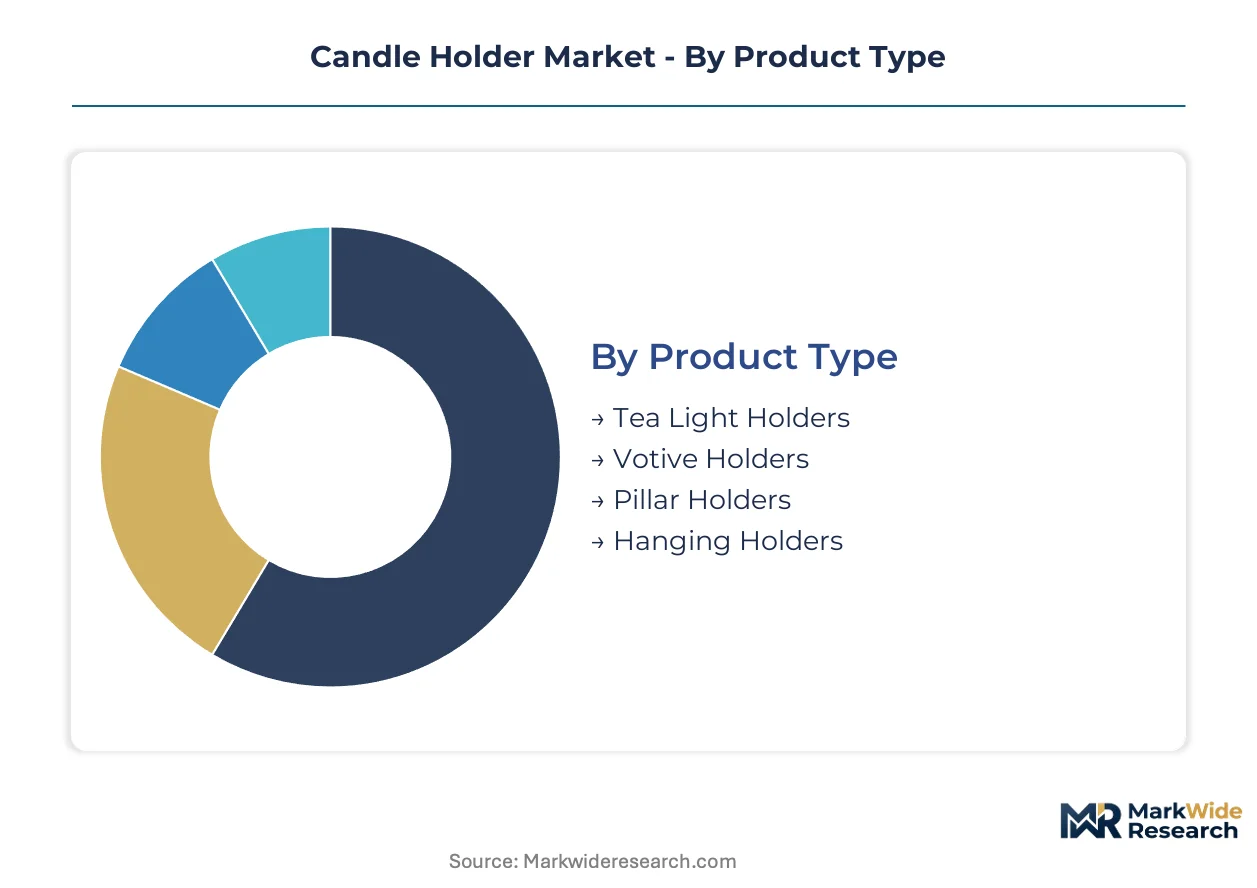
Candle holder segmentation reveals distinct channel affinities that shape procurement strategies. Material and style choices determine whether products flow through hospitality bulk contracts, artisan marketplaces, or mass retail seasonal rotations.
Product Type:
Channel distribution varies sharply by holder geometry, with hospitality buyers favoring stable tabletop designs while gift channels drive suspended formats.
- Tea Light Holders:Compact aluminum or glass shells engineered for heat dissipation across 4-hour burn cycles. Hotels in Germany specify these in bulk for guest room ambient lighting, though LED flameless substitutes erode seasonal gift volume in the United States.
- Pillar Holders:Heavy-base designs with 10cm+ diameter tolerance and flame clearance specifications. Restaurants in the United States scale dedicated SKU lines for dining floor plans, driving premium metal and ceramic procurement.
- Votive Holders:Short cylindrical forms optimized for religious and ceremonial use.
- Hanging Holders:Suspended geometries with reinforced mounting hardware for outdoor and event applications.
By volume, tea light configurations lead. By growth pace, pillar holders for hospitality are expanding most quickly.
Material:
Cost tier alignment determines margin structure, with foundry metals and blown glass commanding premium positioning against pressed alternatives.
- Metal:Cast brass, aluminum, and lead-free alloys governed by REACH nickel release restrictions. European manufacturers migrate toward ceramic-based coating systems to eliminate allergen exposure, compressing supplier margins while elevating certification costs.
- Glass:Borosilicate and soda-lime formulations with specified heat tolerance thresholds. Specialty production concentrates in Chinese manufacturing clusters, exposing importers to shipping disruption and tariff exposure.
- Ceramic:Glazed stoneware and porcelain commanding margin pools among artisan and gift channels.
- Wood:Finished hardwoods with fire-retardant treatments for rustic styling segments.
Metal and glass dominate absolute volume. Ceramic is gaining share fastest among verified craft provenance labels.
Size:
Application context dictates dimensional requirements, with venue scale and candle burn duration driving specification.
- Small:Under 8cm base diameter for personal and travel use.
- Medium:Standard 8-15cm footprint for residential tabletop deployment.
- Large:15-25cm bases for hospitality floor and console placement.
- Extra Large:25cm+ statement pieces for commercial lobby and event staging.
Medium formats anchor residential procurement. Large sizes show the steepest expansion trajectory through hospitality contract growth.
Style:
Customer type fragmentation splits demand between demographic cohorts seeking either curation-driven discovery or functional minimalism.
- Modern:Clean geometries with matte metal and frosted glass finishes. Millennial and Gen-Z households in the United Kingdom prioritize these through subscription-based home décor curation services.
- Rustic:Distressed wood, hammered metal, and imperfect ceramic glazes. Collector-oriented positioning in Germany and France sustains niche premiumization through verified craft provenance.
- Vintage:Reproduction and antique-sourced designs for heritage interior schemes.
- Minimalist:Reduced form factors with hidden structural elements and neutral palettes.
Modern styling leads current volume. Rustic designs climb fastest through artisan channel premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters export borosilicate glass components to hospitality buyers in Germany and the United States, establishing the dominant trade-flow corridor for heat-resistant candle holder materials. REACH compliance costs and ECHA substance restrictions are reshaping procurement patterns across destination markets. Artisan craft networks in India and Eastern Europe are capturing premium positioning through verified provenance labels.
United States
Hospitality venues in Texas and California are scaling dedicated SKU lines for ambient dining environments, driving premium metal and ceramic procurement. The Consumer Product Safety Commission enforces flame stability and tip-resistance standards for tabletop designs. Greater Boston hosts specialty retailers prioritizing subscription-based home décor curation over seasonal big-box purchasing.
Germany
Hotels in Bavaria and North Rhine-Westphalia specify tea light holders in bulk for guest room ambient lighting, creating stable contract demand. ECHA nickel release restrictions under REACH Annex XVII mandate alternative plating chemistries for metal finishes. Berlin-Brandenburg anchors artisan craft networks migrating toward ceramic-based coating systems to eliminate allergen exposure risks.
China
Manufacturing clusters in the Yangtze River Delta and Pearl River Delta concentrate specialty borosilicate production for export markets. GB standards specify heat tolerance thresholds for glassware, creating technical barriers for non-compliant producers. Zhejiang Province foundries face margin compression from REACH-driven material substitution requirements in European buyer specifications.
India
Tier-1 cities Mumbai and Delhi show nascent demand for decorative home accessories as apartment living normalizes among urban middle-class households. The Bureau of Indian Standards governs fire-retardant treatments for wood-based products entering organized retail channels. Rajasthan ceramic artisans are consolidating demand around verified craft provenance labels for export to European gift channels.
United Kingdom
Millennial and Gen-Z households in London and the Southeast prioritize modern styling through discovery-driven subscription services. GDPR compliance shapes direct-to-consumer platform data handling for social commerce and live-streaming sales channels. Midlands manufacturing clusters supply cast metal components to hospitality buyers seeking insurance-compliant hybrid LED designs.
Candle Holder Market Vendor Landscape
Listed leaders compete with private specialists across channel access and sourcing scale, creating a tiered structure where mass retail volume sits adjacent to artisan premium positioning. Big-box retailers leverage private-label portfolios and seasonal floor space dominance, while specialty distributors capture margin pools through craft provenance verification. Three archetypes define competitive positioning: scale-driven mass merchants, design-forward home improvement chains, and curated marketplace platforms. Capacity expansion and portfolio diversification represent the dominant competitive moves, with players extending material science capabilities and hospitality contract capabilities.
Within the scale-driven mass merchant tier, Walmart Inc. and Target Corporation exemplify volume-oriented positioning through rotating seasonal collections and big-box floor space optimization. Among home improvement specialists, Lowe's Companies, Inc. and The Home Depot, Inc. occupy positions anchored in mid-tier channel dominance and private-label development. Ingka Holding B.V. represents the design-forward archetype through Scandinavian aesthetic positioning. Amazon.com, Inc. sits within the curated marketplace vector, capturing behavioral shifts toward discovery and rotation over accumulation.
| Leading Market Players |
|---|
| Lowe's Companies, Inc. |
| Ingka Holding B.V. |
| Walmart Inc. |
| The TJX Companies, Inc. |
| Target Corporation |
| Amazon.com, Inc. |
| Newell Brands, Inc. |
| Party City Holdco Inc. |
| The Home Depot, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term hospitality procurement contracts lock in multi-year supply access for premium metal and ceramic holders while anchoring price visibility against aluminum and brass input volatility. These agreements insulate German hotel chains and United States restaurant groups from spot-market swings while compressing margin buffers for artisan foundries unable to guarantee volume throughput.
Pricing Analysis
Current-generation hand-finished ceramic commands substantial premiums over prior-generation pressed-glass alternatives, while next-generation hybrid LED-compatible designs trade at intermediate tiers. Three-tier pricing structure across artisan-provenance, mid-market private-label, and economy seasonal tiers differentiates primarily by certification grade and craft verification. Cost compression in mid-market metal casting is intensifying because REACH-compliant alloy substitutions elevate foundry processing expenses. Hospitality buyers exhibit the least price sensitivity due to insurance and liability requirements, whereas seasonal gift-channel purchasers drive hard volume negotiations.
Supply Chain Analysis
Inventory lead times for specialty borosilicate glass stretch substantially due to concentrated production in Chinese Yangtze River Delta and Pearl River Delta manufacturing clusters. Raw material flows draw from Zhejiang Province foundries for cast metal components, Rajasthan ceramic workshops for glazed stoneware, and German coating specialists for REACH-compliant finishing systems. Single-source vulnerability concentrates in specialty glass dependency, exposing importers to shipping disruption and tariff exposure. Distribution runs through hospitality contract direct-ship, artisan marketplace platforms, and big-box retail seasonal allocation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity abounds as subscription-based home décor curation displaces traditional seasonal purchasing, creating defendable niches for provenance-verified artisans and direct-to-consumer platforms.
For Market Incumbents: Compound channel control through exclusive hospitality contract extensions and captive supply of REACH-compliant metal finishing capacity. LED flameless substitution and private-label expansion at Lowe's and Target threaten mid-market positioning. Certification investment in ECHA-compliant coating systems offers defensive margin protection. For New Entrants and Emerging Players: Anchor in India's Tier-1 and Tier-2 urban middle-class penetration, where apartment-living normalization drives nascent decorative accessory demand. Rajasthan ceramic artisans and direct-to-consumer social commerce platforms represent the most penetrable white-space targets. Live-streaming sales channels bypass wholesale markups for craft-provenance storytelling. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based home décor curation platforms serving Millennial and Gen-Z households. Long-term viability favors vertically integrated specialists controlling both artisan provenance verification and direct-to-consumer platform infrastructure. Watch for inflection signals in EU Green Deal circularity certification adoption rates among German and French gift-channel retailers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Investment | ECHA nickel release restrictions mandate ceramic-based plating systems for European market access. |
| Direct-to-Consumer Platform Launch | Social commerce and live-streaming channels capture subscription-driven discovery behavior among urban households. |
| Hospitality Contract Expansion | Texas and California venues scale dedicated SKU lines for insurance-compliant ambient dining environments. |
| Artisan Provenance Certification | Verified craft labels consolidate premium positioning in German and French gift channels. |
| Hybrid LED-Compatible Design Development | Form factor convergence addresses United States venue insurance requirements while preserving decorative holder aesthetics. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospitality procurement directors, artisan foundry owners, retail category buyers, and ceramic studio operators. Secondary validation drew from customs trade records, ECHA substance restriction databases, United States Consumer Product Safety Commission guidance documents, and hospitality industry procurement surveys. Bottom-up volume triangulation across material segments and top-down value reconciliation against channel flow data anchored the analytical framework.
Across the analysis window, forecasts modeled material type, holder geometry, style category, distribution channel, and regional regulatory cluster segmentation. CAGRs derived from trend extrapolation of hospitality procurement expansion rates and artisan channel premiumization trajectories. Borosilicate glass supply concentration indices and REACH compliance cost curves informed scenario boundaries.
Decision-makers should treat outputs as directional under sustained hospitality contract growth and stable alloy input cost assumptions; material deviation in trade policy or generational craft transfer rates would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
Table and Floor Lamps Market