
 Kids Desk Lamp Market | 2026-2036
Kids Desk Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Desk Lamp Market Insights
App-enabled brightness scheduling and parental control software is consolidating around hardware ecosystems, transforming one-time lamp purchases into recurring service relationships. Philips leverages its Hue platform to sustain engagement through subscription-based lighting scenes for study routines. Xiaomi anchors its Mi Home ecosystem with aggressively priced connected lamps that feed data into broader smart-home analytics. Yeelight competes on open-platform interoperability, allowing third-party automation tools to control its color-temperature algorithms.
Kids desk lamps are task-oriented luminaires engineered to deliver illuminance between 300 and 500 lux at the reading surface, typically employing diffused LED arrays with color-rendering indices above 90 to reduce visual fatigue during extended study sessions. Their primary purpose is to provide localized, adjustable lighting that supports ergonomic posture and circadian rhythm management for children. LED product types dominate volume due to collapsing component costs and multi-decade lifespan claims, while touch control features command margin premiums by simplifying interfaces for young users. Rechargeable segments are growing fastest as cord-free designs accommodate flexible desk arrangements and shared spaces in compact households.
China's GB standards for LED performance and the EU's RoHS restrictions on hazardous substances in electronics both constrain material choices and drive design investment. The US Consumer Product Safety Commission evaluates tip-over stability and cord safety for fixtures targeting children under twelve. Stakeholders must monitor how emerging blue-light exposure guidelines from health agencies reshape spectral output requirements and certification burdens.
Market Dynamics
The convergence of circadian lighting science with parental anxiety over screen-time eye strain is compressing replacement cycles and elevating certification requirements as the dominant market-shaping force.
Growth Catalysts
- GB standards for LED performance:China's mandatory efficacy and flicker thresholds accelerate fixture turnover in the world's largest manufacturing base, creating spillover demand for export-certified models.
- Home learning infrastructure:Permanent hybrid schooling arrangements in post-pandemic households sustain elevated procurement of dedicated task lighting for children's study spaces.
- Rechargeable lithium-polymer cells:Collapsing battery costs enable cord-free designs that penetrate compact urban dwellings where outlet placement constrains traditional fixtures.
Market Restraints
- Driver IC concentration:Taiwan and South Korea suppliers control 70% of flicker-free LED driver production, exposing assemblers to single-source vulnerability during capacity crunches.
- Optical-grade diffuser plastics:Polycarbonate and PMMA resin prices track petrochemical volatility, compressing margins on entry-tier products where material substitution degrades light quality.
- Blue-light hazard certification:IEC 62471 testing requirements add 8-12 weeks to product launch timelines, disadvantaging smaller manufacturers against scaled competitors with captive labs.
Strategic Opportunities
- India's BIS compulsory registration:Delayed enforcement of quality norms creates a window for early entrants to establish brand recognition before compliance barriers harden.
- Occupational therapy integration:Sensory-friendly lighting protocols for neurodivergent children represent an unaddressed specification gap in current product portfolios.
- Utility demand-response programs:Smart-enabled lamps that modulate output based on grid signals qualify for rebate streams in deregulated electricity markets.
Industry Challenges
- Optical engineering talent:Human-centric lighting design requires rare cross-training in photobiology and industrial design, with university programs lagging commercial need by 3-5 years.
- Multi-protocol smart home integration:Fragmentation across Matter, Zigbee, and proprietary ecosystems forces duplicative SKU development and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Desk Lamp Market |
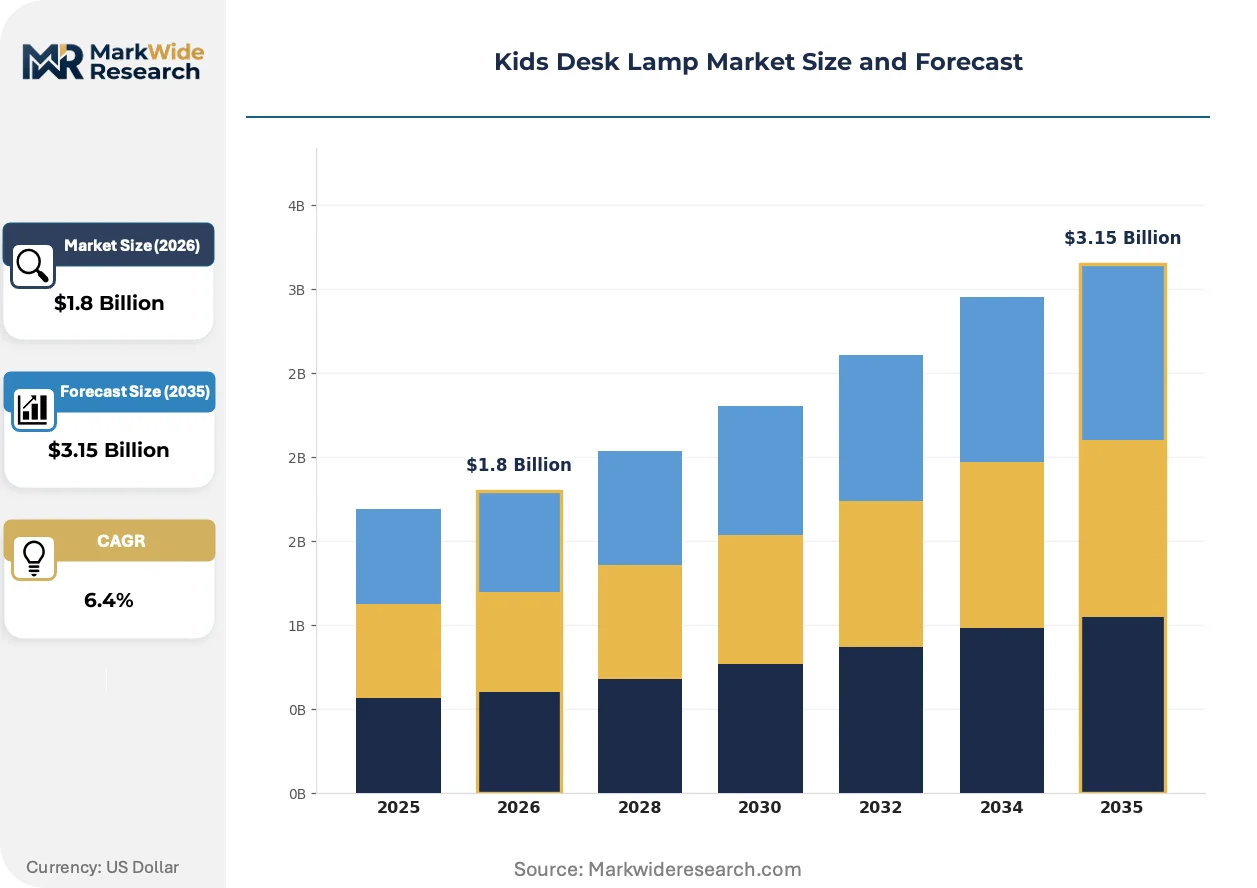
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Rechargeable, Battery-Powered, Adjustable Material: Plastic, Metal, Wood, Fabric Design Style: Modern, Cartoon, Vintage, Minimalist Feature: Touch Control, Dimming, Color Changing, Timer |
| Companies Covered | BenQ, Philips, Xiaomi, Panasonic, Yeelight, OPPLE, Eyespro, Signify, Osram, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Desk Lamp Market Trends and Innovations
Product architecture is fragmenting into interoperable subsystems as manufacturers seek to decouple hardware lifecycles from software capability evolution. This decomposition enables faster iteration and reduces obsolescence risk for end users.
LED array design is modularizing around standardized light-engine platforms that separate thermal management, optics, and control electronics into swappable units. Tier-one fixture brands adopt these architectures to extend product refresh intervals while monetizing upgrade cartridges. The approach compresses R&D amortization across multiple housing designs and accelerates compliance adaptation when spectral output guidelines shift.
RoHS substance restrictions from ECHA are forcing reformulation of solder alloys and phosphor coatings used in high-CRI emitters. Manufacturers serving EU markets now maintain parallel bill-of-materials to segregate compliant and non-compliant supply chains. Pediatric-focused product lines bear disproportionate compliance burden as retailers demand full material disclosure for liability insulation.
Subscription-based lighting scene libraries are displacing perpetual-license software in premium connected segments. Parents in North American and Western European markets demonstrate willingness to pay recurring fees for curated study-routine automations tied to academic calendars. This behavioral shift transforms lamp vendors into ongoing service providers with data monetization potential through anonymized usage pattern aggregation.
Kids Desk Lamp Market Segmentation
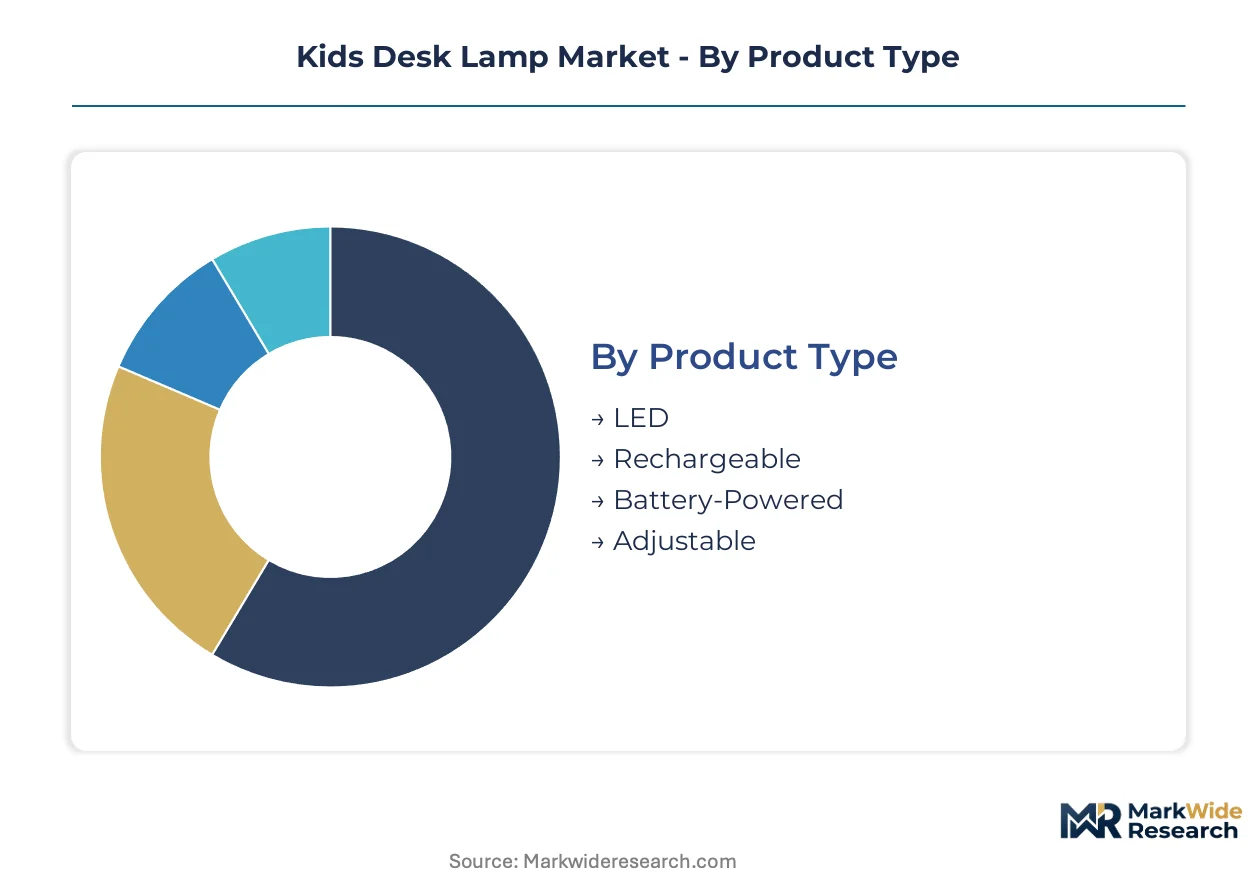
Segmentation in kids desk lamps reveals how technical specifications and aesthetic positioning split procurement decisions across parent demographics. Fixture choices vary sharply between households prioritizing circadian health features versus those seeking decorative room integration.
Product Type:
Standalone task lighting dominates home learning setups, while embedded rechargeable systems penetrate compact multi-use spaces where cord management proves critical.
- LED:Solid-state emitters with efficacy above 100 lumens per watt deliver the 300-500 lux illuminance threshold for reading surfaces. Chinese manufacturing clusters around Shenzhen and Dongguan supply the majority of COB arrays, with GB standards compliance now mandatory for domestic circulation.
- Rechargeable:Lithium-polymer cell integration enables placement flexibility in shared bedrooms and temporary study nooks. South Korean battery suppliers constrain capacity during peak back-to-school procurement windows, creating allocation bottlenecks for smaller assemblers.
- Battery-Powered:Disposable alkaline configurations persist in price-sensitive segments and emergency backup roles.
- Adjustable:Articulating arm mechanisms with three or more pivot points accommodate ergonomic posture variation across age ranges.
LED leads volumes today; Rechargeable is gaining share fastest.
Material:
Cost tier stratification separates premium natural finishes from mass-market synthetic housings, with regulatory pressure on substance safety widening the gap.
- Plastic:ABS and polycarbonate blends offer impact resistance for active children's environments. ECHA RoHS restrictions on flame retardant additives force reformulation cycles every 18-24 months for EU-bound production.
- Metal:Aluminum die-cast housings provide thermal dissipation for high-output arrays and tip-resistant base mass.
- Wood:Sustainable forestry certifications command parent willingness to pay premiums in Nordic and German markets.
- Fabric:Textile shades diffuse glare for ambient room lighting extensions of core task fixtures.
Plastic dominates unit economics; Metal captures margin concentration.
Design Style:
Aesthetic segmentation maps directly onto age-band targeting and room décor coordination, with licensed character collaborations commanding shelf placement premiums.
- Modern:Clean geometric profiles with matte finishes align with contemporary interior design trends. Urban Chinese households in Shanghai and Beijing drive specification intensity for this segment.
- Cartoon:Licensed character housings from entertainment properties convert impulse purchases in retail environments.
- Vintage:Banker-style green glass and brass finishes appeal to design-conscious parents seeking heirloom aesthetics.
- Minimalist:Reduced visual footprint and neutral color palettes suit Scandinavian-influenced nursery and bedroom schemes.
Modern leads current procurement; Minimalist shows steepest expansion trajectory.
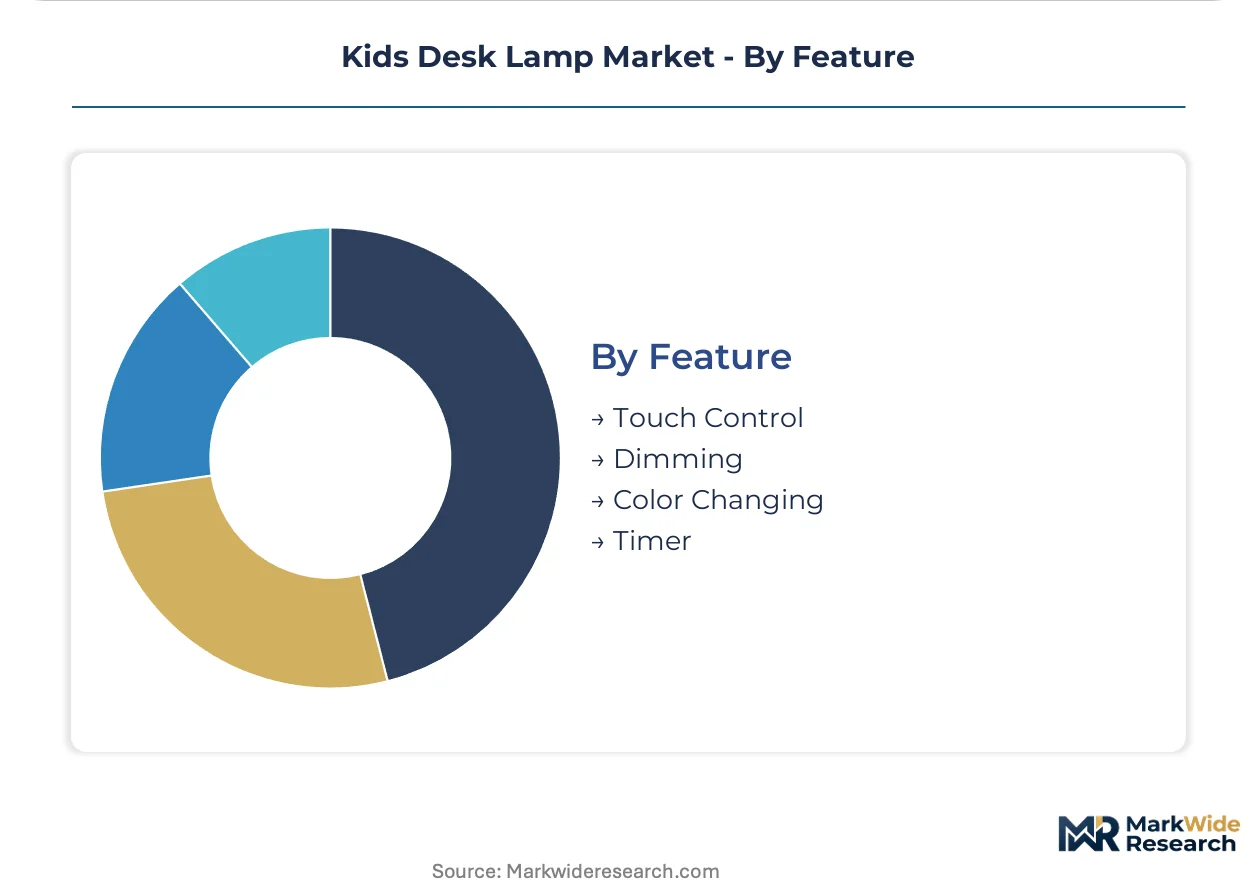
Feature:
Interface sophistication separates entry-tier commodities from experience-differentiated offerings, with parental control functionality now table stakes in connected segments.
- Touch Control:Capacitive surfaces replace mechanical switches for durability and cleanability in children's hands. This interface tier commands 15-20% price premiums over rocker-switch equivalents.
- Dimming:Continuous or stepped luminance adjustment supports circadian rhythm management and evening wind-down routines.
- Color Changing:RGB arrays enable mood setting and sensory regulation for neurodivergent children, an emerging specification gap in current portfolios.
- Timer:Automated shutoff conserves battery charge and enforces screen-time boundaries through lighting cues.
Touch Control anchors volume leadership; Timer functionality is climbing the fastest as parental automation demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing clusters and domestic consumption create volume leadership, while Germany's engineering standards command premium positioning in European procurement.
China
Domestic demand from Shanghai and Beijing households drives fixture upgrades as GB standards for LED performance mandate efficacy thresholds. MIIT enforces flicker-free certification that accelerates product turnover. Shenzhen and Dongguan manufacturing clusters supply COB arrays for both domestic circulation and export-certified models.
Germany
Parental willingness to pay premiums for sustainable forestry certifications shapes wood-finish procurement. ECHA RoHS restrictions on flame retardant additives force 18-24 month reformulation cycles. Bavaria's design-conscious households anchor demand for heirloom-aesthetic vintage banker-style fixtures.
United States
Subscription-based lighting scene libraries convert one-time purchases into recurring revenue in North American households. The Consumer Product Safety Commission evaluates tip-over stability for fixtures targeting children under twelve. Pacific Coast urban markets prioritize cord-free rechargeable designs for compact dwellings.
India
Delayed enforcement of BIS compulsory registration creates a window for early entrants to establish brand recognition. CEA grid stability programs intersect with smart-enabled lamp demand-response qualifications. Maharashtra and Gujarat manufacturing bases scale assembly capacity for price-sensitive battery-powered segments.
Japan
METI circadian lighting guidelines reshape spectral output requirements for pediatric-focused product lines. JIS standards compliance distinguishes premium-tier imports from mass-market alternatives. Kanto region households drive specification intensity for minimalist Scandinavian-influenced nursery designs.
Kids Desk Lamp Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-anchored technology firms capturing recurring revenue streams while OEM assemblers compete on component cost. The vendor base organizes into three tiers: platform-integrated ecosystem players, component-scale specialists, and regional contract manufacturers. Consolidation pressures concentrate among driver IC suppliers, while downstream fixture assembly remains fragmented. Dominant competitive moves include strategic partnerships for smart-home protocol integration and geographic expansion into delayed-enforcement regulatory windows.
Within the platform-integrated tier, Philips and Xiaomi exemplify divergent ecosystem strategies. Philips leverages its Hue infrastructure to sustain engagement through subscription-based lighting scenes. Xiaomi anchors aggressively priced connected lamps within its Mi Home ecosystem. Yeelight occupies a position emphasizing open-platform interoperability for third-party automation tools. Panasonic, BenQ, and OPPLE represent the component-scale specialist archetype, while Eyespro and Signify sit within regional premium positioning segments.
| Leading Market Players |
|---|
| BenQ |
| Philips |
| Xiaomi |
| Panasonic |
| Yeelight |
| OPPLE |
| Eyespro |
| Signify |
| Osram |
| Others |
Pricing and Supply Chain Analysis
Platform-anchored OEM procurement from Xiaomi, Philips, and Yeelight anchors pricing power in subscription-tiered and hardware-plus-service models, compressing margin capture for component-scale assemblers serving undifferentiated retail channels.
Pricing Analysis
Capacity additions in China's Shenzhen and Dongguan manufacturing clusters are reshaping price floors for entry-tier LED fixtures while premium connected segments sustain three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on GB standards compliance tier and Hue/Mi Home ecosystem certification, with parental control software subscriptions commanding recurring revenue streams. Cost compression in polycarbonate diffuser resins is intensifying because petrochemical volatility feeds raw material uncertainty. Mass-market retail buyers exhibit highest price sensitivity; ecosystem-locked households demonstrate lowest.
Supply Chain Analysis
Optical engineering talent shortages in Guangdong province and Zhejiang province constrain ramp speeds for human-centric lighting programs. Manufacturing gravity centers on China, Taiwan, and South Korea, with COB LED arrays and flicker-free driver ICs drawing from concentrated upstream suppliers. Lithium-polymer cells, optical-grade PMMA, and rare-earth phosphors represent critical input dependencies. Single-source vulnerability in Taiwan and South Korea driver production exposes assemblers to allocation crunches. Distribution runs through e-commerce platforms, electronics retail chains, and direct-to-parent subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Parental procurement is shifting toward circadian-certified, flicker-free specifications that command sustained premium positioning over commodity alternatives.
For Market Incumbents: Acquire captive optical engineering capabilities to reduce reliance on scarce cross-trained photobiology-industrial design talent. Defensive consolidation around open-platform interoperability certifications neutralizes Yeelight's third-party automation advantage. Capacity bottlenecks in South Korean battery supply threaten Q3 back-to-school fulfillment for cordless SKUs. For New Entrants and Emerging Players: Capture sensory-friendly lighting protocols for neurodivergent children, an unaddressed specification gap in incumbent portfolios. India's delayed BIS enforcement represents the most penetrable geographic window for brand establishment before compliance barriers harden. Direct-to-occupational-therapist channel development accelerates clinical credibility building. For Investors and Strategic Acquirers: Smart-home ecosystem operators are the most active acquirer in this space, seeking lighting hardware to anchor subscription service expansion. Five-to-ten year viability rests on recurring revenue conversion rates and data monetization infrastructure. Monitor IEC 62471 certification backlog duration as inflection signal for scaled competitor advantage over smaller assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Partnership | Philips Hue and Mi Home ecosystems lock in recurring subscription revenue through lighting scene libraries. |
| Backward Integration into Driver IC Design | Captive flicker-free engineering reduces Taiwan and South Korea supplier concentration risk. |
| Occupational Therapy Channel Development | Sensory-friendly protocols for neurodivergent children open clinically endorsed premium positioning. |
| BIS Pre-Compliance Brand Building | Early Indian market entry before enforcement hardens establishes durable recognition. |
| Modular Light-Engine Architecture | Swappable thermal and optical units extend refresh intervals while monetizing upgrade cartridges. |
Research Methodology
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each market cluster. Product development executives at ecosystem-integrated firms, optical engineering directors at component specialists, retail category buyers, and regulatory affairs leads at export-focused assemblers contributed structured interviews. Secondary validation drew from MIIT GB standards filings, ECHA RoHS substance restriction updates, CPSC safety evaluations, and customs trade flow records. Bottom-up SKU-level buildups and top-down macro allocation triangulated volume and value estimates.
Granularity was maintained at the product-type, material-grade, design-style, and feature-tier levels across the projection horizon. Modeled dimensions included LED versus rechargeable versus battery-powered configurations, plastic versus metal versus wood housing materials, and touch-control versus dimming versus timer functionality splits. CAGRs were derived from segment-level growth rate synthesis calibrated to parent demographic spending elasticity. Circadian lighting science adoption curves and GB standards compliance turnover rates served as industry-specific forecast inputs.
Regulatory enforcement delays, battery cell allocation crunches, and blue-light guideline revisions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding parental willingness-to-pay for connected features and ecosystem lock-in persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Europe Ceiling Fan Market