
 Kitchen Lighting Market | 2026-2036
Kitchen Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Lighting Market Analysis
Multi-source procurement is repositioning how kitchen lighting brands manage component supply and final assembly. Acuity Brands leverages its North American manufacturing footprint to sustain rapid fulfillment for big-box retail channels. Philips Lighting competes through integrated LED module design that reduces downstream installation complexity. Hinkley anchors its market presence in decorative pendant and chandelier categories for premium residential kitchens.
Kitchen lighting encompasses luminaires engineered for task illumination, ambient distribution, and aesthetic integration within food preparation and dining zones, typically operating at color temperatures between 2700K and 4000K with CRI values above 80 for accurate food rendering. LED technology dominates new installations due to lumen-per-watt efficiency and extended operational lifespan exceeding 25,000 hours. Recessed lights and under cabinet lights capture distinct margin pools, with recessed fixtures leading volume in new construction while under cabinet installations grow fastest in renovation activity. Pendant lights occupy the premium decorative segment where design differentiation commands higher price realization.
The Department of Energy enforces minimum efficacy standards that restrict halogen and incandescent sales, while the EU Ecodesign Directive and CE marking requirements shape product eligibility across European distribution channels. China's GB standards and CCC certification govern domestic manufacturing quality and export readiness for kitchen luminaires produced in Guangdong and Zhejiang provinces. Stakeholders must monitor regulatory phase-out schedules and certification alignment to preserve market access across major demand centers.
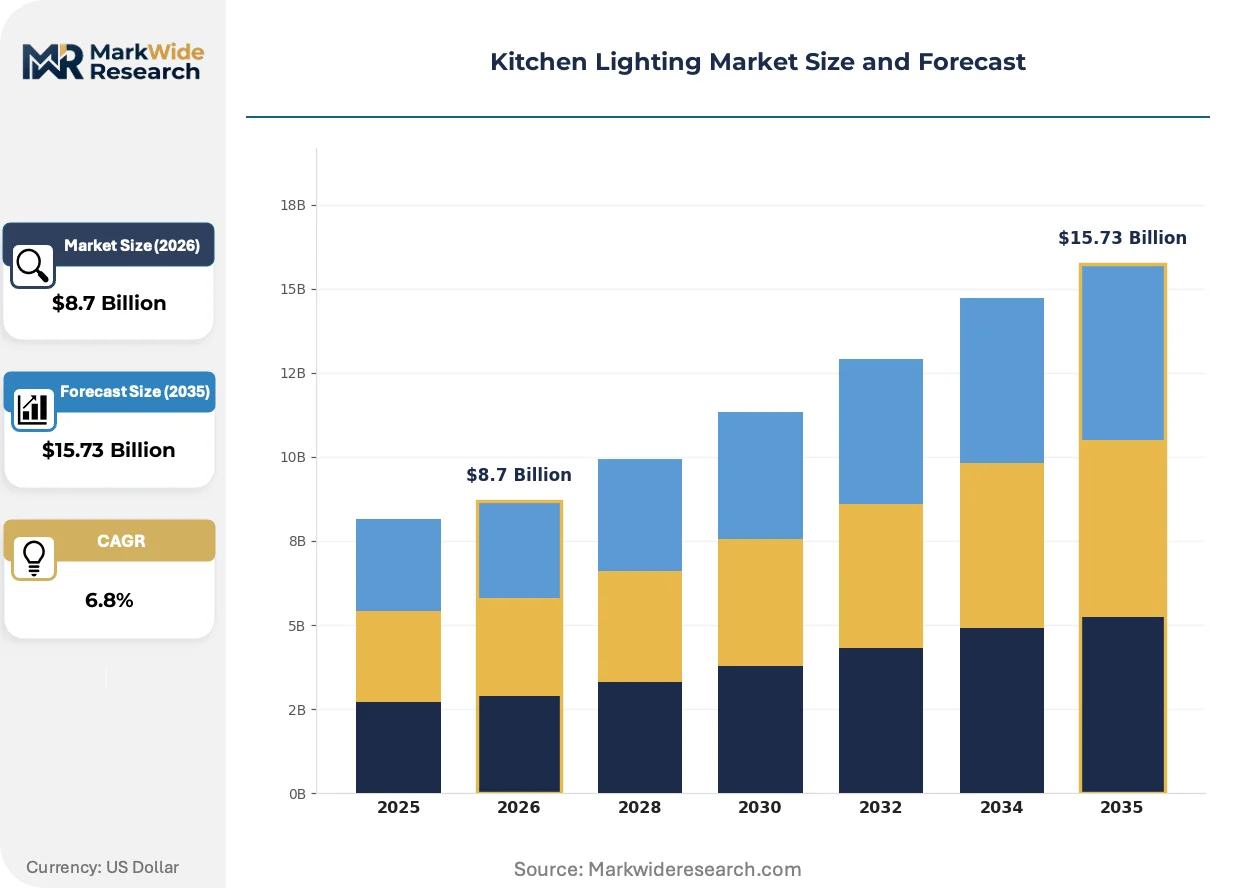
Market Dynamics
LED efficacy mandates from the Department of Energy and EU Ecodesign Directive are compressing fixture replacement cycles while rewiring competitive advantage toward module-integrated suppliers.
Growth Catalysts
- Residential renovation acceleration:Kitchen remodeling rates in the United States and Germany are shortening fixture lifecycles as homeowners prioritize aesthetic upgrades alongside efficiency gains.
- EU Ecodesign Directive:Phased halogen and incandescent phase-outs are forcing technology migration toward LED platforms with integrated driver electronics.
- Guangdong manufacturing cluster:Concentrated LED module production in China's Pearl River Delta is compressing component lead times for North American and European assembly operations.
Market Restraints
- Aluminum and copper price volatility:Heat sink and conductor material costs fluctuate with commodity markets, squeezing margin on mid-tier fixture categories.
- Driver electronics supply concentration:Taiwan and South Korea dominate LED driver IC fabrication, creating single-source vulnerability for luminaire assemblers.
- Wireless protocol fragmentation:Competing smart home standards (Zigbee, Matter, proprietary mesh) complicate interoperability certification and inventory planning.
Strategic Opportunities
- Human-centric lighting protocols:Circadian rhythm tuning features are penetrating premium residential segments as wellness positioning differentiates fixture portfolios.
- India kitchen modernization:Urban middle-class expansion and modular kitchen adoption are creating first-mover advantage for LED-integrated cabinet and task lighting.
- Connected kitchen ecosystems:Voice-activated and sensor-driven illumination is converging with appliance automation, opening bundled specification opportunities with cabinet and appliance manufacturers.
Industry Challenges
- Optical engineering talent scarcity:Specialized lens and reflector design capabilities are concentrated among aging technical workforces in Germany and Japan.
- Multi-certification burden:Simultaneous UL, CE, and CCC testing timelines extend product launch windows and strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Lighting Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recessed Lights, Pendant Lights, Under Cabinet Lights, Track Lighting Technology: LED, Fluorescent, Halogen, Incandescent Installation: Wall-Mounted, Ceiling-Mounted, Surface-Mounted, Flush-Mounted End User: Residential, Commercial, Retail, Hospitality |
| Companies Covered | Feiss, Quoizel, Philips Lighting, ERCO Lighting, Progress Lighting, Maxim Lighting, Minka-Lavery, Acuity Brands, Hinkley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Lighting Market Emerging Trajectories
Illumination control architectures are migrating from wall-switch dominance toward embedded intelligence, rewiring how kitchen lighting is specified, installed, and serviced across residential and commercial channels.
Tunable white LED engines are absorbing specification share in high-end residential kitchens where designers demand seamless transitions from 2700K evening ambiance to 4000K task precision. Custom home builders and kitchen design studios specify these systems at accelerating rates. The technology is absorbing margin from static-CCT alternatives by bundling driver intelligence into the luminaire rather than the wall.
The EU Ecodesign Directive's 2023 tightening of standby power limits is forcing redesign of smart-connected fixtures to eliminate phantom loads. Manufacturers must integrate zero-standby driver topologies or risk market exclusion across European distribution channels. German retail chains and specification channels are demanding compliance documentation ahead of enforcement dates, compressing certification timelines for Asian exporters.
Builder and contractor procurement is consolidating around pre-configured lighting packages specified by kitchen cabinet and appliance OEMs. Traditional electrical distributor channels face disintermediation as cabinet manufacturers bundle illumination into turnkey room solutions. This pattern concentrates most visibly in United States production homebuilding where national builders negotiate master specifications directly with integrated lighting-cabinet suppliers.
Kitchen Lighting Market Segmentation
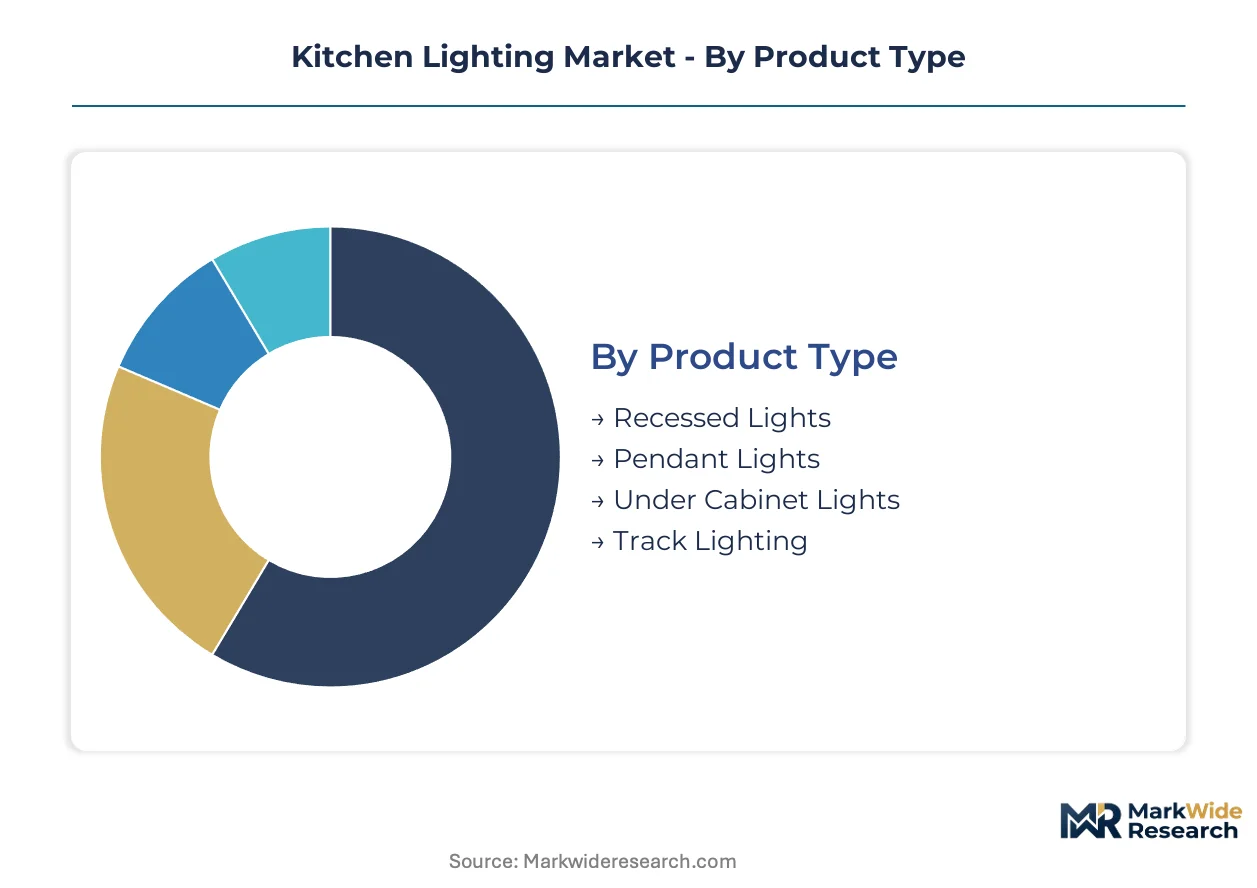
Kitchen lighting segmentation reveals divergent margin structures across fixture categories. Product architecture and installation method determine specification channels and replacement frequency.
Product Type:
Volume concentrates in builder-grade recessed fixtures while premium realization flows through decorative pendants and specialized task luminaires.
- Recessed Lights:Downlight housings with integrated LED modules dominate new residential construction specifications. United States production homebuilders specify these at scale for kitchen ceilings, driven by code-compliant efficacy mandates from the Department of Energy that favor integrated LED architectures over lamp-based alternatives.
- Under Cabinet Lights:Linear LED strips and puck fixtures engineered for task illumination at countertops. Renovation activity in Germany and the United States accelerates retrofit demand as homeowners prioritize food preparation visibility alongside ambient upgrades.
- Pendant Lights:Suspended decorative fixtures commanding design premiums in custom residential kitchens.
- Track Lighting:Adjustable rail systems retaining specification in commercial kitchen and food service environments.
Today's leader: Recessed Lights. Tomorrow's challenger: Under Cabinet Lights.
Technology:
Regulatory phase-outs are compressing legacy technology lifecycles while LED module integration captures specification across all price tiers.
- LED:Solid-state luminaires with efficacy exceeding 100 lumens per watt and operational lifespans surpassing 25,000 hours. EU Ecodesign Directive mandates and Department of Energy standards are eliminating competing technologies from distribution channels in Germany, France, and the United States.
- Halogen:Tungsten-halogen lamps facing phased elimination under EU standby power regulations and comparable US efficiency standards.
- Fluorescent:Linear tube fixtures retaining presence in commercial kitchen retrofits with existing housing infrastructure.
- Incandescent:Legacy filament technology restricted to specialty decorative applications exempt from broad regulatory prohibition.
LED holds absolute dominance. Halogen retains marginal presence only where regulatory exemptions apply.
Installation:
Mounting geometry determines electrical contractor labor allocation and renovation feasibility.
- Ceiling-Mounted:Suspended and surface-ceiling configurations standard in residential new construction.
- Wall-Mounted:Sconce and bracket fixtures for accent illumination in dining-adjacent kitchen zones.
- Surface-Mounted:Direct-to-ceiling housings preferred in retrofit applications where plenum access is constrained.
- Flush-Mounted:Low-profile luminaires integrating with architectural ceiling planes in contemporary residential design.
Ceiling-Mounted fixtures generate highest volume. Surface-Mounted configurations are expanding most quickly in renovation channels.
End User:
Customer type segments reveal divergent procurement patterns and specification authority structures.
- Residential:Single-family and multi-family housing where homeowners or builders direct fixture selection. United States kitchen remodeling rates and German residential renovation subsidies concentrate demand in owner-occupied housing.
- Commercial:Corporate food service and institutional kitchen facilities prioritizing durability and maintenance access over design differentiation.
- Retail:Food retail environments with display case and preparation area illumination requirements.
- Hospitality:Restaurant and hotel kitchen operations where lighting quality intersects with health inspection compliance and staff working conditions.
Residential commands volume leadership. Commercial offers steadiest replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors kitchen lighting manufacturing concentration, with Shenzhen and Foshan housing integrated LED module foundries that supply assembly operations across North America and Europe. Fixture demand concentrates in residential renovation corridors where regulatory mandates accelerate technology turnover.
United States
Kitchen remodeling activity in the Sun Belt and Northeast corridors shortens fixture replacement cycles as homeowners prioritize aesthetic upgrades. Department of Energy efficacy mandates eliminate halogen and incandescent options from retail channels, compressing specification toward integrated LED architectures. Dallas and Atlanta distribution hubs coordinate rapid fulfillment for big-box retail and production homebuilder procurement.
Germany
Residential renovation subsidies in Bavaria and North Rhine-Westphalia concentrate demand for under-cabinet and recessed LED retrofits. EU Ecodesign Directive standby power limits force redesign of smart-connected fixtures, with Berlin and Munich retail chains demanding compliance documentation ahead of enforcement dates. Stuttgart engineering consultancies specialize in optical lens design for premium residential segments.
China
Urban middle-class expansion in Shanghai and Beijing accelerates modular kitchen adoption, creating specification demand for integrated cabinet and task illumination. GB standards and CCC certification govern domestic manufacturing quality in Guangdong and Zhejiang export zones. Zhongshan fixture assemblers compress lead times through captive LED module sourcing from adjacent Shenzhen suppliers.
India
Metropolitan kitchen modernization in Mumbai and Delhi-NCR drives first-mover specification of LED-integrated cabinet systems. Bureau of Indian Standards efficacy regulations align product eligibility with international efficiency benchmarks. Gujarat and Tamil Nadu manufacturing zones scale assembly capacity for domestic distribution and regional export.
United Kingdom
London and Southeast England kitchen renovation activity concentrates specification authority among design studios and custom builders. CE marking requirements post-Brexit transition maintain alignment with EU Ecodesign standards for fixture import eligibility. Midlands distribution corridors coordinate logistics for pan-European assembly component flows.
Kitchen Lighting Market Vendor Landscape
Global majors compete with regional champions across certification bandwidth and channel access. The vendor base stratifies into three tiers: integrated module suppliers with captive driver electronics, decorative specialists commanding design premiums, and scale-driven assemblers serving production homebuilders. Competitive moves concentrate on geographic expansion through distributor acquisition and portfolio diversification into connected lighting ecosystems.
Within the integrated technology tier, Acuity Brands and Philips Lighting exemplify module-forward positioning that reduces downstream installation complexity. Among decorative specialists, Hinkley occupies a position anchored in premium pendant and chandelier categories for custom residential kitchens. Feiss and Quoizel represent mid-market archetypes competing through design breadth and retail channel penetration.
| Leading Market Players |
|---|
| Feiss |
| Quoizel |
| Philips Lighting |
| ERCO Lighting |
| Progress Lighting |
| Maxim Lighting |
| Minka-Lavery |
| Acuity Brands |
| Hinkley |
| Others |
Supply Flow & Price Mechanics
Production homebuilder procurement consolidation in the United States is compressing fixture margins and forcing Asian assemblers to absorb aluminum and copper volatility through longer-term contract structures. This demand-side concentration rewards suppliers with captive LED module production while squeezing pure-play decorative specialists.
Pricing Analysis
Aluminum heat sink and copper conductor costs pass through to fixture pricing with a three-to-six-month lag, pressuring mid-tier recessed and under-cabinet categories most acutely. Three-tier pricing structure across premium, standard, and economy levels separates decorative pendants with optical engineering investment from commodity builder-grade downlights. Cost compression in standard-tier fixtures is intensifying because Taiwanese driver IC supply concentration limits sourcing flexibility. Production homebuilders exhibit highest price sensitivity, while custom kitchen design studios prioritize CRI performance and tunable white capabilities over unit cost.
Supply Chain Analysis
Domestic-content requirements in India's Bureau of Indian Standards efficacy regulations are redirecting component flows toward Gujarat and Tamil Nadu assembly zones. Guangdong province, Taiwan, and South Korea anchor global LED module and driver IC supply. Raw material dependencies center on aluminum for thermal management, copper for conductors, and rare-earth phosphors for white LED color rendering. Single-source vulnerability in Taiwanese driver fabrication creates inventory risk for North American and European luminaire brands. Distribution runs through big-box retail chains, electrical distributors, and direct cabinet OEM partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Ecodesign Directive standby power limits and Department of Energy efficacy mandates continuously reset baseline technology requirements and compress replacement cycles.
For Market Incumbents: Anticipate cabinet OEM bundling disintermediating traditional electrical distributor channels by securing master specification relationships with national production homebuilders. Backward integration into LED module design protects margin from driver IC supply concentration. Prioritize zero-standby driver topology R&D to preserve European market access ahead of enforcement deadlines.
For New Entrants and Emerging Players: Capture India's metropolitan kitchen modernization corridor through modular cabinet partnerships and Bureau of Indian Standards certification investment. Circadian rhythm tuning and human-centric lighting protocols offer penetrable premium residential white space. A specification-direct approach targeting kitchen design studios bypasses entrenched retail channel barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale decorative specialists possessing optical engineering talent and established CE/UL certification bandwidth. Long-term viability hinges on connected lighting ecosystem integration and voice-activated control protocol compatibility. Watch for Matter standard adoption rates as inflection signal for smart kitchen lighting bundling opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Module Backward Integration | Captive Shenzhen sourcing insulates Acuity Brands and Philips Lighting from Taiwanese driver IC volatility. |
| Cabinet OEM Partnership | Master specifications with national builders concentrate procurement authority away from electrical distributors. |
| Zero-Standby Driver Redesign | EU Ecodesign Directive compliance preserves German and French retail channel eligibility for Asian exporters. |
| Circadian Rhythm Capability Launch | Tunable white engines differentiate premium portfolios for custom kitchen design studios. |
| India Manufacturing Footprint | Gujarat and Tamil Nadu assembly positions suppliers for Bureau of Indian Standards-aligned domestic demand. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and the United Kingdom, with primary inputs from each market's stakeholder ecosystem. The analysis combines interviews with kitchen design studio principals, electrical contractor procurement leads, cabinet OEM specification managers, and LED module engineering directors with secondary validation from Department of Energy efficacy filings, EU Ecodesign Directive documentation, Bureau of Indian Standards notifications, and customs trade data. Bottom-up fixture shipment analysis and top-down residential construction and renovation spending triangulation anchor volume and value estimates.
Granularity-level modeling disaggregates the kitchen lighting market across product type, technology platform, installation method, and end-user category throughout the forecast period. CAGRs derive from regression analysis against residential renovation spending indices, regulatory phase-out schedules, and LED efficacy improvement curves. Specific forecast inputs include kitchen remodeling permit data from Sun Belt and Northeast U.S. corridors and modular kitchen adoption rates in Shanghai and Mumbai metropolitan zones.
Aluminum and copper commodity price swings, wireless protocol standardization outcomes, and regulatory enforcement timing shifts are the dominant revision risks to modeled trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
Kids Desk Lamp Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market