
 Floor Lamps Market | 2026-2036
Floor Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Lamps Market Intelligence
Lighting design talent is rotating toward smart-enabled fixture development, tightening the pool available for traditional incandescent craftsmanship. Koninklijke Philips N.V. leverages its Amsterdam-based R&D hub to sustain LED driver integration across residential lines. Signify anchors European commercial specifications through its Interact connected lighting platform. IKEA competes on flat-pack logistics and circular material sourcing, dominating mass-market distribution in Nordic and German retail corridors.
A floor lamp is a portable luminaire comprising a weighted base, vertical support member, and light source positioned above eye level, typically delivering ambient or task illumination between 800 and 3,000 lumens depending on optical design and source efficacy. Metal and glass material segments command margin pools in premium residential channels where brushed brass and hand-blown opal diffusers signal design authenticity. LED light source configurations represent the fastest-growing structural category as EU Ecodesign and RoHS constraints render halogen and CFL alternatives commercially untenable across hospitality and educational end-user applications.
The EU Ecodesign Directive and REACH chemical compliance framework mandate phasing of mercury-bearing sources and restrict heavy metals in metal finishes, forcing reformulation of plating baths and solder joints throughout Polish and Italian manufacturing basins. CE marking under the Low Voltage Directive governs electrical safety for all luminaires sold within member states, creating non-tariff barriers for non-compliant Asian imports. Stakeholders must monitor the EU AI Act's emerging implications for voice-activated smart lamps and decide whether to internalize cybersecurity certification or outsource compliance to specialized testing houses.
Market Dynamics
The EU Ecodesign Directive's phase-out of halogen and incandescent sources is compressing fixture design cycles and forcing rapid LED driver integration across residential and hospitality portfolios.
Growth Catalysts
- Smart Home Integration:Voice-activated control protocols are penetrating German and French urban renovation clusters, pulling premium torchiere and arc designs into connected lighting ecosystems.
- REACH Chemical Compliance:Heavy metal restrictions in plating baths are accelerating reformulation investments across Polish and Italian manufacturing basins, creating first-mover advantages for compliant suppliers.
- Solid-State Lighting Migration:LED efficacy improvements above 150 lumens per watt are rendering legacy CFL alternatives commercially untenable in educational and hospitality specifications.
Market Restraints
- Driver Component Volatility:Semiconductor shortages in LED power electronics create lead time uncertainty for fixture assemblers dependent on East Asian chip foundries.
- Artisan Skill Concentration:Hand-blown opal glass and brushed brass finishing expertise clusters in Northern Italian and Portuguese craft zones, limiting scalable premium output.
- Substitution by Integrated Architectural Lighting:Recessed linear systems and cove illumination in new-build residential construction displace portable ambient fixtures.
Strategic Opportunities
- Circular Material Sourcing:EU Green Deal circularity requirements create margin pools for suppliers mastering recycled aluminum and reclaimed glass logistics.
- Cybersecurity Certification Services:The EU AI Act's emerging voice-activation mandates open specialized testing house partnerships for manufacturers lacking in-house compliance capabilities.
- Urban Renovation Clusters:Berlin and Paris apartment modernization waves concentrate demand for space-efficient arc and task-oriented floor lamp configurations.
Industry Challenges
- Lighting Design Talent Rotation:Smart-enabled fixture development is tightening the pool available for traditional incandescent craftsmanship, compressing heritage product development timelines.
- CE Marking Complexity:Low Voltage Directive electrical safety testing creates non-tariff barriers for non-compliant Asian imports, extending certification cycles for new market entrants.
- Legacy System Integration:Proprietary smart home protocols fragment connectivity standards, forcing multi-platform compatibility investments that dilute R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Lamps Market |
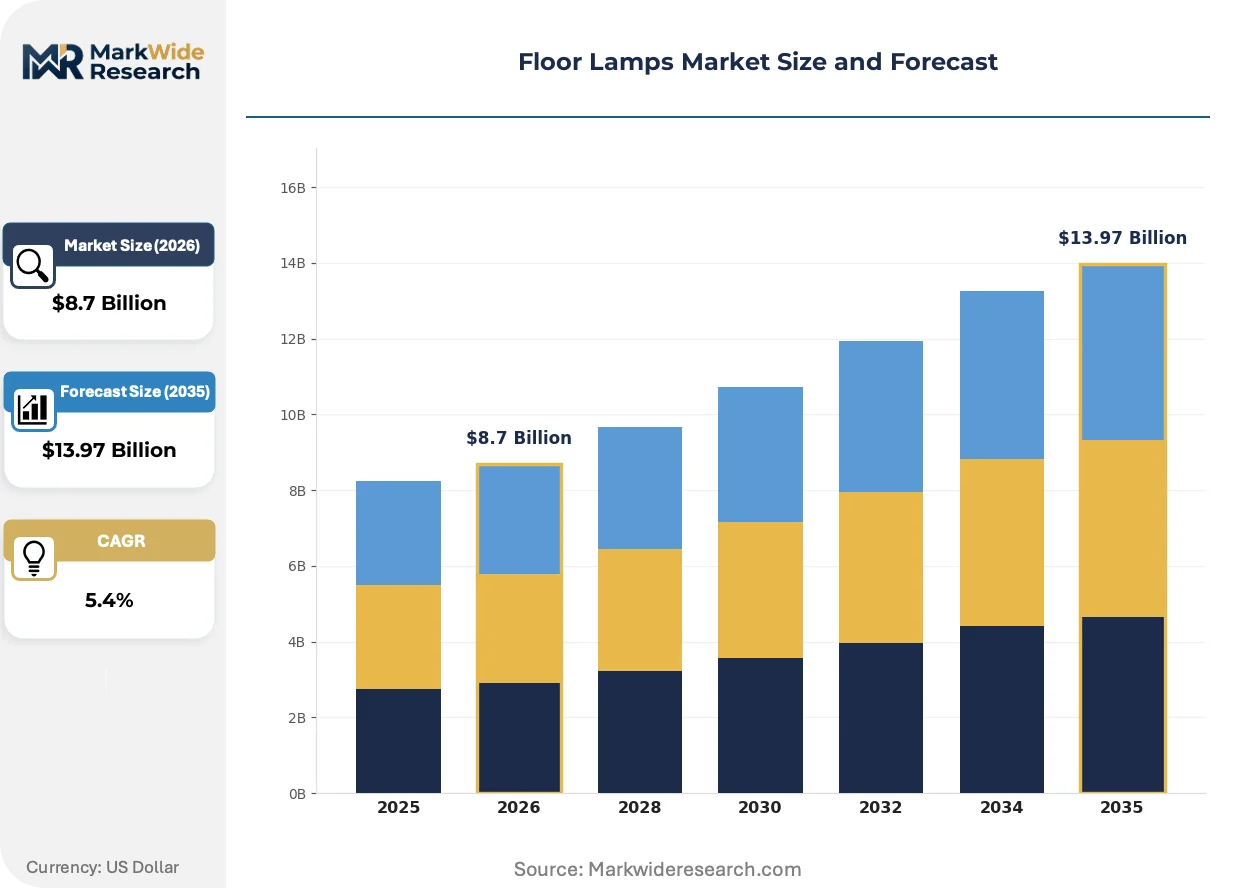
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Torchiere, Swing Arm, Arc, Tripod, Bankers Material: Metal, Wood, Glass, Plastic, Fabric Light Source: LED, Incandescent, Fluorescent, Halogen, CFL End User: Residential, Commercial Offices, Hospitality, Educational Institutes, Libraries |
| Companies Covered | IKEA, Koninklijke Philips N.V, Signify, Artemide, Flos, Louis Poulsen, GUANYA, YLlighting, AOZZO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Lamps Market Strategic Shifts & Innovations
Fixture miniaturization and connected intelligence are converging to reshape residential illumination procurement, compressing the boundary between portable and architectural lighting categories.
Chip-on-board LED modules is miniaturizing optical engines while maintaining lumen output, enabling slimmer vertical support profiles in premium residential lines. German and French interior designers are specifying these reduced-form-factor units for compact urban apartments. The technology is compressing traditional shade-to-source dimensional ratios, allowing arc designs with tighter curvature radii.
REACH chemical compliance enforcement is tightening heavy metal restrictions in metal finishing processes across European manufacturing basins. Plating bath reformulation investments are concentrating in Polish and Italian supplier networks. Hospitality specification channels are responding by auditing supplier certificates of compliance before contract award.
Direct-to-consumer channel expansion is fragmenting traditional retail concentration in Nordic and German mass-market corridors. IKEA's flat-pack logistics model faces disintermediation pressure from digitally native brands offering configurable finishes and shorter fulfillment windows. This pattern is most visible in Netherlands and Denmark urban consumer segments prioritizing customization over immediate availability.
Floor Lamps Market Segmentation
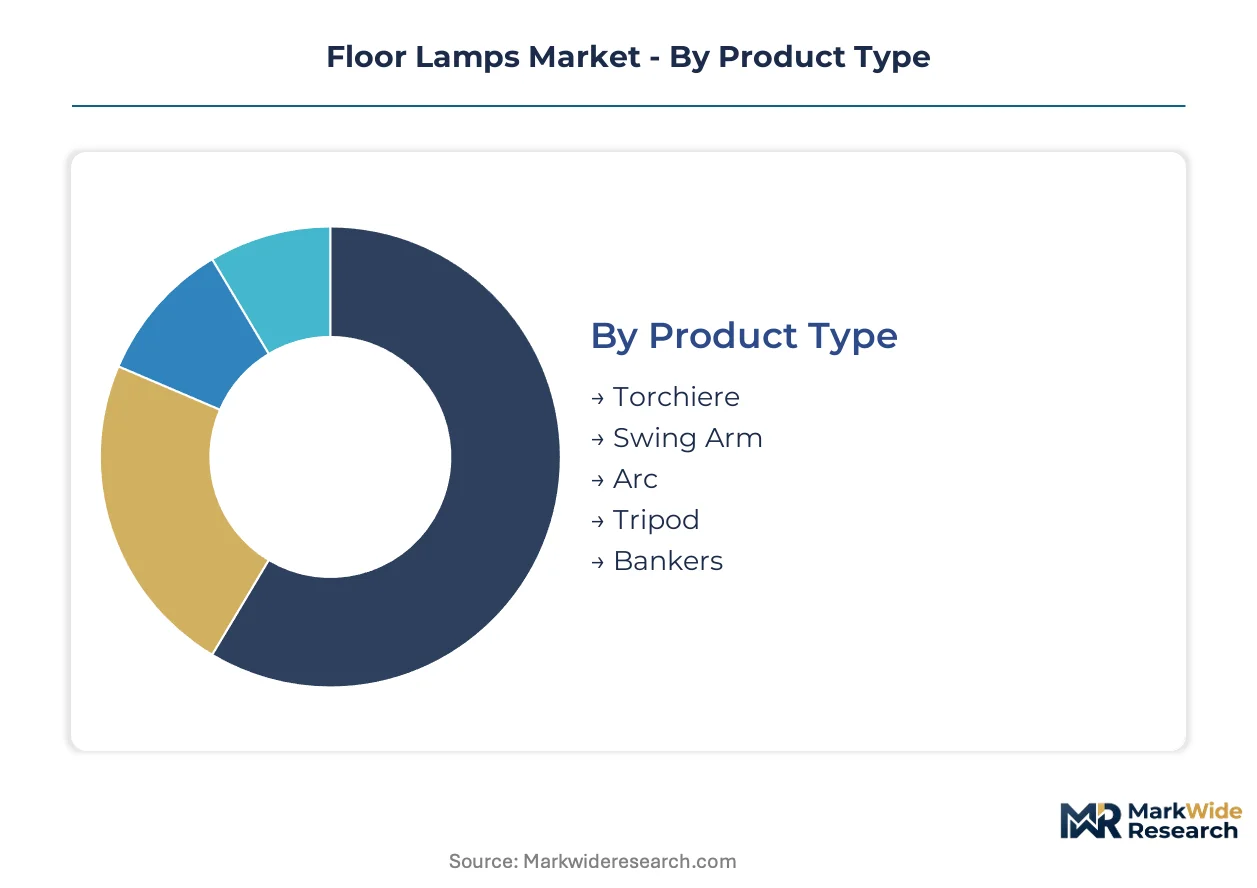
Segmentation in floor lamps reveals how fixture specifications diverge across regulatory environments and end-use procurement standards. Understanding these divisions exposes where compliance investments concentrate and which material-light source combinations unlock premium positioning.
Product Type:
Domestic production clusters in Italy and Poland favor torchiere and arc designs for EU renovation demand, while export-oriented assembly in Portugal targets swing arm and tripod configurations for North American contract furniture channels.
- Torchiere:Uplighting fixtures with upward-facing bowls or shades directing illumination toward ceilings for ambient distribution. German and French urban renovation clusters specify these for compact apartments where perimeter lighting proves impractical. EU Ecodesign Directive phase-out schedules accelerate LED retrofit demand in this category.
- Arc:Cantilevered arms extending light sources beyond weighted bases, enabling sofa-side positioning without floor-space intrusion. Paris and Berlin interior designers specify reduced-form-factor versions enabled by chip-on-board LED miniaturization. REACH compliance on brushed brass finishes concentrates sourcing among Northern Italian suppliers.
- Swing Arm:Adjustable horizontal extensions for task-oriented illumination in reading and craft applications.
- Tripod:Three-legged base structures offering stability with minimal material weight, popular in Nordic mass-market retail.
- Bankers:Traditional shaded designs with pull-chain switching, retaining niche demand in heritage interior specifications.
Torchiere holds the largest share; momentum sits with arc configurations as space-efficient urban living intensifies.
Material:
Cost tiers stratify sharply between hand-finished metal-glass combinations commanding hospitality premiums and flat-pack plastic-wood assemblies dominating German and Nordic retail corridors.
- Metal:Brushed brass, powder-coated steel, and aluminum extrusions forming structural bases and decorative housings. Polish and Italian plating bath reformulation investments respond to REACH heavy metal restrictions. CE marking under the Low Voltage Directive governs electrical safety for all conductive housings.
- Glass:Hand-blown opal diffusers and borosilicate shades signaling design authenticity in premium residential channels. Northern Italian and Portuguese craft zones concentrate artisan expertise, constraining scalable output. Hospitality specification channels audit certificates of compliance before contract award.
- Wood:Solid and veneered timber bases serving sustainability-positioned mass-market lines, particularly in Nordic retail.
- Plastic:Injection-molded ABS and polycarbonate components enabling flat-pack logistics and circular material sourcing under EU Green Deal requirements.
- Fabric:Linen, cotton, and synthetic shade textiles diffusing point sources into ambient distributions.
Metal commands the revenue concentration; glass climbs the fastest as hand-finished authenticity premiums expand.
Light Source:
Application requirements split between residential retrofit demand pulling LED adoption and educational procurement maintaining fluorescent specifications during budget cycles.
- LED:Solid-state modules delivering 800-3,000 lumens at efficacy levels above 150 lumens per watt. EU Ecodesign Directive mandates render halogen and CFL alternatives commercially untenable across hospitality and educational end-user applications. Driver component volatility from East Asian semiconductor supply creates lead time uncertainty for fixture assemblers.
- Incandescent:Tungsten filament sources phased out under EU Ecodesign schedules, retaining only heritage restoration niches requiring historical accuracy.
- Fluorescent:Linear and compact tube configurations persisting in educational institute procurement during extended replacement cycles.
- Halogen:Directional reflector lamps facing parallel phase-out pressures under ecodesign efficiency minimums.
- CFL:Mercury-bearing spiral tubes restricted under RoHS and REACH chemical compliance frameworks.
LED holds the largest share; incandescent and halogen face steepest contraction trajectories under regulatory phase-out.
End User:
Customer type determines specification intensity, with hospitality and educational institutes enforcing compliance auditing that residential channels often bypass.
- Residential:Individual consumers and interior designers procuring through retail and direct-to-consumer channels. German and French urban renovation clusters concentrate demand for space-efficient arc and task-oriented configurations. Smart home integration protocols penetrate this segment most rapidly.
- Hospitality:Hotels, restaurants, and event venues requiring durable finishes and standardized replacement protocols. This segment enforces REACH chemical compliance auditing most rigorously, concentrating contract awards among certified Polish and Italian suppliers.
- Commercial Offices:Corporate workspace procurement favoring integrated architectural lighting, displacing portable ambient fixtures in new-build construction.
- Educational Institutes:Schools and universities maintaining extended replacement cycles that slow LED migration in budget-constrained jurisdictions.
- Libraries:Specialized reading room applications requiring color rendering indices above 90 for visual comfort during extended use.
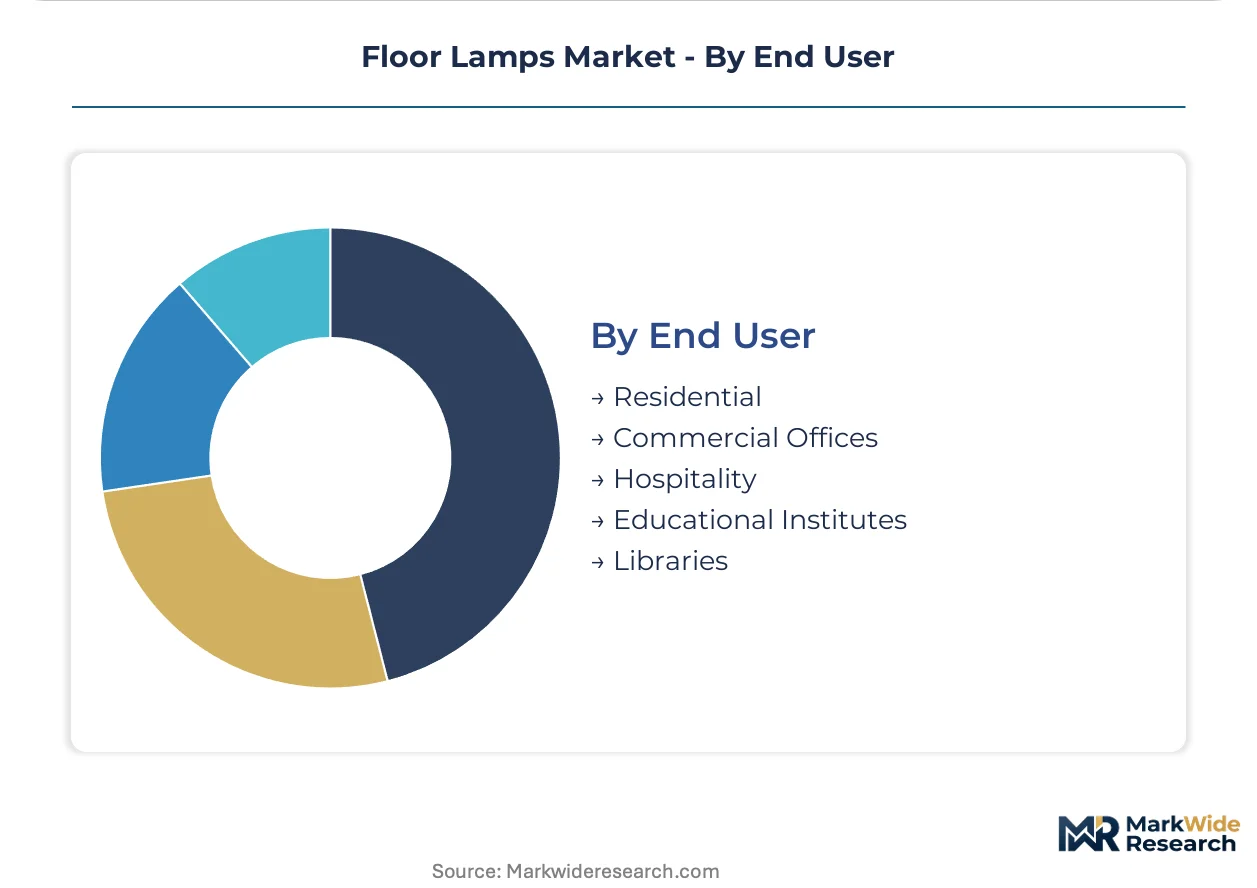
Residential holds the largest share; hospitality gains share fastest as compliance-certified suppliers capture specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH enforcement by ECHA anchors European demand transformation, compressing fixture design cycles and accelerating LED migration across residential and hospitality channels.
Germany
Berlin and Munich renovation clusters specify space-efficient arc and torchiere configurations for compact urban apartments. The EU Ecodesign Directive's halogen phase-out accelerates LED retrofit demand in residential channels. Bavarian plating suppliers invest in REACH-compliant bath reformulation to maintain hospitality contract eligibility.
France
Paris interior designers drive reduced-form-factor arc lamp specifications enabled by chip-on-board LED miniaturization. ANSM and CNIL oversight extends to voice-activated smart lighting cybersecurity requirements. Lyon and Marseille manufacturing basins concentrate hand-blown opal glass expertise for premium residential finishes.
Italy
Milan and Turin craft zones anchor brushed brass finishing and artisan glass production for hospitality specification channels. REACH chemical compliance enforcement tightens heavy metal restrictions in Northern Italian plating operations. Domestic suppliers capture premium positioning through certified material sourcing.
Poland
Warsaw and Krakow assembly operations serve EU mass-market demand with reformulated plating baths meeting REACH heavy metal thresholds. The EU Green Deal's circularity requirements drive recycled aluminum logistics investments. Polish manufacturers gain first-mover advantages in compliant metal finishing for export markets.
Netherlands
Amsterdam R&D concentration supports LED driver integration and connected lighting platform development. Dutch urban consumers prioritize customization over immediate availability, fragmenting traditional retail concentration. Rotterdam logistics hubs facilitate direct-to-consumer channel expansion for digitally native brands.
Floor Lamps Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier combines electronics integration with lighting design heritage, while specialists concentrate on material craftsmanship and regional distribution. Three archetypes dominate: diversified electronics conglomerates with lighting divisions, artisan heritage brands with craft positioning, and flat-pack mass-market distributors with circular logistics mastery. Competitive moves center on smart home protocol partnerships and circular material certification.
Among diversified electronics conglomerates, Koninklijke Philips N.V. and Signify occupy positions bridging semiconductor integration with fixture specification. IKEA exemplifies the mass-market archetype through flat-pack logistics and circular sourcing. Artisan heritage representation includes Louis Poulsen and Flos, anchoring premium positioning through craft-based authenticity.
| Leading Market Players |
|---|
| IKEA |
| Koninklijke Philips N.V |
| Signify |
| Artemide |
| Flos |
| Louis Poulsen |
| GUANYA |
| YLlighting |
| AOZZO |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements with Northern Italian plating suppliers lock in REACH-compliant brushed brass access and price visibility for hospitality-grade arc and torchiere fixtures. These contracts insulate premium manufacturers from spot-market volatility in hand-blown opal glass while cementing margin pools unavailable to mass-market competitors dependent on Asian injection-molded components.
Pricing Analysis
Polish and Italian metal-finishing clusters command 40-60% premiums over Portuguese and Chinese alternatives due to REACH certification and CE marking compliance. Three-tier pricing structure across premium, standard, and economy levels separates hand-finished brass-and-glass hospitality specifications from flat-pack Nordic retail and Asian import tiers. Cost compression in economy segments intensifies as direct-to-consumer digitally native brands bypass traditional retail markups. Educational institutes exhibit highest price sensitivity due to extended replacement cycles, while hospitality procurement prioritizes certified compliance over unit cost.
Supply Chain Analysis
Poland and Italy anchor metal finishing and artisan glass production for EU-compliant hospitality channels, while Portugal and Vietnam concentrate export-oriented assembly for North American contract furniture. LED driver electronics draw from East Asian semiconductor foundries, creating single-source vulnerability for fixture assemblers. Distribution runs through Rotterdam logistics hubs for digitally native brands and traditional Nordic retail corridors for flat-pack mass-market players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. REACH compliance certification creates switching costs that lock hospitality specifiers into validated supplier networks, insulating incumbents from price-based displacement.
For Market Incumbents: Shield premium positioning by deepening backward integration into Northern Italian hand-blown glass craft zones and Polish REACH-compliant plating operations. Accelerate Interact-connected and voice-activated smart home certification ahead of EU AI Act enforcement to raise compliance barriers for Asian competitors lacking cybersecurity testing capabilities.
For New Entrants and Emerging Players: Lead with circular material sourcing credentials targeting Netherlands and Denmark urban consumer segments prioritizing customization and sustainability over immediate availability. Exploit direct-to-consumer channel expansion to disintermediate traditional Nordic retail concentration, leveraging Rotterdam logistics infrastructure for shortened fulfillment windows.
For Investors and Strategic Acquirers: Specialist LED driver integrators with hospitality certification track records offer asymmetric exposure to solid-state lighting migration and smart home protocol consolidation. Monitor ECHA enforcement intensity as the inflection signal for compliance-premium expansion or contraction in metal-finishing margin pools.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification Investment | ECHA enforcement locks hospitality specifiers into validated supplier networks, creating pricing power. |
| Smart Home Protocol Integration | EU AI Act voice-activation mandates favor early movers with cybersecurity testing capabilities. |
| Circular Material Sourcing Program | EU Green Deal requirements create margin pools for recycled aluminum and reclaimed glass logistics mastery. |
| Direct-to-Consumer Channel Buildout | Rotterdam logistics hubs enable digitally native brands to bypass traditional Nordic retail concentration. |
| Artisan Craft Zone Acquisition | Northern Italian hand-blown opal glass expertise constrains scalable premium output, creating scarcity value. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU customs trade data, ECHA compliance registries, and hospitality procurement database records. Primary interviews engaged lighting design directors, hospitality specification consultants, plating bath operations managers, and LED driver procurement leads. Secondary validation drew from SEC filings of listed lighting conglomerates, EU Ecodesign Directive implementation reports, and REACH enforcement bulletins. Bottom-up fixture shipment analysis triangulates against top-down residential renovation spending estimates across German and French urban clusters.
Segmentation dimensions modeled include product type, material composition, light source technology, and end-user procurement channel across the projection horizon. CAGRs derive from regression analysis of historical LED adoption curves, regulatory phase-out schedules, and smart home penetration rates in Western European renovation markets. Industry-specific forecast inputs incorporate chip-on-board LED miniaturization trajectories and Ecodesign Directive amendment timelines.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity, stable East Asian semiconductor supply, or continued EU Green Deal circularity funding would require recalibration. Forecasts reflect assumptions regarding regulatory implementation pacing and residential renovation cycle durability. Recalibration cycles align with material shifts in ECHA enforcement patterns and smart home protocol standardization outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Landscape Lighting Market