
 Decorative Lighting Market | 2026-2036
Decorative Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Lighting Market Intelligence
The growing influence of the hospitality sector over traditional residential applications is recalibrating product development priorities and channel strategies. Signify leverages its extensive portfolio in connected LED systems to capture high-value commercial projects. Hubbell differentiates through its specialized solutions tailored for architects and designers in the commercial space. General Electric sustains its market presence through a broad distribution network covering both residential and business segments, addressing a diverse consumer base.
Decorative lighting comprises fixtures where aesthetic form is a primary design function, complementing architectural and interior design elements. Key performance metrics include a high Color Rendering Index (CRI) above 90 and specific color temperatures to create desired moods. The transition to LED technology is nearly complete, rendering older incandescent and halogen options niche. While chandeliers maintain a strong position in high-end residential applications, pendant lights and wall sconces are specified heavily by designers for commercial projects.
Energy efficiency mandates, including the EU's RoHS directive and the US EPA's ENERGY STAR program, shape product design and material selection. In parallel, China's GB standards for lighting products govern market access and performance criteria for one of the largest consumer markets. Navigating these varied international standards is critical for market participants. The central strategic choice for vendors involves balancing investments in smart, connected features against material and design innovation.
Market Dynamics
The market's primary structural force is the demand pull from the global hospitality and high-end commercial real estate sectors. This shift away from a residential-led model is fundamentally altering product design, material choices, and go-to-market strategies for manufacturers.
Growth Catalysts
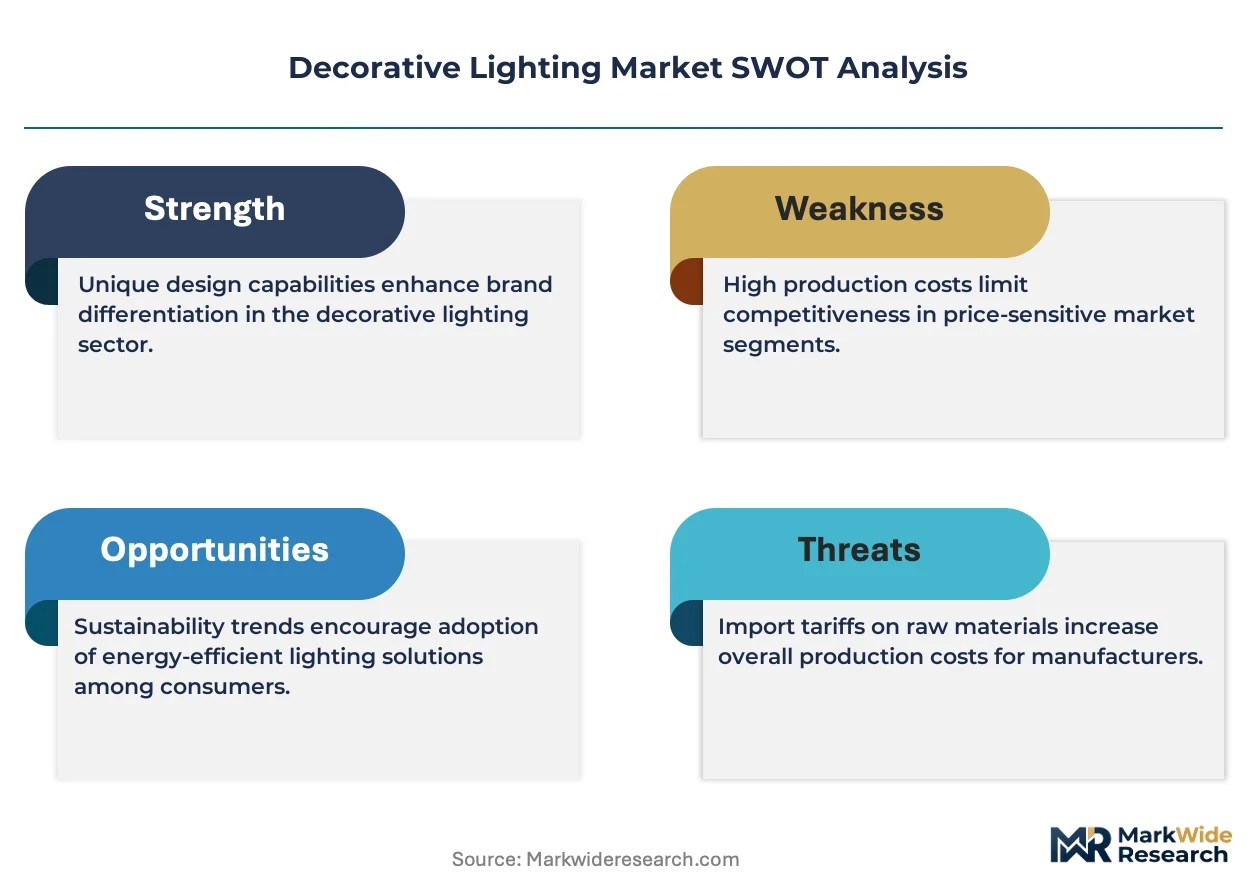
- Energy Efficiency Mandates:Regulations including the EU's RoHS directive and the US EPA's ENERGY STAR program accelerate the replacement of legacy lighting with energy-efficient LED fixtures, creating a consistent renovation-driven demand stream.
- Hospitality Sector Expansion:A global boom in hotel construction and refurbishment, particularly in metropolitan hubs like Dubai and Shanghai, directly stimulates demand for high-value, aesthetically driven lighting specified by interior designers.
- High-CRI LED Availability:The widespread accessibility of LED components with a Color Rendering Index (CRI) above 90 allows manufacturers to meet stringent designer specifications for color accuracy, unlocking applications in retail and galleries.
Market Restraints
- Input Material Volatility:Fluctuations in the cost of rare earth elements, critical for the phosphors used in high-quality LEDs, create margin pressure and unpredictable production costs for manufacturers of premium fixtures.
- Integrated Lighting Substitution:The trend towards minimalist architecture increasingly favors integrated, linear lighting solutions built directly into ceilings and walls, which can displace the need for separate decorative fixtures in some commercial projects.
- Interoperability Hurdles:A lack of standardization among smart lighting control protocols creates complexity for installers and end-users, acting as a deterrent to adoption in projects requiring integration with diverse building automation systems.
Strategic Opportunities
- Multifunctional Fixtures:Integrating acoustic-dampening materials into large-format pendant lights presents an opportunity to serve open-plan offices and restaurants seeking solutions that combine ambient lighting with noise reduction.
- Human-Centric Lighting:Developing decorative fixtures with tunable-white technology allows vendors to penetrate the wellness market, including premium corporate offices, healthcare facilities, and educational institutions seeking to improve occupant well-being.
- Secondary City Expansion:Targeting emerging luxury residential and commercial developments in fast-growing secondary cities within developing economies offers a new frontier for growth beyond saturated primary metropolitan markets.
Industry Challenges
- Fragmented Global Standards:Manufacturers face significant compliance costs and logistical hurdles in navigating disparate regulatory frameworks, such as China's GB standards, North America's UL listings, and Europe's CE marking requirements.
- Design IP Infringement:The prevalence of counterfeit and imitation fixtures, particularly for iconic and high-margin designs, erodes brand equity and forces significant investment in legal protection and anti-counterfeiting measures.
- Artisanal Skill Shortages:A diminishing pool of skilled artisans proficient in traditional techniques like glassblowing, metalworking, and finishing creates production bottlenecks for high-end, bespoke lighting manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Lighting Market |
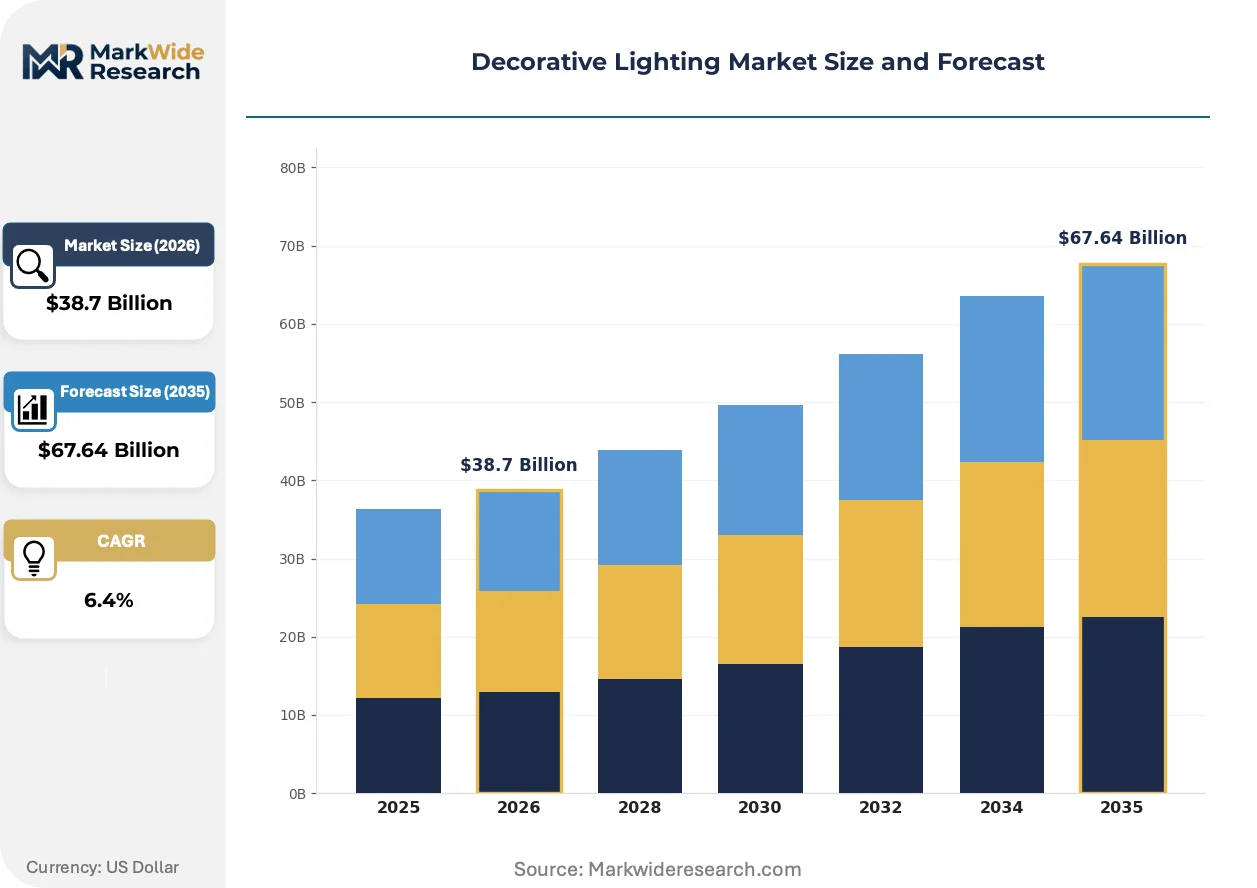
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pendant Lights, Chandeliers, Wall Sconces, String Lights Application: Residential, Commercial, Outdoor, Hospitality Consumer Type: Homeowners, Businesses, Contractors, Designers Technology: LED, Incandescent, Fluorescent, Halogen |
| Companies Covered | Acuity Brands, Signify, General Electric, Osram, Philips, Hubbell, Fagerhult, Bridgelux, Ideal Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Lighting Market Strategic Shifts & Innovations
The market is defined by the fusion of aesthetic design with intelligent, connected functionality. This integration moves decorative fixtures from static objects to dynamic components of a responsive architectural environment, driven by sustainability and user experience demands.
Smart lighting control is a central product evolution. These systems provide tunable white, dim-to-warm, and full color (RGBW) capabilities embedded directly within the fixture. Commercial end-users, especially in hospitality and corporate offices, are the primary adopters. This technology is converging with building management systems and IoT platforms, enabling fixtures to respond to occupancy, daylight levels, and pre-programmed scenes automatically.
Europe's Corporate Sustainability Reporting Directive (CSRD) is a significant regulatory driver. The directive compels manufacturers to disclose detailed information on material sourcing, energy consumption in production, and end-of-life recyclability. High-end commercial segments in the EU are most affected, as architects and corporate clients now prioritize fixtures with transparent, verifiable sustainability credentials to meet their own reporting obligations.
A fundamental shift in buying behavior sees architects and interior designers taking control of specification. This trend disrupts the traditional distributor-led sales model, favoring direct engagement with manufacturers or specification-focused showrooms. This designer-led procurement is most visible within the luxury residential and boutique commercial sectors in global design capitals like London and New York, where aesthetic curation is paramount.
Decorative Lighting Market Segmentation
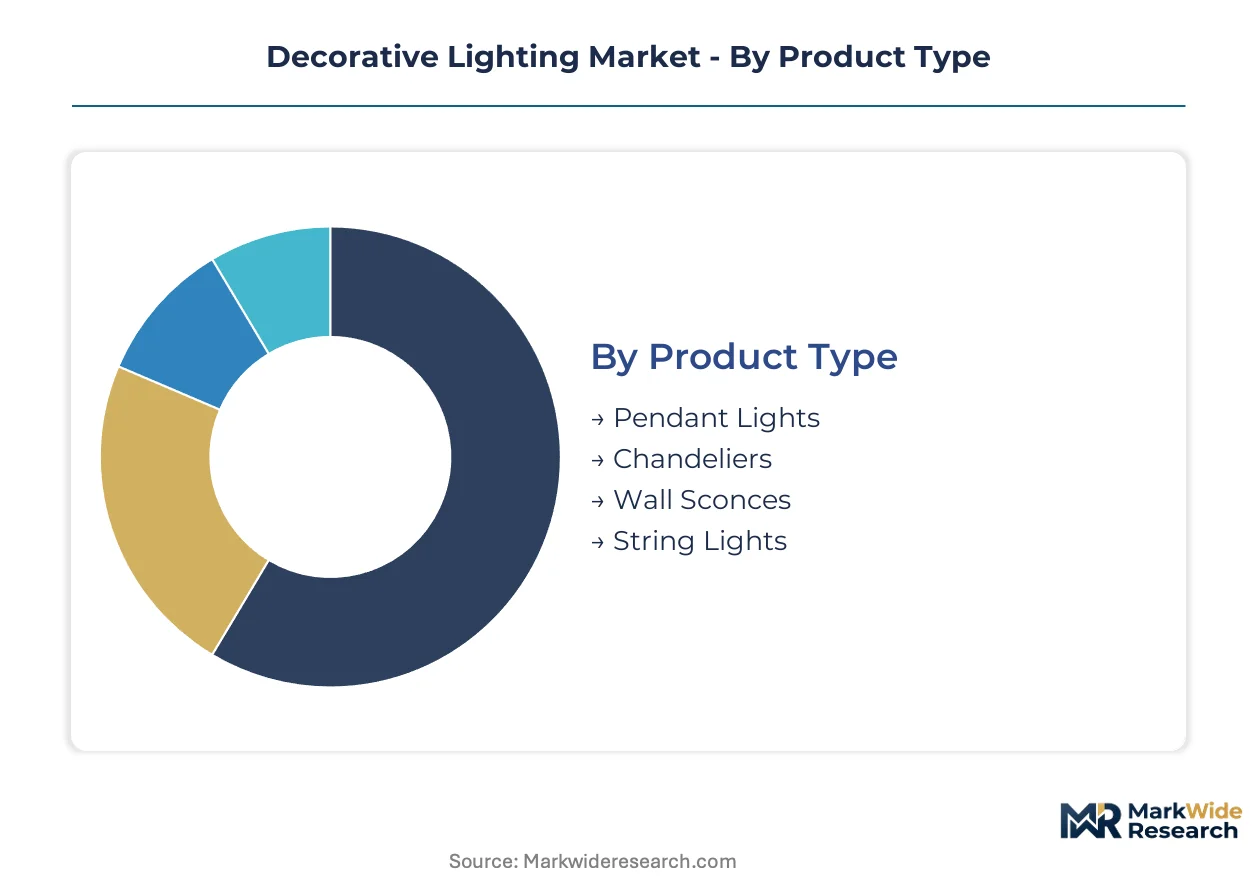
Understanding the Decorative Lighting Market through segmentation reveals distinct demand patterns and regulatory influences. Manufacturers must align product development and distribution channels with the specific needs of each segment. This granular view highlights where value creation and competitive differentiation are most pronounced.
Product Type:
Compliance with various safety and performance standards dictates the market access for different decorative lighting product types.
- Pendant Lights:These fixtures suspend from the ceiling, often featuring a single light source or multiple elements, requiring UL listing in North America and CE marking in Europe for commercial use. Demand is concentrating in high-end hospitality projects and corporate offices, driven by designers seeking versatile aesthetic elements.
- Chandeliers:Large, multi-arm fixtures typically featuring intricate designs, often requiring specialized fire safety certifications and material compliance for public spaces. High-end residential applications and luxury hotel lobbies globally drive demand, emphasizing artisanal craftsmanship and bespoke finishes.
- Wall Sconces:These fixtures mount directly to a wall, providing accent or ambient illumination, needing specific ingress protection (IP) ratings for certain environments.
- String Lights:Comprising multiple small lights on a single cable, these are primarily used for temporary or outdoor decorative purposes, subject to specific low-voltage safety standards.
Pendant Lights sits at the top of the volume ranking, with Wall Sconces climbing the fastest.
Application:
Customer engagement models and project scale significantly differentiate decorative lighting applications.
- Hospitality:This segment encompasses hotels, restaurants, and resorts, demanding bespoke and durable fixtures with specific color temperatures and high CRI values for guest experience. Global hotel construction booms, particularly in Dubai and Shanghai, directly stimulate demand.
- Commercial:Office buildings, retail spaces, and public venues constitute this segment, prioritizing energy-efficient, integrated solutions with smart control capabilities for operational savings. Demand is strong in metropolitan hubs undergoing urban redevelopment.
- Residential:Decorative lighting for private homes and apartments, focusing on aesthetic appeal, ease of installation, and increasingly, smart home integration features.
- Outdoor:Fixtures designed for exterior use, including landscapes, facades, and public areas, requiring robust weather resistance and specific IP ratings.
Hospitality applications command the highest average selling prices, while Outdoor installations are expanding most quickly.
Consumer Type:
The purchasing influence and specification power varies considerably across different decorative lighting consumer types.
- Designers:Interior designers and architects are key specifiers, influencing product selection for commercial and luxury residential projects, prioritizing aesthetics, performance, and brand reputation. Their procurement patterns often involve direct engagement with manufacturers.
- Businesses:Commercial enterprises, including hospitality groups and corporate clients, purchase decorative lighting for their premises, valuing energy efficiency, smart features, and project management support. Their decisions are often driven by long-term operational costs.
- Homeowners:Individual consumers purchasing decorative lighting for their residences, often influenced by retail trends, brand recognition, and ease of purchase.
- Contractors:Professionals responsible for installation and project execution, prioritizing ease of installation, product availability, and compliance with building codes.
Designers exert the greatest influence on high-value projects, with Businesses showing the steepest expansion trajectory.
Technology:
Technology maturity and regulatory pressures define the competitive landscape within decorative lighting solutions.
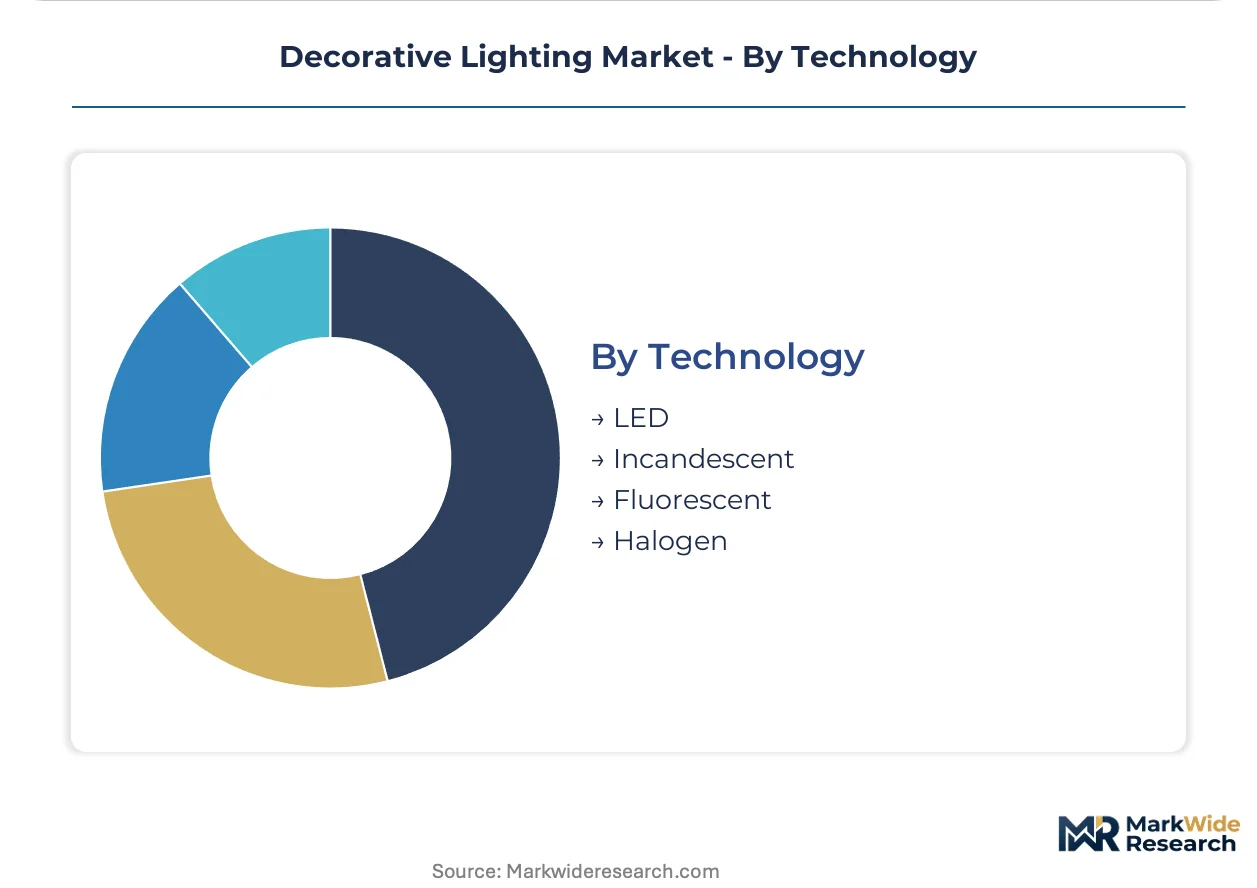
- LED:Light Emitting Diode technology dominates the market due to superior energy efficiency, long lifespan, and design flexibility, mandated by regulations like the EU's RoHS directive. This technology is nearly complete in its transition from legacy options.
- Incandescent:Traditional lighting technology, characterized by warm light output but low energy efficiency, now occupies niche or heritage applications and faces phasing out due to energy efficiency mandates. Its use is limited by environmental regulations in many regions.
- Fluorescent:Energy-efficient but less aesthetically versatile than LED, primarily found in utilitarian applications, gradually being replaced by LED alternatives.
- Halogen:An improved form of incandescent, offering brighter light but still less efficient than LED, facing similar regulatory pressures for phase-out.
LED technology captures the overwhelming majority of new installations, while Incandescent options maintain a niche presence in restoration projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives some decorative lighting production shifts, as manufacturers seek locations with less stringent environmental or labor cost regulations. This enables cost efficiencies for high-volume fixture components. However, demand for premium decorative lighting remains concentrated in specific, high-value global markets.
United States
Demand for high-CRI LED fixtures accelerates in hospitality and commercial real estate projects across major cities. The US EPA's ENERGY STAR program encourages energy-efficient lighting solutions for new constructions and renovations. Design hubs like New York and Los Angeles drive innovation in luxury residential and boutique commercial specifications.
Germany
European luxury residential and commercial developments fuel demand for sophisticated decorative lighting designs. Germany's strong adherence to the EU's RoHS directive ensures material compliance and sustainability in product development. The design cluster in Cologne focuses on integrating advanced smart lighting controls into architectural projects.
China
Rapid expansion of high-end hotels and luxury commercial spaces in metropolitan areas like Shanghai stimulates demand for bespoke decorative lighting. China's GB standards for lighting products govern market access and performance criteria for all imported and domestic fixtures. Production capabilities in Guangdong province support both mass-market and custom design manufacturing.
United Arab Emirates
Unprecedented growth in the hospitality sector, particularly in Dubai, creates substantial demand for unique, high-value decorative lighting installations. The UAE's focus on sustainable building practices influences material choices and energy efficiency requirements. Major developments in Abu Dhabi emphasize large-scale, custom architectural lighting solutions.
United Kingdom
Renovation projects in London's luxury residential and commercial sectors drive specifications for aesthetic and technologically advanced lighting. The UK's commitment to energy efficiency, aligned with former EU directives, accelerates the adoption of LED decorative fixtures. Design studios in London are pivotal in curating global trends for high-end interior spaces.
Decorative Lighting Market Key Industry Players
Strategic partnerships dominate the current landscape, allowing firms to combine design expertise with technological capabilities. The market structure exhibits a tiered approach, with premium design houses coexisting alongside large-scale industrial manufacturers. Three strategic archetypes include design-led specialists, technology-focused integrators, and broad-portfolio providers. Portfolio diversification into smart lighting systems and geographic expansion into emerging luxury markets represent key competitive moves.
Among established players, Signify represents a technology-focused integrator, leveraging its extensive portfolio in connected LED systems for high-value commercial projects. Its global presence allows it to capture significant market share in smart lighting solutions. Hubbell, Inc., exemplifies a design-led specialist, differentiating through specialized solutions tailored for architects and designers in the commercial space, particularly in North America. General Electric, a broad-portfolio provider, sustains its market presence through a wide distribution network covering both residential and business segments, addressing a diverse consumer base. These companies collectively anchor different segments of the decorative lighting value chain.
| Leading Market Players |
|---|
| Acuity Brands |
| Signify |
| General Electric |
| Osram |
| Philips |
| Hubbell |
| Fagerhult |
| Bridgelux |
| Ideal Industries |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps, specializing in bespoke decorative fixtures, often dictate premium pricing through controlled artisanal supply chains. This ownership structure influences both material procurement and distribution strategies.
Pricing Analysis
Distributor margins significantly influence the final cost of decorative lighting fixtures, particularly for commercial projects. Project-based pricing dominates high-end installations, while per-unit transactional models serve the mass market. Price differentiation stems from customization levels, brand premium, and certifications like UL or CE marking. Input material volatility, especially for rare earth elements, creates upward pricing pressure, with homeowners exhibiting higher price sensitivity than designers.
Supply Chain Analysis
Reverse logistics for decorative lighting primarily involves returns and limited refurbishment for high-value components, rather than widespread remanufacturing. Supply concentration centers in China for mass-market components, with Germany and Italy specializing in artisanal fixtures. The industry relies heavily on rare earth elements for phosphors, specialized glass, and various metal alloys, facing commodity price volatility as a key structural risk. Distribution runs through designer-led procurement, specialized showrooms, and broad retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Decorative Lighting Market is a late-cycle quality story, driven by a pronounced demand shift towards premium specifications in hospitality and luxury residential projects. This focus on aesthetic and performance excellence defines competitive strategies.
For Market Incumbents: Extend portfolio diversification into smart lighting systems to counter integrated lighting substitution, a significant threat in minimalist architectural designs. Geographic expansion into emerging luxury markets provides new growth avenues beyond saturated primary hubs. Invest in R&D for human-centric lighting features to meet rising wellness demands. Consolidate market share through strategic acquisitions of design-led specialists.
For New Entrants and Emerging Players: Architects and interior designers represent critical channel partners for new entrants seeking market penetration. Target emerging luxury residential and commercial developments in fast-growing secondary cities within developing economies. Focus on multifunctional fixtures, integrating acoustic dampening, to serve open-plan offices and restaurants. Direct engagement with architects in the boutique commercial segment offers a penetrable go-to-market angle.
For Investors and Strategic Acquirers: Technology-focused integrators are the most active acquirers in this space, seeking to enhance smart capabilities. The market demonstrates long-term viability, driven by sustained demand for aesthetic and functional integration in high-value projects. Target design-led specialists with strong intellectual property and established designer relationships. Monitor the adoption rates of standardized smart lighting control protocols for early signals of market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Smart Lighting Integration | Captures high-value commercial projects seeking advanced control capabilities. |
| Target Secondary City Developments | Unlocks new growth frontiers beyond saturated primary metropolitan markets. |
| Develop Multifunctional Fixtures | Addresses client needs for combined ambient lighting and acoustic solutions. |
| Invest in Tunable-White Technology | Penetrates the wellness market, improving occupant well-being in corporate settings. |
| Strengthen Designer Engagement | Secures specification control in luxury residential and boutique commercial sectors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary interviews engaged interior designers, architects, lighting manufacturers' product managers, and hospitality procurement managers. Secondary data sources included industry association reports, government energy efficiency databases like US EPA and EU RoHS, and company financial filings. This approach ensured bottom-up and top-down triangulation of market data.
Forecasts were anchored to historical reference periods, with growth rates projected across the analysis window based on established trends. The analytical framework modeled segmentation by product type, application, consumer type, technology, and regional market. Compound Annual Growth Rates (CAGRs) were derived from historical data and future projections. New construction starts in hospitality and LED component cost trends served as key forecast inputs.
Revisions become necessary when significant regulatory shifts or material supply disruptions materialize, impacting market dynamics. Forecasts reflect assumptions regarding economic stability and technological progression. Practitioners should monitor global construction trends and energy efficiency mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Kids Desk Lamp Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Table and Floor Lamps Market