
 Table and Floor Lamps Market | 2026-2036
Table and Floor Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Table and Floor Lamps Market Insights
Buyer concentration across the hospitality sector is restructuring procurement dynamics for decorative lighting. Signify leverages its vertical integration into LED module production to secure long-term contracts with hotel chains. IKEA Group competes through flat-pack logistics and private-label bulb bundling that lowers total installed cost. Acuity Brands anchors its position in commercial specification channels where architects control fixture selection.
Table and floor lamps are portable luminaires typically housing E26/E27 or GU10 bases with shade assemblies in glass, fabric, or metal, designed to deliver task or ambient illumination at adjustable heights for residential and commercial interiors. Floor lamps occupy the largest volume share among product types due to their prevalence in open-plan living and co-working layouts where ceiling modifications are restricted. Metal and glass material segments command premium positioning in modern and contemporary style categories, while wood and fabric combinations dominate residential reading lamp specifications where warmth and diffused output matter.
EPA Energy Star certification and EU Ecodesign Directive requirements shape minimum efficacy standards and standby power limits for lamp assemblies sold in their respective jurisdictions. CE marking under the EU Low Voltage Directive governs electrical safety for fixtures entering European distribution channels. Stakeholders must monitor evolving state-level building energy codes in California and New York that increasingly embed lighting power density limits affecting portable fixture specification in commercial fit-outs.
Market Dynamics
LED efficacy mandates across the European Union are compressing fixture refresh cycles for hospitality operators, while German boutique hotel construction and heritage retrofits sustain premium artisan procurement against a backdrop of tightening supply chains for specialized shade materials.
Growth Catalysts
- Ecodesign Directive efficacy thresholds:EU regulations mandating minimum lumens-per-watt ratios force commercial buyers toward LED-integrated portable fixtures, accelerating replacement demand across German and French hospitality fit-outs.
- Heritage building electrification:Strict preservation codes in Italian and Spanish historic districts prohibit ceiling modifications, channeling illumination investment into adjustable-height floor lamps with period-appropriate aesthetics.
- Co-working space proliferation:Open-plan layouts in Netherlands and Denmark commercial developments restrict hardwired installations, elevating portable task lighting to primary illumination strategy.
Market Restraints
- Artisan glass supply concentration:Mouth-blown shade production clusters in Murano and Bohemia regions, creating vulnerability to energy cost spikes and skilled craftsperson shortages.
- Raw material volatility:Brass and copper rod pricing fluctuates with Chilean and Peruvian mining output, compressing margin buffers for metal-dominant fixture portfolios.
- Technical retrofit limitations:Legacy E26 socket infrastructure in North American residential stock constrains rapid adoption of proprietary smart-base systems requiring complete fixture replacement.
Strategic Opportunities
- Polish and Romanian hospitality expansion:Underpenetrated luxury hotel development in Warsaw and Bucharest creates first-mover positioning for specification-grade portable lighting with EU certification bundling.
- Repairability mandate alignment:French AGEC law requirements for spare parts availability and disassembly documentation favor modular fixture architectures with standardized component interfaces.
- Biophilic design convergence:Integration of circadian-tunable LED drivers with natural material housings addresses wellness-focused commercial interiors in Scandinavian markets.
Industry Challenges
- Certification timeline compression:CE marking under Low Voltage Directive plus emerging national building codes in California and New York require parallel testing tracks, extending product launch windows.
- Supply chain reconfiguration friction:Relocation of metal fabrication from Asian sources to Turkish and North African suppliers demands qualification of new anodizing and finishing capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Table and Floor Lamps Market |
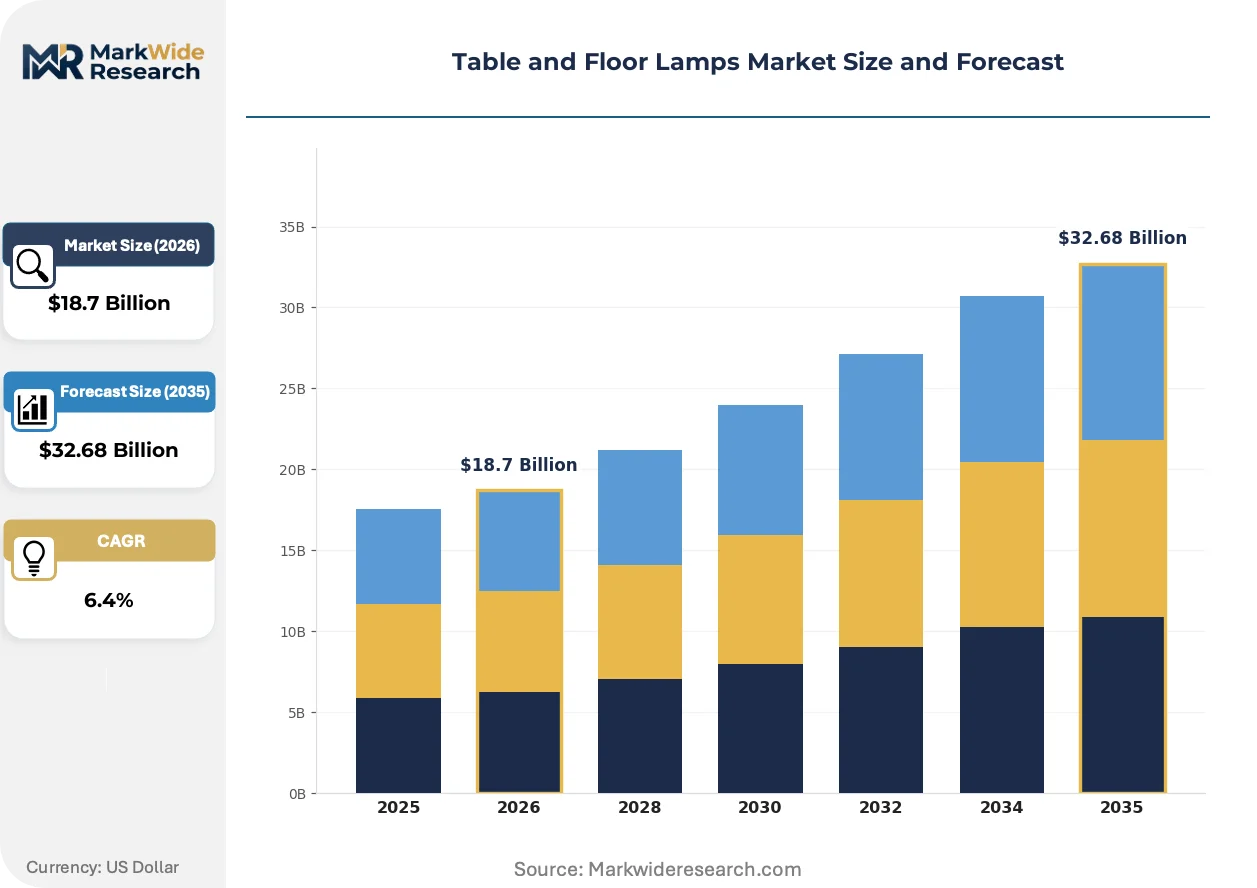
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table Lamps, Floor Lamps, Accent Lamps, Reading Lamps Material: Wood, Metal, Glass, Fabric Style: Modern, Traditional, Industrial, Contemporary End User: Residential, Commercial, Hospitality, Educational |
| Companies Covered | Signify, IKEA Group, Acuity Brands, Artemide, FLOS, Philips, OSRAM, Wayfair, Kichler Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Table and Floor Lamps Market Trends and Innovations
Portable luminaire architecture is fragmenting into interchangeable sub-assemblies as sustainability mandates and customization demands collide, compressing traditional integrated fixture economics while opening modular service models.
Magnetic shade attachment systems with standardized base interfaces are modularizing fixture configuration. Hospitality procurement teams in Berlin and Vienna are piloting seasonal shade swap programs rather than complete fixture replacement. This architecture compresses inventory carrying costs while enabling rapid aesthetic refresh without electrical contractor involvement.
EPA Energy Star certification expansion into portable fixture categories is tightening standby power limits for smart-enabled lamps. California Title 24 building standards now embed lighting power density calculations affecting commercial portable specification. German hotel operators are prioritizing dual-certified products satisfying both EU Ecodesign and US Energy Star to streamline transatlantic property standardization.
Direct-to-designer platforms are disintermediating traditional wholesale distribution for specification-grade portable lighting. Scandinavian interior design studios are sourcing custom metal-and-fabric combinations through digital configurators that bypass regional distributor markups. This channel compression is most pronounced in Copenhagen and Stockholm, where architect-led procurement controls fixture selection for boutique commercial projects.
Table and Floor Lamps Market Segmentation
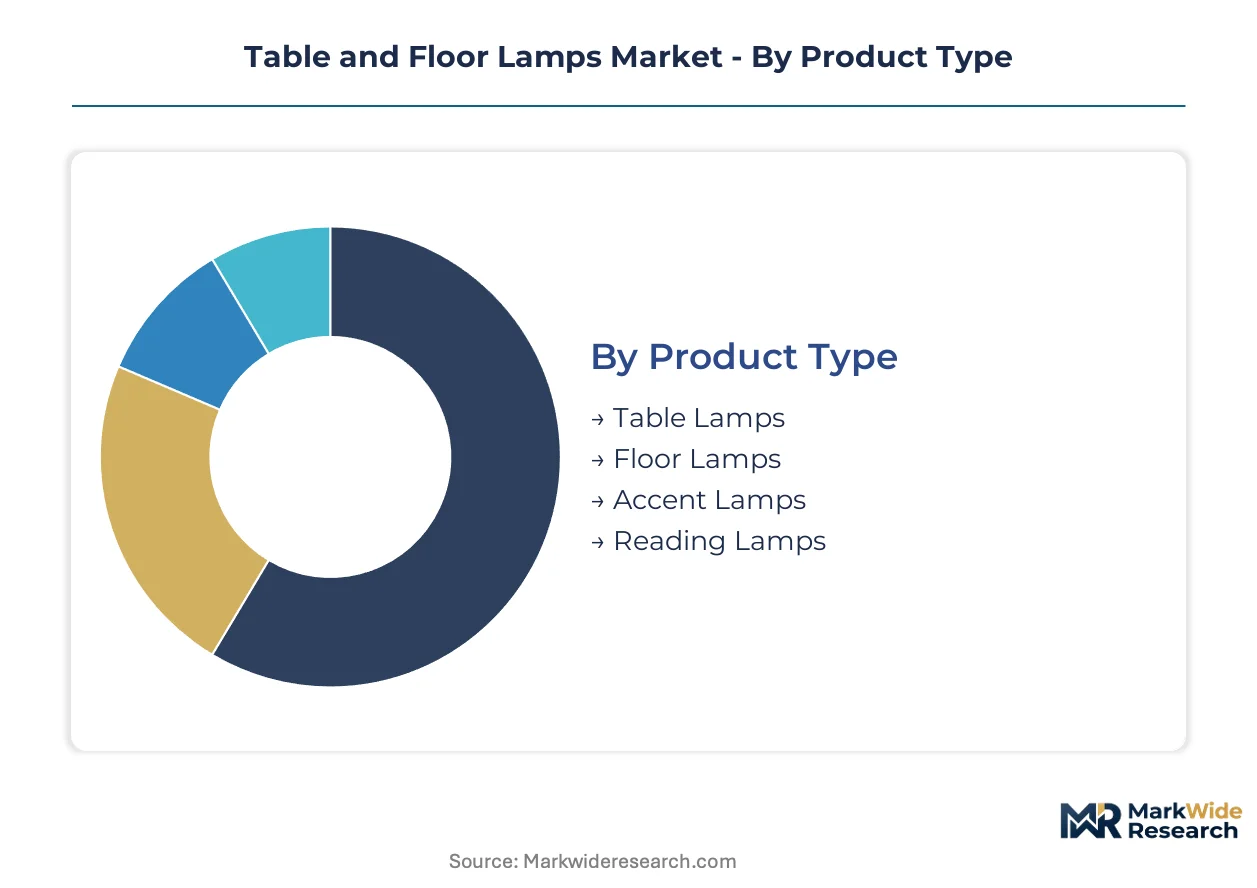
Segmentation in the portable lighting sector reveals how specification requirements diverge across installation constraints, material sourcing economics, and end-use certification burdens. Buyers prioritize different performance axes—scale, aesthetics, or regulatory compliance—depending on whether the fixture serves residential reading nooks, heritage hotel lobbies, or open-plan co-working floors.
Product Type:
Scale and installation flexibility separate the four product categories, with ceiling modification restrictions in commercial and heritage settings driving specification toward height-adjustable solutions.
- Floor Lamps:Vertical luminaires standing 150-180cm with weighted bases and adjustable heads or arms, designed for ambient or task illumination without electrical infrastructure changes. Demand concentrates in German boutique hotels and Dutch co-working developments where heritage codes and lease restrictions prohibit hardwired ceiling work, with LED efficacy mandates accelerating refresh cycles for outdated halogen units.
- Table Lamps:Compact portable fixtures typically 30-60cm in height with E26/E27 or GU10 bases, optimized for bedside, desk, or console table placement. Residential specifications in Italy and Spain favor these for reading applications, though smart-base incompatibility with legacy North American socket infrastructure constrains rapid upgrade adoption.
- Accent Lamps:Decorative luminaires under 40cm emphasizing aesthetic contribution over primary illumination, often featuring artisan glass or ceramic housings. Murano and Bohemia mouth-blown shade production clusters create supply vulnerability to energy cost spikes.
- Reading Lamps:Task-optimized designs with focused beam control, adjustable arms, and minimal glare for sustained visual work. Wood and fabric combinations dominate Scandinavian residential procurement where warmth and diffused output matter.
Floor Lamps leads on scale; Reading Lamps leads on momentum.
Material:
Raw material sourcing geography and finishing capability qualification directly shape margin structures and supply chain reconfiguration options.
- Metal:Brass, copper, steel, and aluminum housings with anodized, brushed, or powder-coated finishes, commanding premium positioning in modern and industrial style categories. Brass and copper rod pricing fluctuates with Chilean and Peruvian mining output, compressing margin buffers for metal-dominant portfolios.
- Glass:Mouth-blown, pressed, or borosilicate shade assemblies requiring specialized craftsperson labor, concentrated in Italian Murano and Czech Bohemia regions. Heritage hotel operators in Vienna and Berlin specify these for period-appropriate aesthetics despite supply concentration risks.
- Wood:Solid timber or veneer housings emphasizing warmth and biophilic design alignment, prevalent in Scandinavian residential and wellness-focused commercial interiors.
- Fabric:Linen, silk, or synthetic shade materials delivering diffused ambient output, standard in residential reading lamp specifications.
Metal commands the largest volume position; Glass faces the steepest supply constraints.
Style:
Architect and interior designer control over fixture selection creates channel dynamics where aesthetic positioning determines distribution pathway and margin capture.
- Modern:Clean lines, minimal ornamentation, and integrated LED modules with metal and glass material dominance. Copenhagen and Stockholm architect-led procurement channels favor these for boutique commercial projects.
- Contemporary:Current design period interpretations blending material experimentation with technological integration, including circadian-tunable LED drivers. French AGEC law repairability requirements favor modular architectures in this segment.
- Traditional:Period-referenced forms with ornate metalwork and fabric shades, specified for Italian and Spanish heritage building electrification where strict preservation codes apply.
- Industrial:Exposed hardware, raw metal finishes, and utilitarian aesthetics, prevalent in converted warehouse co-working spaces in Netherlands and Denmark.
Modern leads specification frequency; Contemporary gains share fastest.
End User:
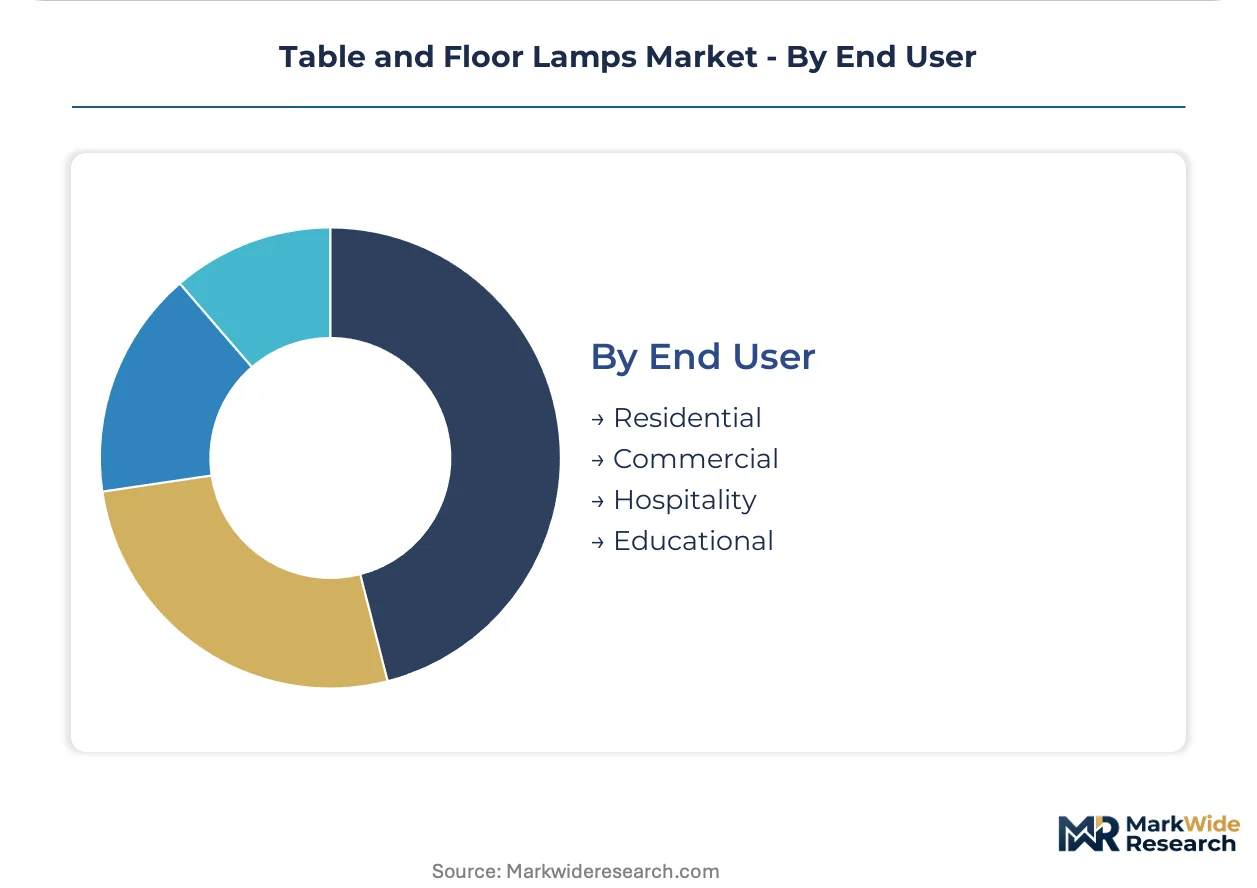
Procurement authority structures and regulatory exposure vary sharply across residential, commercial, institutional, and hospitality buyers.
- Hospitality:Hotel chains and boutique operators with centralized procurement teams, subject to EU Ecodesign Directive efficacy thresholds and dual-certification preferences for transatlantic property standardization. German construction and heritage retrofits sustain premium artisan procurement despite tightening supply chains.
- Residential:Individual consumers and renovation contractors, constrained by legacy E26 socket infrastructure in North America and influenced by flat-pack logistics and private-label bulb bundling economics.
- Commercial:Office developers and co-working operators prioritizing open-plan flexibility, with California Title 24 and New York building codes embedding lighting power density calculations affecting portable specification.
- Educational:Schools and universities with extended procurement cycles and public-sector bidding requirements, lagging hospitality and commercial segments in LED refresh adoption.
Hospitality leads on specification value; Commercial expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium artisan procurement while the United States contends with legacy socket infrastructure that slows LED-integrated adoption. France imposes repairability mandates that favor modular fixture architectures. Italy and Spain channel investment into portable lighting for heritage districts where preservation codes restrict ceiling modifications.
Germany
Boutique hotel construction in Berlin and Munich drives specification-grade floor lamp demand, while heritage building retrofits across Bavaria sustain Murano glass procurement despite supply chain tightening. The EU Ecodesign Directive mandates minimum lumens-per-watt ratios that accelerate replacement of halogen units in commercial fit-outs. The Ruhr industrial region hosts metal fabrication clusters reconfiguring supply chains toward Turkish and North African finishing capabilities.
United States
Residential renovation contractors face technical retrofit limitations as legacy E26 socket infrastructure constrains proprietary smart-base adoption. California Title 24 building standards embed lighting power density calculations affecting commercial portable specification in Los Angeles and San Francisco developments. The Pacific Northwest co-working corridor elevates portable task lighting as primary illumination strategy where lease restrictions prohibit hardwired installations.
France
Parisian hospitality operators pilot seasonal shade swap programs enabled by magnetic attachment systems that compress inventory carrying costs. The AGEC law mandates spare parts availability and disassembly documentation that favors modular fixture architectures with standardized component interfaces. Lyon and Marseille design studios leverage direct-to-designer platforms that disintermediate traditional wholesale distribution for specification-grade portable lighting.
Italy
Strict preservation codes in Rome and Florence historic districts prohibit ceiling modifications, channeling illumination investment into adjustable-height floor lamps with period-appropriate aesthetics. CE marking under the EU Low Voltage Directive governs electrical safety for fixtures entering European distribution channels. The Murano glass production cluster faces vulnerability to energy cost spikes and skilled craftsperson shortages that concentrate artisan shade supply.
Spain
Barcelona and Madrid heritage electrification projects sustain demand for traditional-style portable fixtures with ornate metalwork and fabric shades. The EU Ecodesign Directive efficacy thresholds force commercial buyers toward LED-integrated portable fixtures across hospitality fit-outs. Valencia hosts emerging metal fabrication capabilities qualifying new anodizing and finishing processes for regional supply chain reconfiguration.
Table and Floor Lamps Market Competitive Landscape
European producers anchor the specification-grade tier; Asian fabricators hold volume manufacturing positions. The vendor base organizes around three strategic archetypes: vertically integrated lighting conglomerates controlling LED module production, flat-pack logistics specialists bundling private-label bulb economics, and architect-channel specification houses dominating commercial selection processes. Competitive moves concentrate on backward integration into captive LED supply and geographic expansion into underpenetrated Central European hospitality markets.
Among vertically integrated conglomerates, Signify exemplifies upstream control over LED module production that secures long-term hospitality contracts. IKEA Group occupies a position within flat-pack logistics and private-label bulb bundling that lowers total installed cost for residential buyers. Acuity Brands anchors the commercial specification channel where architect-led procurement controls fixture selection for boutique projects.
| Leading Market Players |
|---|
| Signify |
| IKEA Group |
| Acuity Brands |
| Artemide |
| FLOS |
| Philips |
| OSRAM |
| Wayfair |
| Kichler Lighting |
| Others |
Pricing and Supply Chain Analysis
Hospitality procurement teams demanding EU Ecodesign Directive compliance are compressing supplier margins, forcing metal fabricators toward Turkish finishing capabilities and accelerating shade material substitution away from concentrated Murano and Bohemia sources.
Pricing Analysis
Capacity additions in Turkish and North African metal finishing are reshaping price floors for brass and copper-dominant fixture portfolios. Three-tier pricing structure across premium artisan, specification-grade, and flat-pack residential levels separates heritage hotel procurement from mass-market retail. Cost compression in standard-grade metal fixtures is intensifying because Chilean mining output volatility feeds directly into rod pricing. Hospitality chains exhibit least price sensitivity due to long-term contract structures; residential renovation contractors show highest sensitivity to total installed cost.
Supply Chain Analysis
Mouth-blown glass supply rests on Italian Murano and Czech Bohemia craftsperson clusters with limited geographic diversification. Brass rod draws from Chilean and Peruvian mining output; fabric shade materials source from South Asian textile mills. Single-source vulnerability concentrates in artisan glass production where energy cost spikes and skilled labor shortages constrain output expansion. Distribution runs through architect-led specification channels for premium tiers and flat-pack retail logistics for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Table and Floor Lamps Market functions as a stable compounder, with LED efficacy mandates across the European Union generating predictable replacement demand that sustains manufacturer revenue visibility.
For Market Incumbents: Lock in long-term hospitality contracts through captive LED module supply and dual-certification bundling that satisfies both EU Ecodesign and US Energy Star requirements. Threats from direct-to-designer platform disintermediation in Scandinavian markets demand reinforced architect-channel relationships through digital configurators and specification support teams. For New Entrants and Emerging Players: Enter via Polish and Romanian hospitality expansion where luxury hotel development remains underpenetrated and first-mover positioning in specification-grade portable lighting is achievable. The most penetrable segment is modular fixture architectures aligned with French AGEC law repairability mandates; go-to-market leverage centers on spare parts availability documentation and standardized component interfaces. For Investors and Strategic Acquirers: Asymmetric upside sits with specification-grade portable lighting houses controlling architect-channel access in German and Scandinavian markets. Long-term viability over a multi-year window hinges on sustainability-mandated modular design capabilities and circadian-tunable LED integration. The signal to watch is hospitality operator pilot adoption of seasonal shade swap programs enabled by magnetic attachment systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Module Production | Signify's captive supply secures long-term hospitality contracts against component volatility. |
| Modular Fixture Architecture Development | French AGEC law compliance opens specification access through repairability-mandated design. |
| Geographic Expansion into Central European Hospitality | Warsaw and Bucharest hotel construction creates first-mover positioning for EU-certified suppliers. |
| Direct-to-Designer Platform Launch | Copenhagen and Stockholm architect-led procurement channels bypass distributor markup compression. |
| Dual Certification Investment | German hotel operator transatlantic standardization preferences streamline US property rollout. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospitality procurement directors, lighting specification architects, metal fabrication plant managers, and Murano glass workshop owners with secondary validation against EU Ecodesign Directive filings, EPA Energy Star certification databases, and Turkish customs export records. Bottom-up segment sizing triangulated against top-down market reconstruction.
Segment-weighting approaches distributed value and volume across product type, material composition, style category, and end-use procurement authority dimensions throughout the forecast period. CAGRs derived from historical trajectory analysis and regulatory mandate timing rather than extrapolation. Industry-specific forecast inputs incorporated LED efficacy threshold implementation schedules and heritage building electrification project pipelines.
Inputs from hospitality operator procurement databases and architect specification registries were available through the study window; gaps in artisan glass workshop production data introduce uncertainty bands around premium segment sizing. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and supply chain reconfiguration pace. A small set of named triggers—French AGEC law expansion, California Title 24 amendments, and Chilean mining labor actions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
North Africa Ceiling Fan Market