
 Europe Ceiling Fan Market | 2026-2036
Europe Ceiling Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ceiling Fan Market Intelligence
Buyer concentration across Europe's hospitality sector is decoupling from traditional procurement patterns as boutique hotel chains and co-living operators fragment the specification landscape. Hunter Fan Company leverages its heritage brand strength to anchor premium positioning in renovated heritage properties across France and the United Kingdom. CasaFan competes through design-forward specialization, while Panasonic Corporation extends its electronics ecosystem into smart-enabled fan systems for integrated building management.
A ceiling fan is an electrically powered air circulation device comprising a rotating hub with multiple blades, typically spanning 900 to 1,400 millimeters in diameter, driven by either alternating current induction motors or direct current brushless motors to create convective cooling through air displacement. The primary industrial and commercial purpose centers on enhancing thermal comfort while reducing HVAC energy loads through improved air distribution and perceived temperature reduction. Energy Efficient Fans dominate procurement specifications as Ecodesign regulations tighten minimum performance thresholds, while Smart Technology features represent the fastest-growing specification category as building automation systems penetrate mid-market residential and commercial installations. Decorative Fans retain margin concentration in heritage restoration and luxury residential segments where aesthetic integration commands specification priority.
The EU Ecodesign Directive and F-Gas Regulation collectively shape product standards by mandating minimum energy efficiency indices and restricting refrigerant-dependent cooling alternatives that indirectly compete with fan-based ventilation. CE marking requirements under the Low Voltage Directive and Electromagnetic Compatibility standards govern market access, with national regulators such as KBA in Germany and ANSM-affiliated testing bodies in France enforcing compliance through market surveillance. Stakeholders must monitor the interplay between tightening Ecodesign tiers and smart technology interoperability standards to align R&D roadmaps with procurement specifications that increasingly bundle energy performance with connected building infrastructure.
Market Dynamics
The EU Ecodesign Directive is compressing motor efficiency tiers and forcing wholesale technology transitions across European manufacturing bases, with brushless DC motors displacing AC induction architectures in procurement specifications.
Growth Catalysts
- Residential Retrofit Demand:Italian and Spanish households are replacing aging cooling infrastructure with energy-efficient ceiling fans as primary thermal comfort solutions, bypassing refrigerant-dependent air conditioning.
- F-Gas Regulation:Restrictions on hydrofluorocarbon refrigerants are eliminating competitive alternatives and positioning fan-based ventilation as compliant cooling across commercial hospitality applications.
- Smart Building Integration:BACnet and KNX protocol adoption is converging with ceiling fan controls, enabling automated air distribution that reduces HVAC energy loads in renovated office stock.
Market Restraints
- Copper and Rare Earth Volatility:Brushless DC motor production depends on neodymium magnet supply chains concentrated in Chinese processing facilities, exposing European assemblers to input cost swings.
- Southern European Demand Concentration:Italy, Spain, and Portugal account for disproportionate volume, leaving manufacturers exposed to regional economic cycles and construction permit delays.
- Technical Ceiling on Efficiency Gains:Aerodynamic blade design approaches theoretical limits, constraining further energy performance differentiation under tightening Ecodesign tiers.
Strategic Opportunities
- Co-Living and Boutique Hospitality:Fragmented accommodation operators across France and Germany are specifying design-forward fans as brand differentiation tools in renovation projects.
- CE Marking Harmonization:Mutual recognition agreements under the Low Voltage Directive are reducing retesting burdens for manufacturers entering adjacent Eastern European markets.
- Photovoltaic Pairing:DC-native ceiling fan architectures are converging with residential solar installations, creating off-grid cooling propositions for rural Iberian properties.
Industry Challenges
- Electronics Firmware Expertise Gap:Traditional mechanical fan manufacturers lack embedded systems capabilities for smart control development, forcing reliance on external semiconductor partners.
- Multi-Tier Certification Complexity:CE marking under Electromagnetic Compatibility standards requires parallel testing against national deviations in Germany and France, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ceiling Fan Market |
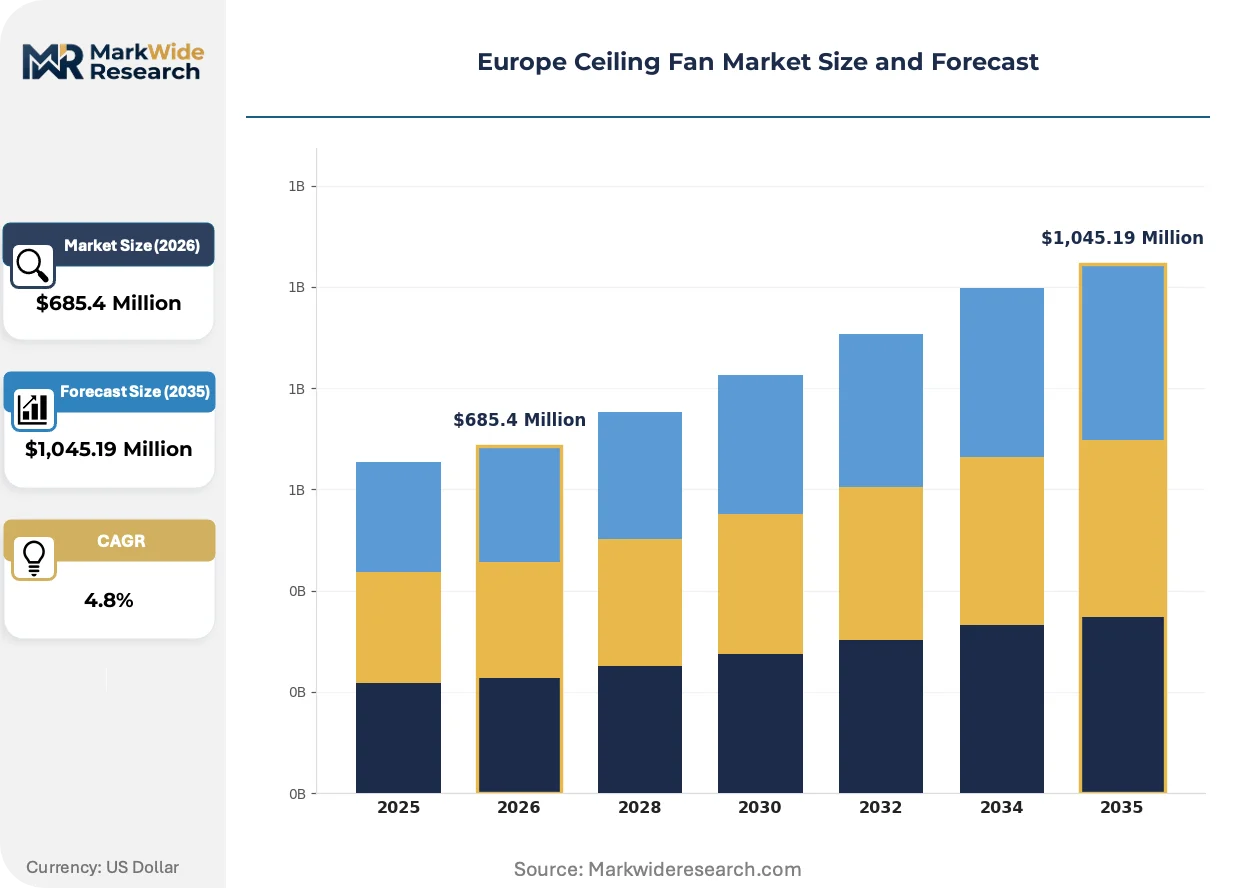
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fans, Decorative Fans, Remote Control Fans, Energy Efficient Fans End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesale Feature: Reversible Motor, Integrated Lighting, Smart Technology, Quiet Operation |
| Companies Covered | Big Ass Fans, The Henley Fan Company, Hunter Fan Company, Panasonic Corporation, Havells India Ltd., CasaFan, Ferguson PLC, Westinghouse Electric Corporation, Crompton Greaves Consumer Electricals Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ceiling Fan Market Strategic Shifts & Innovations
Product architectures are bifurcating between stripped-down efficiency platforms for mass residential deployment and sensor-rich connected systems for commercial building automation, with specification criteria fragmenting accordingly.
Brushless DC motor technology is converging with variable frequency drive controls to deliver granular speed modulation and whisper-quiet operation. Boutique hotel operators across Provence and Tuscany are specifying these platforms for guest room renovations. The technology is converging with occupancy sensors to enable demand-responsive air circulation that cuts HVAC runtime in heritage properties with limited ductwork.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules and indirectly elevating fan-based cooling in commercial specifications. Building services engineers in Madrid and Barcelona are redesigning thermal comfort strategies around displacement ventilation paired with ceiling fans. Hospitality developers across Southern Europe are responding by deleting split-system air conditioning from mid-market property fit-outs.
Specification authority is migrating from facilities managers to sustainability officers under corporate ESG mandates. Large employers in Frankfurt and Amsterdam are bundling ceiling fan deployment with building certification targets like BREEAM. This behavioral shift is most visible in Benelux commercial retrofits where procurement committees now weight embodied carbon and operational efficiency above first-cost considerations.
Europe Ceiling Fan Market Segmentation
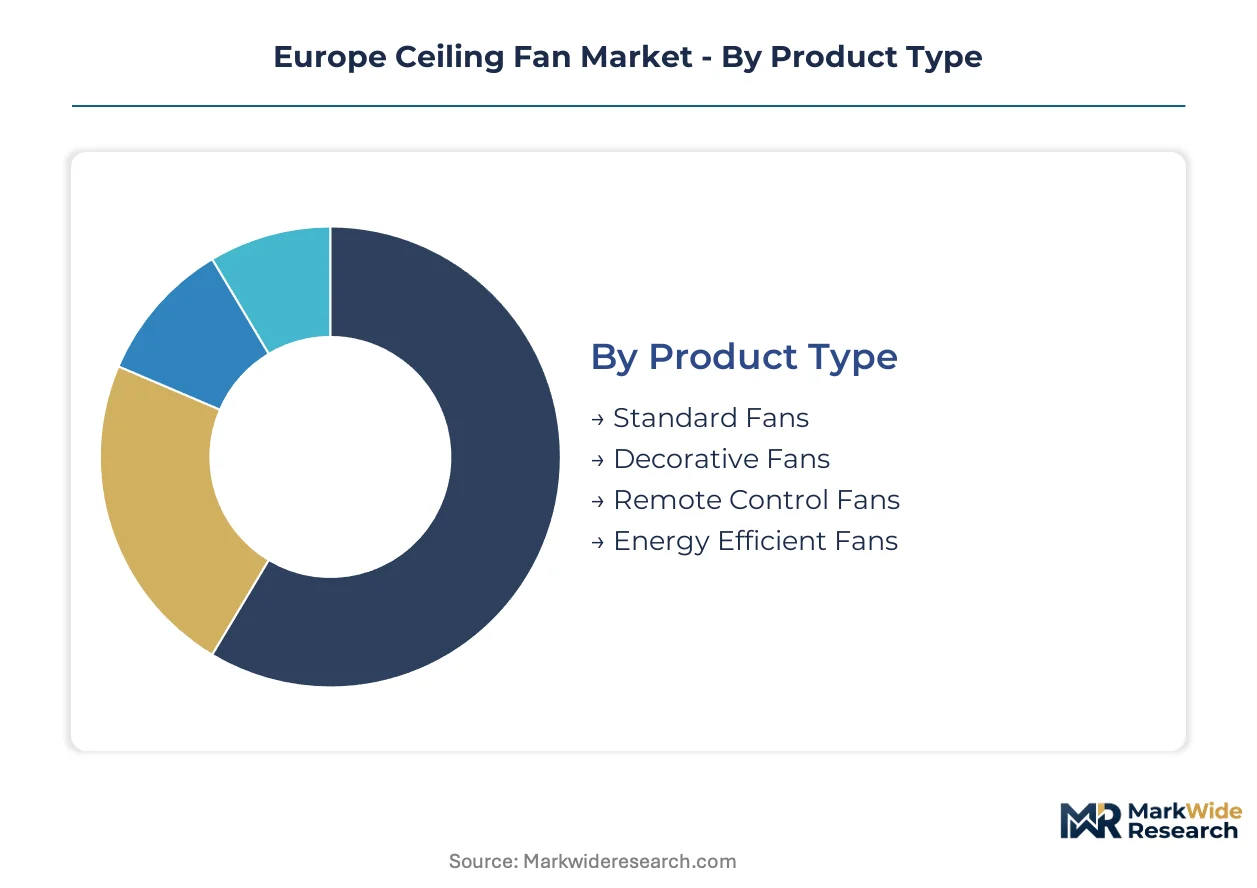
Specification criteria across Europe's ceiling fan market fragment sharply between energy compliance mandates and aesthetic integration requirements. Procurement committees weight Ecodesign tier alignment against smart building protocol compatibility, creating divergent product architectures.
Product Type:
Cost tier determines specification authority, with premium positioning commanding design-forward selection while mass deployment prioritizes efficiency certification.
- Energy Efficient Fans:These platforms integrate brushless DC motors and aerodynamically optimized blade geometries to meet tightening Ecodesign efficiency indices. Demand concentrates in Italian and Spanish residential retrofits where households bypass refrigerant-dependent cooling. The EU F-Gas Regulation indirectly elevates these specifications as compliant alternatives gain procurement priority.
- Decorative Fans:Heritage restoration projects across Provence and Tuscany specify these units where aesthetic integration commands premium positioning. Boutique hotel operators fragment traditional procurement patterns by selecting design-forward platforms as brand differentiation tools. Margin concentration remains highest where blade finishes and custom housing materials align with period architectural requirements.
- Standard Fans:AC induction motor architectures dominate mass residential deployment in Portugal and rural Iberian markets where first-cost sensitivity prevails over efficiency optimization.
- Remote Control Fans:Convenience features penetrate mid-market Spanish apartment renovations where hardwired wall controls prove impractical in aging electrical infrastructure.
Volume sits with Standard Fans; growth tilts toward Energy Efficient Fans.
End User:
Application context reshapes technical requirements, with commercial installations demanding BACnet interoperability while residential selection centers on acoustic performance.
- Residential:Southern European households in Italy and Spain drive replacement cycles as aging cooling infrastructure gives way to fan-based thermal comfort. Ecodesign tier compression accelerates technology transitions from AC induction to brushless DC architectures in procurement specifications.
- Hospitality:Co-living operators and boutique hotel chains across France and Germany fragment traditional specification authority. Design-forward fans serve as brand differentiation tools in renovation projects where heritage properties limit ductwork modifications.
- Commercial:Frankfurt and Amsterdam employers bundle deployment with BREEAM certification targets under corporate ESG mandates.
- Industrial:Warehouse and logistics facilities in Benelux prioritize displacement ventilation paired with high-volume air circulation.
Procurement volume clusters in Residential; Hospitality climbs the fastest.
Distribution Channel:
Customer type fragments access patterns, with project-scale commercial buyers bypassing retail entirely while residential retrofit depends on tactile evaluation.
- Direct Sales:Large hospitality developers and commercial building services engineers specify through manufacturer representatives. KNX and BACnet protocol integration requirements necessitate technical consultation unavailable through retail channels.
- Specialty Stores:Milan and Barcelona showrooms serve heritage restoration architects requiring material finish validation. Design-forward selection for Tuscan boutique properties depends on physical blade and housing inspection.
- Online Retail:Standard and remote-control platforms penetrate price-sensitive Portuguese and Spanish residential markets.
- Wholesale:Electrical contractors in Southern Europe bulk-procure for multi-unit residential retrofit programs.
Transaction volume flows through Specialty Stores; Direct Sales expands most quickly.
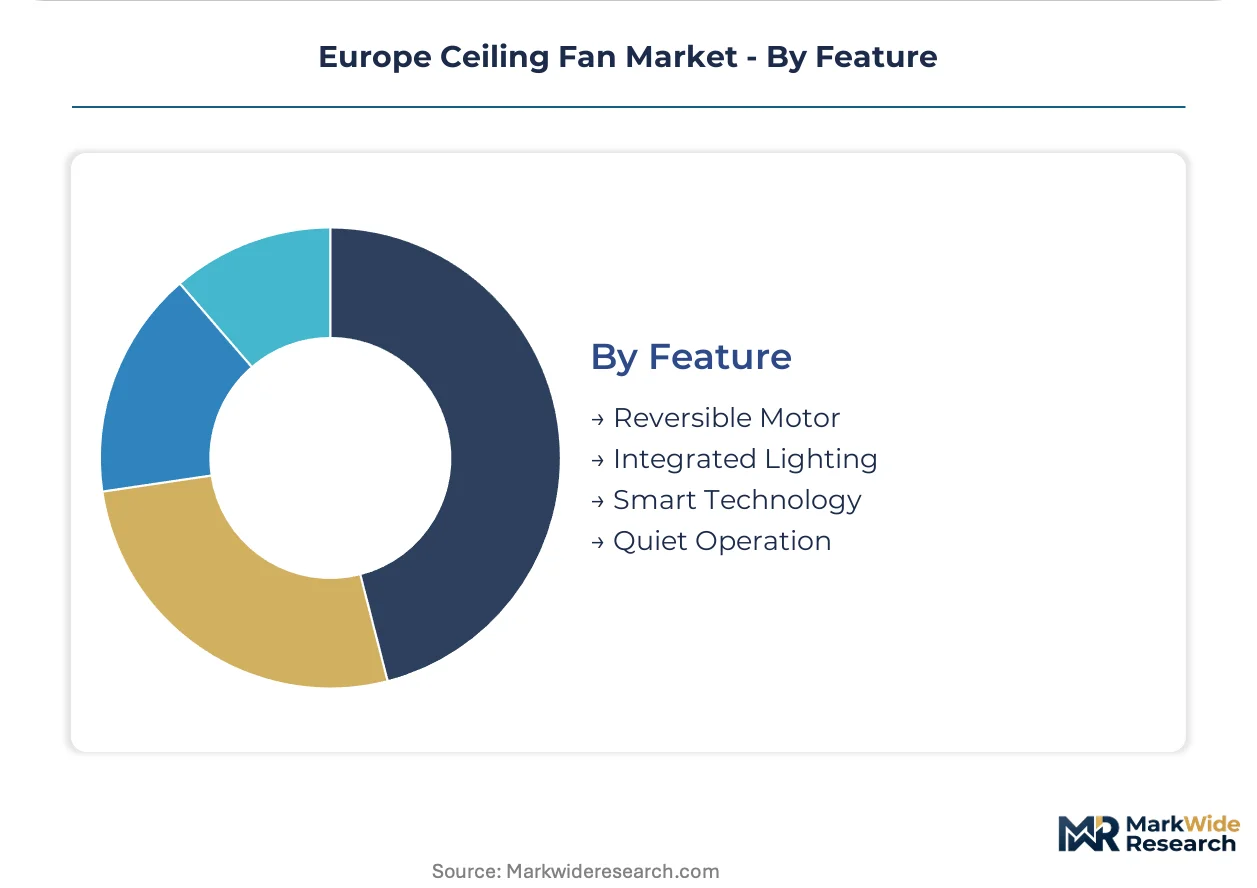
Feature:
Maturity gradients separate established motor functionality from emerging connectivity requirements, with specification authority migrating toward sustainability officers under ESG mandates.
- Smart Technology:Sensor-rich platforms enable demand-responsive air circulation through occupancy detection and automated speed modulation. BACnet and KNX protocol adoption converges with fan controls in renovated Frankfurt and Amsterdam office stock.
- Quiet Operation:Brushless DC motor architectures with variable frequency drive controls deliver whisper-quiet performance. Guest room renovations across Provence and Tuscany specify these platforms where acoustic comfort determines satisfaction metrics.
- Reversible Motor:Seasonal airflow direction switching addresses thermal stratification in high-ceilinged heritage properties.
- Integrated Lighting:LED-embedded housings consolidate ceiling fixtures in space-constrained Spanish apartments.
Penetration is deepest for Reversible Motor; Smart Technology gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and Spanish households drive replacement demand as aging cooling infrastructure gives way to fan-based thermal comfort. Southern European markets concentrate volume, while Northern European commercial retrofits accelerate specification of smart-enabled systems.
Italy
Tuscan boutique hotels and heritage properties specify design-forward fans as brand differentiation tools in renovation projects. The EU Ecodesign Directive compresses motor efficiency tiers and accelerates technology transitions from AC induction to brushless DC architectures. Milan showrooms serve architects requiring material finish validation for period restoration work.
Spain
Madrid and Barcelona building services engineers redesign thermal comfort strategies around displacement ventilation paired with ceiling fans. The EU F-Gas Regulation tightens refrigerant phase-down schedules and elevates fan-based cooling in commercial specifications. Hospitality developers across Southern Spain delete split-system air conditioning from mid-market property fit-outs.
Germany
Frankfurt employers bundle ceiling fan deployment with BREEAM certification targets under corporate ESG mandates. KBA enforces CE marking compliance under Electromagnetic Compatibility standards through market surveillance. The KNX protocol adoption converges with fan controls in renovated office stock across the Rhine-Main metropolitan region.
France
Provence guest room renovations specify brushless DC platforms where acoustic comfort determines satisfaction metrics. ANSM-affiliated testing bodies enforce Low Voltage Directive compliance through national deviation testing. Heritage restoration projects across the Côte d'Azur fragment traditional procurement patterns with design-forward selection.
Netherlands
Amsterdam commercial retrofits weight embodied carbon and operational efficiency above first-cost considerations under sustainability officer authority. The CSRD disclosure requirements elevate procurement documentation standards for building certification alignment. Benelux warehouse facilities prioritize displacement ventilation paired with high-volume air circulation systems.
Europe Ceiling Fan Market Key Industry Players
German and Italian producers anchor one tier; Asian specialists hold component supply positions. The vendor base organizes around heritage brand strength, electronics ecosystem extension, and design-forward specialization. Three archetypes dominate: established mechanical manufacturers pivoting toward smart controls, electronics conglomerates leveraging building automation expertise, and boutique fabricators serving aesthetic-driven hospitality segments. Competitive moves center on strategic partnerships for semiconductor sourcing and portfolio diversification into integrated lighting systems.
Within the heritage-brand tier, Hunter Fan Company and Westinghouse Electric Corporation occupy positions anchored in renovated property specifications across France and the United Kingdom. Panasonic Corporation exemplifies the electronics-ecosystem archetype, extending building automation capabilities into connected fan systems. CasaFan represents design-forward specialization, serving fragmented boutique hospitality operators across Provence and Tuscany where aesthetic integration commands premium positioning.
| Leading Market Players |
|---|
| Big Ass Fans |
| The Henley Fan Company |
| Hunter Fan Company |
| Panasonic Corporation |
| Havells India Ltd. |
| CasaFan |
| Ferguson PLC |
| Westinghouse Electric Corporation |
| Crompton Greaves Consumer Electricals Limited |
| Others |
Cost & Logistics Intelligence
Brushless DC motor adoption across European manufacturing bases simultaneously compresses production economics and concentrates procurement leverage among semiconductor-integrated suppliers. The technology transition from AC induction architectures feeds back into supply chain restructuring as assemblers shed mechanical component sourcing in favor of magnet and drive-control partnerships.
Pricing Analysis
Volume sits with standard AC induction platforms while margins concentrate in smart-enabled brushless DC tiers. Price differentiation hinges on Ecodesign certification tier and smart protocol compatibility, with KNX-integrated systems commanding premium positioning over basic remote-control units. Cost compression in mass residential segments is intensifying because Portuguese and Spanish first-cost buyers resist efficiency premiums. Electrical contractors represent the most price-sensitive procurement channel, while heritage restoration architects exhibit least sensitivity due to aesthetic specification authority.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese rare earth processing facilities, while semiconductor fabrication for variable frequency drives centers on Taiwan and South Korea. Copper winding supply draws from German and Polish metal processors, with blade housing plastics sourced from Benelux petrochemical complexes. Single-source vulnerability in magnet supply chains exposes European assemblers to export restriction risk. Distribution runs through manufacturer representatives for commercial project-scale buyers, with specialty showrooms and wholesale electrical channels serving fragmented residential retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
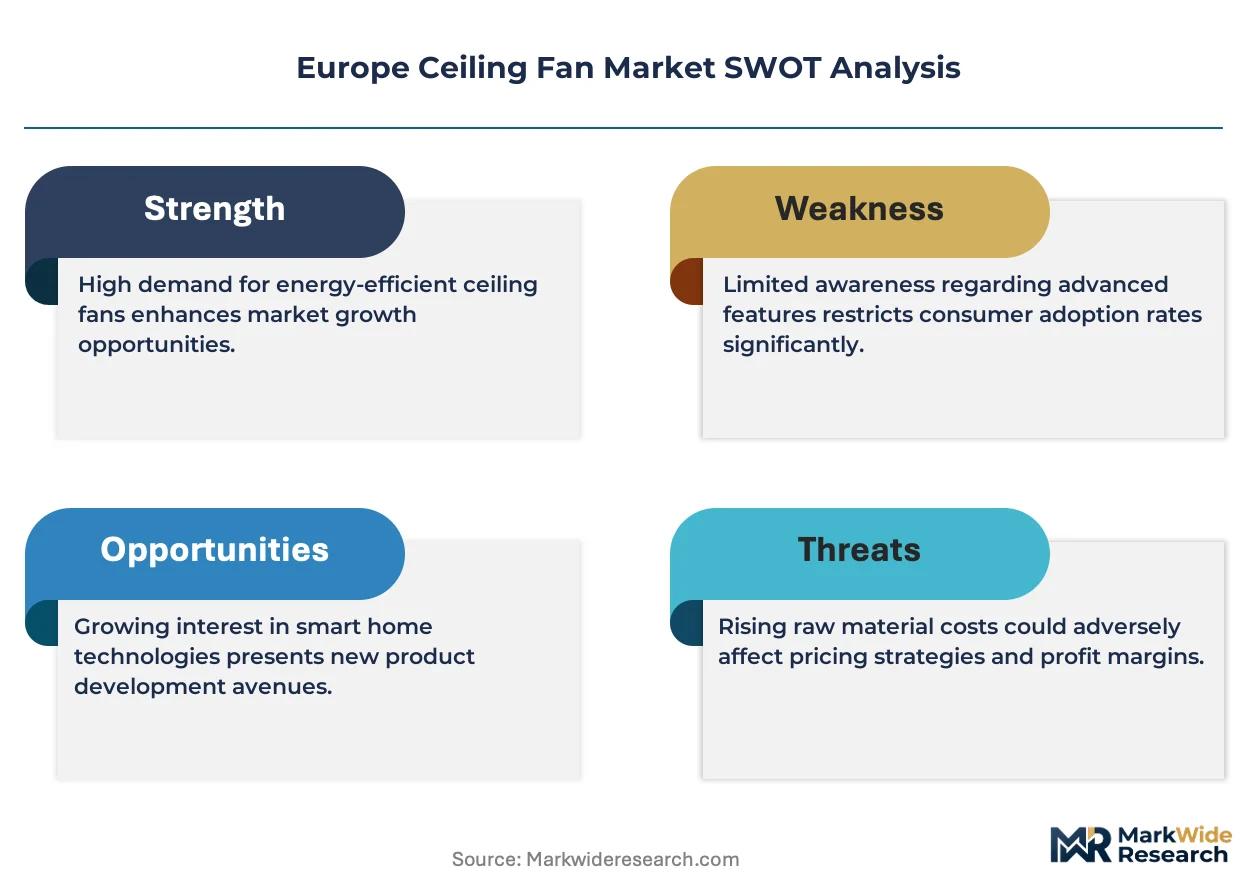
EU Ecodesign tier compression is forcing technology transitions that weaker mechanical manufacturers cannot fund, creating consolidation pressure across the supplier base. Margin concentration in smart-enabled and design-forward segments rewards players with firmware capabilities or heritage brand equity.
For Market Incumbents: Lock in semiconductor partnerships to bridge the electronics firmware expertise gap threatening traditional mechanical manufacturers. Secure KNX and BACnet certification pathways ahead of tightening smart building integration requirements. Backward integration into magnet supply arrangements mitigates Chinese rare earth processing concentration risk. For New Entrants and Emerging Players: E-commerce direct-to-consumer routes penetrate price-sensitive Portuguese and Spanish residential markets underserved by established brand distribution. Target co-living and boutique hospitality operators across France and Germany with design-forward platforms as brand differentiation tools. White-space exists in photovoltaic-paired DC-native architectures for rural Iberian off-grid properties. For Investors and Strategic Acquirers: Exit pathways concentrate in electronics ecosystem extension plays and heritage brand consolidation. Long-term viability favors assemblers with captive magnet sourcing or embedded systems capabilities over pure mechanical manufacturers. Watch Ecodesign tier implementation timing as the inflection indicator for technology transition funding requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Protocol Certification Investment | KNX and BACnet integration unlocks Frankfurt and Amsterdam commercial retrofit specifications under ESG mandates. |
| Magnet Supply Partnership | Long-term rare earth processing agreements insulate brushless DC production from Chinese export volatility. |
| Heritage Brand Acquisition | Design-forward positioning in Provence and Tuscany boutique hospitality commands premium margin capture. |
| Photovoltaic System Integration | DC-native architectures pair with residential solar installations across rural Iberian markets. |
| Embedded Systems Capability Buildout | In-house firmware development reduces reliance on external semiconductor partners for smart control features. |
Research Approach
EU regulatory filings, Ecodesign tier documentation, and F-Gas Regulation implementation schedules formed the secondary backbone for standard and compliance mapping. Primary interviews with building services engineers, electrical contractor procurement leads, heritage restoration architects, and hospitality development executives combined with customs trade data and national construction permit databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Historical trendline analysis of motor technology substitution patterns and efficiency standard adoption curves anchored the projection framework. Segmentation modeling spanned product architecture, end-use application, distribution channel, and smart feature penetration across the projection horizon. CAGRs derived from technology transition velocity and regulatory compliance timelines, with inputs from copper and rare earth price volatility indices and Southern European construction cycle indicators.
The model holds under steady Ecodesign implementation schedules; deviation in magnet export restrictions or F-Gas phase-down acceleration would shift technology transition timelines. Forecasts reflect assumptions around smart building protocol adoption rates and hospitality sector renovation activity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Kids Desk Lamp Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Kitchen Lighting Market