
 Christmas Lights and Christmas Decorations Market | 2026-2036
Christmas Lights and Christmas Decorations Market Size, Share, and Industry Trends Forecast 2026-2036
Christmas Lights and Christmas Decorations Market Insights
Seasonal lighting assembly labor is rotating toward higher-skill LED electronics integration as incandescent production phases down. Balsam Hill leverages direct-to-consumer channel control to dominate premium artificial tree segments. Koninklijke Philips N.V. sustains technology leadership in connected, app-controlled holiday lighting systems. Kurt S. Adler, Inc. specializes in licensed character ornaments and collectible decorative pieces for specialty retail.
Christmas lights and decorations encompass electrically illuminated strands, standalone ornaments, and seasonal display fixtures engineered to UL 588 safety standards for seasonal-use electrical products, with LED variants specified at 4-6 watts per 100 bulbs versus 40-60 watts for legacy incandescent designs. LED Lights now anchors the product mix as municipalities and commercial buyers prioritize energy-cost reduction across extended operating schedules. Residential application maintains volume leadership while Commercial application captures disproportionate margin pools from custom architectural installations. Online Retail is displacing traditional wholesale channels for replacement bulb and accessory purchases.
UL standards in the United States, CE marking under EU Ecodesign requirements, and China's GB 7000 series for luminaire safety collectively shape product compliance costs and market access thresholds for seasonal lighting imports. The EU's F-Gas Regulation and expanding state-level right-to-repair legislation in California and New York are pressuring manufacturers toward modular, serviceable LED designs with standardized connectors. Stakeholders must monitor how emerging battery-storage and solar-integrated outdoor displays reshape procurement specifications for off-grid municipal and park installations.
Market Dynamics
The EU's Ecodesign Directive and RoHS standards are forcing incandescent-to-LED conversion across import-dependent supply chains, compressing assembly labor toward electronics integration while reshaping procurement specifications for municipal and commercial buyers.
Growth Catalysts
- LED wattage differential:Municipal buyers in Germany's Bavaria region prioritize 4-6 watt LED strands over 40-60 watt incandescent alternatives for extended Christmas market operating schedules, cutting energy costs by an order of magnitude.
- Commercial property expansion:North American retail corridor managers are expanding seasonal lighting budgets to capture foot traffic through custom architectural installations.
- Right-to-repair momentum:California and New York state legislation pressures manufacturers toward modular LED designs with standardized connectors, extending product lifecycles and reducing replacement frequency.
Market Restraints
- Input cost volatility:Copper and semiconductor pricing fluctuations squeeze margin structures for LED driver electronics, particularly affecting low-volume residential suppliers without forward-contracting power.
- Regulatory friction:China's GB 7000 series luminaire safety standards create compliance cost layering with UL 588 and CE marking requirements, extending certification timelines for cross-border shipments.
- Substitution threat:Projection-based digital holiday displays and immersive experience venues capture share from physical lighting installations among younger demographics in urban cores.
Strategic Opportunities
- Solar-battery convergence:Off-grid municipal and park installations in Germany and Austria are specifying solar-integrated outdoor displays, opening procurement categories beyond grid-tied products.
- App-controlled systems:Connected lighting platforms enable subscription-based programming services and remote diagnostics, shifting revenue from hardware to recurring software.
- Specialty retail licensing:Collectible character ornaments and limited-release decorative pieces command premium positioning through controlled distribution and scarcity marketing.
Industry Challenges
- Electronics assembly skill gap:Seasonal lighting factories face acute shortages of technicians trained in SMT soldering and LED driver programming, forcing wage compression or automation capex.
- Multi-jurisdiction certification lag:Simultaneous UL 588, CE marking, and GB 7000 testing creates 8-14 month product launch timelines, misaligning with compressed seasonal buying windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Christmas Lights and Christmas Decorations Market |
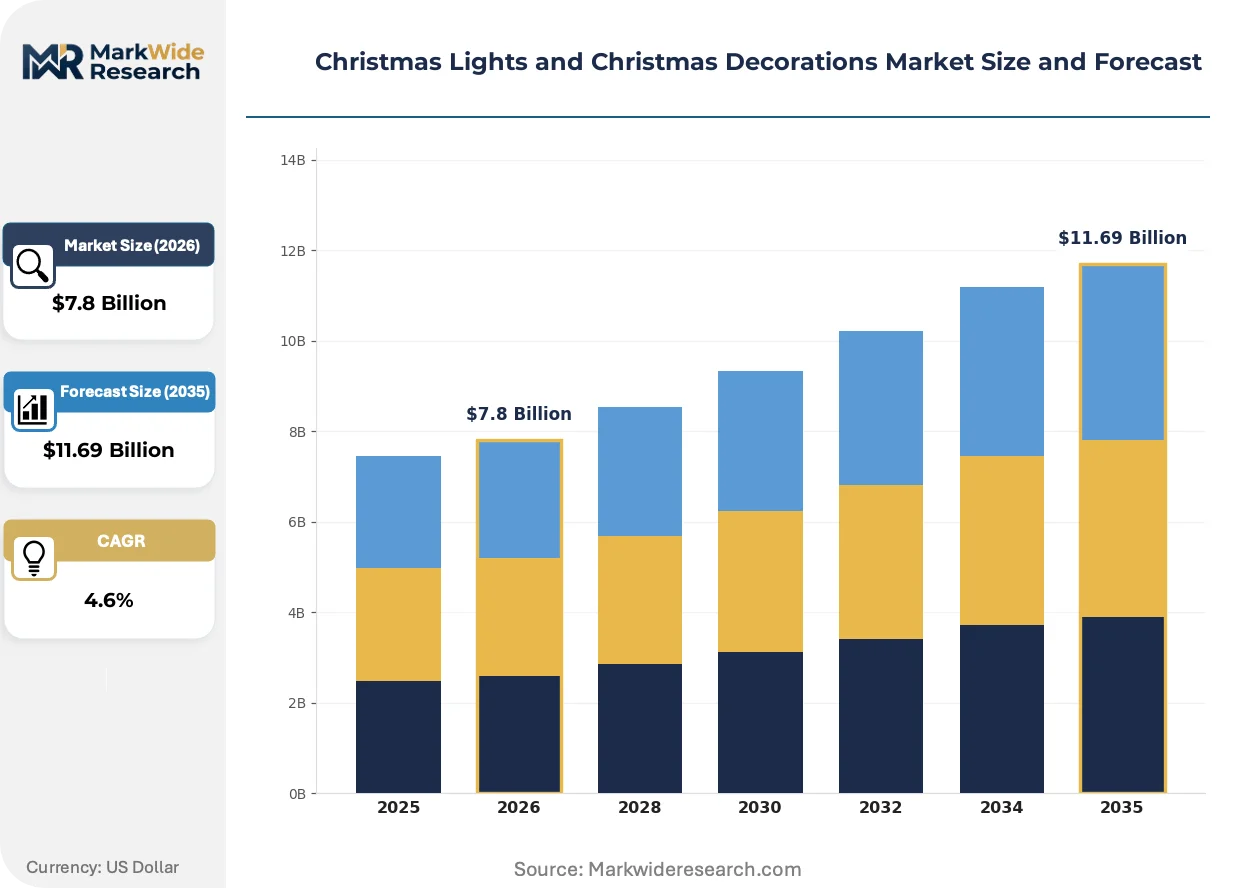
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Incandescent Lights, Neon Lights, Decorative Ornaments Application: Residential, Commercial, Event Planning, Retail Displays End User: Homeowners, Businesses, Event Coordinators, Retail Merchants Distribution Channel: Online Retail, Specialty Stores, Wholesale, Pop-Up Shops |
| Companies Covered | Blachere Illumination, Lenox Corporation, General Electric, The Bradford Exchange, Hallmark Cards Inc., Koninklijke Philips N.V., Kurt S. Adler, Inc., Amscan, Balsam Hill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Christmas Lights and Christmas Decorations Market Trends and Innovations
Active reshaping in this market centers on component-level transformation, regulatory-driven design standardization, and channel migration away from wholesale intermediaries toward direct fulfillment models.
Micro-LED chip-on-board technology is miniaturizing individual diodes below 100 microns while maintaining lumen output, enabling denser strand configurations and flexible form factors previously impossible with discrete packaged LEDs. Commercial installers in Germany's municipal Christmas markets are adopting these strands for complex three-dimensional tree wraps and building facades. The technology is miniaturizing the physical footprint of control electronics, allowing battery and solar integration into previously grid-dependent applications.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in manufacturing processes, forcing decorative lighting producers to retool assembly lines toward solvent-free adhesive and coating systems. This industrial consequence elevates capital requirements for EU market access while creating compliance differentiation for early adopters. Premium artificial tree and ornament segments are most affected, with Bavarian producers accelerating water-based finishing transitions to maintain CE marking eligibility.
Online retail platforms are capturing replacement bulb and accessory purchases that previously flowed through hardware store and garden center wholesale channels, compressing distributor margins and forcing inventory consolidation. The segment being disrupted is independent lighting retailers, replaced by manufacturer-direct storefronts and marketplace fulfillment. This channel rotation is most visible in North American residential markets, where Prime-enabled delivery windows compress emergency replacement cycles from days to hours.
Christmas Lights and Christmas Decorations Market Segmentation
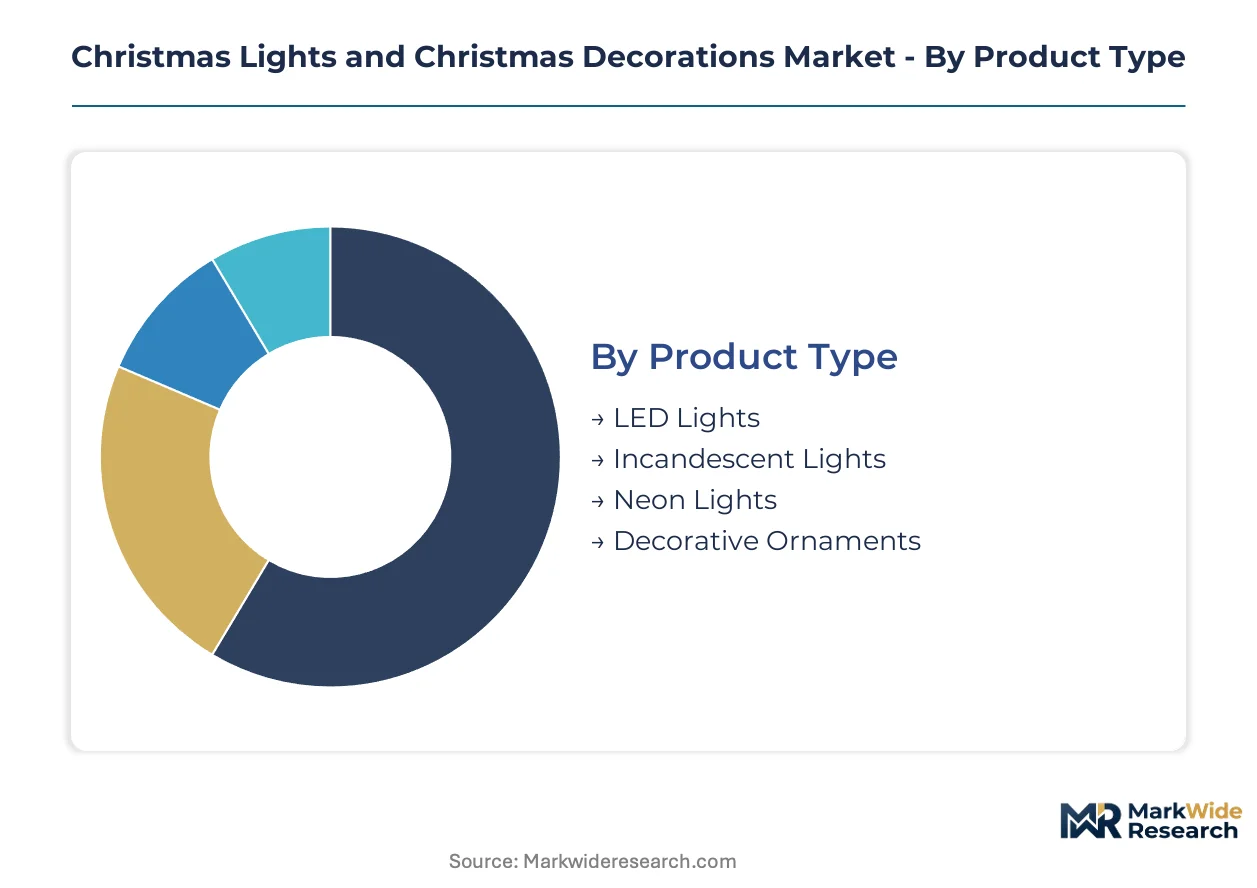
Christmas lighting procurement splits sharply between bulk municipal buyers in Germany's Bavaria region and fragmented North American residential replacement cycles. Understanding these segment boundaries clarifies where LED conversion investments concentrate versus where incandescent liquidation still generates margin.
Product Type:
German municipal Christmas markets and Austrian park installations drive export-led demand for two product categories, while domestic North American consumption absorbs the remainder.
- LED Lights:Engineered at 4-6 watts per 100 bulbs versus 40-60 watts for legacy designs, these strands meet EU Ecodesign Directive thresholds for Bavarian municipal procurement. Demand concentrates in commercial architectural installations where extended operating schedules make energy-cost reduction decisive.
- Incandescent Lights:Phased-down production now serves price-sensitive residential replacement cycles in rural North American markets and developing economies without RoHS enforcement. Manufacturers without forward-contracting power face margin compression from copper volatility.
- Neon Lights:Custom glass-tube fabrication for commercial signage and experiential retail displays commands premium positioning through controlled craft production.
- Decorative Ornaments:Licensed character pieces and limited-release collectibles generate scarcity-driven pricing through specialty retail channels.
LED Lights commands the established base. The steepest expansion runs through Neon Lights as immersive experience venues substitute projection displays for physical installations.
Application:
Margin concentration follows application tier, with custom commercial work capturing disproportionate returns against commoditized residential volume.
- Residential:Volume leadership in bulb replacement and accessory purchases, now migrating from hardware store wholesale channels to manufacturer-direct online fulfillment with Prime-enabled delivery compression.
- Commercial:Custom architectural installations across North American retail corridors generate premium pricing through project-specific engineering and extended operating warranties.
- Event Planning:Temporary deployment specifications for corporate and municipal celebrations drive seasonal rental and full-service installation revenue.
- Retail Displays:Window and interior merchandising systems integrate synchronized lighting with merchandise presentation, requiring rapid deployment timelines aligned with holiday selling seasons.
Residential maintains volume dominance. Commercial applications are climbing the fastest as property managers expand seasonal lighting budgets for foot traffic capture.
End User:
Procurement sophistication separates institutional buyers with multi-year LED amortization models from transactional residential purchasers.
- Homeowners:Fragmented demand for replacement bulbs and strand extensions, increasingly fulfilled through online retail platforms rather than garden center intermediaries.
- Businesses:Corporate facility managers and commercial property owners specify UL 588 safety compliance for seasonal-use electrical products across extended operating schedules.
- Event Coordinators:Professional planners source full-service installation and removal, bundling labor with equipment rental for municipal and corporate celebrations.
- Retail Merchants:Seasonal merchandising teams procure synchronized display systems with compressed deployment windows aligned with holiday selling peaks.
Homeowners represent the volume foundation. Businesses are gaining share fastest as energy-cost reduction mandates accelerate incandescent-to-LED conversion.
Distribution Channel:
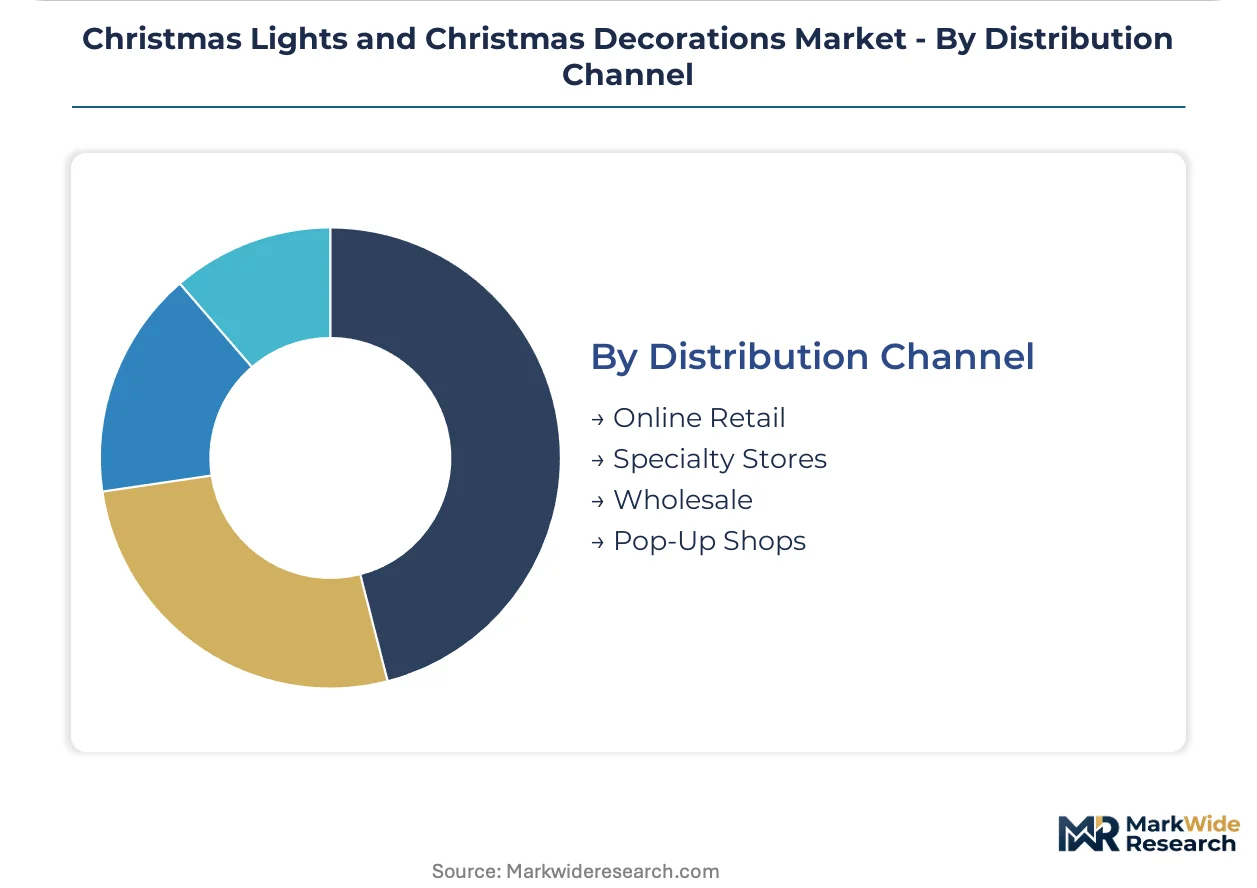
Channel migration away from wholesale intermediaries toward direct fulfillment is compressing distributor margins and consolidating inventory risk with manufacturers.
- Online Retail:Marketplace platforms and manufacturer-direct storefronts now capture replacement bulb and accessory purchases previously flowing through hardware store channels, compressing emergency replacement cycles from days to hours.
- Specialty Stores:Curated ornament and collectible segments maintain foot traffic through licensed character exclusives and scarcity marketing.
- Wholesale:Traditional hardware store and garden center channels face margin compression as inventory risk shifts to direct fulfillment models.
- Pop-Up Shops:Seasonal temporary retail captures impulse purchases and last-minute replacement demand in high-traffic urban and suburban locations.
Wholesale retains residual volume. Online Retail shows the steepest expansion trajectory as Prime-enabled delivery windows reshape consumer expectations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Bavaria region consumes Christmas lighting as municipal infrastructure investment, while North American buyers treat it as discretionary retail expenditure. This consumption-mix differential shapes procurement timelines, certification requirements, and margin structures across major demand centers.
United States
Commercial property managers across Texas and Florida retail corridors are expanding seasonal lighting budgets to capture foot traffic through custom architectural installations. The EPA's ENERGY STAR program and state-level right-to-repair legislation in California and New York pressure manufacturers toward modular LED designs with standardized connectors. Chicago's Magnificent Mile and New York's Fifth Avenue anchor North American premium commercial installations.
Germany
Municipal Christmas markets in Bavaria and North Rhine-Westphalia drive concentrated procurement of commercial-grade LED installations with extended operating warranties. The EU's Ecodesign Directive and F-Gas Regulation enforce energy-efficiency thresholds and solvent-free manufacturing processes. Nuremberg's Christkindlesmarkt and Munich's Marienplatz markets specify 4-6 watt LED strands for 6-8 week operating schedules.
China
Export-oriented manufacturing clusters in Guangdong and Zhejiang provinces supply LED component assembly and finished strand production for import-dependent markets. The GB 7000 series luminaire safety standards create compliance cost layering with UL 588 and CE marking requirements. Yiwu's commodity trading hub consolidates sourcing for seasonal lighting wholesalers serving European and North American buyers.
Canada
Health Canada's PMRA and electrical safety standards under CSA Group certification shape product access for seasonal lighting imports. Toronto's retail corridor managers and Vancouver's municipal park departments prioritize extended-warranty LED installations for harsh winter operating conditions. Quebec's winter festival circuit drives commercial-grade procurement for temporary outdoor displays.
United Kingdom
London's Oxford Street and Edinburgh's Christmas market operators specify commercial-grade LED installations with compressed deployment timelines aligned with holiday selling peaks. The UK's post-EU regulatory framework maintains CE marking alignment for lighting products while developing independent UKCA certification requirements. Birmingham's Frankfurt Christmas Market anchors English municipal procurement volume.
Christmas Lights and Christmas Decorations Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Christmas lighting and decorations, with technology differentiation separating connected-system providers from commodity strand assemblers. The market structure concentrates around three archetypes: diversified electronics conglomerates with lighting divisions, direct-to-consumer artificial tree specialists, and licensed-character ornament houses serving specialty retail. Competitive moves center on backward integration into LED driver electronics and channel control through manufacturer-direct storefronts.
Among diversified technology conglomerates, Koninklijke Philips N.V. exemplifies the connected-systems archetype through its positioning in app-controlled holiday lighting platforms. Kurt S. Adler, Inc. and Balsam Hill occupy distinct specialist positions, with the former representing licensed-character collectible distribution and the latter exemplifying direct-to-consumer channel control in premium artificial tree segments. These three anchors illustrate how technology integration, licensing specialization, and fulfillment model innovation define competitive positioning.
| Leading Market Players |
|---|
| Blachere Illumination |
| Lenox Corporation |
| General Electric |
| The Bradford Exchange |
| Hallmark Cards Inc. |
| Koninklijke Philips N.V. |
| Kurt S. Adler, Inc. |
| Amscan |
| Balsam Hill |
| Others |
Pricing and Supply Chain Analysis
Guangdong province's export-oriented LED assembly capacity operates at seasonal utilization peaks that compress margin structures for stranded inventory. This scale concentration in Chinese manufacturing clusters shapes price floors for commodity strands while German municipal buyers extract volume discounts through multi-year offtake structures.
Pricing Analysis
Contract-based long-term offtake dominates German municipal procurement, with Nuremberg and Munich specifying 4-6 watt LED strands through annual framework agreements. Price differentiation rests on UL 588 certification tier and volume scale, with commercial architectural installations commanding premium positioning. Cost compression in residential tiers intensifies because copper and semiconductor volatility squeezes low-volume suppliers. Rural North American homeowners exhibit highest price sensitivity, while Bavarian procurement offices prioritize energy-cost amortization over unit pricing.
Supply Chain Analysis
Just-in-time inventory strategies prevail among North American retail corridor managers, while German municipal buyers maintain strategic stockpiles ahead of October deployment windows. Supply concentrates in China, Vietnam, and Mexico, with Guangdong and Zhejiang provinces anchoring LED component assembly. The chain draws from copper wire, semiconductor drivers, and ABS resin inputs. Single-source vulnerability runs through Guangdong's concentrated SMT soldering capacity. Distribution runs through manufacturer-direct storefronts and marketplace fulfillment, displacing hardware store wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
App-controlled lighting platforms are expanding recurring-revenue attach faster than hardware sales, converting transactional bulb replacement into subscription-based programming services. This service-layer growth outpaces strand assembly margins by shifting customer relationships from seasonal purchase to continuous engagement.
For Market Incumbents: Shield installed base erosion from projection-based digital displays by accelerating backward integration into LED driver electronics. Capture channel control through proprietary connector standards that resist right-to-repair standardization. Prioritize certification investment in UL 588 modular designs to extend replacement cycles and lock in municipal specification adherence. For New Entrants and Emerging Players: Differentiate on solar-battery convergence for off-grid municipal installations in Austria and Bavaria, where procurement categories remain undefined. Target event planning rental services with full-service installation bundling, the least penetrated application tier. Pursue direct-to-consumer storefront launch with Prime-enabled delivery compression for emergency replacement demand. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected-systems providers with app-controlled platforms and subscription programming services. Long-term viability favors specialists with captive LED driver technology and manufacturer-direct channel control over commodity strand assemblers. Watch solar-integrated outdoor display procurement specifications as inflection indicator for category expansion beyond grid-tied products.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Lighting Platform Launch | Enables subscription-based programming services and remote diagnostics for municipal buyers. |
| Backward Integration into LED Drivers | Captures margin pool from semiconductor volatility and reduces single-source supplier dependency. |
| Solar-Battery Product Line Expansion | Opens procurement categories for off-grid Bavarian park installations beyond grid-tied specifications. |
| Direct-to-Consumer Channel Buildout | Compresses emergency replacement cycles from days to hours through Prime-enabled fulfillment. |
| Modular Design Certification Investment | Extends product lifecycles under California and New York right-to-repair legislation pressure. |
Research Methodology
Desk research of customs trade records, UL certification databases, and municipal procurement disclosures preceded structured interviews with LED strand manufacturers, commercial property managers, and specialty retail buyers. Primary fieldwork with Bavarian Christmas market operators and Guangdong assembly plant managers was cross-validated against Ecodesign Directive compliance filings and ENERGY STAR product listings. Bottom-up segment sizing triangulated with top-down trade flow analysis across the analysis window.
Variance decomposition across product type, application tier, and distribution channel shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating LED wattage differential adoption curves and incandescent phase-down timelines. Forecast inputs included municipal procurement budget disclosures and copper futures pricing volatility indices.
The analysis sits within stated boundaries; outcomes outside sustained EU Ecodesign enforcement or accelerated right-to-repair legislative adoption would require recalibration. Forecasts reflect assumptions regarding semiconductor supply stabilization and seasonal labor availability in Guangdong assembly clusters. Revision becomes warranted when solar-battery procurement specifications cross threshold penetration in German municipal tenders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
Kids Desk Lamp Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market