
 Europe Electric Fireplace Market | 2026-2036
Europe Electric Fireplace Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Fireplace Market Insights
Hospitality sector procurement is expanding across boutique hotels and serviced apartments in France, Germany, and the Netherlands. Glen Dimplex Group leverages its manufacturing scale to supply major European hotel chains with built-in electric hearth systems. Flamerite sustains competitive positioning through R&D intensity in flame-effect technology. Kalfire anchors its presence in the premium architectural segment across Benelux markets.
Europe electric fireplace denotes an electrically powered heating appliance simulating flame visuals through LED projection or water-vapor mist, typically rated between 1.0 kW and 2.4 kW output, designed for zone heating and ambient enhancement in residential and commercial interiors. Wall-mounted units dominate volume due to space efficiency in dense urban dwellings, while freestanding models retain margin pools in rural and retrofit applications. Smartphone app control methods are capturing the fastest growth trajectory as consumers integrate heating into smart home ecosystems. Traditional design styles maintain steady demand in heritage property renovations across Southern Europe.
EU Ecodesign regulations and the F-Gas Regulation shape product efficiency benchmarks and refrigerant restrictions for hybrid heat-pump fireplace combinations. CE marking requirements under the EU Construction Products Regulation govern electrical safety and electromagnetic compatibility for all units sold in member states. Stakeholders must monitor forthcoming EU Green Deal building renovation targets that will redefine minimum energy performance standards for installed heating appliances.
Market Dynamics
The EU Green Deal building renovation targets are compressing replacement cycles for heating appliances across member states, forcing hospitality operators and residential developers toward Ecodesign-compliant electric alternatives ahead of legacy system end-of-life.
Growth Catalysts
- Ecodesign efficiency mandates:The EU Ecodesign Directive mandates minimum seasonal efficiency requirements for electric heating appliances, compelling hotel chains in France and Germany to retrofit properties with compliant electric hearth systems.
- Smart home ecosystem penetration:Smartphone app control methods are capturing demand as consumers in Milan and Amsterdam integrate zone heating into residential automation platforms.
- Urban density constraints:Wall-mounted electric units address space limitations in dense European city centers where traditional chimney infrastructure is impractical or prohibited.
Market Restraints
- Input cost volatility:Semiconductor and LED component prices fluctuate with Asian foundry capacity, compressing margins for manufacturers dependent on imported electronic assemblies.
- Substitution threat from heat pumps:Hybrid heat-pump systems eligible for national renovation subsidies in Germany and the Netherlands divert capital from purely electric decorative heating.
- CE marking complexity:The EU Construction Products Regulation requires electromagnetic compatibility testing that extends product launch timelines by four to six months for new entrants.
Strategic Opportunities
- Benelux premium architectural segment:High-end residential developments in Brussels and Rotterdam specify custom built-in electric hearths as design centerpieces with integrated media walls.
- Serviced apartment channel expansion:Institutional landlords across the Netherlands are standardizing electric fireplaces in build-to-rent portfolios to differentiate amenity packages.
- Water-vapor flame technology convergence:Mist-based flame simulation is converging with HVAC humidification systems, opening specification opportunities in wellness-focused hospitality projects.
Industry Challenges
- Electronics engineering talent scarcity:Firmware development for IoT-enabled heating controls competes with broader consumer electronics sectors for embedded systems specialists.
- Legacy electrical infrastructure compatibility:Pre-1990s residential wiring in Southern European heritage properties requires costly upgrades to support 2.4 kW rated units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Fireplace Market |
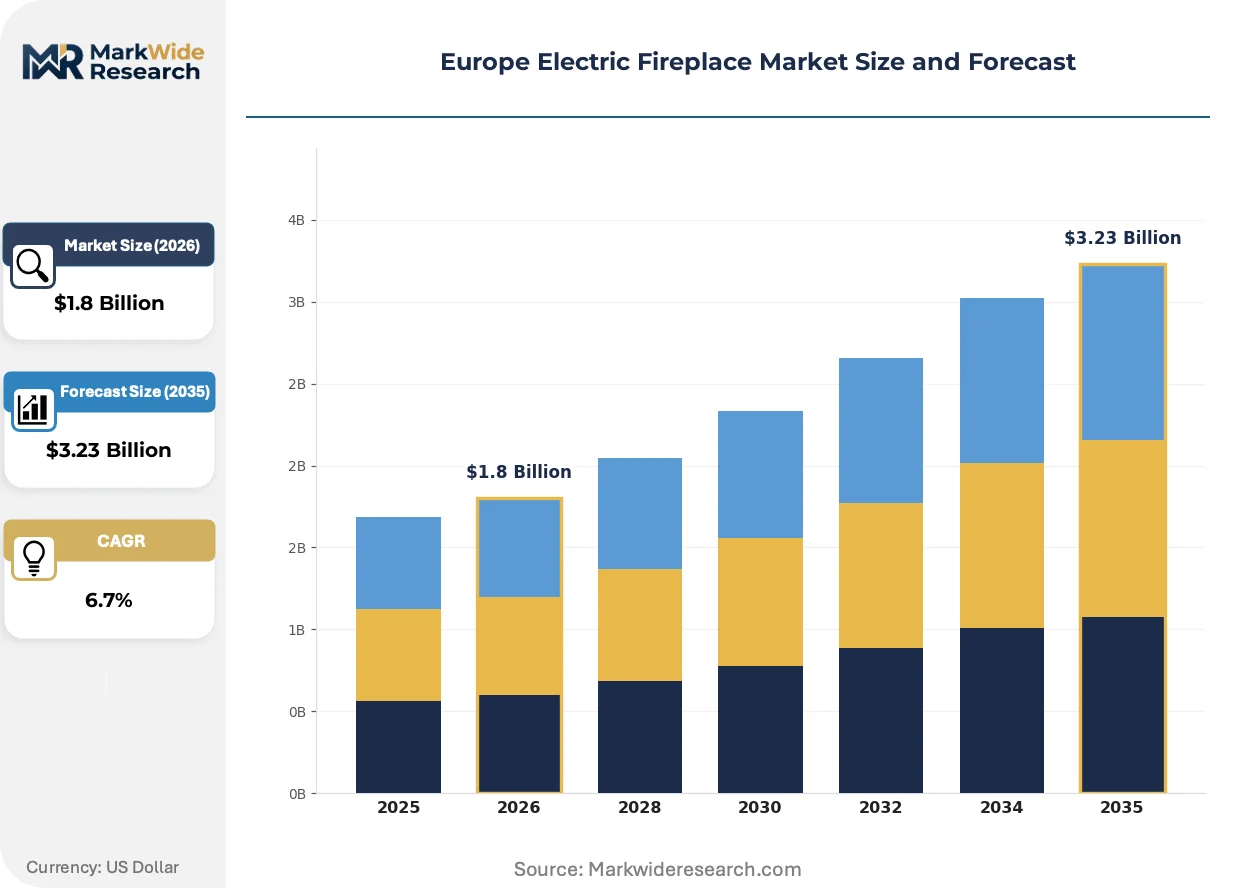
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Freestanding, Insert, Portable Design Style: Modern, Rustic, Traditional, Contemporary Control Method: Remote Control, Wall Switch, Smartphone App, Manual End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Modern Flames, Flamerite, Glen Dimplex Group, Be Modern Group, Focus Creation, Stovax Heating Group, Kalfire, DRU (Spartherm Group), Planika Sp. z o.o., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Fireplace Market Trends and Innovations
Product development is pivoting toward seamless environmental integration, with manufacturers embedding heating appliances into architectural finishes rather than treating them as standalone fixtures. This reorientation demands simultaneous advances in materials science, connectivity protocols, and installation methodologies.
LED projection systems with variable color temperature are converging with circadian lighting controls, enabling residential developers in Amsterdam to market electric hearths as wellness infrastructure. Boutique hotels in Copenhagen have adopted these systems to differentiate guest experiences without combustion-related maintenance liabilities. The technology is converging with building management platforms, compressing the traditional separation between decorative and functional heating procurement.
The F-Gas Regulation restricts refrigerant options for hybrid heat-pump fireplace combinations, forcing manufacturers to redesign thermal exchange architectures for units sold across EU member states. This constraint accelerates R&D investment in pure electric alternatives that bypass refrigerant compliance entirely. Spanish and Italian producers are responding fastest, reconfiguring product lines to eliminate hybrid configurations before the 2027 phase-down deadlines.
Specifiers in France now bundle electric hearth procurement with interior design contracts rather than HVAC tenders, shifting vendor relationships toward finish carpentry and millwork channels. This disintermediation of traditional heating distributors compresses margin pools for wholesalers while rewarding direct manufacturer-to-designer partnerships. The pattern is most visible in Paris and Lyon residential renovations, where architects specify flame-effect technology as aesthetic infrastructure rather than thermal equipment.
Europe Electric Fireplace Market Segmentation
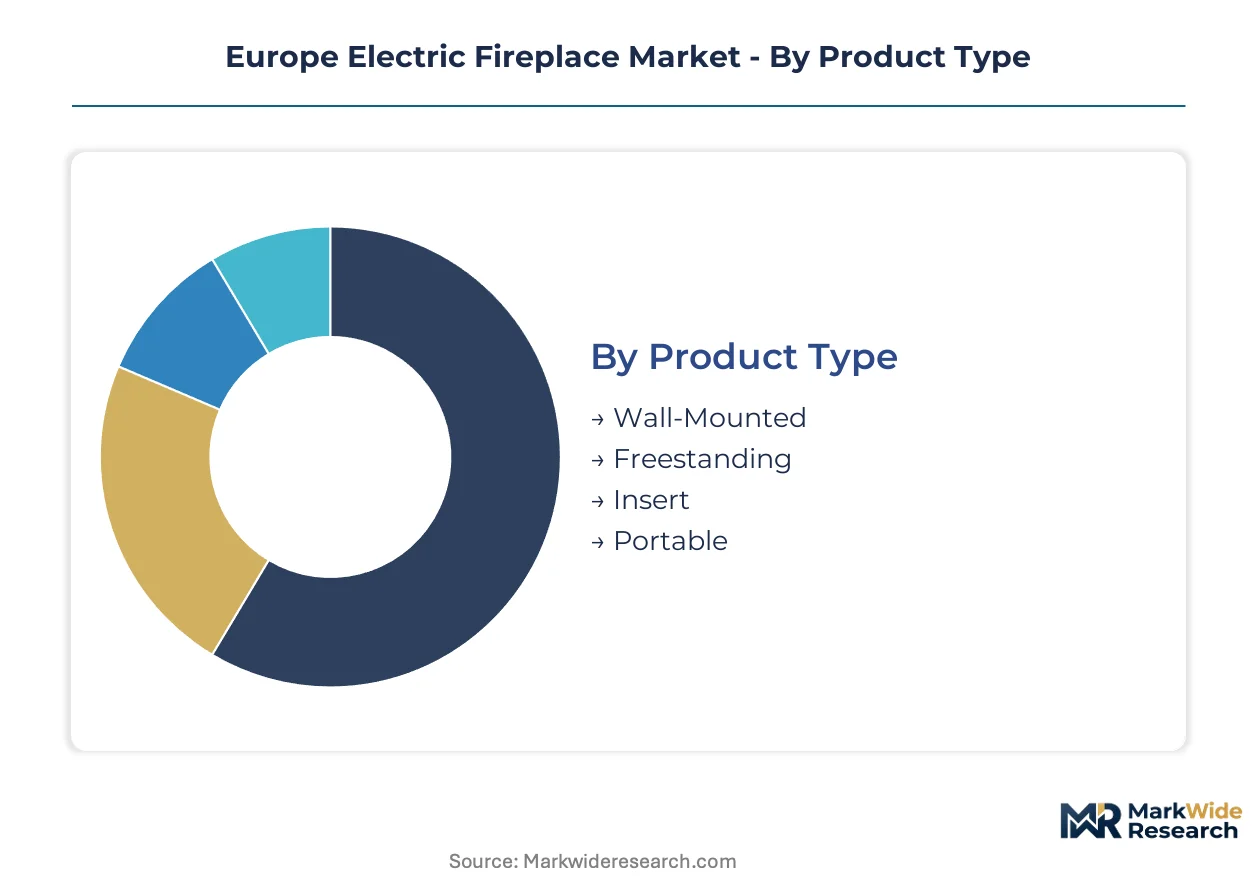
Electric fireplace procurement in Europe fragments across installation constraints, aesthetic preferences, and control sophistication. Specifiers in Milan and Amsterdam prioritize space-efficient wall-mounted units with smartphone integration, while heritage renovations in Southern Europe sustain demand for traditional forms. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditizes.
Product Type:
Volume concentrates in space-constrained urban formats, while premium margin pools accrue to built-in architectural solutions requiring specialized installation.
- Wall-Mounted:Units affix directly to vertical surfaces without floor footprint, typically 1.0-2.0 kW output. Demand concentrates in Paris and Amsterdam residential renovations where chimney infrastructure is prohibited or impractical, driven by EU Ecodesign efficiency mandates compressing replacement cycles in dense urban cores.
- Freestanding:Self-supporting units with integrated enclosures permit flexible placement. Rural properties across Bavaria and the French Alps specify these for retrofit applications where masonry hearths are cost-prohibitive to restore, though heat pump subsidies in Germany divert some capital from decorative electric alternatives.
- Insert:Designed for insertion into existing fireplace openings, converting dormant masonry to electric operation.
- Portable:Compact plug-in units with casters or handles for room-to-room mobility.
Today's leader: Wall-Mounted. Tomorrow's challenger: Insert.
Design Style:
Architectural specification channels now bundle aesthetic selection with interior design contracts rather than HVAC procurement, elevating finish quality as a competitive differentiator.
- Modern:Clean lines, minimal frames, and monochromatic finishes dominate Benelux new-build residential and Rotterdam commercial developments. Brussels architects specify these as media wall centerpieces, integrating LED flame projection with circadian lighting controls for wellness positioning.
- Traditional:Ornate mantelpieces, faux brick surrounds, and classical proportions align with heritage property renovations across Tuscany and Andalusia. Pre-1990s electrical infrastructure in these properties often requires costly upgrades to support higher-wattage units, constraining installation velocity.
- Rustic:Distressed wood, stone-look finishes, and farmhouse aesthetics target rural hospitality in the Scottish Highlands and Alpine regions.
- Contemporary:Hybrid aesthetics blending modern minimalism with warm material palettes, gaining traction in Copenhagen boutique hotels seeking differentiated guest experiences without combustion maintenance liabilities.
Modern commands specification share in new construction. Traditional maintains resilience in renovation pipelines.
Control Method:
Integration into residential automation platforms is climbing the fastest, though installation simplicity preserves demand for legacy interfaces in retrofit contexts.
- Smartphone App:WiFi or Bluetooth-enabled units integrate with Alexa, Google Home, and proprietary home automation platforms. Milan developers market these as wellness infrastructure with circadian-tuned flame color temperature, capturing demand from consumers seeking zone heating within smart home ecosystems.
- Remote Control:Handheld infrared or radio-frequency remotes remain standard in hospitality procurement across French and German hotel chains, where guest-facing simplicity outweighs integration sophistication.
- Wall Switch:Hardwired controls satisfy electrical code requirements in commercial installations and heritage properties where wireless reliability is questioned.
- Manual:Physical knobs or switches on the unit itself, specified for cost-sensitive applications and backup operation during connectivity failures.
Remote Control dominates hospitality standardization. Smartphone App is gaining share fastest in residential premium tiers.
End User:
Hospitality procurement is expanding most quickly among boutique hotels and serviced apartments, while residential volume sustains manufacturer scale.
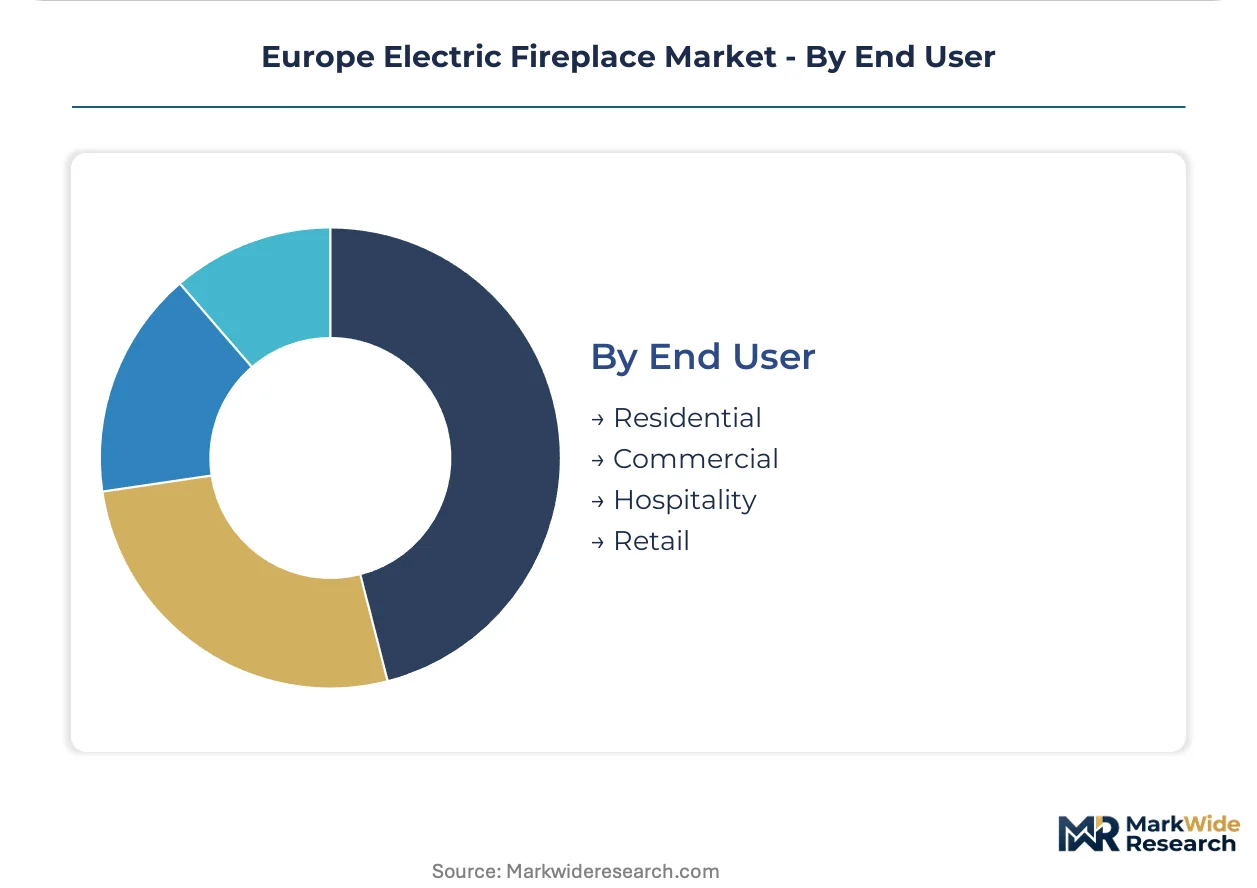
- Residential:Individual homeowners and tenants across urban renovations and rural retrofits constitute the volume base. Amsterdam and Lyon residential developers specify electric hearths as aesthetic infrastructure rather than thermal equipment, compressing traditional HVAC distributor margins.
- Hospitality:Boutique hotels, serviced apartments, and extended-stay properties in France, Germany, and the Netherlands are retrofitting with Ecodesign-compliant units ahead of legacy system end-of-life. Glen Dimplex supplies major European chains with built-in systems eliminating combustion maintenance.
- Commercial:Offices, restaurants, and retail spaces seeking ambient enhancement without ventilation requirements.
- Retail:Showrooms and customer-facing environments where flame simulation supports brand atmosphere.
Residential anchors volume scale. Hospitality is climbing fastest on Green Deal renovation deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting manufacturing footprints as compliance cost differentials widen across EU member states. The EU Green Deal renovation targets are compressing replacement cycles unevenly, creating procurement hotspots where Ecodesign enforcement tightens fastest.
Germany
Boutique hotel chains in Berlin and Munich are retrofitting properties with Ecodesign-compliant electric hearth systems ahead of legacy heating end-of-life. The Federal Emission Control Act (BImSchG) enforces strict efficiency benchmarks for installed heating appliances. Bavarian manufacturers supply built-in systems to hospitality operators seeking to eliminate combustion maintenance liabilities.
France
Paris and Lyon residential developers specify electric fireplaces as aesthetic infrastructure rather than thermal equipment, compressing traditional HVAC distributor margins. The RE2020 environmental regulation mandates low-carbon heating in new construction, favoring electric alternatives. Île-de-France architects bundle flame-effect technology with interior design contracts, disintermediating heating wholesalers.
Netherlands
Institutional landlords across Amsterdam and Rotterdam are standardizing electric hearths in build-to-rent portfolios to differentiate amenity packages. The Dutch Building Decree (Bouwbesluit) sets minimum energy performance standards that electric units satisfy more readily than gas alternatives. Randstad urban density constraints favor wall-mounted formats with smartphone integration.
Italy
Heritage property renovations across Tuscany and Lombardy sustain demand for traditional-design electric inserts, though pre-1990s electrical infrastructure requires costly upgrades. The Italian Technical Standards for Construction (NTC) govern electromagnetic compatibility for installed appliances. Milan developers market smart-enabled units as wellness infrastructure with circadian-tuned flame controls.
Belgium
High-end residential developments in Brussels specify custom built-in electric hearths as design centerpieces with integrated media walls. The Belgian Energy Performance of Buildings (EPB) regulations accelerate replacement of inefficient heating systems. Flemish architectural firms are converging electric fireplace specification with finish carpentry procurement channels.
Europe Electric Fireplace Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium architectural channels favoring direct designer relationships while hospitality procurement flows through established heating distributors. The vendor base concentrates around three strategic archetypes: scale-driven integrated manufacturers, R&D-intensive flame-technology specialists, and regional millwork-integrated fabricators. Capacity expansion and portfolio diversification toward smart-enabled controls represent the dominant competitive moves as connectivity becomes a baseline specification.
Within the scale-driven tier, Glen Dimplex Group and Be Modern Group occupy positions as volume suppliers to major European hospitality chains. Flamerite exemplifies the R&D-intensive archetype, anchoring competitive positioning through flame-effect technology investment. Kalfire sits within the premium architectural segment, serving Benelux markets where custom built-in specifications dominate. These three patterns—scale manufacturing, technology specialization, and premium integration—structure competitive rivalry across procurement channels.
| Leading Market Players |
|---|
| Modern Flames |
| Flamerite |
| Glen Dimplex Group |
| Be Modern Group |
| Focus Creation |
| Stovax Heating Group |
| Kalfire |
| DRU (Spartherm Group) |
| Planika Sp. z o.o. |
| Others |
Pricing and Supply Chain Analysis
Architectural premium-commodity bifurcation between custom built-in systems and mass-market wall-mounted units manifests in divergent margin structures and supply chain footprints across the European electric fireplace sector. CE marking complexity and Ecodesign compliance costs concentrate in premium tiers, while volume manufacturers absorb Asian component volatility through contract hedging.
Pricing Analysis
Distributor margin compression in traditional HVAC channels is accelerating direct manufacturer-to-designer partnerships in France and Belgium. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and flame-technology sophistication. Pricing pressure stems from semiconductor and LED input cost volatility tied to Asian foundry capacity constraints. Hospitality procurement teams exhibit lowest price sensitivity due to maintenance liability elimination, while residential retrofit buyers in Southern Europe prioritize economy tiers constrained by pre-1990s electrical upgrade costs.
Supply Chain Analysis
Electronics engineering talent scarcity in Germany and the Netherlands constrains firmware development capacity for IoT-enabled heating controls. Manufacturing concentration centers on Bavaria, Flanders, and Northern Italy for final assembly, with LED modules and semiconductor assemblies drawing from Taiwan and South Korea. Single-source vulnerability in water-vapor flame simulation components creates exposure to specialized supplier bottlenecks. Distribution runs through finish carpentry and millwork channels in premium architectural segments, while hospitality procurement maintains traditional heating distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between German Ecodesign enforcement and Italian manufacturing cost bases offers margin capture opportunities for operators with cross-border compliance capabilities. The Federal Emission Control Act's efficiency benchmarks create procurement urgency that Southern European producers can exploit through rapid product reconfiguration.
For Market Incumbents: Lock in specification relationships with Paris and Brussels architectural firms before finish carpentry channels fully disintermediate traditional heating distributors. Capacity addition in Flanders addresses Benelux premium demand while backward integration into LED flame-projection modules mitigates Asian component volatility. Hybrid heat-pump subsidy competition from German national renovation programs threatens pure electric decorative heating margins, requiring wellness-positioning differentiation through circadian lighting convergence. For New Entrants and Emerging Players: Serviced apartment institutional landlords in the Netherlands represent an underserved buyer archetype with standardized build-to-renter amenity procurement cycles. Water-vapor flame technology convergence with HVAC humidification systems opens specification opportunities in wellness-focused hospitality projects across Copenhagen and Amsterdam. Direct designer partnerships in Milan residential developments bypass established HVAC distributor gatekeeping. For Investors and Strategic Acquirers: Consolidation pressure builds where R&D-intensive flame-technology specialists face scale disadvantages against integrated manufacturers with hospitality chain supply contracts. Long-term viability favors vendors with smart-home ecosystem certification and CE marking regulatory expertise. Acquisition target archetypes include regional millwork-integrated fabricators with established Benelux architectural relationships. Watch for F-Gas Regulation phase-down deadlines accelerating pure electric product line reconfiguration as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Ecosystem Certification | Alexa and Google Home integration opens specification channels in Amsterdam and Milan residential automation platforms. |
| Water-Vapor Flame Technology Convergence | Mist-based simulation integration with HVAC humidification captures wellness hospitality procurement in Copenhagen boutique hotels. |
| Direct Designer Partnership Development | Paris and Lyon interior design contract bundling disintermediates traditional HVAC distributor margin pools. |
| CE Marking Regulatory Expertise Investment | Electromagnetic compatibility testing acceleration compresses four-to-six month product launch timelines for new entrants. |
| Benelux Premium Architectural Channel Expansion | Brussels and Rotterdam custom built-in specifications reward finish carpentry integration capabilities. |
Research Methodology
Bottom-up residential and hospitality procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with product development executives at heating appliance manufacturers, regulatory affairs specialists, hospitality procurement directors, interior design firm principals, and electrical contractor networks were validated against secondary sources including EU Ecodesign Directive filings, CE marking databases, F-Gas Regulation compliance disclosures, and national building renovation subsidy program documentation. Triangulation across these sources ensures segmentation accuracy.
Input-output matrix framing connects flame-technology R&D expenditure, smart control integration rates, and regional regulatory enforcement intensity to volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, design style, control method, and end-user category, with installation constraint density and heritage property renovation pipeline as industry-specific forecast inputs. CAGRs were derived from replacement cycle compression analysis under EU Green Deal building renovation targets.
Inputs from hospitality procurement databases and architectural specification registries were available through the study window; gaps in real-time smart home platform integration adoption rates introduce uncertainty bands around connectivity-enabled segment forecasts. Forecasts reflect documented assumptions regarding Ecodesign enforcement timelines and F-Gas Regulation phase-down adherence. Material deviation in German heat pump subsidy allocation or Italian electrical infrastructure upgrade velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
Kids Desk Lamp Market