
 North America Ceiling Fan Market | 2026-2036
North America Ceiling Fan Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ceiling Fan Market Intelligence
ENERGY STAR certification is unwinding competitive access in the North America ceiling fan landscape, filtering out smaller importers and elevating established manufacturers. Hunter Fan leverages its century-old brand equity and deep retail partnerships to sustain shelf dominance across home improvement channels. Big Ass Fans anchors the industrial segment with engineered air-movement systems for warehousing and agricultural facilities. MacroAir specializes in high-volume low-speed (HVLS) architectures that differentiate on energy efficiency metrics in commercial installs.
A ceiling fan is a mechanical air-circulation device comprising an electric motor, rotor assembly, and multiple aerodynamically profiled blades, typically spanning 29 to 72 inches in diameter, designed to enhance thermal comfort through convective heat transfer rather than direct air conditioning. The primary purpose spans residential climate mitigation, commercial ventilation support, and industrial destratification in spaces with high ceilings. Energy-efficient fans and smart fans represent the fastest-expanding product categories as Bluetooth connectivity and DC motor technology reshape consumer expectations and utility rebate eligibility. Residential use remains the volume anchor, while industrial spaces command premium pricing due to durability specifications and installation complexity.
The US Department of Energy (DOE) appliance efficiency standards and California's Title 24 building code collectively shape motor efficiency minimums and blade performance testing protocols across the region. Health Canada and the US Environmental Protection Agency (EPA) administer parallel ENERGY STAR qualification pathways that manufacturers must navigate for cross-border market access. Stakeholders should monitor emerging amendments to federal standby power regulations and state-level electrification incentives that will determine which motor technologies qualify for preferential procurement.
Market Dynamics
DC motor technology is compressing incumbent AC motor architectures as Title 24 and DOE efficiency standards harden minimum performance thresholds across North American jurisdictions, forcing wholesale product portfolio refreshes.
Growth Catalysts
- Title 24 Building Standards:California's energy code mandates minimum efficacy thresholds that only DC motor platforms satisfy, creating regulatory pull for premium product lines in new residential construction.
- Cooling Degree Day Concentration:Texas, Florida, and California generate sustained replacement cycles and new-install demand as housing permits and extreme heat events cluster in these states.
- Smart Home Integration:Bluetooth mesh and Wi-Fi connectivity protocols enable utility rebate eligibility and consumer preference capture through programmable scheduling and voice control compatibility.
Market Restraints
- Copper and Rare Earth Magnet Volatility:DC motor stators depend on neodymium and copper windings subject to mining concentration and export restriction risk.
- Guangdong Supply Concentration:Motor controller PCBs and blade molding capacity cluster in Pearl River Delta facilities, exposing North American brands to port congestion and tariff uncertainty.
- Incumbent AC Motor Replacement Inertia:Existing installed base of functional AC units in rental housing and commercial retrofits delays upgrade cycles despite efficiency gains.
Strategic Opportunities
- Mexico Manufacturing Expansion:Nearshoring motor assembly and blade fabrication to Baja California and Nuevo León reduces tariff exposure and shipping lead times for US distribution.
- Agricultural Destratification:Dairy barns and poultry facilities in Wisconsin and Iowa represent underpenetrated HVLS applications where temperature uniformity drives yield metrics.
- Inflation Reduction Act Electrification Incentives:Federal rebates for efficient home appliances create price-point compression that accelerates DC motor adoption in mass-market retail channels.
Industry Challenges
- DC Motor Control Firmware Talent Scarcity:Embedded systems engineers capable of optimizing brushless motor algorithms command premium compensation and lengthen product development timelines.
- ENERGY STAR Certification Backlogs:EPA testing facility capacity constraints and documentation requirements delay product launches by six to nine months, misaligning with seasonal demand peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ceiling Fan Market |
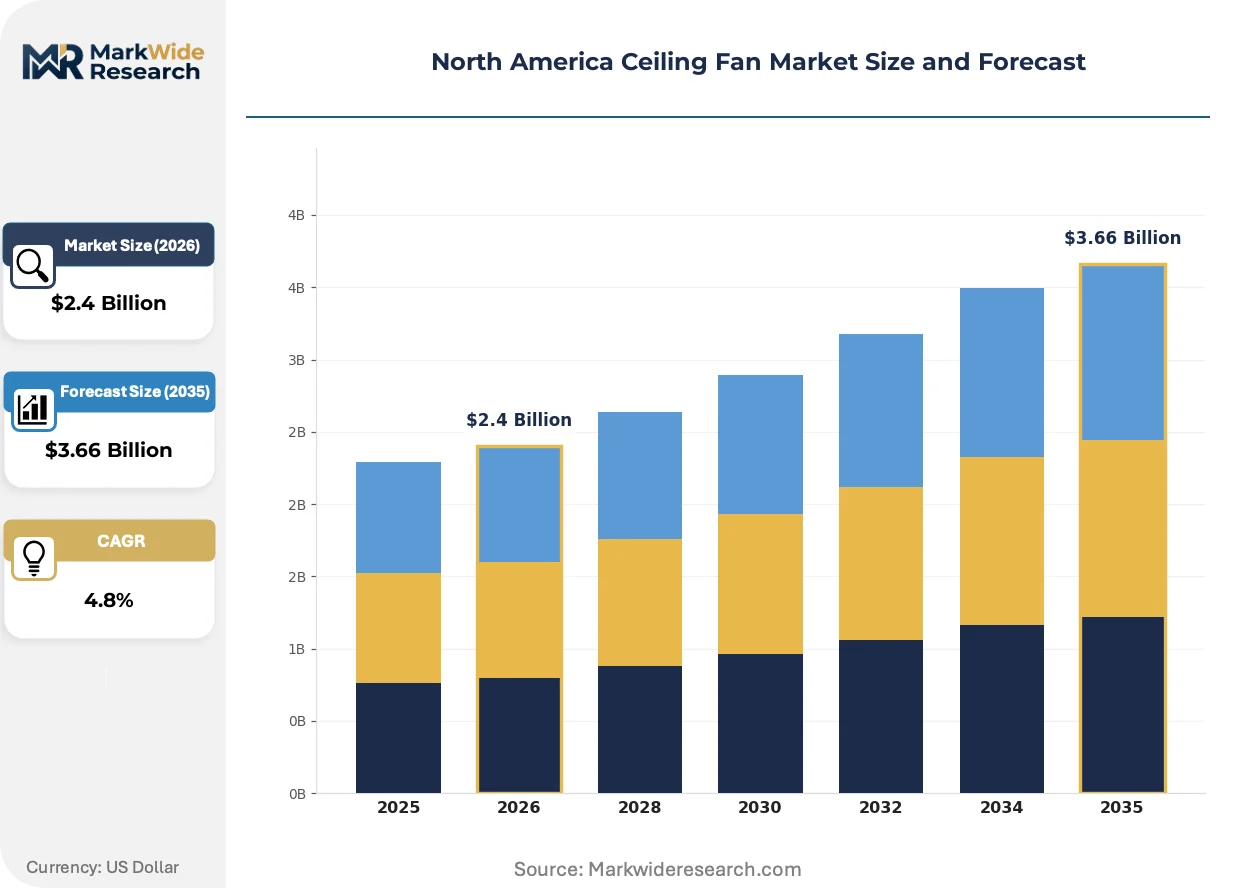
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fans, Energy-Efficient Fans, Smart Fans, Decorative Fans Application: Residential Use, Commercial Structures, Industrial Spaces, Outdoor Settings Technology: DC Motor, AC Motor, Bluetooth Connectivity, Remote Control Distribution Channel: Online Retailers, Home Improvement Stores, Specialty Stores, Direct Sales |
| Companies Covered | MacroAir, Rite-Hite, Hunter Fan, Refresh Fans, Envira-North, Big Ass Fans, Humongous Fan, Epic Fan, Patterson Fan, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ceiling Fan Market Strategic Shifts & Innovations
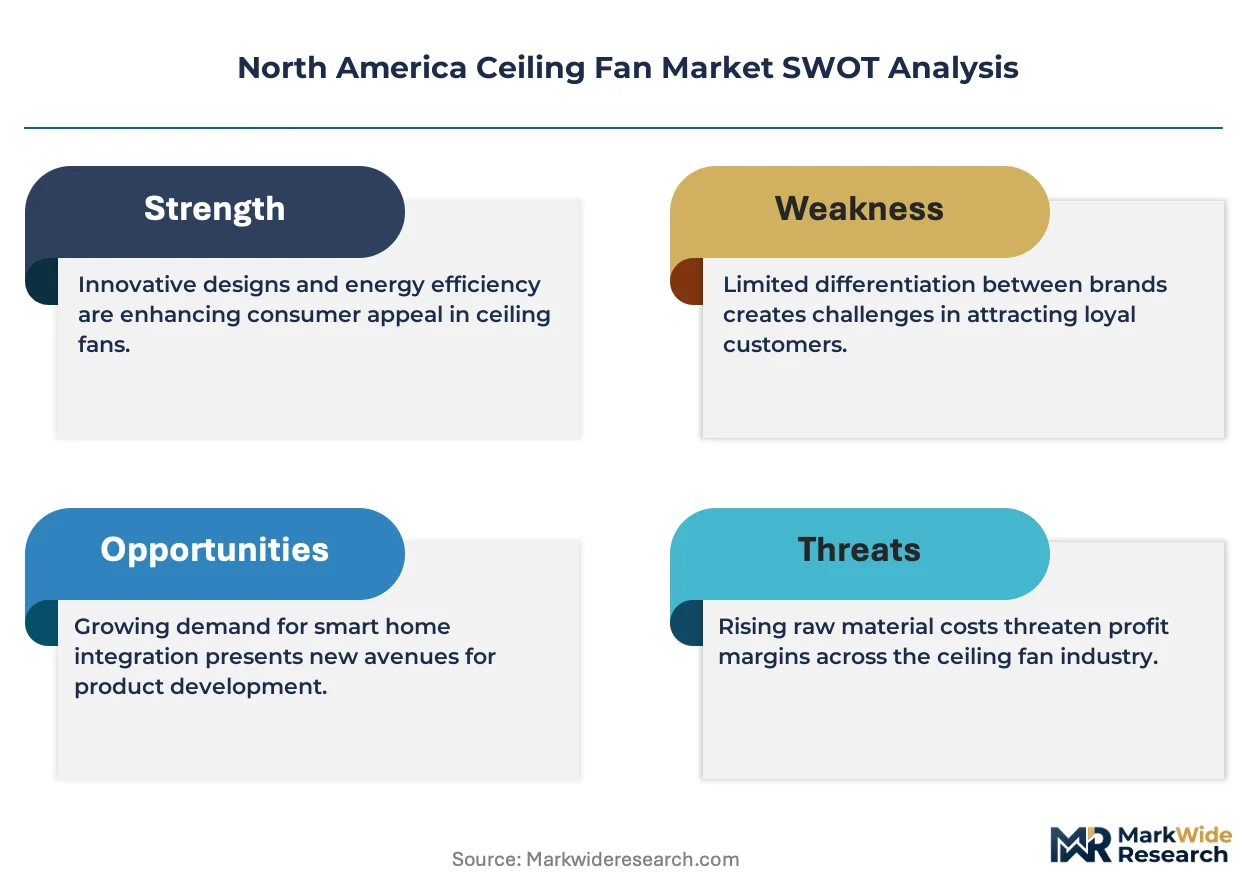
Product architecture is splitting along efficiency-performance lines as connectivity modules and aerodynamic blade engineering become primary differentiation vectors rather than decorative styling.
Brushless DC motor platforms is bifurcating the competitive landscape between premium connected systems and basic AC alternatives. Residential builders in Arizona and Nevada are specifying DC models as standard in mid-tier subdivisions. This technology compression is squeezing AC-only manufacturers into price-driven commodity segments while elevating DC-capable suppliers into rebate-eligible procurement channels.
DOE standby power regulations are tightening phantom-load thresholds for ceiling fans with integrated lighting and control modules. Manufacturers must redesign power supplies and firmware sleep states to meet sub-one-watt requirements. The residential replacement segment faces the steepest compliance costs as legacy inventory must clear distribution before new standards take effect.
Home improvement retailers are consolidating shelf space around private-label and exclusive-brand arrangements, displacing traditional national brand dominance. Lowe's and Home Depot are expanding house-brand DC motor offerings with direct sourcing from Asian contract manufacturers. This channel consolidation is most pronounced in Texas and Florida markets where new construction volume justifies dedicated SKU rationalization programs.
North America Ceiling Fan Market Segmentation
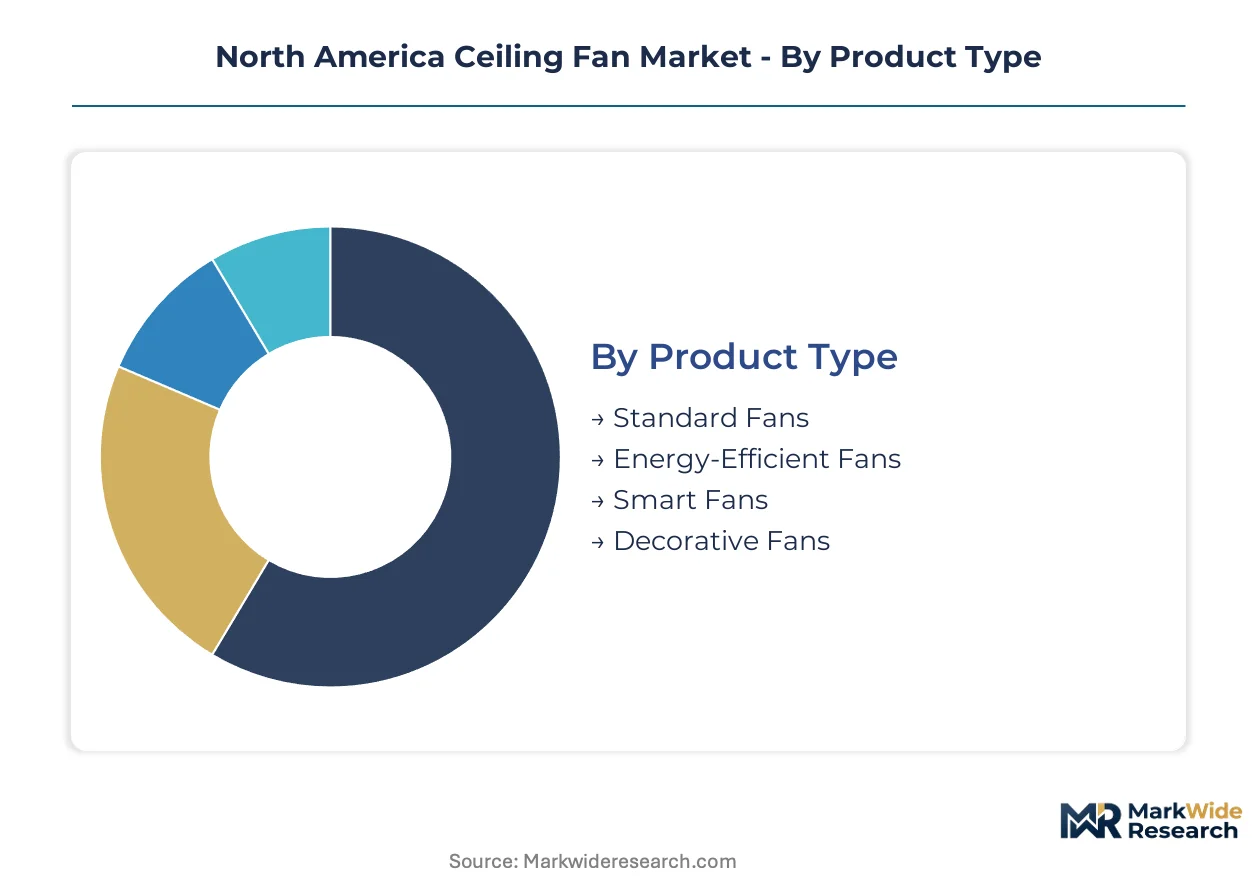
Ceiling fan segmentation in North America follows divergent regulatory pathways across product tiers, with ENERGY STAR thresholds and Title 24 compliance creating sharp performance boundaries that reshape channel economics and manufacturer portfolios.
Product Type:
EPA certification tiers and California building codes partition the product landscape into rebate-eligible premium tiers and baseline alternatives.
- Standard Fans:AC motor platforms dominate this tier with fixed-speed operation and basic pull-chain controls. Rental housing in Texas and Florida sustains volume as landlords prioritize upfront cost over operating efficiency.
- Energy-Efficient Fans:DC motor architectures with brushless stators deliver 70% wattage reduction versus AC equivalents. New residential construction in California and Arizona specifies these as code-compliant defaults, pulling manufacturers toward DOE testing protocols.
- Smart Fans:Wi-Fi and Bluetooth mesh connectivity enable utility demand-response programs and voice assistant integration.
- Decorative Fans:Ornate blade finishes and integrated lighting assemblies target renovation markets in historic districts and upscale subdivisions.
Energy-efficient fans handle the majority of throughput; smart fans are the fastest mover on share.
Application:
Installation height and air volume requirements create distinct specification regimes across building categories.
- Residential Use:Single-family homes and multi-family units drive replacement cycles and new construction attachment rates. Cooling degree day concentration in Sun Belt states sustains year-round demand without seasonal collapse.
- Commercial Structures:Office buildings, retail spaces, and hospitality venues specify HVLS and standard ceiling mount systems based on ceiling height and occupancy density. Energy rebate programs in Illinois and New York accelerate retrofit specifications.
- Industrial Spaces:Manufacturing floors and warehousing facilities demand corrosion-resistant housings and sealed bearings for continuous operation.
- Outdoor Settings:Wet-rated and damp-rated enclosures serve patios, verandas, and agricultural outbuildings across humid Gulf Coast and arid Southwest climates.
Residential use anchors absolute volume; industrial spaces command the steepest expansion trajectory on margin contribution.
Technology:
Motor topology and control interfaces determine rebate eligibility and installation labor economics.
- DC Motor:Electronically commutated brushless designs with permanent magnet rotors achieve 30-50 watt draw versus 75-90 watts for AC equivalents. Title 24 efficacy mandates in California and emerging codes in Washington and Colorado force specification migration.
- AC Motor:Split-capacitor and shaded-pole designs persist in replacement markets and price-sensitive new construction. Existing installed base in Midwest rental housing delays upgrade cycles despite higher operating costs.
- Bluetooth Connectivity:Mesh networking protocols enable group control and utility-integrated demand response without Wi-Fi infrastructure dependencies.
- Remote Control:Radio frequency and infrared handheld units address retrofit installations where wall switch wiring is absent or inaccessible.
AC motor platforms still handle the majority of installed base throughput; DC motor systems are climbing the fastest on new specification share.
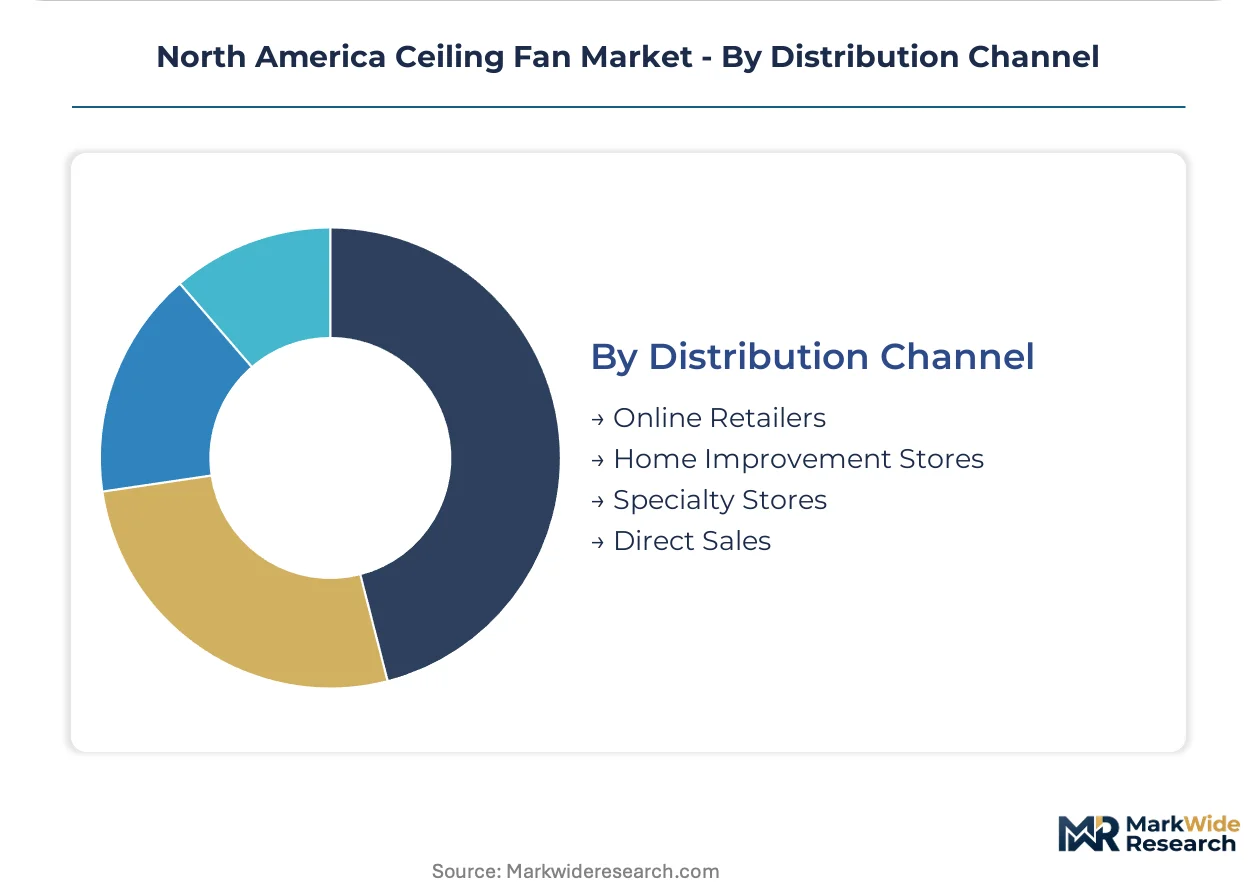
Distribution Channel:
Channel concentration in home improvement retail shapes brand access and margin structure across geographic markets.
- Online Retailers:Amazon and direct-to-consumer platforms capture replacement demand and contractor bulk purchasing with SKU breadth unavailable in physical retail. Shipping logistics for oversized blade assemblies constrain category penetration.
- Home Improvement Stores:Home Depot and Lowe's control new construction specification through builder program relationships and exclusive brand arrangements. Texas and Florida market volume justifies dedicated DC motor SKU rationalization.
- Specialty Stores:Lighting showrooms and HVAC distributors serve custom residential and commercial specification with design consultation and installation coordination.
- Direct Sales:Manufacturer-owned channels and contractor programs bypass retail markup for large-scale commercial and agricultural deployments.
Home improvement stores handle the majority of throughput; online retailers are gaining share fastest on replacement cycle capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors North American ceiling fan distribution, handling inbound motor assemblies and blade components from Asian manufacturing centers before rail dispersal across the Sun Belt.
United States
Texas and Florida housing permits drive replacement cycles and new construction attachment rates. The DOE appliance efficiency standards and California's Title 24 building code shape motor efficiency minimums across jurisdictions. Dallas-Fort Worth and Houston concentrate builder-grade procurement through home improvement retail channels.
California
Cooling degree day concentration and electrification incentives sustain premium DC motor demand in residential construction. Title 24 efficacy mandates force specification migration toward brushless motor platforms. The Inland Empire and Central Valley housing markets anchor code-compliant installation volume.
Texas
Extreme heat events and sustained population growth generate year-round ceiling fan demand without seasonal collapse. ERCOT grid reliability concerns accelerate interest in low-wattage DC motor systems. Houston and Austin metro areas concentrate new construction specification through national builder programs.
Florida
Humid subtropical climate sustains outdoor-rated and damp-rated fan demand for patios and verandas. Miami-Dade and Tampa Bay housing markets drive replacement velocity in coastal construction. The state building code alignment with IECC standards shapes wind-load and efficiency specifications.
Canada
Health Canada and EPA parallel ENERGY STAR qualification pathways govern cross-border product access. Ontario and Quebec residential construction maintains steady demand through energy rebate programs. The Greater Toronto Area concentrates distribution infrastructure for national retail channel supply.
North America Ceiling Fan Market Key Industry Players
Listed leaders compete with private specialists across brand equity and channel access dimensions. The vendor base organizes around three tiers: century-old heritage brands with retail shelf dominance, engineered air-movement specialists serving commercial and industrial verticals, and private-label fabricators supplying home improvement house brands. Consolidation pressure concentrates in the mid-market as rebate eligibility requirements filter out smaller importers. Strategic moves center on DC motor platform refreshes and exclusive retail arrangements.
Within the heritage brand tier, Hunter Fan Company occupies a position exemplifying century-old retail partnerships and consumer recognition. Among engineered air-movement specialists, Big Ass Fans and MacroAir represent the industrial and HVLS archetypes respectively, anchoring premium specification in warehousing and agricultural facilities. These three entities illustrate the competitive structure: one legacy consumer brand, one industrial-scale fabricator, and one efficiency-focused technology specialist.
| Leading Market Players |
|---|
| MacroAir |
| Rite-Hite |
| Hunter Fan |
| Refresh Fans |
| Envira-North |
| Big Ass Fans |
| Humongous Fan |
| Epic Fan |
| Patterson Fan |
| Others |
Cost & Logistics Intelligence
DC motor controller sourcing from Taiwan and South Korea is displacing legacy AC component procurement from mainland China, simultaneously compressing landed costs for premium tiers while exposing brands to semiconductor foundry allocation cycles and memory pricing volatility. This substitution dynamic reshapes how manufacturers balance inventory carrying costs against tariff exposure when configuring North American distribution networks.
Pricing Analysis
Volume-discount tiering structures separate ENERGY STAR-certified DC platforms from basic AC alternatives, with certification grade and motor efficiency tier serving as primary price differentiation drivers. Pricing pressure stems from home improvement retailers consolidating shelf space around private-label DC offerings sourced directly from Asian contract manufacturers. Residential builders in Texas and Florida exhibit lowest price sensitivity due to rebate-eligible procurement programs, while Midwest rental housing operators remain most cost-conscious.
Supply Chain Analysis
Just-in-time inventory strategies dominate motor assembly and blade fabrication, though neodymium magnet and copper winding stockpiling has intensified following rare earth export restriction episodes. Manufacturing concentrates in China, Taiwan, and Vietnam, with controller PCBs drawing from Taiwanese semiconductor foundries and blade molding anchored in Guangdong facilities. Tariff exposure on Chinese-origin components constitutes the primary structural risk. Distribution runs through the Port of Los Angeles-Long Beach complex before rail dispersal to Dallas-Fort Worth and Houston distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Title 24 efficacy mandates and DOE standby power regulations are fragmenting specification requirements across jurisdictions, creating niche opportunities for regionally specialized manufacturers and compliance-focused service providers.
For Market Incumbents: Compound brand equity through exclusive retail arrangements with Home Depot and Lowe's builder programs, locking out challenger DC motor platforms. Invest in ENERGY STAR certification pipeline capacity to clear six-to-nine-month EPA testing backlogs before seasonal demand peaks. Vertical integration into Mexico assembly operations reduces tariff exposure while compressing lead times for Sun Belt construction cycles.
For New Entrants and Emerging Players: Firmware customization services for brushless DC motor optimization represent a service-layer gap where incumbents under-serve agricultural and industrial destratification applications. Target dairy barn and poultry facility operators in Wisconsin and Iowa with HVLS specification support bundled with installation coordination. Pursue direct-to-contractor digital channels bypassing retail markup capture.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed HVAC component specialists holding captive motor controller capabilities but lacking blade fabrication or North American distribution infrastructure. Five-to-ten-year viability hinges on DC motor platform refresh execution and Title 24 jurisdiction expansion beyond California. Monitor Washington and Colorado building code amendments as inflection indicators for regional specification pull-through.
| Strategic Initiative | Industry Significance |
|---|---|
| DC Motor Platform Refresh | Title 24 compliance unlocks California new construction procurement channels for premium tiers. |
| Mexico Manufacturing Expansion | Baja California assembly reduces tariff exposure and shipping lead times for US distribution. |
| Smart Home Integration Partnership | Bluetooth mesh certification enables utility demand-response program eligibility and rebate capture. |
| Agricultural Destratification Entry | HVLS specification in dairy and poultry facilities opens underpenetrated Midwest volume. |
| Private-Label Supply Agreement | Exclusive house-brand arrangements with Lowe's and Home Depot secure shelf space in Texas and Florida. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with residential construction procurement managers, HVAC contractor business owners, home improvement retail category buyers, motor controller firmware engineers, and agricultural facility operations directors. Secondary validation drew from DOE appliance efficiency standard filings, EPA ENERGY STAR qualification databases, California Energy Commission Title 24 compliance documentation, and US Census Bureau housing permit data. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, technology, and distribution channel dimensions.
Across the analysis window, forecasts model residential versus commercial versus industrial application splits, DC versus AC motor technology migration, and online versus physical retail channel evolution. CAGRs derive from regression analysis of housing permit velocity, cooling degree day concentration, and regulatory compliance timeline assumptions. Industry-specific inputs include Title 24 jurisdiction expansion probability and Inflation Reduction Act electrification incentive uptake rates.
Underlying assumptions cover steady copper and rare earth magnet supply continuity, with deviation risk concentrated in Guangdong port congestion episodes and EPA testing facility capacity constraints. Forecasts reflect these documented assumptions. Revision becomes warranted when DC motor cost parity against AC alternatives accelerates beyond modeled thresholds or when federal standby power regulations tighten phantom-load requirements ahead of anticipated timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Kids Desk Lamp Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
Chandelier Market