
 Landscape Lighting Market | 2026-2036
Landscape Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Landscape Lighting Market Outlook
Market Context
China is rewriting capacity dynamics in landscape lighting through expanded LED module and driver manufacturing clusters in Guangdong and Zhejiang provinces. Signify NV leverages its vertically integrated LED supply chain to sustain cost leadership across European and North American specification channels. Acuity Brands Inc. anchors its position through deep distribution control in the North American professional contractor segment. Kichler Lighting LLC specializes in premium residential-grade fixtures with extended corrosion-resistant finishes for coastal environments.
Technical Definition and Segment Structure
Landscape lighting encompasses permanently installed outdoor luminaires designed to illuminate gardens, pathways, architectural facades, and terrain features, typically operating at 12V–120V with IP65 or higher ingress protection ratings to withstand moisture, dust, and temperature cycling. Its primary commercial purpose is to extend functional and aesthetic use of exterior spaces after dark while enhancing safety, security, and property valuation. Path lights and spot lights together occupy the dominant product positions, though solar-powered configurations are recording the fastest expansion as photovoltaic efficiency gains and lithium-ion cell cost reductions reshape the power source landscape. The commercial application segment commands premium margin pools due to specification complexity and long-term maintenance contracts, while residential demand remains volume-driven through big-box and e-commerce channels.
Regulatory Framework and Outlook
China's MIIT enforces GB standards for luminaire efficacy and electromagnetic compatibility, while the EPA and DOE regulate outdoor fixture energy performance in the United States through ENERGY STAR qualification and Dark Sky compliance programs. The EU Green Deal and F-Gas Regulation are progressively restricting mercury-containing lamp imports, accelerating LED retrofit cycles across European municipal procurement. Stakeholders must monitor evolving photocell and smart-control interoperability standards, as connected landscape lighting systems become the default specification for large-scale commercial and public space deployments.
Market Dynamics
China's tightening GB efficiency standards for outdoor luminaires are compressing fixture margins while accelerating LED retrofit cycles across municipal and commercial procurement channels worldwide.
Growth Catalysts
- Solar photovoltaic integration:Declining lithium-ion cell costs and improved PV conversion efficiency are enabling off-grid landscape lighting deployments in remote hospitality and residential developments across the Middle East.
- Smart city infrastructure mandates:The EU Green Deal's energy performance requirements are forcing municipal procurement toward connected, photocell-enabled systems with remote diagnostics and adaptive dimming protocols.
- Extended outdoor hospitality hours:Resort developers in the United Arab Emirates are expanding illumination budgets to activate terraces, pools, and garden venues after sunset, driving specification-grade fixture demand.
Market Restraints
- Aluminum and copper price volatility:Raw material cost swings for die-cast housings and electrical conductors are squeezing fixture manufacturers' gross margins and complicating long-term project bidding.
- Guangdong-Zhejiang supply concentration:Overreliance on China's LED module and driver manufacturing clusters creates vulnerability to regional power rationing, logistics disruptions, and trade policy friction.
- Mercury lamp phase-out friction:The EU F-Gas Regulation's restrictions on legacy discharge lamp imports are stranding existing fixture inventories and accelerating premature capital expenditure cycles for European contractors.
Strategic Opportunities
- Underpenetrated Indian municipal markets:India's Smart Cities Mission and urban beautification programs are opening specification-grade procurement channels previously dominated by unorganized local assemblers.
- Dark Sky compliance premiums:The International Dark-Sky Association's certification program is creating price-insensitive demand for full-cutoff, shielded fixtures in ecotourism and astronomical observation zones.
- LiDAR-integrated adaptive lighting:Convergence of motion sensing with pedestrian detection algorithms is enabling demand-responsive illumination that cuts energy consumption in public parks and university campuses.
Industry Challenges
- Photocell interoperability gaps:Proprietary wireless protocols from competing controls vendors are fragmenting system integration and inflating commissioning costs for multi-site commercial deployments.
- IP65+ sealing expertise shortage:Qualified technicians for gasket specification, thermal management, and ingress protection validation remain scarce in North American electrical contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Landscape Lighting Market |
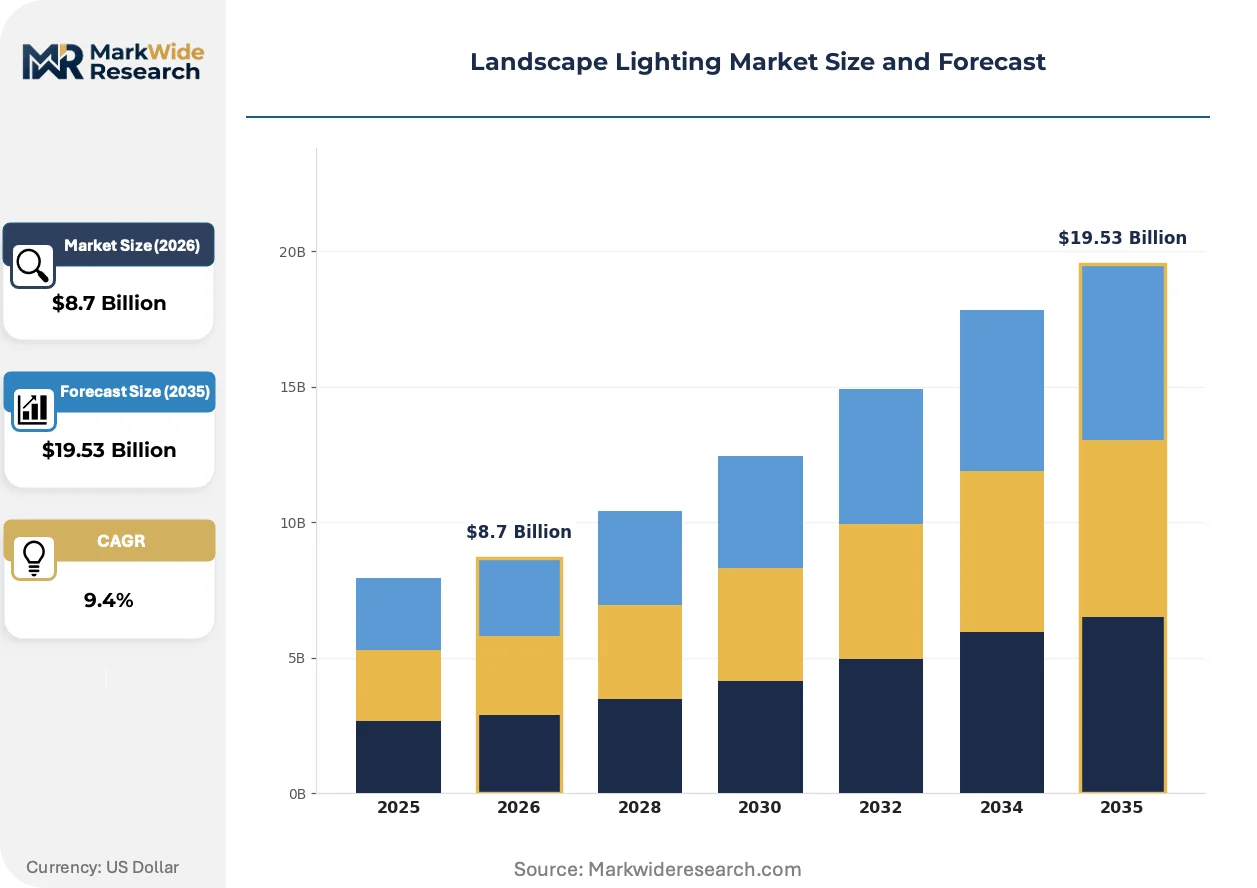
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Path Lights, Spot Lights, Flood Lights, Deck Lights Power Source: Solar, Hardwired, Battery-Operated, Low Voltage Material: Metal, Plastic, Glass, Wood Application: Residential, Commercial, Public Spaces, Recreational Areas |
| Companies Covered | Acuity Brands Inc., Signify NV, Kichler Lighting LLC, Hubbell Inc., Eaton Corp. Plc, ams OSRAM AG, BEGA Gantenbrink-Leuchten KG, FX Luminaire, RAB Lighting Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Landscape Lighting Market Strategic Shifts
Photovoltaic-battery systems are collapsing the installed cost gap between grid-tied and off-grid landscape lighting, while connected controls and circular design mandates rewrite procurement specifications.
DC-native LED engines paired with lithium iron phosphate battery packs are collapsing the economic viability of traditional 120V trenching and transformer infrastructure for pathway and accent lighting. Estate developers and golf course operators are specifying solar-dominant systems for new construction, eliminating electrical contractor dependencies and compressing project timelines from weeks to days. This shift is collapsing revenue pools for underground cable and copper conductor suppliers while expanding fixture OEM service contracts to cover battery replacement cycles.
The EU F-Gas Regulation's progressive mercury lamp restrictions are accelerating LED retrofit mandates across European municipal procurement frameworks. France's ANSM and Germany's KBA have aligned national implementation timelines, forcing inventory liquidation of high-pressure sodium and metal halide stocks. Commercial landscape maintenance contractors are responding by consolidating supplier relationships to secure extended warranty terms on solid-state replacements.
Specification-grade buyers are unbundling installation from long-term maintenance, forcing fixture OEMs to compete on lifecycle service contracts rather than upfront hardware pricing. North American hospitality developers now separate capital expenditure bids from ten-year relamping and control system upgrade agreements. This bifurcation is most visible in California and Florida coastal markets where salt-air corrosion drives accelerated fixture degradation and demands predictive replacement scheduling.
Landscape Lighting Market Segmentation
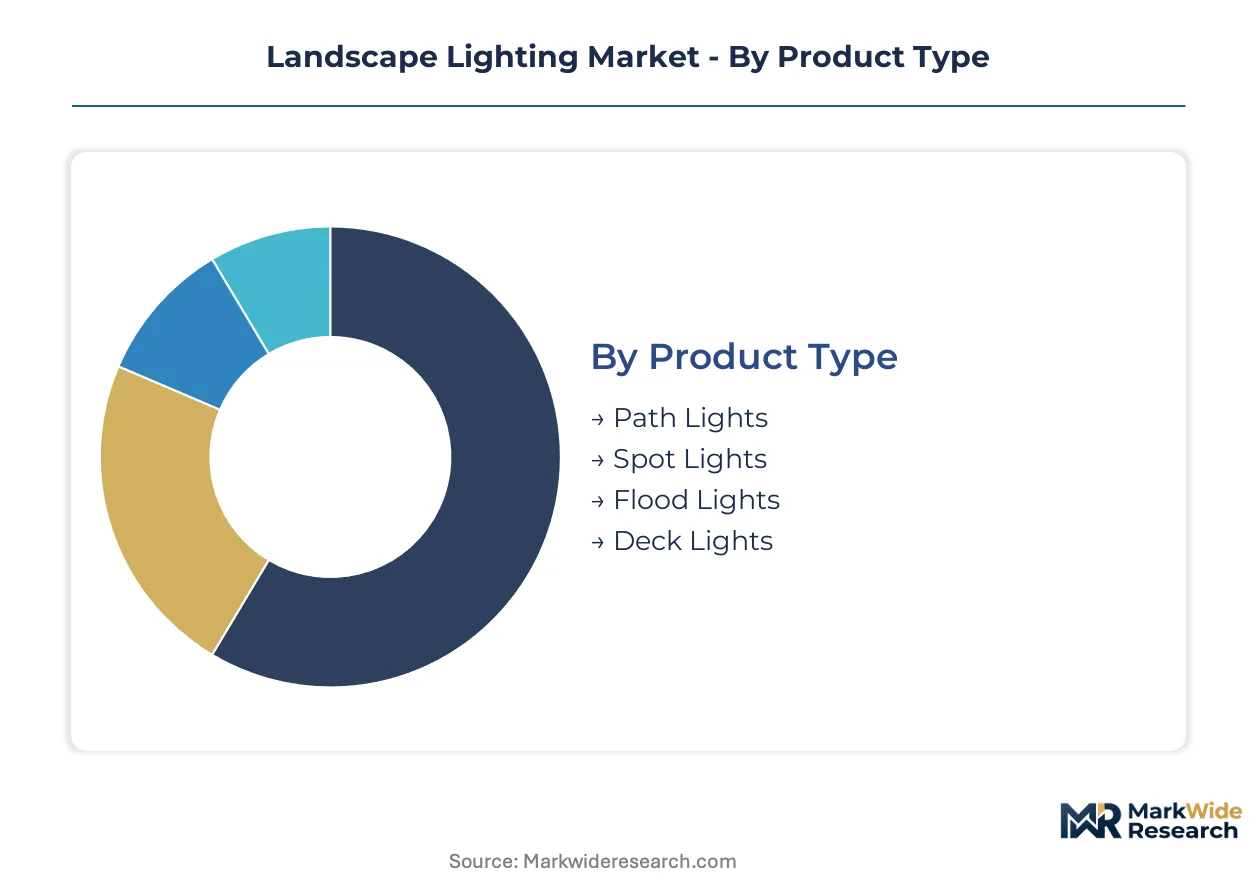
Landscape lighting procurement splits across four distinct category systems, each governing different phases of the specification process. Product type and power source decisions occur earliest in project timelines, while material and application choices cascade through engineering, aesthetic, and regulatory filters.
Product Type:
Mature fixture categories dominate installed bases, though emerging form factors are capturing specification attention in hospitality and smart-city deployments.
- Path Lights:Low-profile bollard and post-mounted luminaires typically housing COB LED arrays or integrated solar modules with 2700K-3000K CCT output. Municipal sidewalk programs in the United Arab Emirates specify these for pedestrian safety corridors, with procurement volumes rising alongside mega-project construction timelines.
- Spot Lights:Directional accent fixtures with adjustable beam angles (15° to 60°) and precision optics for architectural grazing and tree uplighting. Resort developers across Dubai and Abu Dhabi are expanding spot light budgets to extend terrace and garden venue usability past sunset.
- Flood Lights:Wide-beam wash luminaires delivering 1000+ lumens for facade illumination and security perimeter coverage.
- Deck Lights:Recessed and surface-mounted mini-luminaires for railing, stair, and platform integration in residential and marina applications.
Path lights retain volume leadership; spot lights hold the steepest expansion curve.
Power Source:
Cost tier stratification separates grid-dependent infrastructure from off-grid alternatives, with mid-tier battery systems bridging the gap in transitional markets.
- Solar:Photovoltaic-integrated fixtures with monocrystalline panels and lithium iron phosphate battery packs, eliminating trenching and transformer dependencies. Remote hospitality developments in Saudi Arabia and Oman are specifying solar-dominant systems to compress installation timelines from weeks to days.
- Hardwired:Line-voltage (120V) and low-voltage transformer-fed systems requiring licensed electrical contractor installation and underground conductor runs.
- Battery-Operated:Self-contained fixtures with replaceable or rechargeable cells for temporary installations and retrofit scenarios lacking circuit access.
- Low Voltage:12V-24V systems with centralized transformers, dominant in North American residential landscapes where safety codes limit line-voltage proximity to water features.
Hardwired installations retain volume leadership; solar configurations are gaining share fastest as photovoltaic efficiency improvements collapse lifecycle cost differentials.
Material:
Application environment dictates material selection, with corrosion resistance premiums separating coastal from inland procurement specifications.
- Metal:Die-cast aluminum, brass, and stainless steel housings with powder-coat or anodized finishes for thermal management and salt-air durability. Florida and California coastal markets command marine-grade 316 stainless steel premiums due to accelerated corrosion cycles.
- Plastic:UV-stabilized polycarbonate and ABS composites for cost-sensitive residential mass-market channels.
- Glass:Tempered and borosilicate lens materials for optical clarity and thermal shock resistance in high-output fixtures.
- Wood:Teak and cedar housings for aesthetic integration in naturalistic landscape designs, requiring regular maintenance in humid climates.
Metal housings retain volume leadership; glass optical components hold the steepest specification-grade growth trajectory.
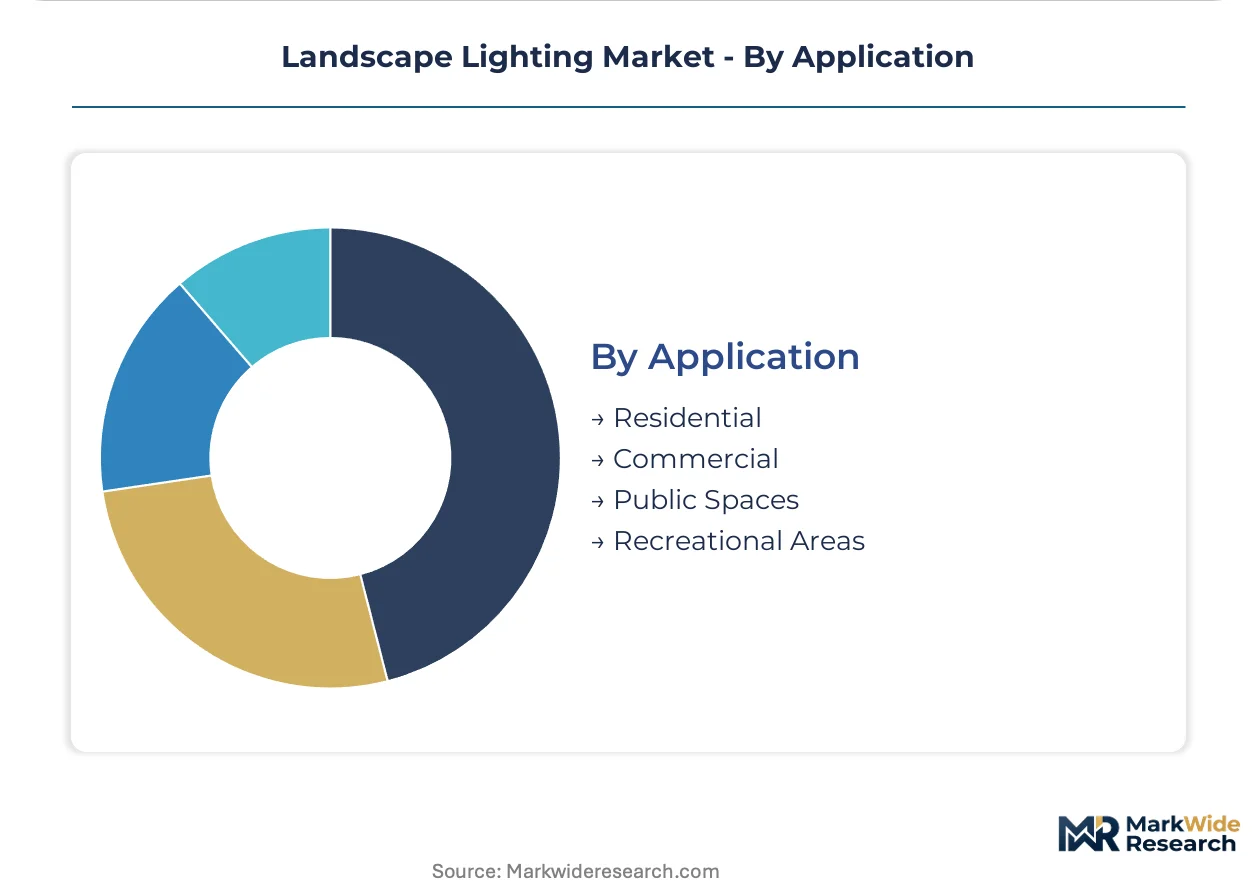
Application:
Customer type fragmentation separates volume-driven residential procurement from margin-rich commercial and public sector channels with extended service contract potential.
- Residential:Single-family and multi-family exterior illumination through big-box retail, e-commerce, and professional contractor channels. China's GB efficiency standards are tightening fixture requirements for imported products in this price-sensitive segment.
- Commercial:Hospitality, retail, and corporate campus deployments with specification complexity and ten-year maintenance agreements. North American developers now unbundle capital expenditure from lifecycle service contracts.
- Public Spaces:Municipal parks, plazas, and roadway median installations governed by EU Green Deal energy performance mandates and Dark Sky compliance programs.
- Recreational Areas:Golf courses, sports fields, and campground lighting with extended operating hours and vandalism resistance requirements.
Residential applications retain volume leadership; commercial deployments hold the steepest margin expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB efficiency standards for outdoor luminaires are compressing fixture margins across Chinese manufacturing clusters while accelerating LED retrofit specifications in import-dependent markets worldwide.
United States
Commercial hospitality developers in Florida and California are unbundling capital expenditure from ten-year maintenance contracts, with salt-air corrosion driving predictive replacement scheduling in coastal sub-markets. EPA ENERGY STAR qualification and Dark Sky compliance programs govern municipal procurement for parks and university campuses. Die-cast aluminum and marine-grade 316 stainless steel demand concentrates in Miami-Dade and Orange County specification channels.
Germany
Municipal procurement frameworks are accelerating LED retrofit mandates as the F-Gas Regulation restricts mercury-containing lamp imports, stranding existing high-pressure sodium inventories. KBA's alignment with France's ANSM implementation timelines forces contractors to consolidate supplier relationships for extended warranty terms. Specification-grade fixture demand clusters in Bavaria's municipal beautification programs and North Rhine-Westphalia's industrial campus conversions.
China
Guangdong and Zhejiang province manufacturing clusters are expanding LED module and driver capacity, though regional power rationing creates supply vulnerability for export-dependent fixture OEMs. MIIT enforces tightening GB standards for luminaire efficacy and electromagnetic compatibility nationwide. Shenzhen and Hangzhou technical institutes are advancing photocell interoperability protocols for smart-city deployment specifications.
United Arab Emirates
Mega-project construction in Dubai and Abu Dhabi is driving specification-grade procurement for terrace, pool, and garden venue illumination to extend usable outdoor hours past sunset. MOHAP's building efficiency guidelines influence hospitality developer specifications for exterior lighting systems. Procurement volumes concentrate in Dubai South and Saadiyat Island master-planned developments.
India
Smart Cities Mission and urban beautification programs are opening specification-grade channels previously dominated by unorganized local assemblers in municipal streetscape and park installations. BIS efficiency labeling requirements are tightening import standards for outdoor luminaires. Demand concentrates in Maharashtra's Mumbai Metropolitan Region and Gujarat's GIFT City infrastructure deployments.
Landscape Lighting Market Competitive Environment
Capability concentration sits with vertically integrated LED engine specialists; scale advantage sits with diversified electrical equipment conglomerates. The vendor base stratifies across three functional tiers: premium specification-grade fixture designers, mass-market residential distributors, and component-integrated system providers. Consolidation pressure is mounting as lifecycle service contracts displace upfront hardware pricing. Dominant competitive moves include backward integration into LED module production and geographic expansion through regional distribution partnerships.
Among diversified electrical equipment conglomerates, Eaton Corp. Plc and Hubbell Inc. occupy positions anchored by broad contractor channel access and specification-grade portfolio breadth. Signify NV represents the vertically integrated archetype with captive LED supply chain control. These three entities exemplify the competitive tension between hardware commoditization and recurring service revenue capture in commercial and municipal deployment channels.
| Leading Market Players |
|---|
| Acuity Brands Inc. |
| Signify NV |
| Kichler Lighting LLC |
| Hubbell Inc. |
| Eaton Corp. Plc |
| ams OSRAM AG |
| BEGA Gantenbrink-Leuchten KG |
| FX Luminaire |
| RAB Lighting Inc. |
| Others |
Value Chain & Pricing Dynamics
Shenzhen Port freight corridors to Rotterdam and Long Beach transmit aluminum ingot and lithium-ion cell cost volatility directly into fixture landed costs, compressing margins for European and North American distributors while amplifying price spreads between specification-grade and mass-market tiers.
Pricing Analysis
Specification-grade landscape lighting in the United Arab Emirates commands premiums of 40-60% above comparable fixtures in Indian municipal procurement, with differentiation driven by marine-grade 316 stainless steel certification and ten-year maintenance bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies the market, though cost compression in die-cast aluminum housings is intensifying because of Guangdong smelter energy surcharges. Residential big-box channels exhibit highest price sensitivity; hospitality developers in Dubai demonstrate lowest sensitivity due to lifecycle service contract unbundling.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for fixture OEMs dependent on Guangdong and Zhejiang LED module clusters. Manufacturing gravity draws from China for LED engines and drivers, Vietnam for cable assemblies, and Germany for precision optics, with copper conductor and aluminum die-cast housing dependencies creating margin vulnerability to LME price swings. Single-source vulnerability concentrates in lithium iron phosphate battery cell supply. Distribution runs through professional electrical contractor networks in North America and specification-grade project channels in the Middle East.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Landscape lighting sits in early-cycle expansion as solar photovoltaic integration penetrates remote hospitality developments previously unreachable by grid infrastructure, opening addressable market expansion beyond traditional electrical contractor dependencies.
For Market Incumbents: Harden specification-grade positioning through captive LED engine production in Guangdong clusters, insulating margin structures from raw material volatility while accelerating photocell interoperability certification to preempt proprietary protocol fragmentation threatening multi-site commissioning economics.
For New Entrants and Emerging Players: India's municipal Smart Cities procurement channels offer the most penetrable white-space, with BIS efficiency labeling requirements displacing unorganized local assemblers and creating specification-grade entry points through extended warranty terms and lifecycle service bundling distinct from capital expenditure bidding.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electrical equipment conglomerates seeking to divest non-core lighting portfolios, with mid-cap fixture designers possessing Dark Sky certification libraries and coastal corrosion expertise representing optimal acquisition profiles. Monitor EU F-Gas Regulation enforcement acceleration as inflection indicator for LED retrofit mandate timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Module Production | Captive Guangdong manufacturing clusters insulate Signify NV and Acuity Brands from driver supply shocks. |
| Dark Sky Certification Program Expansion | Full-cutoff fixture portfolios capture price-insensitive ecotourism demand in Arizona and Chile. |
| LiDAR-Integrated Adaptive Controls Development | Motion-responsive illumination algorithms reduce energy consumption for university campus deployments. |
| Regional Distribution Partnership in UAE | Mega-project specification channels in Dubai South demand localized technical support presence. |
| Lithium Iron Phosphate Battery Supply Agreement | Solar-dominant system warranties hinge on cell replacement cycle predictability for Saudi hospitality developments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, MIIT GB standard filings, EPA ENERGY STAR qualification databases, and EU F-Gas Regulation implementation timelines. Landscape lighting procurement directors at Dubai hospitality developers, electrical contractor network managers in Florida, municipal engineering leads in Maharashtra, and LED module sourcing executives in Shenzhen provided operating perspective. Bottom-up fixture shipment analysis triangulates against top-down construction spend allocation across commercial and residential application segments.
Forecast inputs span product type, power source configuration, material grade tier, and application channel across the projection horizon. CAGRs derive from segment-level demand elasticity modeling against construction pipeline data and regulatory retrofit mandate phasing. Solar photovoltaic efficiency improvement curves and lithium-ion cell cost decline trajectories inform off-grid adoption assumptions. Dark Sky compliance penetration rates and smart-city infrastructure deployment schedules shape connected controls demand projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese conglomerates or sudden aluminum tariff escalations would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
Kids Desk Lamp Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
United States Electric Fireplace Market