
 Chandelier Market | 2026-2036
Chandelier Market Size, Share, and Industry Trends Forecast 2026-2036
Chandelier Market Analysis
Asset-light leasing models for luxury fixtures are reshaping how hospitality groups source statement lighting, reducing upfront capital barriers for premium installations. Elegant Lighting leverages its vertical integration across crystal sourcing and custom fabrication to sustain margin control in bespoke projects. Schonbek anchors its competitive position through specialized heritage craftsmanship in Bohemian crystal techniques. Acuity Brands Lighting competes by extending its commercial LED infrastructure into ornamental fixtures that meet stringent energy codes.
A chandelier is a branched ornamental ceiling-mounted light fixture, typically incorporating multiple lamps and decorative elements such as crystal pendants, glass shades, or metal armatures, designed to provide ambient illumination while serving as an architectural focal point in interior spaces. Crystal chandeliers demand precision-cut lead glass or Swarovski-grade elements, with brass armatures requiring hand-polished finishing and UL-certified wiring assemblies for safety compliance. The hospitality end-user segment leads absolute volume as hotel groups prioritize signature lobby installations that reinforce brand identity. Contemporary style fixtures are capturing accelerated specification rates among residential architects favoring minimalist geometries over traditional ornate forms. Brass material configurations retain premium margin pools due to artisanal forging requirements and extended production lead times that limit commoditization pressure.
The US Department of Energy enforces efficacy standards through ENERGY STAR certification and FTC lighting facts labeling that shape product development priorities for chandelier manufacturers serving North American markets. China's SAMR and NMPA coordinate national standards for electrical safety and electromagnetic compatibility, creating compliance thresholds that filter import access for foreign producers. Stakeholders must monitor evolving efficiency mandates across multiple jurisdictions while calibrating design portfolios between heritage craftsmanship and connected lighting integration.
Market Dynamics
LED efficacy mandates and hospitality procurement centralization are compressing fixture lifecycles while fragmenting supplier relationships across tiered specification channels.
Growth Catalysts
- UAE Hospitality Construction:Dubai and Abu Dhabi hotel developments specify custom crystal installations for signature lobby spaces, pulling high-value bespoke orders from European fabricators.
- China GB Energy Standards:Updated national lighting efficiency codes pressure manufacturers toward LED-integrated designs that reduce operational load in commercial installations.
- Leasing Model Innovation:Asset-light fixture rental programs reduce upfront capital barriers for luxury hospitality groups refreshing property portfolios.
Market Restraints
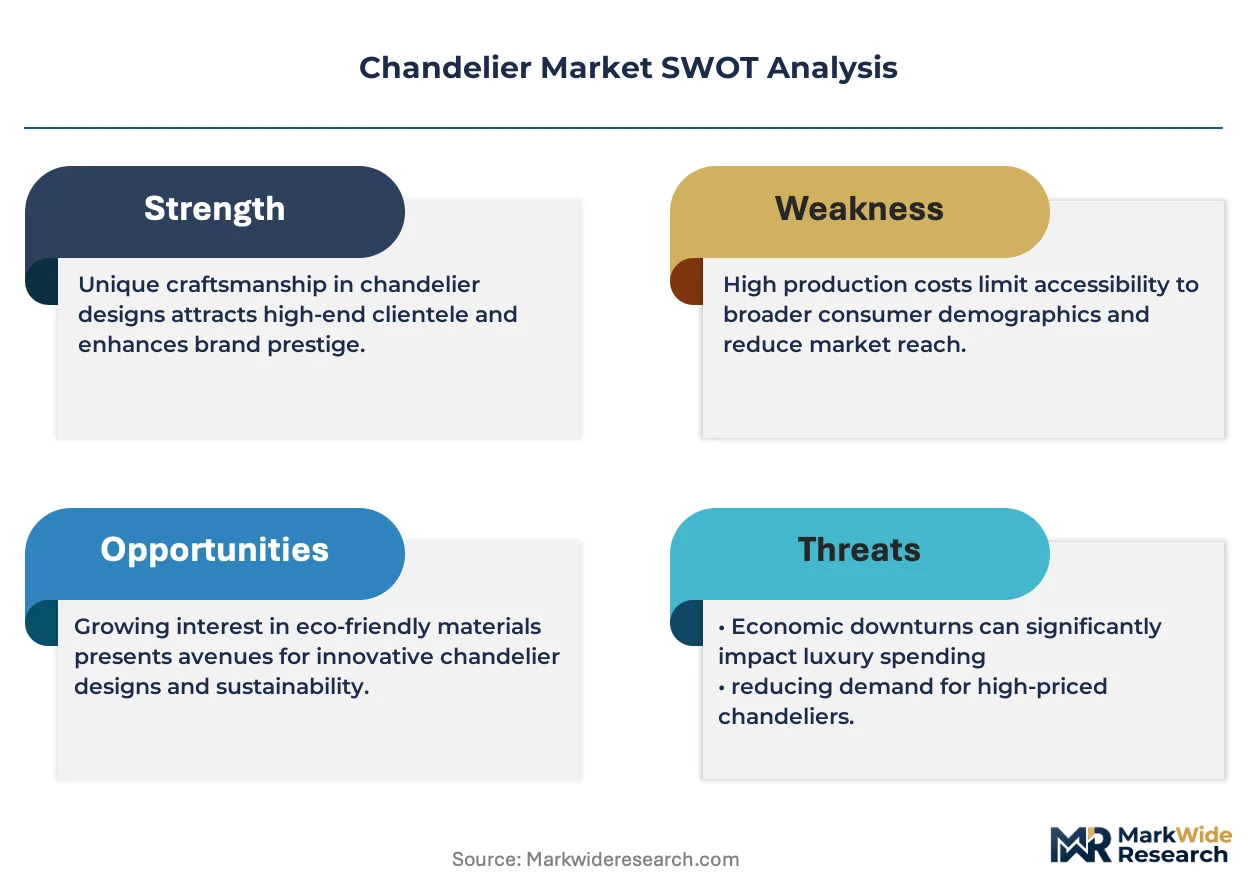
- Lead Crystal Input Costs:Precision-cut Bohemian crystal and Swarovski-grade elements face supply concentration from Austrian and Czech Republic foundries with limited alternative sourcing.
- Artisanal Production Bottlenecks:Brass armature forging and hand-polished finishing require extended lead times that resist automation and scale economies.
- Regulatory Friction:Divergent UL certification requirements for North American markets versus CE marking for European distribution create compliance duplication costs.
Strategic Opportunities
- Connected Lighting Convergence:Integration of DALI-2 and wireless control protocols with ornamental fixtures opens specification pathways in smart building projects.
- Saudi Hospitality Pipeline:Neom and Red Sea tourism developments represent underpenetrated demand for statement lighting in mega-project lobbies and ballrooms.
- EU Green Deal Incentives:Circular economy subsidies for repairable, upgradable luminaires reward modular chandelier architectures with replaceable LED engines.
Industry Challenges
- Heritage Craftsmanship Shortage:Bohemian crystal cutting and hand-forged brass finishing skills face generational attrition without structured apprenticeship pipelines.
- Multi-Jurisdiction Certification Timelines:Simultaneous UL, CE, and GB standard compliance extends product development cycles by 8-14 months for global distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chandelier Market |
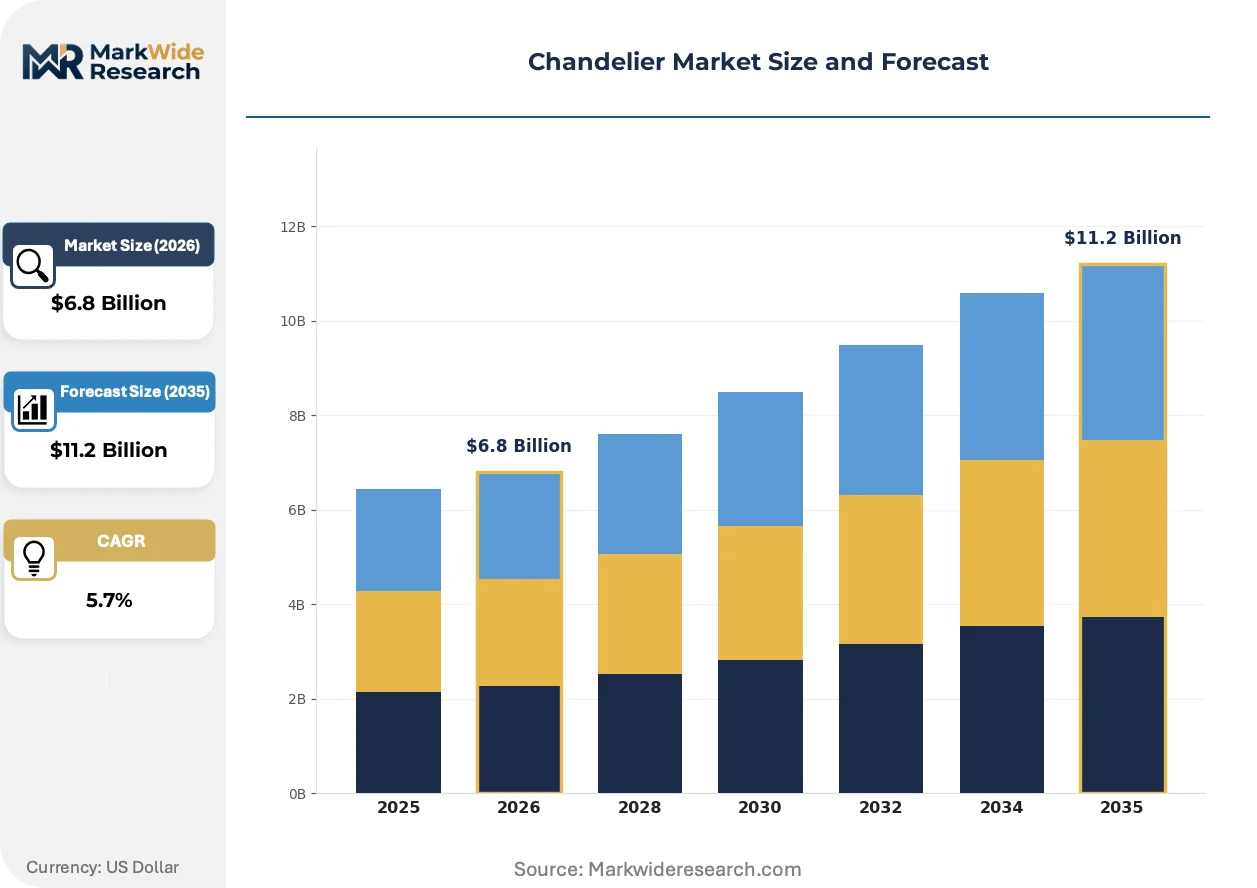
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Candle, Crystal, Modern, Traditional Material: Brass, Glass, Iron, Wood End User: Residential, Commercial, Hospitality, Events Style: Vintage, Contemporary, Rustic, Industrial |
| Companies Covered | Elegant Lighting, Acuity Brands Lighting, Kichler Lighting, James R. Moder Crystal Chandelier, Signify, Koninklijke Philips, Schonbek, King's Chandelier Company, Hinkley Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chandelier Market Emerging Trajectories
Fixture specification is pivoting from static decorative objects to integrated building systems, with procurement authority centralizing under hospitality brand design directors and facilities technology officers.
LED engine technology is migrating from retrofit kits to native chandelier architectures that embed heat dissipation channels within cast brass armatures. Hotel groups in the United Arab Emirates specify these integrated designs for 50,000-hour maintenance intervals. The shift compresses aftermarket parts revenue while elevating initial specification value.
China's SAMR and NMPA coordination on electromagnetic compatibility standards is tightening import access for European and North American producers. Manufacturers serving Chinese commercial projects must establish local testing partnerships or cede specification to domestic competitors. Hospitality developments in Shanghai and Shenzhen increasingly source from certified domestic fabricators.
Specification authority is consolidating under hospitality brand design directors who mandate centralized fixture libraries across property portfolios. Independent hotel operators and regional chains lose procurement autonomy as global brands enforce visual consistency. This concentration is most visible in Middle Eastern and Southeast Asian markets where international flag properties dominate new construction.
Chandelier Market Segmentation
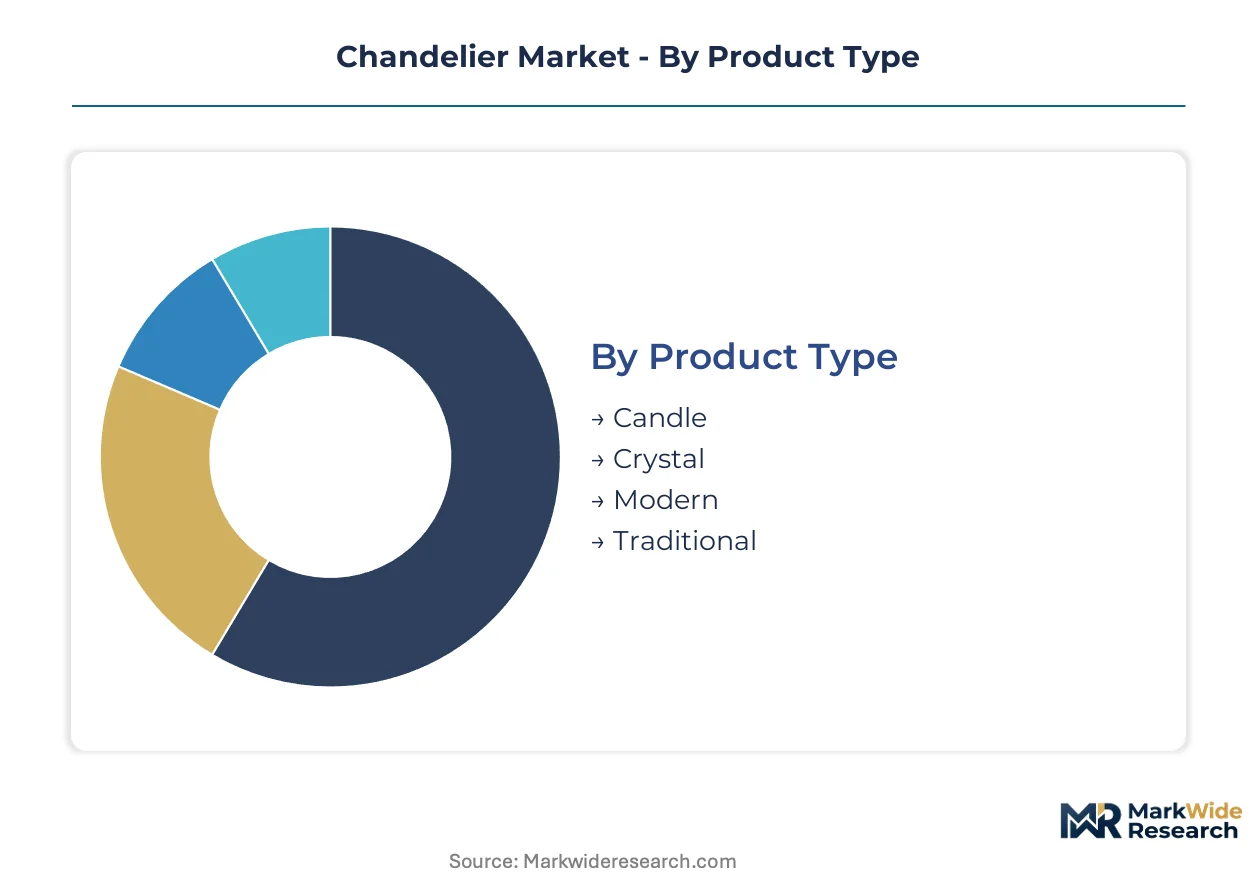
Chandelier procurement patterns diverge sharply across installation contexts, with specification authority consolidating under distinct buyer types. Material selection and stylistic positioning determine margin structures, while end-use concentration shapes volume distribution and design requirements.
Product Type:
Cost tier differentiation separates entry-level fixtures from heritage-grade installations, with fabrication complexity and certification burden widening the gap.
- Crystal:Precision-cut lead glass or Swarovski-grade elements demand hand-polished brass armatures and UL-certified wiring assemblies. UAE hospitality developments in Dubai and Abu Dhabi specify these for signature lobby installations that anchor brand identity.
- Modern:Minimalist geometries favor LED-native architectures with embedded heat dissipation channels and DALI-2 control compatibility. Residential architects in Shanghai and Shenzhen specify these for high-rise luxury apartments seeking maintenance intervals exceeding 50,000 hours.
- Candle:Reproduction designs replicate historical flame-shaped bulb configurations for heritage property restorations.
- Traditional:Ornate multi-tier constructions with hand-forged metalwork serve formal dining and ballroom applications.
Crystal holds installed capacity. Modern is rotating up the share rankings.
Material:
Application context dictates material selection, with hospitality and residential segments imposing divergent performance and aesthetic requirements.
- Brass:Artisanal forging and extended hand-polishing lead times create production bottlenecks that resist automation. Dubai hotel developments specify brass armatures for their oxidation resistance in high-humidity atrium environments.
- Glass:Murano-style hand-blown elements and pressed crystal alternatives offer design flexibility at compressed lead times. Shenzhen commercial installations source these for rapid project turnaround without heritage craftsmanship dependencies.
- Iron:Wrought and cast configurations serve industrial and rustic stylistic programs with lower unit economics.
- Wood:Sustainable timber certifications attract EU Green Deal subsidy eligibility for circular economy projects.
Brass commands specification in prestige hospitality. Glass is gaining share fastest in volume residential.
End User:
Customer type determines procurement centralization, with global brand design directors increasingly mandating fixture libraries across property portfolios.
- Hospitality:International flag properties dominate new construction in Middle Eastern and Southeast Asian markets. Centralized specification authority under brand design directors reduces procurement autonomy for independent operators.
- Residential:High-rise luxury developments in Shanghai and Shenzhen drive specification for connected lighting integration. Architects favor minimalist geometries that complement smart building infrastructure.
- Commercial:Office and retail installations prioritize ENERGY STAR certification and FTC lighting facts compliance for North American distribution.
- Events:Temporary installations and rental programs favor asset-light leasing models that reduce upfront capital barriers.
Hospitality holds installed capacity. Residential is climbing the fastest in specification volume.
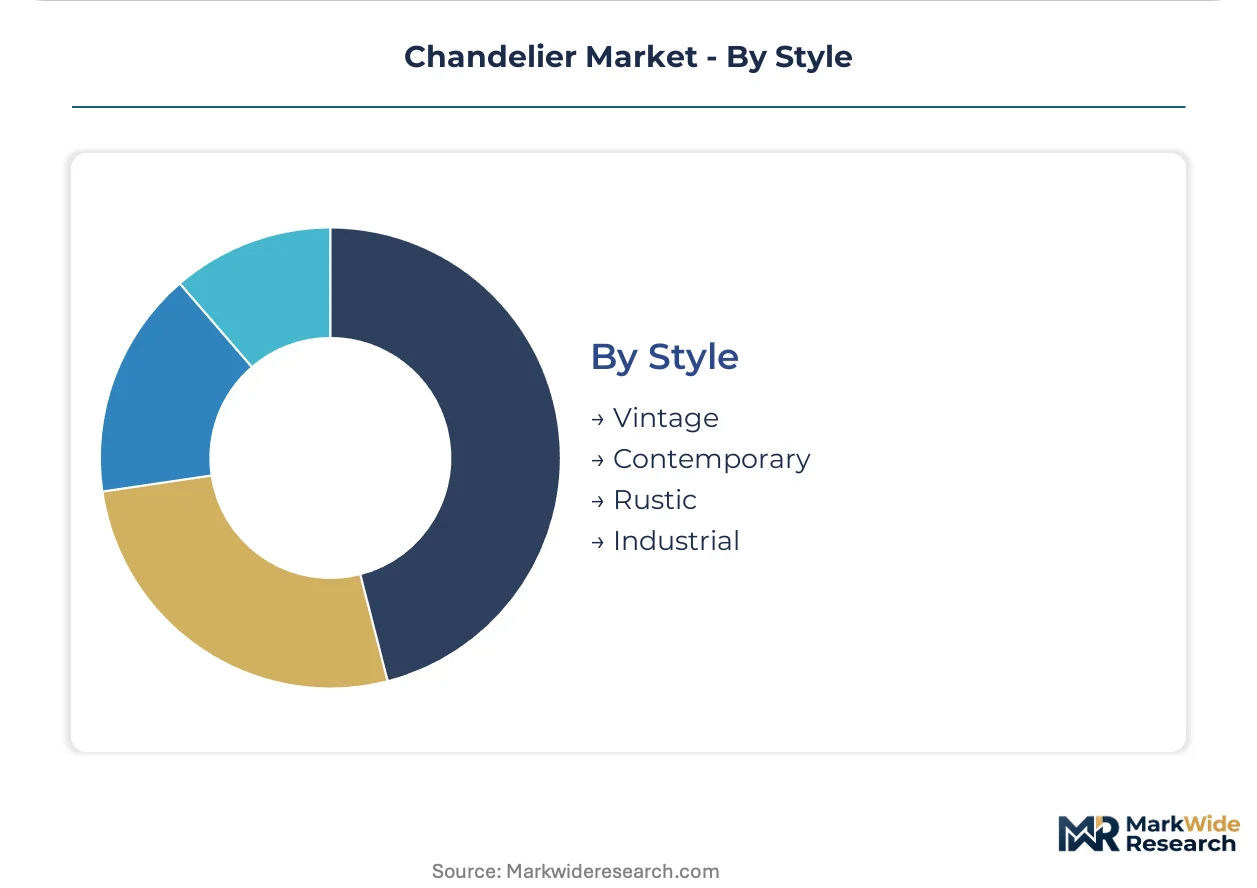
Style:
Maturity gradients separate established heritage categories from emerging contemporary programs, with generational buyer preferences shifting specification authority.
- Contemporary:Clean lines and geometric abstraction displace ornate traditional forms in architect-specified projects. LED-native integration and wireless control protocols align with smart building convergence trends.
- Vintage:Restoration-grade reproductions serve heritage property renovations requiring period-appropriate authenticity. Bohemian crystal cutting techniques face generational attrition without structured apprenticeship pipelines.
- Rustic:Reclaimed material aesthetics and distressed finishes attract boutique hospitality in secondary markets.
- Industrial:Exposed hardware and utilitarian metalwork serve adaptive reuse commercial projects.
Vintage holds installed capacity. Contemporary is expanding most quickly in specification rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality procurement directors in the United Arab Emirates command the highest-value chandelier specifications globally, while residential architects in China and Germany drive volume demand for contemporary LED-integrated fixtures.
United Arab Emirates
Dubai and Abu Dhabi hotel developments specify custom crystal installations for signature lobby spaces, pulling high-value bespoke orders from European fabricators. MOHAP coordinates safety certifications for electrical fixtures in hospitality environments. The Dubai Design District cluster concentrates specification authority under international brand design directors who mandate centralized fixture libraries.
China
Shanghai and Shenzhen luxury residential towers drive demand for minimalist geometries with DALI-2 control compatibility. SAMR and NMPA enforcement of GB energy efficiency standards pressures manufacturers toward LED-native architectures. The Pearl River Delta manufacturing corridor hosts certified domestic fabricators increasingly winning commercial project specifications.
Germany
Heritage property restorations in Bavaria and North Rhine-Westphalia sustain demand for Bohemian crystal reproductions with period-appropriate authenticity. ECHA REACH compliance and CE marking requirements filter import access for non-European producers. The Munich-Stuttgart industrial corridor maintains specialized craftsmanship clusters for hand-forged brass armatures.
United States
Hospitality chains centralize procurement authority under brand design directors who enforce visual consistency across property portfolios. The Department of Energy enforces ENERGY STAR certification and FTC lighting facts labeling that shape product development priorities. The Southeast construction corridor spanning Florida and Georgia concentrates new hotel development specifying statement lighting installations.
Saudi Arabia
Neom and Red Sea tourism developments represent emerging demand centers for mega-project lobbies and ballrooms. SFDA and municipal regulators coordinate safety standards for large-scale hospitality electrical installations. The Riyadh-Eastern Province corridor anchors domestic distribution infrastructure serving western region tourism developments.
Chandelier Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered specification channels, with hospitality procurement centralization favoring scale-capable suppliers. The vendor base spans heritage crystal houses, commercial lighting conglomerates, and regional fabrication specialists. Three archetypes dominate: vertically integrated luxury specialists, commercial LED infrastructure extenders, and artisanal craft preservationists. Competitive moves concentrate on backward integration into crystal sourcing and strategic partnerships with hospitality brand design directors.
Among heritage craft preservationists, Schonbek occupies a position exemplifying Bohemian crystal technique specialization. Elegant Lighting and Acuity Brands Lighting represent contrasting archetypes—one anchored in custom fabrication vertical integration, the other in commercial LED infrastructure extension. These three sit within distinct competitive vectors rather than direct overlap, with specification channels sorting buyers by project scale and heritage authenticity requirements.
| Leading Market Players |
|---|
| Elegant Lighting |
| Acuity Brands Lighting |
| Kichler Lighting |
| James R. Moder Crystal Chandelier |
| Signify |
| Koninklijke Philips |
| Schonbek |
| King's Chandelier Company |
| Hinkley Lighting |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Bohemian crystal foundries tightens supplier leverage over European fabricators, compressing margin flexibility for heritage-grade fixtures while accelerating LED-native substitution in price-sensitive tiers.
Pricing Analysis
Cost-plus contracts with lead-glass indexation dominate procurement between Austrian foundries and chandelier manufacturers. Price differentiation rests on UL versus CE certification tiers and brass-forging complexity. Cost compression in mid-market tiers intensifies as Chinese LED-integrated alternatives displace traditional crystal configurations. Hospitality procurement directors show lowest price sensitivity; residential architects in high-rise developments exhibit highest.
Supply Chain Analysis
Upstream feedstock concentration in Czech Republic and Austria for precision-cut crystal creates single-source vulnerability for heritage-grade producers. Brass armature forging draws from Italian and German metalworking clusters. Tariff exposure on Chinese-sourced LED engines compounds cost volatility. Distribution runs through hospitality brand design directors who mandate centralized fixture libraries across property portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating under hospitality brand design directors who enforce centralized fixture libraries, fragmenting procurement autonomy for independent operators and regional chains.
For Market Incumbents: Insulate heritage craftsmanship positions by securing captive Bohemian crystal supply agreements before generational attrition accelerates. Invest in DALI-2 certification portfolios to capture smart-building specification pathways. LED-native substitution in residential tiers threatens traditional crystal volume. For New Entrants and Emerging Players: Mid-market commercial installations in Saudi Arabia's Neom corridor represent the most penetrable entry point, with underdeveloped local fabrication capacity and mega-project scale. Target asset-light leasing partnerships with hospitality procurement platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across LED-native chandelier architectures as modular engine designs reduce artisanal dependency. Acquire specialized craftsmanship houses with established apprenticeship pipelines for 5-10 year heritage scarcity positioning. Monitor GB standard enforcement velocity in China as inflection indicator for domestic competitor substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Sourcing | Captive supply of Bohemian-grade elements locks margin control against Austrian foundry concentration. |
| DALI-2 Protocol Certification | Smart-building specification eligibility opens procurement pathways with hospitality technology officers. |
| Asset-Light Leasing Program Launch | Reduces upfront capital barriers for luxury hospitality groups refreshing property portfolios. |
| GB Standard Compliance Investment | SAMR certification requirements filter import access for European producers in Chinese commercial projects. |
| Heritage Craft Apprenticeship Pipeline | Structured training programs counter generational attrition in hand-forged brass and crystal cutting techniques. |
Methodological Framework
A standing panel of hospitality procurement directors, lighting specification architects, crystal foundry operations managers, and LED engine procurement leads provided ongoing calibration across primary fieldwork. Secondary validation drew from SAMR GB standard filings, ENERGY STAR certification databases, Dubai Design District development permits, and hospitality brand annual reports. Bottom-up project pipeline analysis triangulated against top-down fixture shipment data from Pearl River Delta manufacturing clusters.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeled by product type, material configuration, end-user category, and stylistic positioning. CAGRs derived from regression analysis of historical specification rates against hospitality construction permits and residential tower completions. Forecast inputs incorporated LED efficacy mandate timelines and GB standard enforcement trajectories.
Stress conditions across lead-crystal supply disruption, hospitality construction cycle downturns, and regulatory acceleration in China were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against hospitality brand capital expenditure disclosures and foundry capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
North America Decorative and Illuminated Mirror Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Table and Floor Lamps Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Outdoor Lighting Market