
 Smart Pacifier Market | 2026-2036
Smart Pacifier Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pacifier Market Insights
Silicone elastomer is broadening its share in smart pacifier nipple construction as manufacturers phase out conventional latex to reduce allergen risk and extend sterilization durability. Koninklijke Philips N.V. leverages its respiratory monitoring heritage to anchor premium positioning in sleep-tracking variants. Newell Brands Inc. competes through mass-market channel control across North American big-box retail. BlueMaestro specializes in compact Bluetooth sensor architecture that occupies a distinct tier among technology suppliers.
A smart pacifier integrates biometric sensors, wireless communication modules, and food-grade silicone or thermoplastic elastomer housings to monitor infant temperature, feeding intervals, or sleep patterns and transmit data to caregiver smartphones or clinical dashboards. Bluetooth-enabled units lead volume shipments due to universal smartphone compatibility and minimal power draw, while IoT-integrated models represent the fastest-expanding margin pool as cloud analytics subscriptions attach. Pediatric clinics and hospitals command higher average unit economics than parent-directed retail channels because procurement bundles include software dashboards and remote nursing support.
FDA Class II device clearance shapes product development timelines and clinical validation requirements for any smart pacifier marketed with diagnostic claims in the United States. CE marking under the EU MDR and REACH substance restrictions govern European market access and material composition standards. Stakeholders must monitor how FDA software-as-a-medical-device guidance and EU AI Act risk classification for health monitoring algorithms reshape compliance investment and partnership structures.
Market Dynamics
FDA Class II clearance pathways compress development timelines for diagnostic-claim smart pacifiers, while Bluetooth Low Energy chipset miniaturization simultaneously reduces hardware footprints and power consumption. These dual pressures force manufacturers to synchronize clinical validation with rapid hardware iteration cycles.
Growth Catalysts
- Pediatric clinic procurement bundles:Hospitals in the United States and Germany now package remote nursing support with device purchases, lifting average unit economics above parent-directed retail channels.
- EU MDR harmonization:CE marking convergence under the Medical Device Regulation accelerates multi-country European market entry for validated sensor platforms.
- Silicone elastomer substitution:Manufacturers phase out latex nipples to eliminate allergen exposure and extend autoclave sterilization durability across neonatal intensive care settings.
Market Restraints
- Semiconductor supply concentration:Bluetooth Low Energy chip fabrication depends on concentrated East Asian foundry capacity, exposing hardware sourcing to geopolitical friction.
- FDA software-as-medical-device guidance:Algorithm health monitoring claims trigger additional validation layers that extend pre-market notification timelines.
- Rechargeable battery chemistry costs:Miniaturized lithium polymer cells carry premium input pricing that constrains economy-tier product viability.
Strategic Opportunities
- Subscription cloud analytics:IoT-integrated pacifiers attach recurring revenue streams through sleep-pattern and feeding-interval dashboards sold to sleep-deprived parent segments.
- Japan's aging caregiver workforce:METI incentives for remote infant monitoring tools align with hospital nursing shortages in Tokyo and Osaka prefectures.
- AI Act health algorithm classification:EU risk-tier frameworks for biometric monitoring create first-mover advantage for manufacturers pre-certifying high-risk algorithmic functions.
Industry Challenges
- Biomedical sensor calibration expertise:Temperature and respiratory rate measurement accuracy requires rare cross-trained hardware-software engineering talent.
- ISO 13485 quality management implementation:Medical device manufacturing standards demand documentation systems that strain legacy consumer-electronics quality teams.
- Legacy hospital IT integration:Bluetooth-to-EHR data pipelines require HL7 FHIR interface development that prolongs enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pacifier Market |
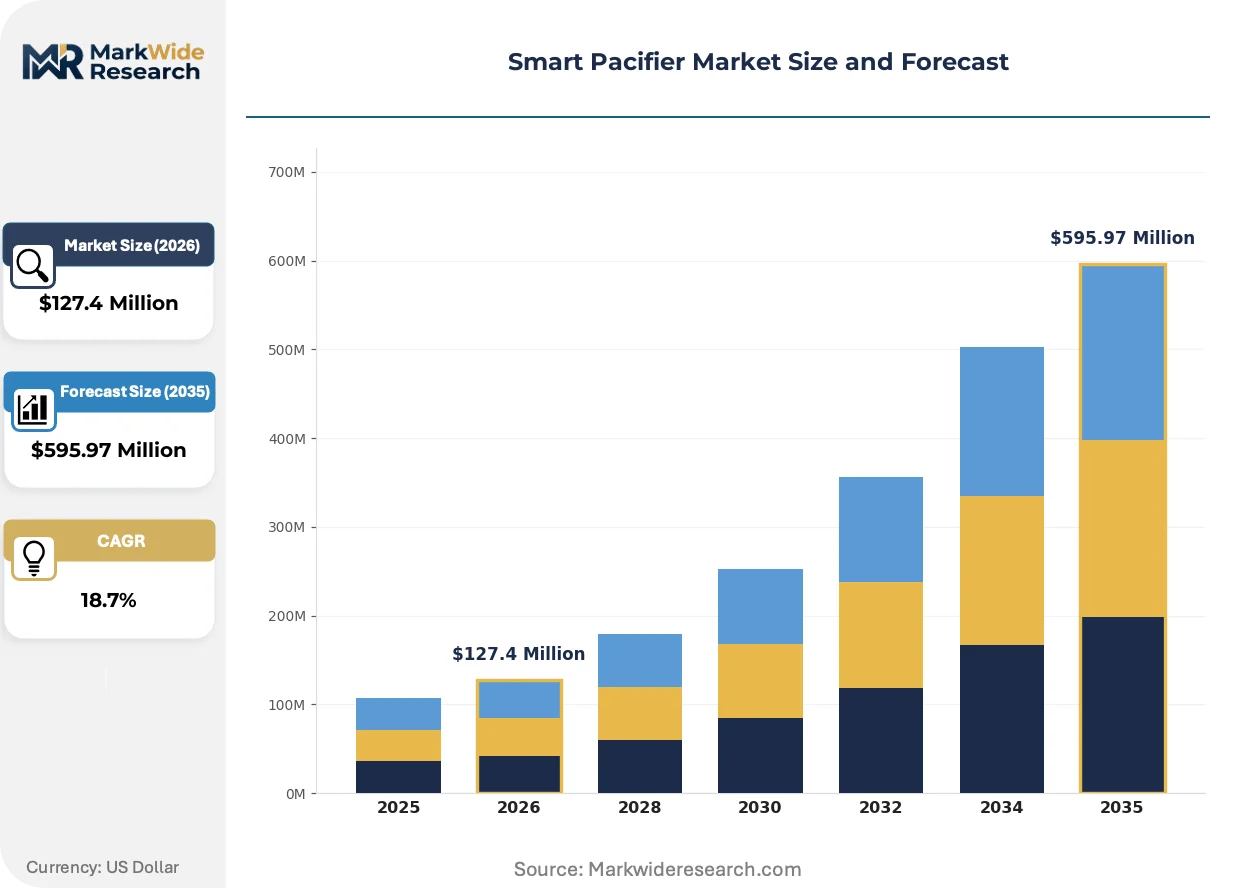
| Market Size in 2026 | $127.4 Million |
| Market Size in 2035 | $595.97 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Pacifiers, Temperature Monitoring Pacifiers, Feeding Trackers, Sleep Monitoring Pacifiers Technology: Bluetooth, NFC, IoT, RFID End User: Parents, Caregivers, Pediatric Clinics, Hospitals Distribution Channel: Online Retail, Pharmacies, Baby Specialty Stores, Supermarkets |
| Companies Covered | Koninklijke Philips N.V., Newell Brands Inc., Pigeon Corporation, MAM Babyartikel GmbH, Angelcare USA LLC, Mayborn Group, BlueMaestro, Brainchild Technologies, LLC, Root3 Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pacifier Market Trends and Innovations
Sensor fusion architectures and wireless protocol standardization are compressing the gap between consumer wellness devices and clinical-grade infant monitors. Manufacturers now face pressure to validate algorithms under medical device frameworks while maintaining consumer-electronics cost structures.
Multi-modal biometric sensing is consolidating discrete temperature, respiratory rate, and feeding detection into single-chip platforms. Pediatric sleep clinics in Germany and Japan pilot these consolidated sensors for overnight apnea screening. The technology is consolidating previously separate hardware subsystems into unified firmware-controlled modules that reduce unit bill-of-materials.
EU AI Act risk classification for health monitoring algorithms is reshaping validation investment priorities. Manufacturers must now document algorithmic transparency and bias mitigation before CE marking. Sleep-tracking variants with diagnostic claims face the strictest conformity assessment routes through notified bodies in the Netherlands and Germany.
Direct-to-parent subscription models are displacing traditional retail markups in the United States. Big-box channel control weakens as caregivers purchase through manufacturer apps with attached clinical coaching tiers. This channel rotation concentrates most visibly in California and New York metropolitan markets where parental willingness to pay for biometric data runs highest.
Smart Pacifier Market Segmentation
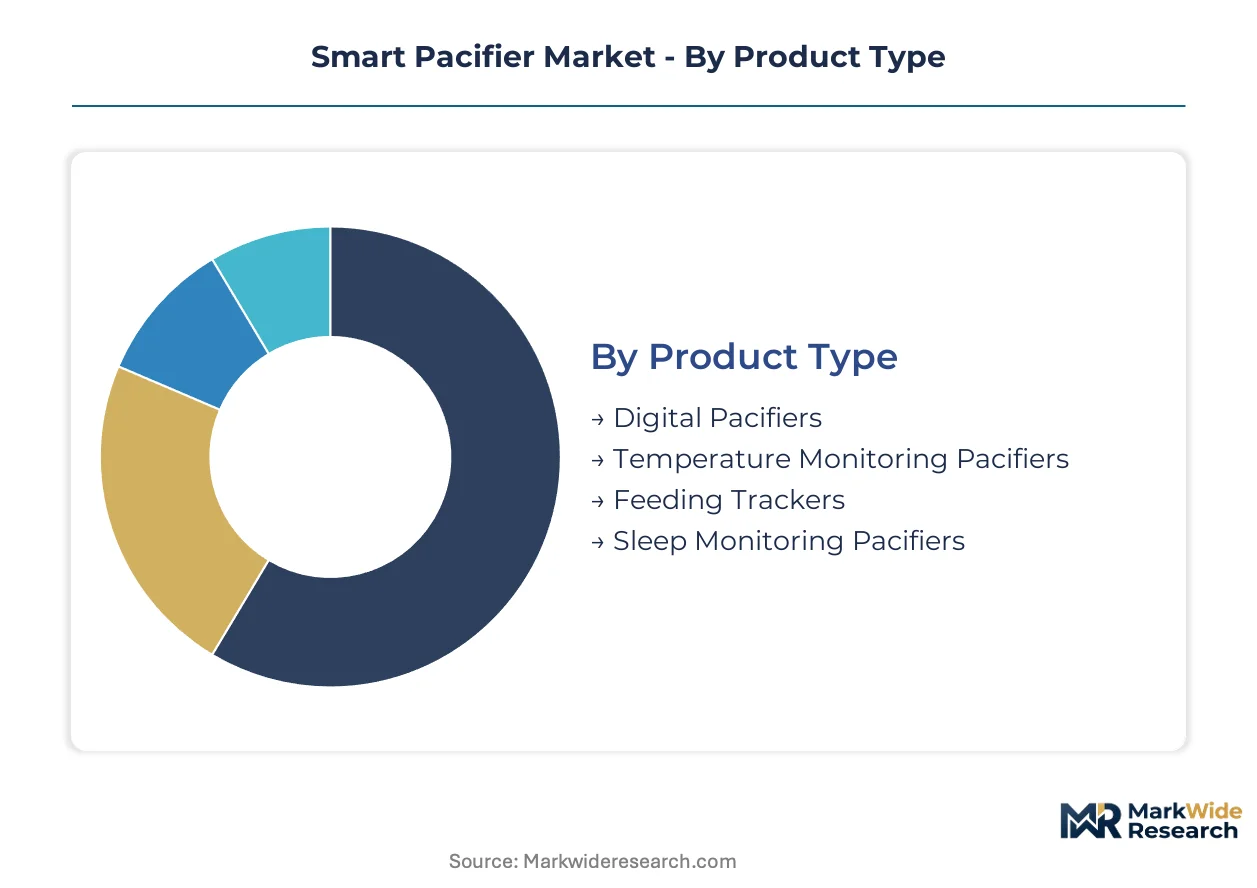
Smart pacifier manufacturers configure product portfolios across four intersecting dimensions where technology choice and channel access determine margin capture. Supply concentration in Bluetooth chipset fabrication and silicone elastomer molding creates divergent economics across these segment boundaries.
Product Type:
Supply concentration in sensor fabrication and clinical validation capacity favors manufacturers with respiratory monitoring heritage.
- Digital Pacifiers:Entry-tier units bundle basic temperature logging with smartphone app pairing through embedded Bluetooth Low Energy modules. Mass-market adoption concentrates in United States big-box retail where parental price sensitivity limits sensor sophistication.
- Temperature Monitoring Pacifiers:Clinical-grade thermistor arrays achieve measurement precision required for neonatal intensive care protocols. German and Japanese pediatric clinics absorb premium volumes where FDA Class II and PMDA clearance justify procurement bundling with remote nursing support.
- Feeding Trackers:Suction pressure sensors detect nursing intervals and duration for lactation consultants.
- Sleep Monitoring Pacifiers:Accelerometer and respiratory rate fusion algorithms target sleep-deprived parent segments in California and New York metropolitan markets.
Temperature Monitoring Pacifiers absorb the bulk of installed capacity; Sleep Monitoring Pacifiers are expanding most quickly.
Technology:
Component sourcing geography and protocol standardization maturity create tiered cost structures across wireless architectures.
- Bluetooth:Universal smartphone compatibility and minimal power draw dominate volume shipments. East Asian foundry concentration for BLE chipsets exposes hardware sourcing to geopolitical friction while compressing unit economics.
- IoT:Cloud analytics subscription attachment generates recurring revenue streams through sleep-pattern dashboards. METI incentives in Japan accelerate hospital pilot programs for remote infant monitoring where nursing shortages concentrate in Tokyo and Osaka prefectures.
- NFC:Near-field protocols serve clinical settings requiring offline data retrieval without battery dependence.
- RFID:Passive identification tags support inventory tracking in hospital procurement systems rather than continuous biometric monitoring.
Bluetooth carries the heaviest production volume; IoT integration is climbing the fastest.
End User:
Purchasing authority and reimbursement pathways split demand between consumer-directed and institutional procurement channels.
- Pediatric Clinics:Bundled software dashboards and remote nursing support lift average unit economics above retail channels. CE marking under EU MDR accelerates multi-country European market entry for validated sensor platforms.
- Parents:Direct-to-consumer subscription models displace traditional retail markups through manufacturer apps with attached clinical coaching tiers.
- Caregivers:Grandparent and nanny segments prioritize simplicity over diagnostic precision.
- Hospitals:HL7 FHIR interface requirements for EHR integration prolong enterprise sales cycles despite higher contract values.
Pediatric Clinics command the premium tier; Parents represent the volume base.
Distribution Channel:
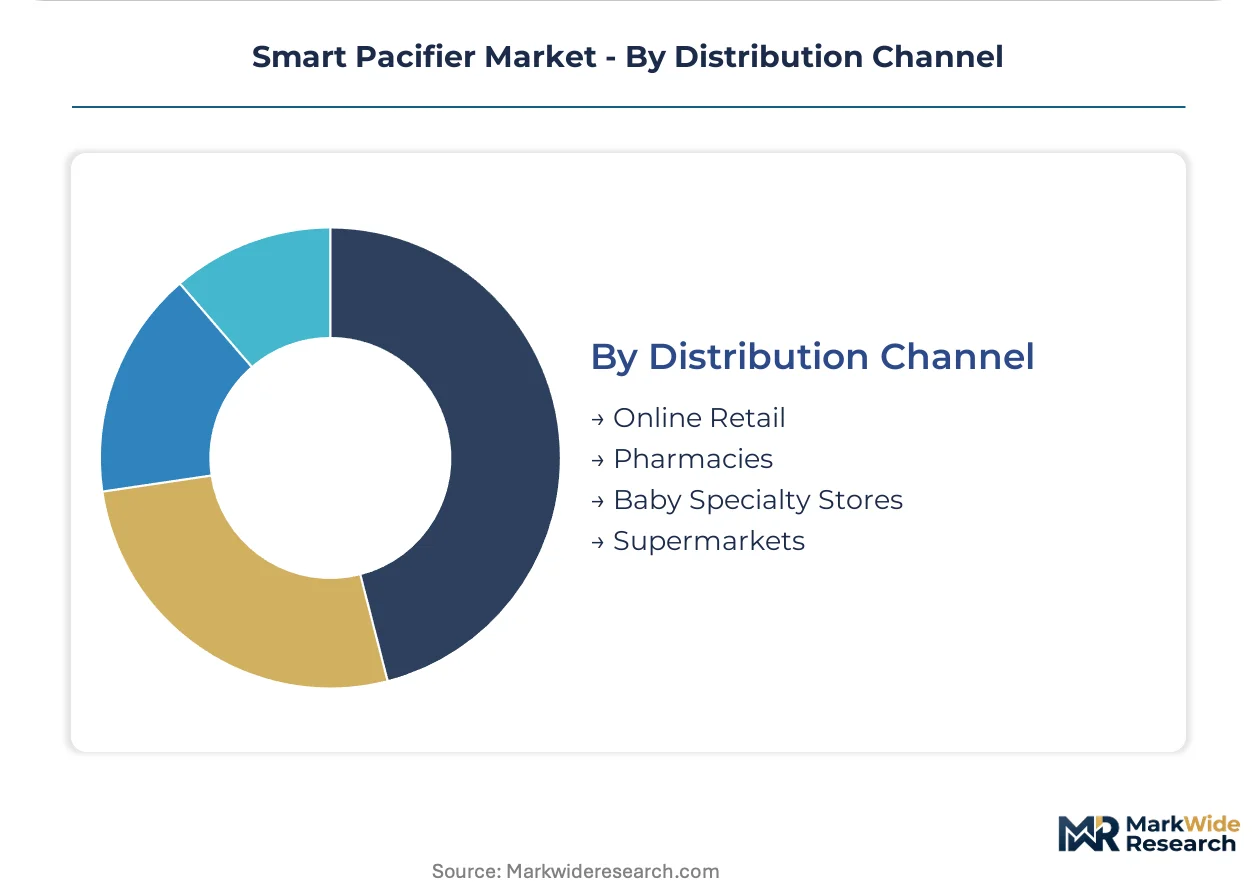
Channel control and customer acquisition cost structures determine margin retention across physical and digital touchpoints.
- Online Retail:Manufacturer-direct apps capture biometric data subscription attach rates while bypassing wholesale markups. California and New York metropolitan markets show highest parental willingness to pay for dashboard access.
- Baby Specialty Stores:Trained staff explain sensor functionality and sterilization protocols to first-time parents. German specialty retail chains leverage CE marking visibility to justify premium positioning.
- Pharmacies:Clinical credibility positioning aligns with temperature monitoring variants seeking diagnostic claim differentiation.
- Supermarkets:Mass-market placement suits entry-tier digital pacifiers with minimal feature differentiation.
Online Retail is gaining share fastest; Baby Specialty Stores retain the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parental willingness to pay for biometric infant data concentrates most visibly in the United States, Germany, and Japan, where pediatric clinic procurement bundles and direct-to-consumer subscription models are displacing traditional retail channels.
United States
California and New York metropolitan markets drive direct-to-parent subscription adoption through manufacturer apps with attached clinical coaching tiers. FDA Class II device clearance shapes product development timelines for diagnostic-claim smart pacifiers marketed across the country. Sleep-tracking variants with respiratory monitoring heritage anchor premium positioning in Boston and San Francisco pediatric sleep clinics.
Germany
Neonatal intensive care units in Munich and Hamburg absorb premium volumes of temperature monitoring pacifiers where CE marking under EU MDR justifies procurement bundling with remote nursing support. German specialty retail chains leverage CE marking visibility to justify premium positioning to first-time parents. Bavarian pediatric clinics pilot multi-modal biometric sensing for overnight apnea screening.
Japan
METI incentives for remote infant monitoring tools align with hospital nursing shortages concentrated in Tokyo and Osaka prefectures. PMDA clearance pathways govern market access for diagnostic-claim variants targeting clinical channels. Kansai region manufacturers supply compact Bluetooth sensor architectures that occupy distinct tiers among technology suppliers.
United Kingdom
London and Southeast England concentrate demand for IoT-integrated pacifiers with cloud analytics subscription attachment. NHS procurement frameworks increasingly evaluate connected infant monitoring tools for postnatal ward deployment. Midlands-based distributors channel entry-tier digital pacifiers through pharmacy retail networks.
Netherlands
Randstad region notified bodies conduct the strictest conformity assessment routes for sleep-tracking variants with diagnostic claims under EU AI Act risk classification. Eindhoven's semiconductor ecosystem supplies Bluetooth Low Energy chipsets that reduce hardware footprints and power consumption. Dutch pediatric clinics accelerate adoption of sensor fusion architectures validated under harmonized CE marking protocols.
Smart Pacifier Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers synchronize clinical validation capacity with rapid hardware iteration cycles. The vendor base stratifies across three tiers: heritage respiratory monitoring specialists, mass-market channel controllers, and compact sensor technology suppliers. Two archetypes anchor competitive positioning: incumbents leveraging medical device manufacturing heritage and entrants exploiting consumer-electronics cost structures. M&A activity and technology licensing agreements represent the dominant competitive moves as firms acquire biomedical sensor calibration expertise and ISO 13485 quality management capabilities.
Within the heritage medical device tier, Koninklijke Philips N.V. and MAM Babyartikel GmbH exemplify manufacturers leveraging respiratory monitoring heritage and European manufacturing base respectively. Among mass-market channel specialists, Newell Brands Inc. occupies a position reflecting North American retail network control. BlueMaestro represents the compact sensor technology archetype, anchoring a distinct tier among Bluetooth architecture suppliers. These three firms collectively illustrate how competitive positioning fragments across clinical validation depth, channel access breadth, and component miniaturization capability.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Newell Brands Inc. |
| Pigeon Corporation |
| MAM Babyartikel GmbH |
| Angelcare USA LLC |
| Mayborn Group |
| BlueMaestro |
| Brainchild Technologies, LLC |
| Root3 Labs |
| Others |
Pricing and Supply Chain Analysis
Pediatric clinic procurement bundles in the United States and Germany anchor premium pricing tiers while parent-directed retail channels absorb cost compression from mass-market entrants. This bifurcation concentrates pricing power with manufacturers holding FDA Class II clearance and CE marking under EU MDR, leaving economy-tier suppliers exposed to input cost volatility.
Pricing Analysis
Volume shipments concentrate in Bluetooth-enabled entry-tier units sold through supermarkets and online retail, while margin capture clusters in IoT-integrated variants with attached cloud analytics subscriptions. Pricing stratifies across clinical-grade certification tiers, with FDA-cleared temperature monitoring pacifiers commanding substantial premiums over wellness-positioned sleep trackers. Cost compression in the economy tier is intensifying because East Asian foundry concentration for BLE chipsets limits supplier bargaining power. Parent-directed retail channels exhibit highest price sensitivity, whereas hospital procurement committees prioritize diagnostic accuracy and EHR integration over unit cost.
Supply Chain Analysis
Bluetooth Low Energy chipset fabrication rests on concentrated foundry capacity in Taiwan, South Korea, and China, exposing hardware sourcing to geopolitical friction and tariff exposure. Silicone elastomer for nipple construction draws from German and Japanese specialty chemical producers, while miniaturized lithium polymer cells feed from South Korean battery manufacturers. Single-source vulnerability in BLE semiconductor fabrication represents the dominant structural risk. Distribution runs through hybrid channels combining manufacturer-direct subscription apps with baby specialty retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around clinical validation capabilities, with FDA software-as-medical-device guidance and EU AI Act compliance costs forcing weaker consumer-electronics entrants toward exit or acquisition.
For Market Incumbents: Deploy ISO 13485 quality management system upgrades to defend hospital procurement channel access against emerging sensor fusion specialists. Acquire biomedical sensor calibration expertise through targeted hiring or technology licensing to counter algorithm validation requirements from notified bodies in the Netherlands and Germany. Deepen backward integration into silicone elastomer molding to secure sterilization durability specifications demanded by neonatal intensive care units. For New Entrants and Emerging Players: Grandparent and nanny caregiver segments represent underserved buyer archetypes prioritizing simplicity over diagnostic precision, offering white-space entry below clinical-grade pricing tiers. Japan's Kansai region and Germany's Bavarian pediatric clinic networks present the most penetrable geographic targets given METI incentives and EU MDR harmonization tailwinds. Pursue direct-to-consumer app launches with stripped-down feature sets to bypass big-box channel control. For Investors and Strategic Acquirers: The window for entry favors compact sensor technology suppliers with pre-certified Bluetooth architectures and existing relationships with East Asian foundries. Long-term viability hinges on acquiring firms with demonstrated algorithmic transparency documentation for EU AI Act high-risk classification. Watch FDA software-as-medical-device guidance finalization as the critical inflection indicator for valuation multiples across the sector.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Class II Clearance Pathway | Accelerates market access for diagnostic-claim variants targeting United States pediatric sleep clinics. |
| CE Marking Under EU MDR | Unlocks multi-country European procurement bundling with remote nursing support services. |
| Bluetooth Sensor Architecture Licensing | Enables rapid hardware iteration without captive foundry investment or geopolitical exposure. |
| Cloud Analytics Subscription Development | Attaches recurring revenue streams to sleep-pattern dashboards for California and New York parent segments. |
| Hospital System Partnership | Secures HL7 FHIR EHR integration contracts that prolong sales cycles but lift average unit economics. |
Research Methodology
SEC filings from connected health device manufacturers, FDA 510(k) premarket notification databases, and EU MDR notified body conformity assessment records formed the secondary backbone. Primary interviews with biomedical engineers, hospital GPO contracts managers, pediatric clinic procurement leads, and Bluetooth sensor technology suppliers combined with bottom-up shipment data and top-down healthcare expenditure modeling to triangulate market sizing.
Historical trendline analysis of FDA Class II device approval timelines and Bluetooth chipset cost curves informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, wireless protocol architecture, end-user purchasing authority, and distribution channel control. CAGRs derived from fitted growth curves applied to pediatric clinic procurement bundle penetration rates and parent-directed subscription attach rates, with cross-validation against neonatal intensive care unit bed capacity expansion in target geographies.
Revisions become necessary when FDA software-as-medical-device guidance finalization, EU AI Act implementing acts, or East Asian semiconductor export controls materialize differently than baseline assumptions. Forecasts reflect documented assumptions about regulatory pathway timelines and caregiver willingness-to-pay elasticity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Slings Market
Baby Products
Potty Training Seat Market
Baby Products
Baby Care Products Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Baby Sleepsuits Market
Baby Products
France Baby Care Products Market
Baby Products
Japan Baby Care Product Market
Baby Products
Baby Bottle Market
Baby Products
Stroller Rental Market
Baby Products
Baby Detergents and Laundry Products Market
Baby Products
AI Smart Baby Monitors Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Baby Changing Light Market
Baby Products
South Africa Baby Care Products Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Cloth Diapers Market