
 Diaper Bag Market | 2026-2036
Diaper Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Diaper Bag Market Intelligence
Smart textile integration and USB-enabled charging compartments is rewriting how diaper bags function as connected parenting accessories. Freshly Picked leverages its direct-to-consumer channel to sustain margin control across premium leather collections. Skip Hop anchors mass-market penetration through big-box retail partnerships and ergonomic design specialization. JuJuBe competes on antimicrobial fabric technology and machine-washable construction standards.
A diaper bag constitutes a portable storage system engineered from woven synthetics, treated canvas, or full-grain leather, typically featuring thermal insulation pockets, wipe-clean linings, and stroller-clip hardware designed to organize infant supplies during transit. Polyester dominates material volume due to cost scalability and water-resistant coating compatibility, while leather commands premium positioning through durability signaling and aesthetic differentiation. Backpack configurations lead type-based demand by distributing weight across dual straps for caregivers managing multiple children, whereas tote formats retain urban professional appeal through office-appropriate silhouettes.
The US Consumer Product Safety Commission enforces flammability and small-part choke-hazard standards that dictate zipper pull and lining material selections, while REACH restrictions in Europe limit phthalate content in PVC-coated fabrics and synthetic leather alternatives. California's Proposition 65 labeling requirements create compliance complexity for brands distributing across multiple state jurisdictions. Stakeholders must monitor evolving chemical disclosure mandates and material traceability expectations as sustainability credentials increasingly influence caregiver purchase decisions.
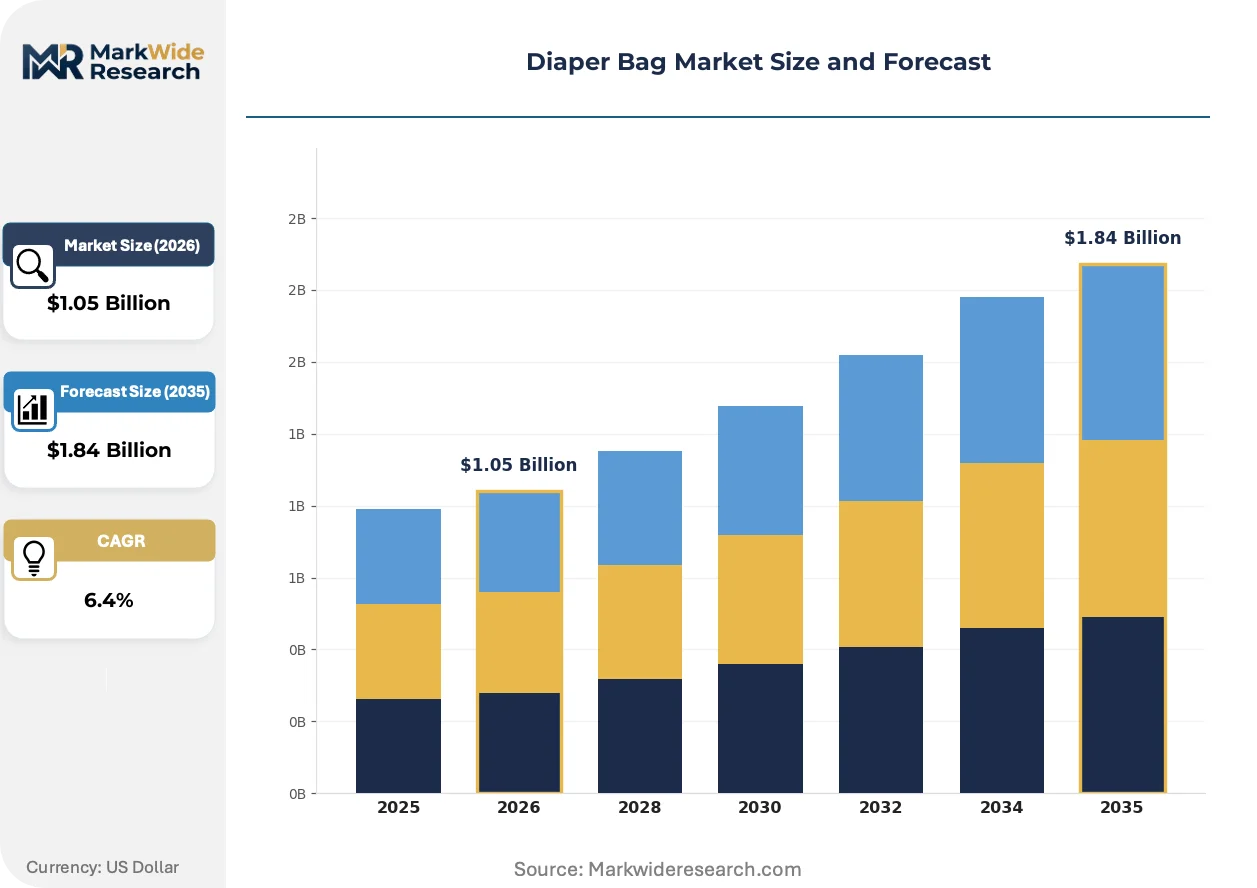
Market Dynamics
REACH chemical disclosure mandates and California Proposition 65 labeling requirements are forcing material substitutions across synthetic leather and coated fabric supply chains, compressing margins for manufacturers dependent on PVC-based constructions while creating compliance arbitrage for early reformulators.
Growth Catalysts
- USB-Enabled Smart Compartments:Integrated charging ports and thermal regulation modules are virtualizing diaper bags into connected parenting hubs, pulling demand from tech-forward millennial caregivers in urban United States clusters.
- REACH Compliance Arbitrage:European phthalate restrictions are accelerating adoption of bio-based polyurethane coatings and silicone-treated natural fibers among export-oriented manufacturers.
- Dual-Income Household Density:Professional caregiver segments in Germany and China are prioritizing backpack configurations with laptop sleeves and stroller-clip hardware, expanding addressable use cases beyond infant transit.
Market Restraints
- Petrochemical Input Volatility:Polyester resin and synthetic rubber prices fluctuate with crude oil benchmarks, compressing margin stability for mass-market producers dependent on coated fabric constructions.
- Concentrated Hardware Sourcing:Zinc-alloy zipper pulls and stroller-clip mechanisms concentrate in Guangdong Province manufacturing clusters, exposing brands to single-region supply disruption risk.
- Leather Substitute Performance Gap:PU-based vegan alternatives exhibit accelerated surface cracking under UV exposure and repeated flex cycling, limiting premium positioning durability claims.
Strategic Opportunities
- Antimicrobial Fabric Certification:Silver-ion and copper-thread textile treatments are creating white space for hospital-grade hygiene positioning among immunocompromised infant caregivers.
- Direct-to-Consumer Channel Expansion:Owned digital storefronts enable margin capture previously ceded to big-box retail, with personalization engines driving conversion in United Kingdom and Australian markets.
- Modular Interior Systems:Magnetic divider panels and removable insulated pods are converging with luggage industry design language, attracting frequent-traveler parent segments.
Industry Challenges
- Flammability Testing Bottlenecks:US Consumer Product Safety Commission certification timelines for novel bio-based foam insulations extend 14-22 weeks, delaying seasonal product launches.
- Cross-Border Chemical Documentation:Divergent state-level disclosure requirements between California, New York, and Washington create compliance fragmentation for unified national inventory strategies.
- Skilled Pattern-Maker Scarcity:Technical expertise in ergonomic weight-distribution engineering for backpack configurations concentrates among aging cohorts in Italian and Portuguese leather goods regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaper Bag Market |
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Backpack, Tote, Messenger, Clutch Material: Canvas, Polyester, Leather, Nylon Feature: Insulated, Waterproof, Ergonomic, Expandable Customer Type: Parents, Caregivers, Nurseries, Retailers |
| Companies Covered | Freshly Picked, Lululemon, Itzy Ritzy, Mina Baie, Beis, Skip Hop, Petunia Pickle Bottom, JuJuBe, Dagne Dover, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaper Bag Market Strategic Shifts & Innovations
Smart textile integration and antimicrobial surface treatments are compressing the functional gap between parenting accessories and medical-grade equipment, while regulatory chemical bans are accelerating material innovation cycles.
Embedded sensor arrays monitoring bottle temperature and diaper inventory levels are virtualizing traditional storage compartments into data-generating parenting infrastructure. Early adopters in South Korea and Scandinavian urban centers are beta-testing Bluetooth-enabled weight sensors that sync with caregiver smartphones. This sensor integration is virtualizing the competitive basis of diaper bag selection from aesthetic preference toward quantified caregiving efficiency metrics.
EU REACH Annex XVII restrictions on organotin stabilizers in PVC-coated fabrics are forcing wholesale reformulation of synthetic leather alternatives used in mid-tier product lines. Manufacturers serving European export markets are accelerating migration to water-based polyurethane dispersions and bio-derived plasticizers. Small-batch Italian producers are capturing premium positioning by marketing chrome-free vegetable-tanned leather constructions that preempt anticipated regulatory expansion.
Subscription-based accessory replenishment models are displacing transactional retail relationships among repeat-purchase caregivers. Direct-to-consumer brands are bundling insulated bottle sleeves and antimicrobial changing mats into quarterly delivery cycles, locking in lifetime value metrics previously unattainable through single-unit sales. This behavioral shift concentrates in United States coastal metropolitan markets where convenience premium tolerance exceeds 40 percent above standard retail pricing.
Diaper Bag Market Segmentation
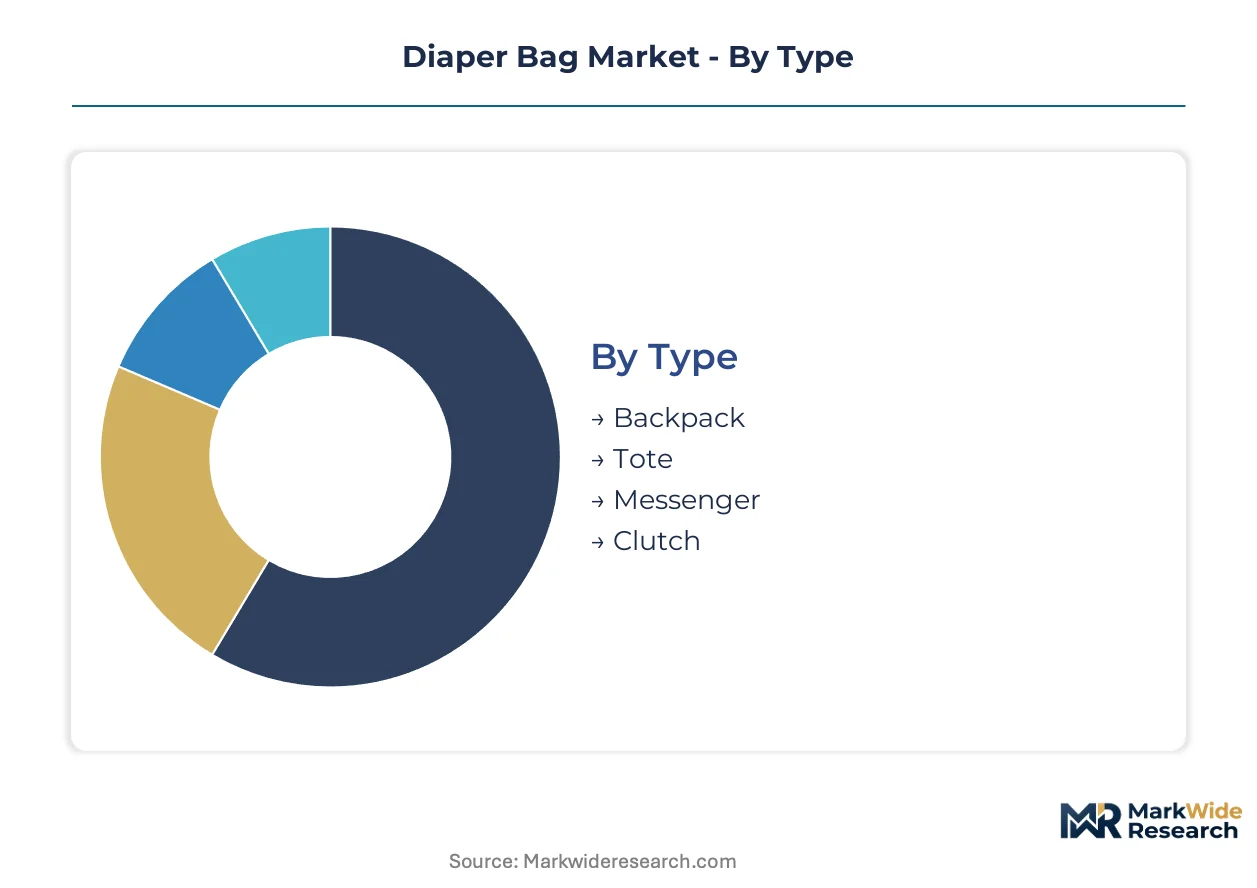
Diaper bag segmentation reveals distinct service and replacement cycles across configurations. Material durability and feature complexity drive divergent warranty claim patterns and accessory attachment rates that reshape lifetime value calculations for manufacturers.
Type:
After-sales-service intensity varies sharply by carrying configuration, with backpack formats generating hardware replacement requests at triple the rate of clutch styles due to load-bearing stress on strap connectors and zipper assemblies.
- Backpack:Dual-strap weight distribution systems incorporate reinforced stitching at shoulder yoke junctions and sternum stabilizers. Demand concentrates among dual-income households in Germany and the United States where caregivers transport multiple children and laptop equipment simultaneously. Strap hardware fatigue drives replacement part orders concentrated 18-24 months post-purchase.
- Tote:Single-shoulder silhouettes with reinforced base panels target urban professionals seeking office-appropriate aesthetics. China and United Kingdom metropolitan clusters show preference for leather-constructed variants with detachable stroller clips. After-sales volume centers on handle attachment reinforcement and interior lining replacement.
- Messenger:Cross-body sling configurations with quick-access front compartments appeal to secondary caregivers and grandparents. Service intensity remains moderate with focus on buckle mechanism longevity.
- Clutch:Compact wristlet formats for short-duration outings carry minimal hardware and lowest service incident rates. Replacement demand concentrates on cosmetic damage rather than functional failure.
By volume, Backpack leads. By growth pace, Tote configurations are expanding most quickly among professional caregiver segments.
Material:
Cost tier stratification separates premium positioning from mass-market penetration, with raw material sourcing geography and treatment complexity determining margin structure and supplier consolidation patterns.
- Polyester:Woven synthetic base with polyurethane coating dominates unit volume through cost scalability and water-resistant performance. Guangdong Province manufacturing clusters supply coated fabric to mass-market brands serving United States big-box retail. Margin compression from petrochemical input volatility constrains premium positioning.
- Leather:Full-grain and top-grain constructions signal durability and aesthetic differentiation in premium tiers. Italian and Portuguese tanneries supply vegetable-tanned variants anticipating REACH regulatory expansion. After-sales service includes conditioning treatment guidance and scratch repair protocols.
- Canvas:Heavyweight cotton duck with waxed or silicone treatments occupies mid-tier positioning. Bio-based coating migration accelerates among European export-oriented producers.
- Nylon:Ripstop weaves with ballistic denier ratings target lightweight durability segments. Service intensity centers on abrasion resistance claims and coating delamination issues.
By volume, Polyester leads. By growth pace, Leather is gaining share fastest among sustainability-conscious premium purchasers.
Feature:
Application-specific functionality determines replacement cycle timing and accessory bundling potential, with thermal regulation and expandability commanding service complexity premiums over passive protection features.
- Insulated:Thermal pocket constructions with closed-cell foam and reflective liners maintain bottle temperature across transit durations. Demand concentrates in climates with extreme seasonal variation and among immunocompromised infant caregivers. Service claims involve seam seal integrity and zipper corrosion from condensation exposure.
- Waterproof:Seam-sealed constructions with coated zippers and welded base panels target outdoor-active parent segments in Pacific Northwest United States and Scandinavian markets. Warranty claims center on coating delamination and tape adhesive failure.
- Ergonomic:Weight-distribution engineering with lumbar padding and breathable back panels. Pattern-maker expertise scarcity in Italian leather regions constrains supply expansion.
- Expandable:Gusseted side panels and modular attachment points accommodate variable load requirements. Service intensity involves zipper track alignment and expansion mechanism durability.
By volume, Insulated leads. By growth pace, Expandable configurations show steepest expansion trajectory among frequent-traveler parent segments.
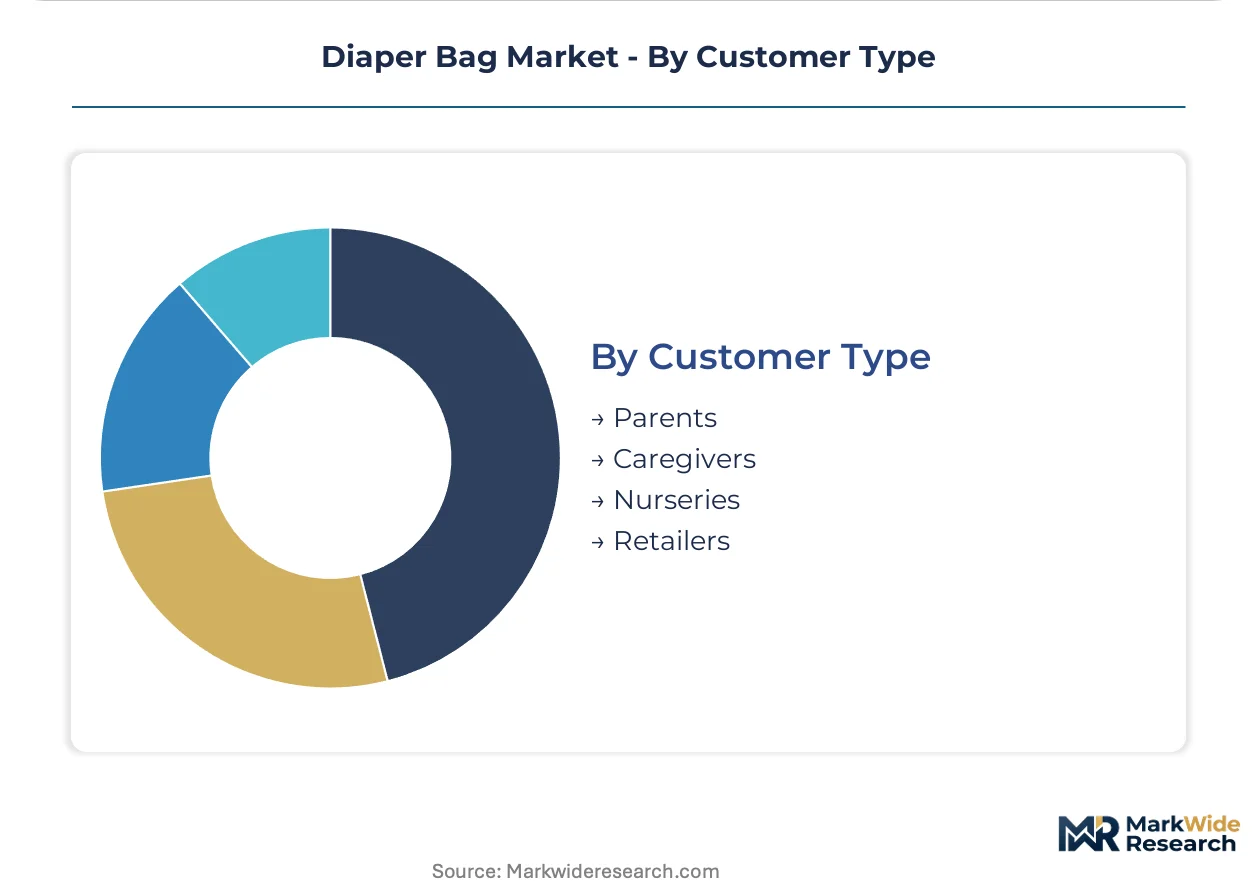
Customer Type:
Procurement patterns diverge across institutional and individual purchasers, with volume concentration and decision-maker identity reshaping distribution channel configuration and margin capture mechanisms.
- Parents:Primary caregivers making individual purchase decisions prioritize multifunctionality and aesthetic coordination with personal accessories. Direct-to-consumer channels capture margin previously ceded to retail intermediaries in United Kingdom and Australian markets.
- Caregivers:Extended family and paid childcare providers represent gift-recipient and secondary-purchaser segments with lower price sensitivity and reduced feature research intensity.
- Nurseries:Institutional procurement from childcare facilities concentrates volume in standardized configurations with antimicrobial certification requirements and bulk replacement scheduling.
- Retailers:Inventory acquisition decisions by big-box and specialty chains determine production batch sizing and seasonal launch timing for manufacturer portfolios.
By volume, Parents lead. By growth pace, Nurseries are climbing the fastest as institutional hygiene standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-income professional caregivers concentrate in urban United States coastal metros, German industrial centers, and Chinese tier-one cities, driving premium backpack configurations with laptop integration and stroller-clip hardware.
United States
Millennial and Gen-Z parents in New York, Los Angeles, and Seattle metros prioritize USB-enabled charging compartments and smart textile integration. The US Consumer Product Safety Commission enforces flammability standards dictating zipper pull and lining material selections. Guangdong Province manufacturing clusters supply coated polyester fabrics to mass-market brands serving Walmart and Target retail networks.
Germany
Professional caregiver segments in Munich, Hamburg, and Frankfurt demand ergonomic backpack configurations with lumbar padding and breathable back panels. REACH Annex XVII restrictions on organotin stabilizers in PVC-coated fabrics accelerate bio-based polyurethane adoption among export-oriented manufacturers. Small-batch Italian tanneries supply vegetable-tanned leather variants to premium positioning brands anticipating regulatory expansion.
China
Domestic consumption in Shanghai, Beijing, and Shenzhen concentrates in leather-constructed tote formats with detachable stroller clips for urban professionals. The country's national product safety regulator enforces GB standards for flammability and small-part choke hazards. Yangtze River Delta manufacturing clusters produce zinc-alloy zipper hardware and thermal insulation pocket assemblies for global brand supply chains.
United Kingdom
Direct-to-consumer channel adoption concentrates in London, Manchester, and Edinburgh metropolitan markets where personalization engines drive conversion. ECHA REACH compliance requirements limit phthalate content in synthetic leather alternatives distributed across European Union member states. Birmingham-based logistics hubs coordinate seasonal inventory flows for big-box retail partnerships.
Australia
Outdoor-active parent segments in Sydney, Melbourne, and Brisbane prioritize waterproof seam-sealed constructions with welded base panels. The Therapeutic Goods Administration (TGA) antimicrobial certification framework creates compliance pathways for silver-ion fabric treatments targeting immunocompromised infant caregivers. Melbourne design studios specialize in modular interior systems with magnetic divider panels for frequent-traveler segments.
Diaper Bag Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. Mass-market penetration anchors through big-box retail partnerships with ergonomic design specialization, while premium positioning sustains margin control through direct-to-consumer digital storefronts. Three archetypes dominate: leather-focused heritage fabricators, synthetic-material volume producers, and technology-integrated smart accessory developers. Competitive moves concentrate on portfolio diversification into antimicrobial fabric certifications and geographic expansion through owned digital channels.
Within the premium leather tier, Freshly Picked and Mina Baie exemplify direct-to-consumer margin capture strategies. Skip Hop occupies a position representing mass-market penetration through big-box retail partnerships. JuJuBe anchors the technology-integrated vector with antimicrobial fabric specialization. These three archetypes illustrate how channel control and product specialization create divergent competitive positions across pricing tiers.
| Leading Market Players |
|---|
| Freshly Picked |
| Lululemon |
| Itzy Ritzy |
| Mina Baie |
| Beis |
| Skip Hop |
| Petunia Pickle Bottom |
| JuJuBe |
| Dagne Dover |
| Others |
Cost & Logistics Intelligence
Guangdong Province manufacturing clusters anchor global coated polyester fabric capacity, concentrating supply-side leverage among mass-market producers serving Walmart and Target retail networks while compressing margin capture for brands without direct-to-consumer channel control.
Pricing Analysis
Cost-plus contracts indexed to polyester resin and synthetic rubber benchmarks dominate mass-market procurement, with three-tier pricing structure across premium leather, standard canvas, and economy polyester levels. Price differentiation rests on certification grade—REACH-compliant bio-based coatings command 15-25% premiums over PVC-based alternatives—and brand equity in direct-to-consumer channels. Pricing pressure stems from petrochemical input volatility, with crude-linked raw materials eroding margin stability for coated fabric producers. Mass-market big-box retail buyers exhibit highest price sensitivity, while premium direct-to-consumer segments tolerate convenience premiums exceeding standard retail pricing.
Supply Chain Analysis
Contract manufacturing concentrates among Yangtze River Delta and Pearl River Delta industrial zones, with specialized producers in Dongguan and Suzhou holding dominant capacity for zinc-alloy hardware and thermal insulation assemblies. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks for polyester resin, Italian and Portuguese tanneries for vegetable-tanned leather, and Australian cotton for waxed canvas constructions. Single-region vulnerability in Guangdong Province zipper hardware exposes brands to supply disruption risk. Distribution runs through Birmingham-based European logistics hubs for seasonal inventory coordination and direct-to-consumer fulfillment centers in coastal United States metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USB-enabled smart compartments and antimicrobial fabric certifications are disrupting traditional competitive positioning, with regulatory chemical bans accelerating material innovation cycles that favor early reformulators over legacy PVC-dependent producers.
For Market Incumbents: Build certification moats around REACH-compliant bio-based polyurethane coatings and FDA-recognized antimicrobial silver-ion treatments to defend against emerging direct-to-consumer entrants with sustainability-first positioning. Deepen backward integration into Italian vegetable-tanned leather supply to preempt premium tier erosion, while expanding owned digital storefronts to capture margin previously ceded to big-box retail intermediaries. For New Entrants and Emerging Players: Pursue white-space positioning in institutional nursery procurement segments, where tightening hygiene standards and bulk replacement scheduling create penetrable demand concentration absent entrenched brand loyalty. Target direct-to-consumer channels in United Kingdom and Australian metropolitan markets with personalization engines and subscription-based accessory replenishment models that lock in lifetime value metrics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors direct-to-consumer brands with captive antimicrobial fabric certification and owned manufacturing relationships over mass-market players dependent on retail channel intermediaries. Long-term viability concentrates on regulatory anticipation capabilities and material traceability infrastructure. Monitor ECHA REACH Annex XVII expansion proposals and California Proposition 65 chemical disclosure amendments as inflection indicators for premium tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Fabric Certification | Silver-ion treatments targeting immunocompromised infant caregivers unlock hospital-grade hygiene positioning and nursery procurement contracts. |
| Direct-to-Consumer Channel Expansion | Owned digital storefronts in United Kingdom and Australian markets capture margin previously ceded to big-box retail intermediaries. |
| Bio-Based Material Reformulation | Water-based polyurethane dispersions and bio-derived plasticizers preempt REACH regulatory expansion and command premium tier pricing. |
| Modular Interior System Development | Magnetic divider panels and removable insulated pods attract frequent-traveler parent segments with luggage industry design convergence. |
| Smart Textile Integration | Bluetooth-enabled weight sensors and thermal monitoring arrays virtualize diaper bags into data-generating parenting infrastructure for tech-forward millennial caregivers. |
Research Approach
Cross-validation between primary interviews with brand managers, category buyers at Target and Walmart, supply planners at Guangdong manufacturing clusters, and direct-to-consumer channel heads anchors the qualitative findings against secondary validation from customs records, Nielsen retail audit data, ECHA REACH regulatory filings, and SEC 10-K disclosures from publicly traded parent companies. Bottom-up demand modeling across type, material, feature, and customer type dimensions triangulates against top-down macroeconomic consumption indicators.
Calibration against historical volume trajectories and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include carrying configuration, material construction grade, functional feature set, and procurement channel archetype. CAGRs derive from regression analysis of correlated demographic and economic variables, with specific inputs including dual-income household density indices, petrochemical price volatility patterns, and e-commerce penetration rates in coastal metropolitan markets.
Sensitivities concentrate around REACH regulatory expansion scope, California Proposition 65 disclosure requirement divergence, and petrochemical input price volatility. Quarterly review of ECHA Annex XVII amendment proposals, state-level chemical disclosure legislation, and crude oil benchmark movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Bottle Market
Baby Products
Global Baby Product Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Shoes Market
Baby Products
Automatic Baby Swing Market
Baby Products
Baby Stroller Market
Baby Products
Potty Training Seat Market
Baby Products
Baby Sleepsuits Market
Baby Products
Global Baby Car Seats Market
Baby Products
Postpartum Products Market
Baby Products
Japan Baby Care Product Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
South Korea Baby Care Products Market
Baby Products
Baby Tableware Market
Baby Products
US Baby Care Products Market