
 Crib Mattress Market | 2026-2036
Crib Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Crib Mattress Market Analysis
Market Context
Certified pediatric sleep consultant shortages across North America is unwinding distribution bottlenecks for premium crib mattress brands. Tempur Sealy International leverages its polymer science heritage to dominate hospital and retail channels with medical-grade foam formulations. Naturepedic anchors the organic segment through GOTS-certified supply chains and transparent material sourcing. Serta Simmons Bedding competes on manufacturing scale, operating multi-facility production networks that service mass-market retailers at volume price points.
Technical Definition and Segment Structure
A crib mattress is a rectangular sleep surface designed for infants, typically measuring approximately 27.5 by 51.5 inches with thickness ranging from three to six inches, constructed from polyurethane foam, innerspring coils, or natural latex and cotton fibers to provide firm support that reduces suffocation risk while meeting dimensional standards for crib fit. The material dimension shows organic cotton and hypoallergenic constructions commanding margin premiums as parental chemical sensitivity concerns intensify, while memory foam faces scrutiny over VOC emissions despite cost advantages. The safety standard dimension has CertiPUR-US and GREENGUARD Gold certifications becoming baseline requirements for market access in premium channels, with non-toxic claims now separating viable entrants from commodity competitors.
Regulatory Framework
The US Consumer Product Safety Commission enforces 16 CFR Part 1633 flammability standards that mandate open-flame resistance testing, while the Federal Trade Commission monitors green marketing claims under its Green Guides to prevent deceptive environmental labeling. The Juvenile Products Manufacturers Association operates a voluntary certification program that many retailers require as a condition of shelf placement, effectively creating a parallel gatekeeping function beyond federal mandates. Stakeholders must monitor evolving state-level chemical disclosure laws in California and New York that extend beyond federal minimums, as these jurisdictions often preview requirements that later diffuse nationally.
Market Dynamics
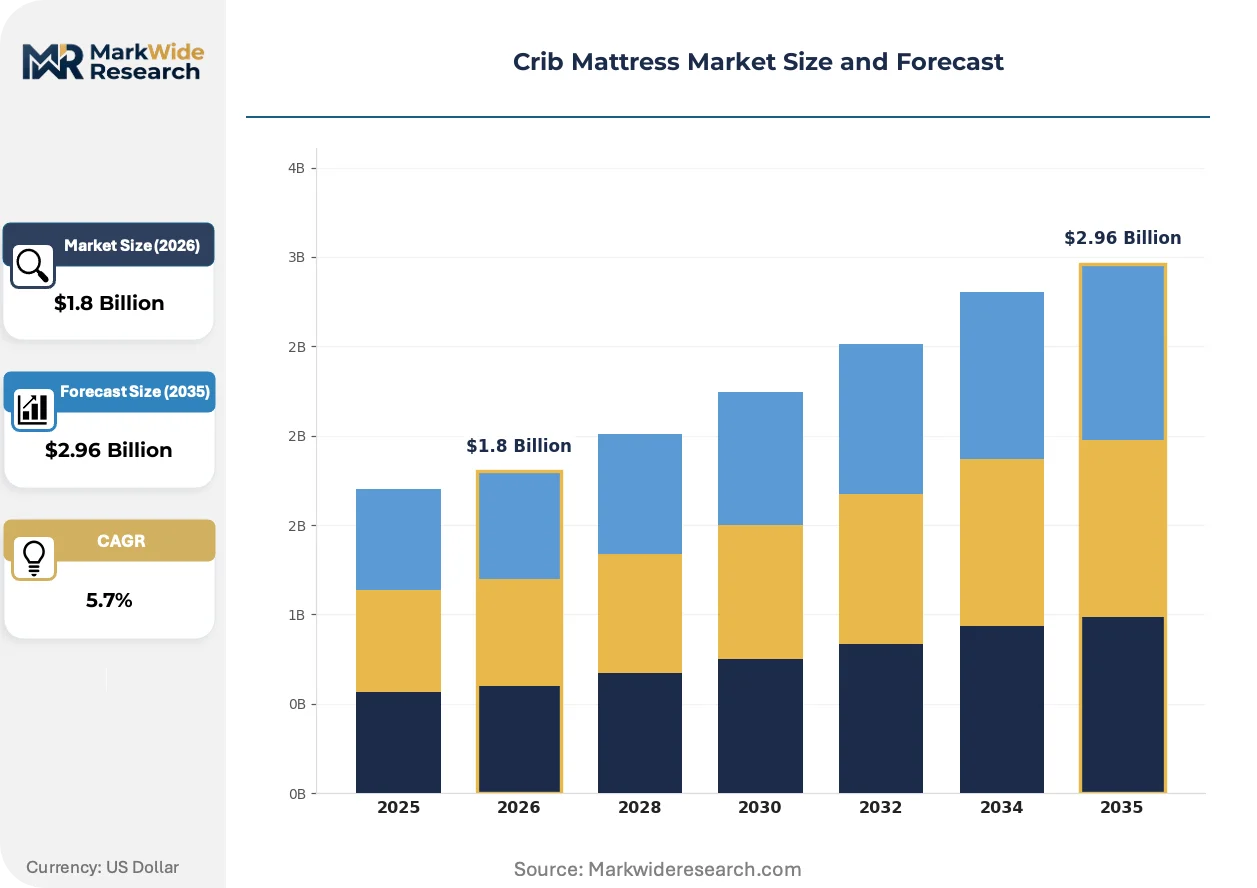
The US Consumer Product Safety Commission's updated flammability standards are compressing foam chemistry options and concentrating certified supply among polymer science specialists, while Millennial and Gen Z parent demographics are pulling demand toward organic material certifications.
Growth Catalysts
- 16 CFR Part 1633 compliance pressure:Federal open-flame resistance mandates are eliminating uncertified foam formulations and redirecting procurement toward GREENGUARD Gold and CertiPUR-US verified supply chains.
- Organic cotton supply chain maturation:GOTS-certified fiber sourcing is scaling production volumes sufficient to serve direct-to-consumer channels at competitive unit economics.
- Pediatric sleep consultant channel:Certified infant sleep specialists across the United States are creating referral-driven demand for premium firm-support constructions.
Market Restraints
- Polyurethane foam input volatility:Petrochemical feedstock price swings compress margin predictability for memory foam producers serving mass-market retail.
- Latex supply concentration:Natural rubber tapping capacity clusters in Southeast Asian plantations, exposing organic segment manufacturers to climate and labor disruption.
- Innerspring coil weight penalty:Metal component density creates freight cost disadvantages versus foam competitors in e-commerce fulfillment.
Strategic Opportunities
- California chemical disclosure preview:State-level transparency mandates extending beyond federal minimums signal national regulatory trajectory and first-mover certification advantages.
- Hospital channel penetration:Medical-grade foam formulations with antimicrobial surfaces are opening NICU and pediatric ward specification opportunities.
- Subscription mattress replacement:Recurring revenue models for timed infant growth-stage upgrades are emerging in urban health-conscious households.
Industry Challenges
- CertiPUR-US testing backlog:Laboratory capacity constraints are extending product launch timelines for new foam formulations.
- FTC Green Guide enforcement:Deceptive environmental claim monitoring is elevating legal review costs for non-toxic marketing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crib Mattress Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Memory Foam, Innerspring, Organic Cotton, Hypoallergenic Size: Standard Crib, Mini Crib, Portable Crib, Convertible Weight: Lightweight, Medium Weight, Heavy Weight, Ultra Lightweight Safety Standard: Non-Toxic, CertiPUR-US, GREENGUARD Gold, Fire Retardant |
| Companies Covered | Tempur Sealy International, Naturepedic, Serta Simmons Bedding, Colgate Mattress, Graco, Delta Children, Moonlight Slumber, Newton Baby, IKEA Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crib Mattress Market Emerging Trajectories
Material science advances and certification protocol evolution are compressing product development cycles while fragmenting competitive position between chemistry heritage and organic sourcing capabilities.
Plant-based polyurethane foam formulations derived from soybean and castor oil feedstocks are displacing petroleum-based memory foam in premium channel positioning. Urban health-conscious households are specifying these constructions at accelerating rates. This displacement is compressing incumbent petrochemical foam margins while opening specialty chemical partnerships for agricultural processor alliances.
The Federal Trade Commission's Green Guides enforcement is tightening substantiation requirements for biodegradable and recyclable claims in juvenile product marketing. Manufacturers must now maintain documentary evidence for environmental attribute statements or face civil penalty exposure. Direct-to-consumer brands with transparent supply chain documentation are capturing shelf placement advantages at specialty retailers.
Urban Millennial parents are consolidating purchase decisions around pediatric sleep consultant recommendations, compressing traditional retail discovery channels. Hospital-affiliated specialists and private practice consultants are displacing big-box floor sales as the primary influence node. This concentration is most visible in coastal United States metropolitan markets with high dual-income professional household density.
Crib Mattress Market Segmentation
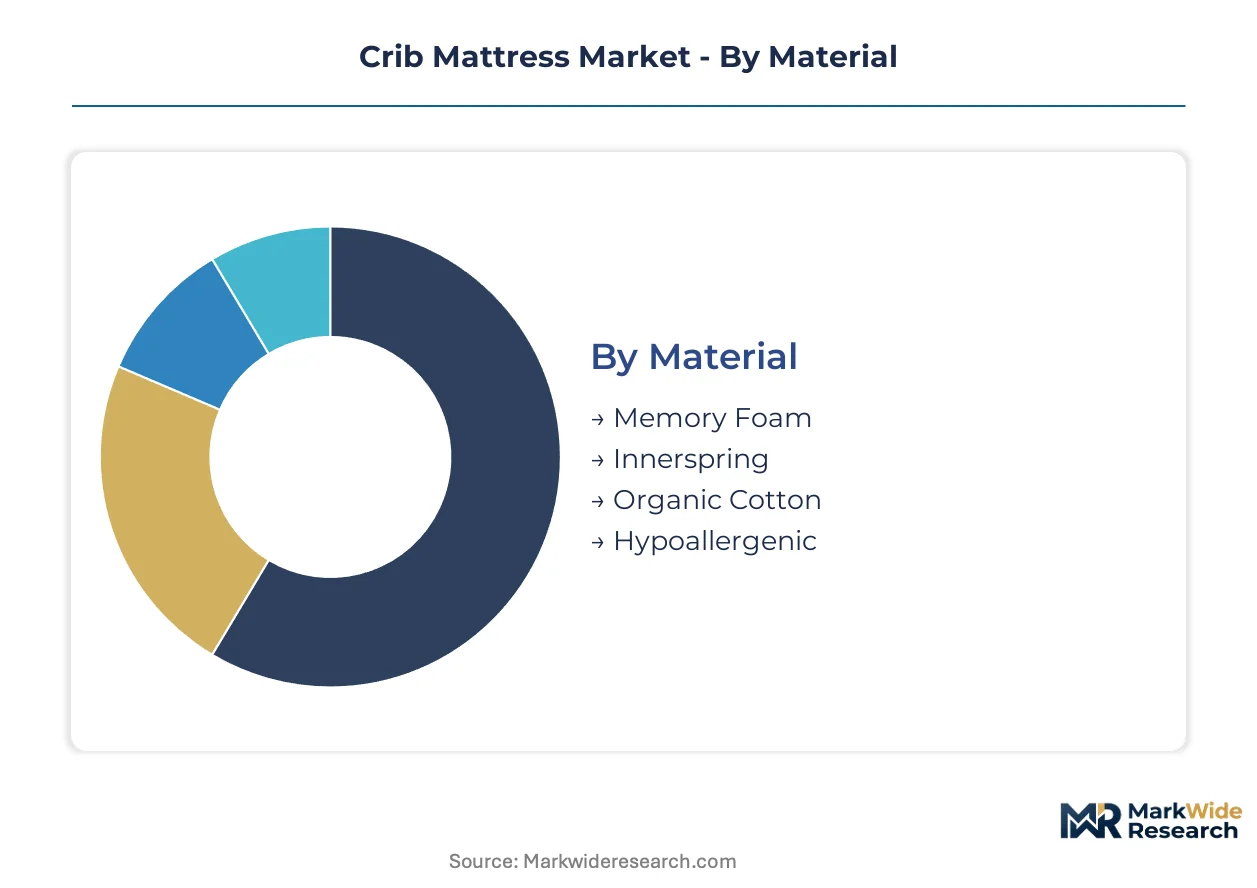
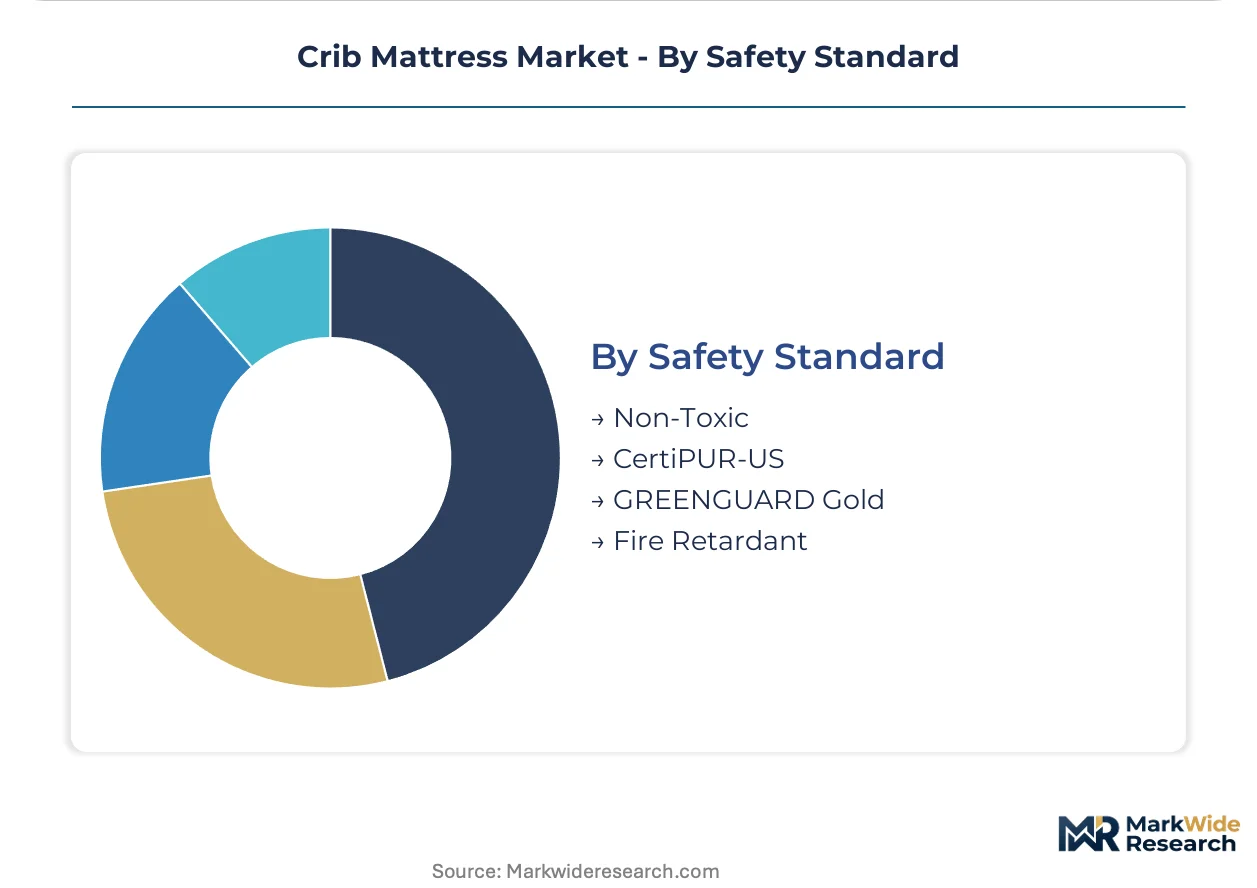
Material composition and safety certification tiers channel crib mattresses into distinct retail ecosystems. Premium direct-to-consumer platforms favor certified organic constructions, while mass-market retail concentrates on standardized foam formulations at volume price points.
Material:
Channel mix splits sharply between hospital and retail procurement, with polymer science specialists dominating institutional accounts and organic fiber suppliers capturing urban direct-to-consumer growth.
- Memory Foam:Polyurethane formulations with viscoelastic properties conform to infant body contours while maintaining firm support profiles. Hospital NICU specifications and mass-market retail chains concentrate demand here, though CertiPUR-US testing backlogs constrain new supplier entry.
- Organic Cotton:GOTS-certified fiber batting layered over firm support cores eliminates synthetic chemical exposure. Coastal United States metropolitan markets with high dual-income professional household density drive expansion, with pediatric sleep consultant referrals accelerating channel penetration.
- Innerspring:Steel coil support systems with fiber padding deliver traditional firmness at lower unit costs. Big-box retailers and secondary market resellers maintain inventory concentration.
- Hypoallergenic:Synthetic fiber constructions with dust mite barriers and moisture-wicking covers target allergy-sensitive households. Specialty medical supply distributors and online health product platforms channel demand.
Memory foam dominates installed base through hospital and mass retail penetration. Organic cotton is where expansion concentrates.
Size:
Dimensional specifications determine fulfillment economics and replacement frequency, with standard sizing enabling inventory pooling while mini formats reduce shipping cost burdens.
- Standard Crib:27.5 by 51.5 inch dimensions compliant with full-size crib regulations. This format anchors hospital procurement contracts and big-box retail assortment planning.
- Mini Crib:Reduced footprint designs for urban apartments and secondary sleeping locations. Space-constrained households in dense metropolitan markets drive fastest volume expansion.
- Portable Crib:Foldable or rollable constructions for travel and grandparent care settings. Travel gear specialty retailers and online marketplaces channel distribution.
- Convertible:Adjustable dimensions transitioning from crib to toddler bed configurations. Extended-use value propositions concentrate in premium direct-to-consumer brands.
Standard crib sizing commands procurement volume through institutional contracts. Mini crib formats are gaining share fastest among urban household formations.
Weight:
Fulfillment cost structures and sheet change ergonomics segment parental preference, with e-commerce penetration favoring lighter constructions that reduce last-mile delivery expense.
- Lightweight:Under 10 pound constructions enabling single-handed sheet changes and lower shipping costs. Direct-to-consumer brands targeting subscription replacement models concentrate here.
- Ultra Lightweight:Sub-7 pound foam-core designs for travel cribs and portable applications. Travel gear specialists and urban rental markets channel demand.
- Medium Weight:10-15 pound range balancing durability with manageable handling. Mass-market retail assortment centers on this tier.
- Heavy Weight:Over 15 pound innerspring and dense foam constructions emphasizing longevity. Secondary market resale and durability-focused consumer segments sustain demand.
Lightweight constructions dominate new product development pipelines. Ultra lightweight formats show steepest expansion trajectory in travel and rental applications.
Safety Standard:
Certification tier serves as primary price segmentation mechanism, with baseline compliance separating mass-market viability from premium positioning.
- GREENGUARD Gold:Stringent VOC emission limits for sensitive environments including schools and healthcare facilities. Hospital channel specifications and affluent urban households concentrate demand here.
- CertiPUR-US:Foam content certification excluding heavy metals and certain flame retardants. Premium retail and direct-to-consumer platforms require this as baseline shelf placement condition.
- Non-Toxic:Marketing claims of chemical-free construction without third-party certification. FTC Green Guide enforcement is elevating substantiation requirements and legal exposure for this segment.
- Fire Retardant:16 CFR Part 1633 compliance constructions using barrier technologies or inherent fiber properties. Mass-market retail minimum requirements sustain volume here despite parental chemical concern migration.
GREENGUARD Gold commands margin premiums through institutional and affluent household targeting. CertiPUR-US is where manufacturer investment concentrates as market access gatekeeper.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Consumer Product Safety Commission anchors regulatory influence through 16 CFR Part 1633 flammability mandates, concentrating certified manufacturing capacity and premium brand headquarters in North American metropolitan corridors.
United States
Millennial and Gen Z parent demographics in coastal metropolitan markets are specifying organic cotton and GREENGUARD Gold certified constructions through pediatric sleep consultant referrals. The Federal Trade Commission's Green Guides enforcement elevates legal substantiation requirements for non-toxic marketing claims. Brooklyn and Los Angeles anchor direct-to-consumer brand headquarters and organic fiber finishing operations serving health-conscious urban households.
Canada
Health Canada and the PMRA maintain aligned flammability standards with US benchmarks, enabling cross-border supply chain integration for certified foam producers. Dual-income professional households in Toronto and Vancouver concentrate demand for premium hypoallergenic constructions. The Greater Toronto Area hosts distribution infrastructure serving domestic retail and US export channels.
Germany
ECHA REACH chemical registration requirements and the EU Green Deal's circular economy mandates are accelerating plant-based polyurethane foam adoption among sustainability-positioned brands. Bavaria and Baden-Württemberg concentrate specialty chemical research partnerships between agricultural processors and polymer formulators. Stuttgart's industrial cluster advances bio-based feedstock integration for premium juvenile product specifications.
China
SAMR's national standards for juvenile products and GB flammability protocols are consolidating manufacturing capacity among certified export-oriented fabricators. The Yangtze River Delta and Pearl River Delta host foam molding and textile finishing operations serving North American and European brand OEM contracts. Zhejiang Province specializes in organic cotton processing infrastructure scaling to meet GOTS-certified export demand.
India
BIS certification requirements for infant products and expanding urban middle-class formations are creating domestic market infrastructure for standard and premium tier mattresses. Maharashtra and Gujarat concentrate polyurethane foam production for mass-market retail distribution. Mumbai's specialty retail corridors and Bangalore's direct-to-consumer startup ecosystem channel international brand penetration and domestic premium positioning.
Crib Mattress Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with polymer science heritage separating hospital-channel specialists from mass-market volume producers. The market structure fragments across three tiers: certified organic direct-to-consumer brands commanding margin premiums, medical-grade foam specialists dominating institutional procurement, and scale manufacturers serving big-box retail at compressed price points. Strategic moves concentrate on certification acquisition for market access and supply chain partnerships for organic fiber security.
Within the polymer science specialist tier, Tempur Sealy International represents medical-grade formulation heritage, while Naturepedic exemplifies organic certification anchoring through transparent GOTS-certified sourcing. Serta Simmons Bedding occupies the scale-driven position, leveraging multi-facility production networks for mass-market retail service.
| Leading Market Players |
|---|
| Tempur Sealy International |
| Naturepedic |
| Serta Simmons Bedding |
| Colgate Mattress |
| Graco |
| Delta Children |
| Moonlight Slumber |
| Newton Baby |
| IKEA Systems |
| Others |
Supply Flow & Price Mechanics
GREENGUARD Gold certification gates both supplier qualification and price differentiation simultaneously, concentrating premium positioning among polymer science specialists with laboratory-verified emission controls while compressing uncertified competitors into commodity tiers. This dual-gate function elevates input costs for verified foam formulations and organic fiber constructions, transmitting certification investment into retail price architecture.
Pricing Analysis
Coastal United States metropolitan markets command 40-60 percent premiums over mass-market retail channels for identical certified constructions, with pediatric sleep consultant referrals reinforcing geographic price stratification. Three-tier pricing structure across premium, standard, and economy levels separates GOTS-certified organic cotton from CertiPUR-US foam and uncertified innerspring alternatives. Cost compression in mass-market memory foam is intensifying because petrochemical feedstock volatility erodes margin predictability for volume producers. Big-box retail procurement teams exhibit highest price sensitivity, while hospital channel buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Inventory cycles for GOTS-certified organic cotton extend 8-12 weeks beyond synthetic alternatives, constraining just-in-time fulfillment for direct-to-consumer brands and elevating working capital requirements. Manufacturing concentration clusters in China, the United States, and India, with Zhejiang Province and the American Southeast hosting complementary foam molding and textile finishing operations. Raw material supply draws from Southeast Asian natural rubber plantations, domestic petrochemical complexes, and certified organic cotton cooperatives across India and Turkey. Single-source vulnerability in natural latex tapping exposes organic segment producers to climate disruption. Distribution runs through hospital procurement contracts, specialty retailer networks, and direct-to-consumer platforms with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric sleep consultant referral networks function as platform intermediaries, consolidating purchase influence and creating interoperability requirements between mattress specifications and infant sleep training protocols. This ecosystem shift rewards brands with certified consultant education programs and hospital affiliation pathways.
For Market Incumbents: Consolidate certification moats by accelerating GREENGUARD Gold and GOTS verification across full product lines before state-level chemical disclosure laws extend beyond federal minimums. Acquire organic cotton processing capacity or secure long-term supply agreements with certified cooperatives to defend against fiber cost inflation. Channel control through exclusive pediatric sleep consultant partnerships offers defensive leverage against direct-to-consumer entrants.
For New Entrants and Emerging Players: Subscription mattress replacement services for timed infant growth-stage upgrades represent a service-layer gap where incumbents under-serve urban dual-income households. Target mini crib formats in space-constrained metropolitan markets with ultra-lightweight foam-core constructions optimized for e-commerce fulfillment. Go-to-market through hospital-affiliated pediatric sleep consultants bypasses big-box retail gatekeeping.
For Investors and Strategic Acquirers: FTC Green Guide enforcement reshapes the acquisition landscape by elevating legal substantiation costs for environmental marketing claims and penalizing unsubstantiated non-toxic positioning. Long-term viability favors certified organic specialists with documentary supply chain transparency over commodity foam producers facing petrochemical margin compression. Watch California chemical disclosure law diffusion as the signal indicating national regulatory trajectory and first-mover certification advantage crystallization.
| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Acquisition | Organic fiber verification unlocks pediatric sleep consultant referral channels and premium direct-to-consumer positioning. |
| Backward Integration into Cotton Processing | Captive supply of certified organic batting reduces input cost volatility and accelerates product development cycles. |
| Hospital Channel Partnership | NICU specification contracts anchor medical-grade credibility and create downstream retail recommendation spillover. |
| Subscription Replacement Model Launch | Recurring revenue from timed infant growth-stage upgrades captures lifetime value in urban health-conscious households. |
| Plant-Based Polyurethane Transition | Soybean and castor oil feedstock partnerships align with EU Green Deal trajectories and coastal United States consumer preferences. |
Methodological Framework
Initial hypotheses were tested against primary input from certified pediatric sleep consultants, juvenile product procurement managers at hospital systems, foam formulation chemists at polymer science specialists, and category buyers at mass-market retailers and refined through secondary validation. Primary fieldwork encompassed structured interviews and channel observation across direct-to-consumer brand headquarters in Brooklyn and Los Angeles, manufacturing facilities in the American Southeast, and textile finishing operations in Zhejiang Province. Secondary sources included US Consumer Product Safety Commission flammability testing records, Federal Trade Commission Green Guide enforcement actions, GOTS certification databases, and trade customs data for foam and fiber imports. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates.
Variance decomposition across material composition, safety certification tier, distribution channel, and geographic market identified segment-level growth drivers and margin structures throughout the forecast period. Segmentation dimensions encompassed memory foam, organic cotton, innerspring, and hypoallergenic constructions; standard, mini, portable, and convertible sizing; and GREENGUARD Gold, CertiPUR-US, non-toxic, and fire-retardant certification tiers. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points and demographic cohort transitions. Industry-specific inputs included pediatric sleep consultant referral network expansion rates and state-level chemical disclosure law adoption timelines.
Underlying assumptions cover continued 16 CFR Part 1633 enforcement stringency, organic cotton supply chain scaling, and millennial parent preference persistence for certified non-toxic constructions, with deviation risk concentrated in petrochemical feedstock price volatility and FTC green marketing enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Products Detergents Market
Baby Products
LAMEA Baby Care Products Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Stroller Rental Market
Baby Products
Baby Pacifier Market
Baby Products
Diaper Bag Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Postpartum Products Market
Baby Products
Baby Wipes Market
Baby Products
Pregnancy Products Market
Baby Products
Baby High Chair Market
Baby Products
Automatic Baby Swing Market
Baby Products
Baby Bouncers Market
Baby Products
Cloth Diapers Market
Baby Products
Japan Baby Care Product Market
Baby Products
Global Pregnancy Pillow Market