

Maternity Products Market Size, Share, and Industry Trends Forecast 2026-2036
Maternity Products Market Insights
Certified lactation consultants and specialized maternity garment technicians is reorganizing how brands design and validate product lines. Seraphine leverages its British design heritage to dominate occasion-wear segments for professional settings. Kindred Bravely anchors its competitive position through direct-to-consumer channel control and community-driven sizing innovation. Gap sustains manufacturing scale across its global supplier network to occupy mid-market price tiers.
Maternity products encompass engineered garments, support devices, and lactation accessories designed with adjustable compression ratings, breathable textile blends, and ergonomic load-distribution geometry to accommodate physiological changes during gestation and recovery. Their commercial purpose centers on maintaining maternal mobility, reducing musculoskeletal strain, and enabling breastfeeding compliance in clinical and domestic environments. Maternity wear and nursing bras currently lead volume contribution due to repeat-purchase frequency and fashion-cycle turnover, while pregnancy pillows and support belts capture expanding margin pools as consumers prioritize sleep quality and pelvic stabilization. Online retailers are outpacing specialty stores in growth velocity, though pharmacies retain structural importance for postpartum medical-grade belts and compression garments.
The FDA regulates postpartum support belts and nursing accessories as Class I or II medical devices, requiring 510(k) clearance for compression and structural claims, while the EU MDR imposes biocompatibility testing and clinical evaluation on maternity products marketed with therapeutic intent. BIS certification in India and GB standards in China further fragment compliance requirements for brands pursuing multi-country distribution. Stakeholders must monitor evolving textile safety standards and telehealth integration opportunities as postnatal care delivery models shift toward remote monitoring and subscription-based replenishment services.
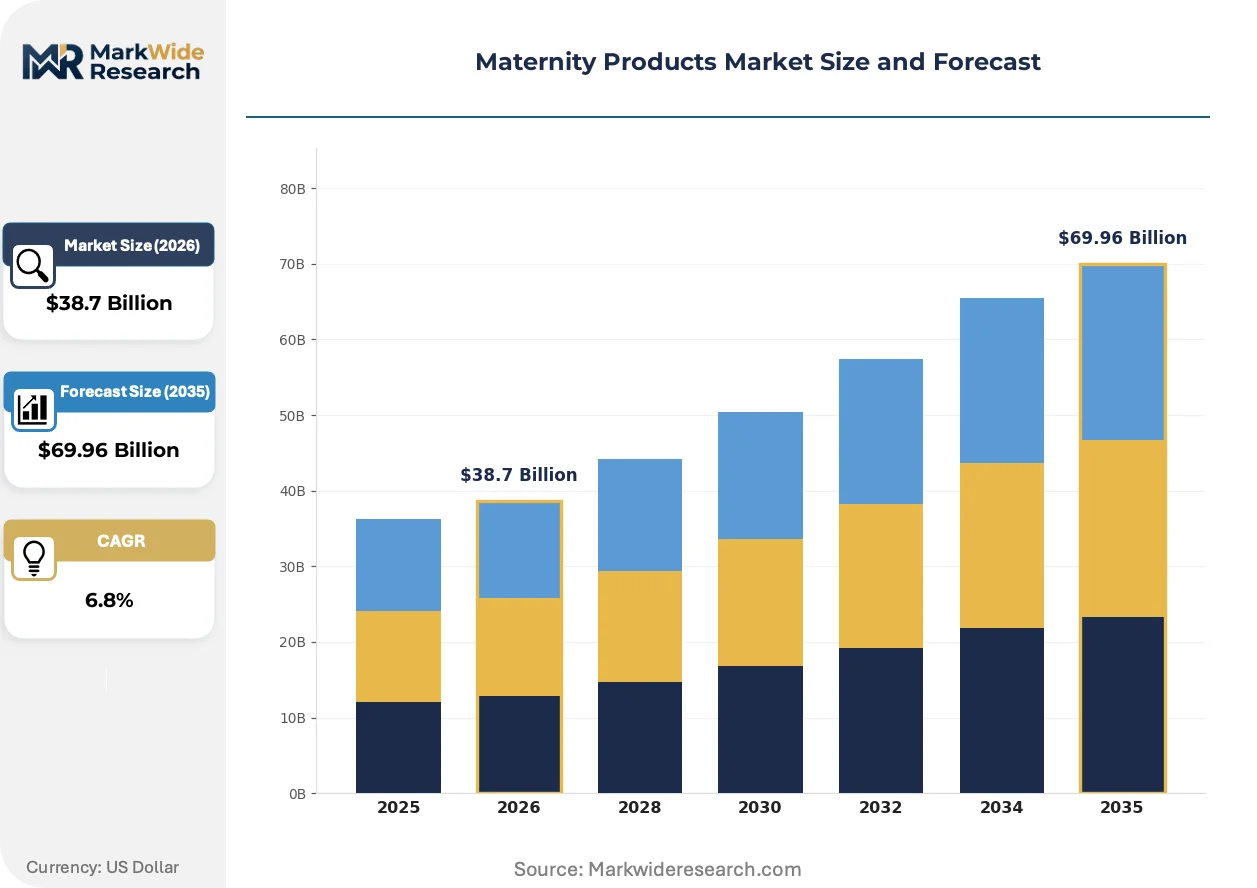
Market Dynamics
Digital-native millennial parents are compressing purchase cycles and forcing maternity brands to rebuild distribution architectures around direct-to-consumer fulfillment and subscription-based replenishment models.
Growth Catalysts
- EU MDR compliance mandates:Biocompatibility testing requirements for therapeutic maternity devices are elevating entry barriers and rewarding pre-certified incumbents with shelf-space advantages in European pharmacies.
- Telehealth integration:Remote postnatal monitoring platforms are creating bundled demand for smart nursing accessories that transmit lactation metrics to maternal health dashboards.
- Compression textile innovation:Breathable microfiber blends with graduated compression ratings are expanding addressable demand beyond clinical postpartum recovery into preventive maternity wellness.
Market Restraints
- Raw material concentration:Medical-grade elastic fiber production concentrates in Guangdong province, exposing brands to input volatility and tariff exposure on Chinese-manufactured components.
- FDA 510(k) timeline friction:Postpartum support belt manufacturers face 12-18 month clearance cycles for structural claims, delaying product launches and compressing effective patent windows.
- Substitute category expansion:General athletic compression wear with adjustable sizing is capturing price-sensitive demand for basic maternity support functions.
Strategic Opportunities
- Underpenetrated Indian maternity segment:BIS certification requirements have kept international brands at bay, creating first-mover advantage for compliant entrants in tier-2 cities.
- Subscription replenishment channels:Direct-to-consumer platforms for disposable nursing pads and breast milk storage bags are capturing recurring revenue pools absent from traditional retail.
- Wearable-lactation convergence:Integration of flow-sensing technology into smart bras is opening premium price tiers for data-driven breastfeeding compliance tools.
Industry Challenges
- Specialized pattern-making talent scarcity:Maternity garment engineering requires anthropometric expertise in gestational biomechanics that conventional fashion technical programs do not produce.
- Multi-jurisdiction certification burden:Simultaneous FDA, EU MDR, and BIS compliance creates documentation complexity that delays unified product launches across target markets.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternity Products Market Trends and Innovations
Material science advances and regulatory digitization are converging to reshape how maternity products are validated, distributed, and consumed across gestational and postpartum phases.
Adaptive compression textiles with embedded shape-memory polymers are fragmenting traditional sizing architectures. These materials adjust tension profiles across trimester progression, reducing SKU complexity for manufacturers. Direct-to-consumer maternity brands are adopting these textiles fastest, compressing the competitive relevance of conventional multi-size inventory models.
EU MDR's clinical evaluation requirements for therapeutic claims are restructuring postpartum device validation protocols. Manufacturers must now submit biocompatibility data and post-market surveillance plans before CE marking. Nursing accessory suppliers with existing ISO 13485 quality systems are absorbing compliance costs more efficiently than apparel-native competitors.
Hospital procurement departments are consolidating vendor lists for maternity discharge kits, favoring single-source suppliers of bundled garments, support belts, and lactation accessories. This concentration is displacing fragmented purchasing across departmental silos. The United States exhibits this pattern most acutely as health systems pursue standardized postpartum care pathways.
Maternity Products Market Segmentation
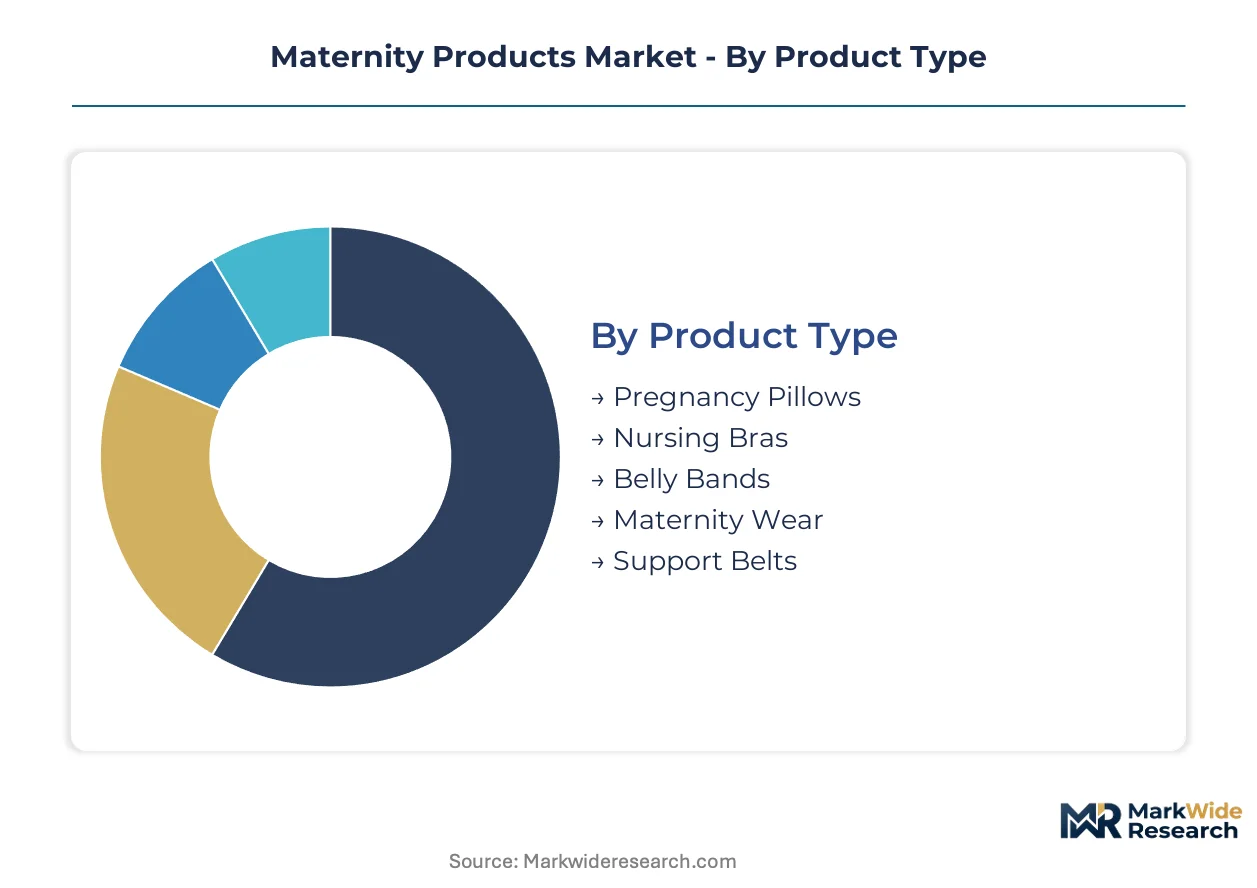
Maternity product segmentation reveals distinct demand profiles across gestational phases and purchasing contexts. Manufacturers align R&D pipelines and inventory models to these category boundaries, recognizing that prenatal comfort solutions and postnatal recovery devices require fundamentally different technical specifications and channel strategies.
Product Type:
Domestic consumption concentrates in pregnancy pillows and nursing bras across North American and European markets, while belly bands and support belts show stronger export orientation toward Asia-Pacific distribution networks. Manufacturing scale and regulatory certification requirements shape which segments travel across borders versus stay regional.
- Maternity Wear:Engineered garments incorporate adjustable side panels, stretch-woven fabrics, and ruching constructions that expand across trimester progression. United States department stores and direct-to-consumer platforms drive sustained replenishment cycles as fashion-conscious consumers refresh wardrobes quarterly. The segment absorbs the highest absolute marketing spend as brands compete on style differentiation.
- Nursing Bras:Wireless constructions with drop-cup mechanisms, moisture-wicking liners, and multiple hook-and-eye closures accommodate lactation-induced size fluctuations. Hospital discharge kit procurement in the United Kingdom and Germany creates institutional volume anchors alongside retail channels. FDA 510(k) pathways for therapeutic compression claims extend development timelines for structural variants.
- Pregnancy Pillows:C-shaped and U-shaped foam configurations with removable washable covers address sleep disruption during third-trimester physiological changes.
- Belly Bands:Elastic abdominal supports with silicone grip strips provide lower back relief and garment coverage during transitional sizing periods.
- Support Belts:Medical-grade pelvic stabilizers with adjustable tension straps reduce sacroiliac strain; EU MDR clinical evaluation requirements constrain therapeutic claim positioning.
Maternity wear commands the established base. The steepest expansion runs through nursing bras.
Application:
Cost tier stratification separates clinical-grade recovery devices from discretionary comfort accessories, with reimbursement eligibility determining price architecture and margin structure across application segments.
- Prenatal Care:Products address gestational musculoskeletal strain, sleep quality degradation, and circulatory compromise through ergonomic support geometries and graduated compression textiles. United States obstetric practice guidelines increasingly recommend standardized support belt protocols, expanding prescription-adjacent demand. Insurance reimbursement variability across state Medicaid programs creates patchy access patterns.
- Postnatal Care:Abdominal binders, perineal cold therapy systems, and pelvic floor rehabilitation devices target tissue recovery and organ repositioning during the six-week puerperium. French and German hospital systems bundle these into standardized discharge kits, concentrating volume with single-source suppliers. EU MDR biocompatibility testing elevates compliance costs for market entry.
- Breastfeeding Support:Nursing pads, nipple shields, and milk collection shells manage lactation logistics and tissue protection.
- Comfort Enhancement:Non-therapeutic pillows, loungewear, and relaxation accessories serve discretionary wellness positioning without clinical validation requirements.
- Mobility Assistance:Compression hosiery and balance-support footwear address edema and center-of-gravity shifts during late gestation.
Prenatal care anchors volume concentration. Postnatal care is climbing the fastest as health systems standardize recovery protocols.
End User:
Customer type fragmentation splits between self-directed consumer purchasing and institutional procurement, with channel strategy and pricing architecture diverging sharply across these boundaries.
- Expectant Mothers:First-trimester purchasers prioritize discretion and adaptability, seeking products that transition across gestational stages without replacement. Direct-to-consumer brands capture this cohort through subscription sizing programs and trimester-staged product curation. Social media peer recommendation drives discovery and trial conversion.
- New Mothers:Postpartum purchasers exhibit urgent need states around lactation establishment and physical recovery, compressing decision cycles and elevating price tolerance for clinically validated solutions. Hospital-based education programs and lactation consultant endorsements shape brand selection. Repeat purchase frequency concentrates in disposable nursing accessories.
- Healthcare Providers:Midwives, obstetricians, and physical therapists prescribe or recommend specific product specifications.
- Parenting Centers:Community-based education facilities distribute samples and provide fitting services for breastfeeding accessories.
Expectant mothers represent the largest addressable population. New mothers generate the highest revenue per user through accelerated purchase velocity.
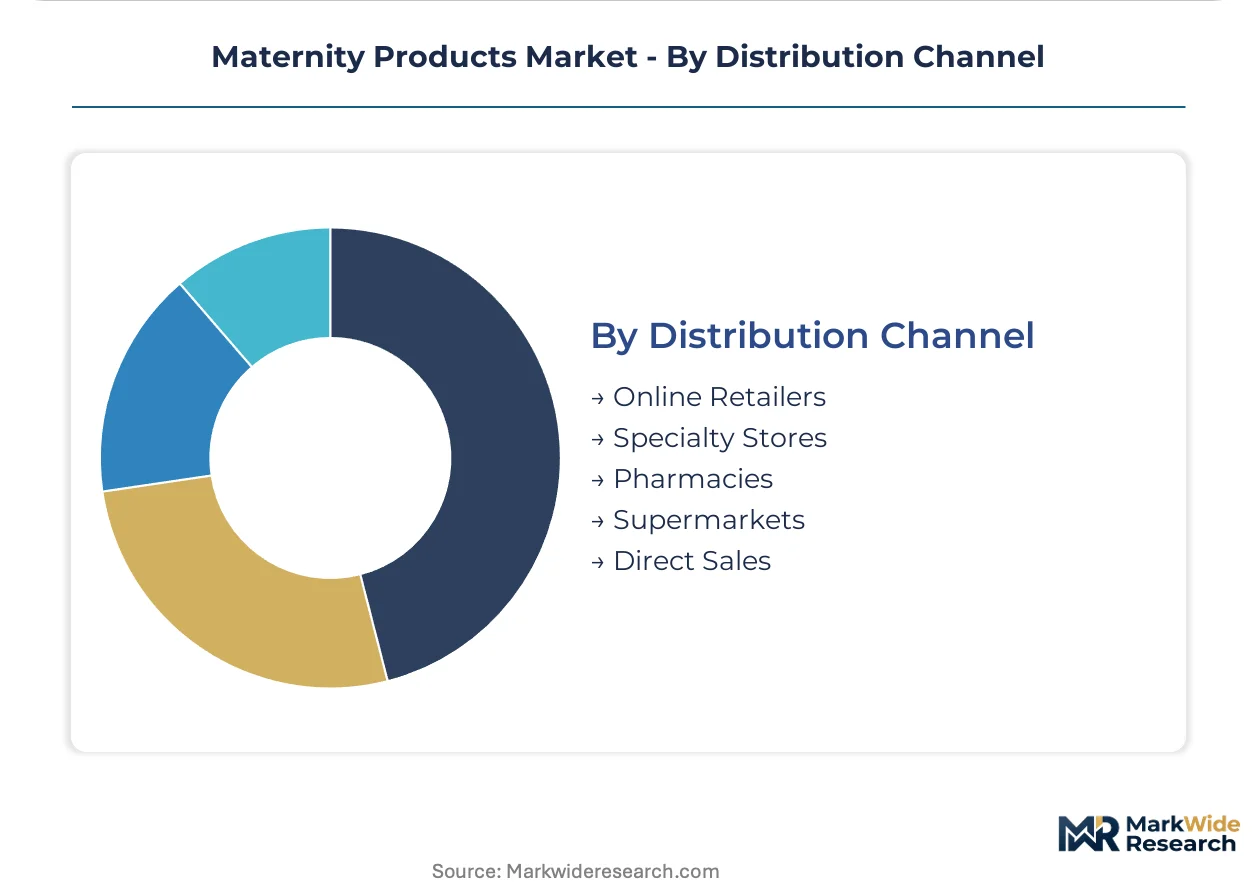
Distribution Channel:
Supply concentration in Chinese textile manufacturing clusters and North American fulfillment infrastructure shapes which channels can achieve competitive landed costs and delivery speed.
- Online Retailers:Platform-native brands and marketplace sellers leverage algorithmic discovery, review aggregation, and subscription replenishment to capture digitally native millennial parents. Amazon and specialized maternity platforms dominate United States volume, while Zalando and regional pure-plays lead European markets. Returns logistics complexity elevates operational costs for fit-dependent categories like nursing bras.
- Specialty Stores:Dedicated maternity retailers and baby boutiques provide fitting services, educational staff, and curated assortments that justify premium positioning. United Kingdom high street presence remains structurally important for occasion-wear segments requiring tactile evaluation. Rent and labor costs pressure unit economics relative to digital channels.
- Pharmacies:Boots, CVS, and Walgreens chains stock medical-grade support belts and compression garments alongside front-of-store nursing accessories.
- Supermarkets:Mass merchandisers capture price-sensitive demand for basic cotton underwear and disposable nursing pads.
- Direct Sales:Brand-owned websites and consultant networks bypass platform fees to preserve margin and capture first-party customer data.
Online retailers are gaining share fastest. Specialty stores retain structural importance for premium positioning and fit validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance requirements for postpartum support devices anchor the United States as the regulatory benchmark shaping product development timelines across developed markets. Digital-native millennial parents in this geography compress purchase cycles through direct-to-consumer channels. EU MDR biocompatibility testing elevates compliance costs for therapeutic claims in European markets.
United States
Premium maternity wear and postnatal recovery products command sustained consumer spending through hospital discharge kit procurement and insurance-adjacent reimbursement. FDA Class I and II device classifications for nursing accessories require 510(k) submissions for compression and structural claims. New York and Los Angeles metropolitan areas concentrate direct-to-consumer brand headquarters and influencer marketing infrastructure.
United Kingdom
Occasion-wear segments for professional settings drive demand through British design heritage positioning and high street retail presence. NHS procurement standardization for postpartum support belts creates volume concentration with certified suppliers. London anchors specialized maternity garment technical talent and pattern-making expertise.
Germany
Hospital discharge kit bundling concentrates volume with single-source suppliers of postnatal recovery devices and lactation accessories. EU MDR clinical evaluation requirements and post-market surveillance obligations constrain therapeutic claim positioning. Bavaria and Baden-Württemberg host medical textile manufacturing clusters serving adjacent orthopedic and maternity segments.
China
Medical-grade elastic fiber production concentrates in Guangdong province, exposing brands to input volatility and tariff exposure on manufactured components. GB standards and NMPA oversight fragment compliance requirements for multi-country distribution. Yangtze River Delta manufacturing clusters supply global brands with textile components and finished garments.
India
BIS certification requirements have kept international brands at bay, creating first-mover advantage for compliant entrants in tier-2 cities. Central government maternal health programs expand addressable demand through subsidized postnatal care access. Maharashtra and Gujarat textile manufacturing hubs develop domestic maternity garment production capacity.
Maternity Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the maternity products landscape. Premium positioning through design heritage and specialized technical expertise occupies distinct competitive territory from scale-driven manufacturing and mass-market distribution. The market structure fragments across direct-to-consumer specialists, multi-brand retailers with maternity lines, and dedicated maternity pure-plays. Strategic moves concentrate on channel control through owned e-commerce platforms and subscription replenishment models, alongside portfolio diversification into adjacent postpartum recovery segments.
Within the design-heritage archetype, Seraphine occupies a position exemplifying occasion-wear specialization for professional settings. Among scale-driven retailers, Gap and H&M represent mass-market manufacturing leverage across global supplier networks. At the direct-to-consumer specialist tier, Kindred Bravely anchors community-driven sizing innovation and channel control. These three companies collectively illustrate the competitive segmentation between premium positioning, manufacturing scale, and digital-native customer acquisition.
| Leading Market Players |
|---|
| H&M |
| ASOS |
| Gap |
| Seraphine |
| Motherhood Maternity |
| Isabella Oliver |
| A Pea in the Pod |
| PinkBlush |
| Kindred Bravely |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for medical-grade elastic fibers concentrate purchasing power among Guangdong-based suppliers, compressing margin buffers for brands dependent on Chinese-manufactured components while elevating pricing leverage for vertically integrated incumbents with captive textile operations.
Pricing Analysis
United States retail pricing for FDA-cleared support belts runs 40-60% above comparable uncertified variants in European pharmacies, reflecting reimbursement-adjacent positioning and 510(k) compliance cost recovery. Three-tier pricing structure across premium, standard, and economy levels segments on certification grade and channel control, with direct-to-consumer specialists capturing margin premiums through subscription bundling. Pricing pressure stems from athletic compression wear substitutes eroding basic support belt demand. Price-sensitive mass-market buyers in supermarket channels contrast with premium-tolerant new mothers seeking lactation consultant-endorsed nursing accessories.
Supply Chain Analysis
Strait of Malacca transit exposure for Indonesian rubber and Vietnamese textile shipments concentrates logistics risk for European and North American brands sourcing from Asia-Pacific manufacturing clusters. Production gravity centers on China, India, and Bangladesh for finished garments, with Germany and the United States hosting specialized medical textile finishing. Raw material dependencies span medical-grade elastane, organic cotton, and shape-memory polymers. Single-source vulnerability in Guangdong elastic fiber production elevates tariff exposure. Distribution runs through direct-to-consumer platforms, hospital procurement departments, and pharmacy chains with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR digitization of clinical evaluation workflows is compressing certification timelines for adaptive compression textiles, creating first-mover advantage for brands with pre-submitted biocompatibility dossiers.
For Market Incumbents: Consolidate pattern-making talent pools through acquisition of specialized maternity garment technical studios in London and New York, defending against direct-to-consumer entrants with superior anthropometric databases. Deepen backward integration into medical-grade elastic fiber production to offset Guangdong supply concentration. Prioritize ISO 13485 certification investment for nursing accessory lines to accelerate EU MDR pathway execution. For New Entrants and Emerging Players: Differentiate on telehealth-integrated smart lactation accessories, targeting the wearable-lactation convergence white space with flow-sensing bra technology. Penetrate tier-2 Indian cities through BIS certification compliance, exploiting first-mover advantage before international brands establish distribution. Deploy hospital discharge kit bundling as primary go-to-market angle, securing volume anchors with health system procurement consolidation. For Investors and Strategic Acquirers: Carve-out targets emerge from multi-brand retailers with underoptimized maternity lines, where design heritage assets sit stranded without dedicated e-commerce infrastructure. Long-term viability hinges on subscription replenishment revenue retention and regulatory certification moats. Monitor FDA 510(k) submission velocity for smart nursing accessories as inflection indicator for telehealth integration adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Biocompatibility testing capabilities unlock pharmacy shelf-space advantages in German and French markets. |
| Direct-to-Consumer Platform Launch | Subscription replenishment for disposable nursing pads captures recurring revenue absent from traditional retail. |
| Adaptive Compression Textile R&D | Shape-memory polymers reduce SKU complexity while expanding addressable demand across trimester progression. |
| Hospital System Partnership | Discharge kit bundling concentrates volume with single-source suppliers as US health systems standardize postpartum pathways. |
| Telehealth Integration Development | Smart bra lactation metrics feed maternal health dashboards, opening premium pricing tiers for data-driven compliance tools. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) submissions, EU MDR clinical evaluation reports, and hospital procurement databases. Interviews with maternity brand product development executives, lactation consultants, hospital GPO contracts managers, and specialized garment pattern-makers informed demand-side validation. Secondary sources include customs trade records for textile component flows, SEC filings for publicly traded parent companies, and Nielsen retail audit data for channel share estimation. Bottom-up SKU-level demand modeling triangulates against top-down macroeconomic elasticity assumptions.
Segmentation dimensions modeled span product type, application phase, end-user archetype, and distribution channel across the analysis window. CAGRs derive from regression-adjusted historical trajectory projection incorporating regulatory timeline friction and telehealth adoption curves. Industry-specific forecast inputs include EU MDR implementation pace for therapeutic device reclassification and millennial digital-native purchasing behavior shifts toward subscription replenishment.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance timeline norms or accelerated EU MDR digitization would require recalibration. Forecasts reflect documented assumptions around raw material cost stability and hospital procurement consolidation velocity. Practitioners should keep alternative scenarios live as tariff exposure on Chinese-manufactured components and substitute category expansion from athletic compression wear evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.