
 Slurry Seal Pavers Market | 2026-2036
Slurry Seal Pavers Market Size, Share, and Industry Trends Forecast 2026-2036
Slurry Seal Pavers Market Analytics
Aftermarket parts and field service revenue is rewriting profitability expectations for slurry seal paver OEMs. XCMG leverages its integrated manufacturing scale to control component costs across the full machine envelope. Bergkamp Inc. specializes in continuous paver designs that reduce material waste during variable-width applications. FAYAT Group anchors its position through a dense dealer network covering European and North American municipal procurement channels.
Slurry seal pavers are self-propelled or towed machines that apply a thin mixture of emulsified asphalt, fine aggregate, mineral filler, and water to existing pavement surfaces at depths typically ranging from three to ten millimeters, creating a wearing course that seals minor cracks and restores surface friction. The equipment employs either auger or paddle mixing systems to maintain material homogeneity before distribution through squeegee boxes or drag spreaders. Polymer-modified systems command premium positioning due to superior binder elasticity and faster traffic return times, while conventional formulations retain volume leadership in budget-constrained municipal programs. Mechanical installation dominates contractor fleets for speed and repeatability, though laser-guided systems gain traction in airport runway applications where grade tolerances tighten.
The Federal Highway Administration's pavement preservation guidelines and individual state DOT material specifications shape product qualification requirements across the United States, while the European Committee for Standardization's EN 12274 framework governs slurry surfacing performance classes in EU member states. China's Ministry of Transport issues GB/T standards for micro-surfacing and slurry seal that constrain import eligibility for non-domestic equipment. Stakeholders must monitor how municipal budget cycles and federal infrastructure funding allocations reshape replacement timing for aging paver fleets.
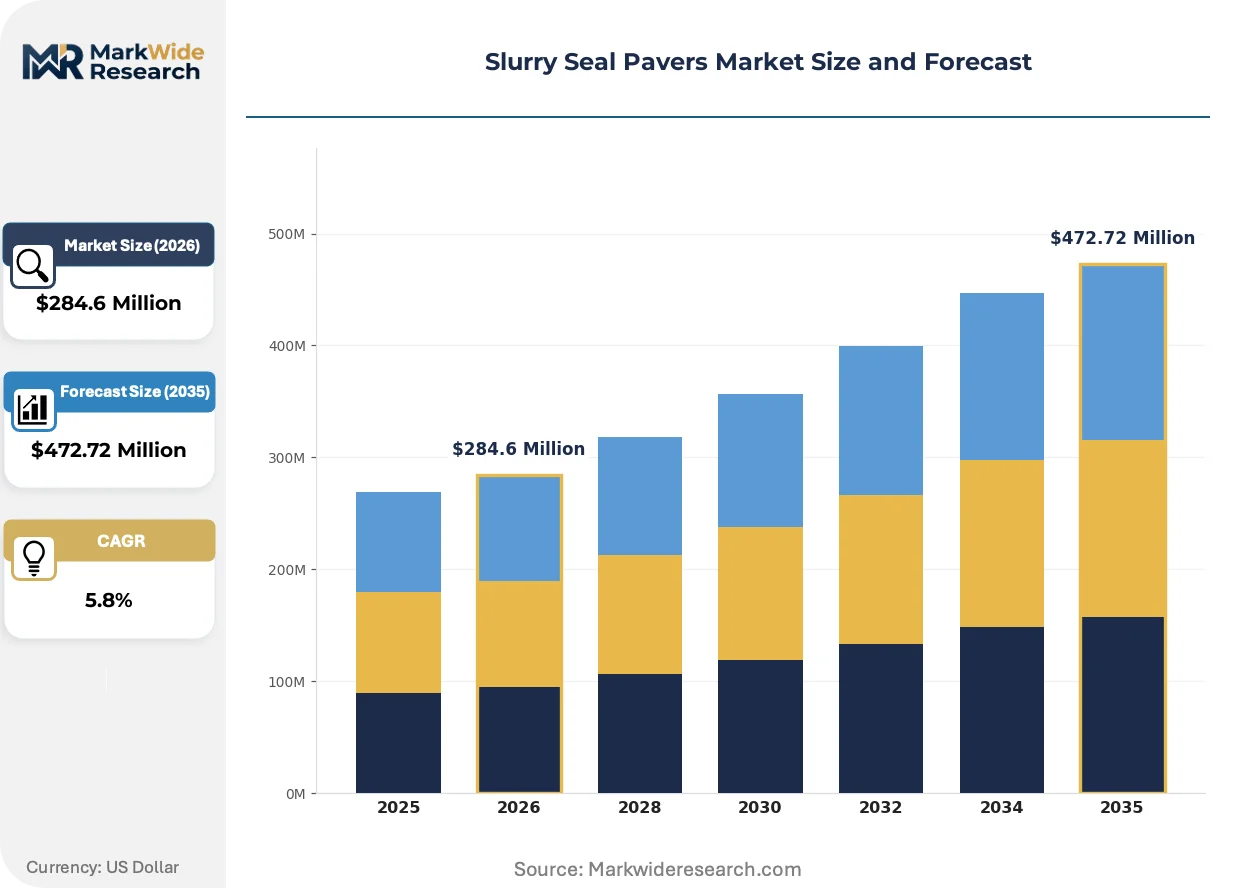
Market Dynamics
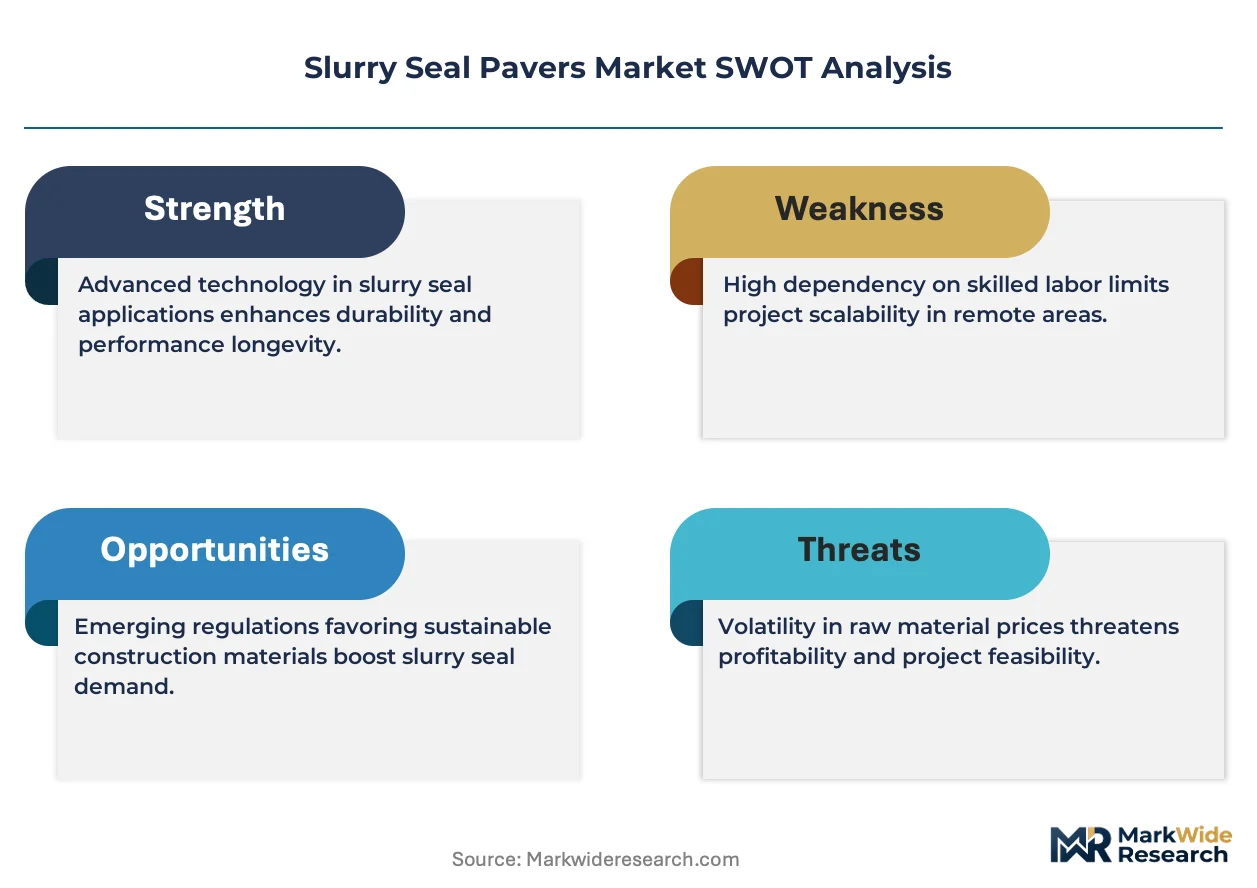
Municipal pavement preservation budgets are tightening procurement criteria around polymer-modified emulsion compatibility, forcing OEMs to redesign mixing systems for higher-viscosity binders without sacrificing material throughput.
Growth Catalysts
- FHWA Pavement Preservation Guidelines:Federal specifications now mandate slurry seal as a preventive maintenance tier, directing state DOT capital toward qualified equipment purchases.
- Sun Belt thermal degradation:Arizona, Texas, and Florida municipalities face accelerated oxidation cracking, expanding annual slurry seal cycle frequency on arterial roads.
- Polymer-modified emulsions:SBR and SBS binder additives reduce traffic return times from 4 hours to 90 minutes, justifying premium equipment pricing for high-volume contractors.
Market Restraints
- Bitumen price volatility:Asphalt cement costs fluctuate with crude oil indices, compressing contractor margins and delaying fleet replacement cycles.
- Emulsion supply concentration:Regional blending plant capacity limits constrain slurry seal program scaling in mountain west and northern plain states.
- EN 12274 performance class fragmentation:European type-testing requirements for micro-surfacing versus slurry seal create SKU complexity for manufacturers serving cross-border municipal tenders.
Strategic Opportunities
- Airport runway specifications:FAA-grade tolerance requirements for surface regularity open premium positioning for laser-guided screed systems on airfield contracts.
- Continuous paver designs:Bergkamp-style variable-width box technology reduces material waste 15-20% on irregular urban street geometries.
- US IIJA infrastructure allocations:Federal highway formula funding increases state pavement preservation program envelopes through 2026.
Industry Challenges
- Emulsion-blender operator certification:ASTM D3910 testing protocols require specialized training that contractor labor pools lack.
- Legacy fleet integration:Mechanical squeegee boxes on 10-15 year old pavers cannot achieve polymer-modified material distribution uniformity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slurry Seal Pavers Market |
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $472.72 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-modified, Rubberized, Conventional, Specialty Installation Method: Mechanical, Manual, Laser-guided, Automated End User: Municipalities, Contractors, Property Management, Industrial Facilities Application: Road Maintenance, Airport Runways, Parking Lots, Driveways |
| Companies Covered | XCMG, FAYAT Group, Etnyre International, Schaefer-Technic, Gaoyuan Shenggong, VSS Macropaver, Bergkamp Inc., Xi’an Dagang Road Machinery, IKOM Construction Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slurry Seal Pavers Market Evolving Landscape
Telematics-enabled predictive maintenance and real-time material quality monitoring are compressing equipment downtime and reducing out-of-specification application callbacks for municipal fleets.
Telematics hardware retrofitted to slurry seal pavers transmits engine diagnostics, emulsion temperature, and aggregate moisture data to contractor dispatch centers. Large municipal fleets in California and Texas are mandating OEM-provided connectivity modules on new procurements. This data stream is virtualizing traditional scheduled maintenance intervals into condition-based interventions, cutting unplanned downtime 30-40%.
REACH restrictions on polycyclic aromatic hydrocarbons in bitumen emulsions are accelerating bio-based binder formulation R&D across European equipment trials. French and German municipal specifiers now require PAH-content declarations on emulsion certificates. Paver OEMs serving EU markets are redesigning tank heating systems for lower-temperature bio-binder storage.
Performance-based contracting is displacing unit-price bidding for pavement preservation in several US state DOT programs. Contractors assume material-performance risk for 3-5 year service life guarantees. Texas and Colorado pilot programs show this model concentrates slurry seal demand among equipment-heavy regional contractors with in-house quality control laboratories.
Slurry Seal Pavers Market Segmentation
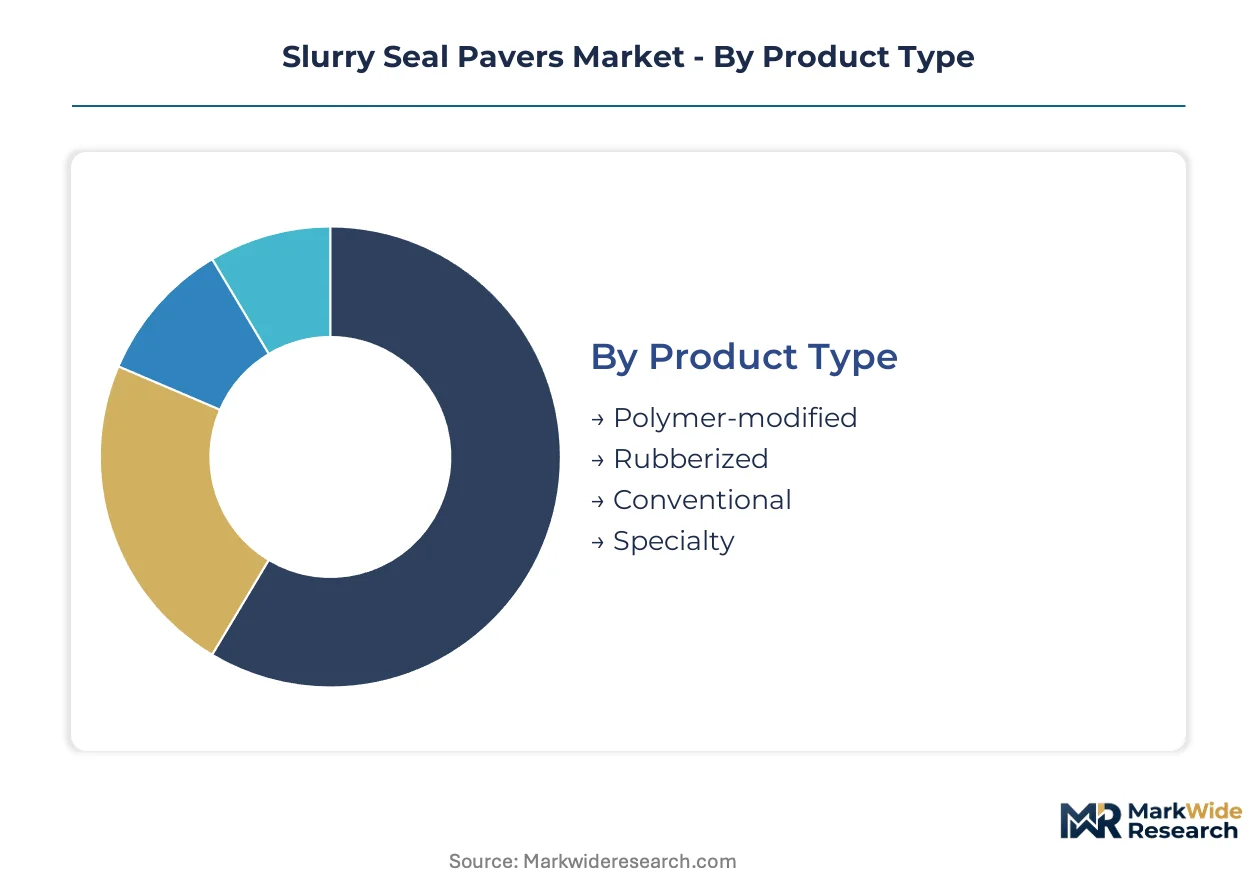
Slurry seal paver procurement patterns diverge sharply across customer archetypes, with aftermarket service contracts and parts availability driving vendor selection more than upfront equipment cost. Municipal fleet managers prioritize standardized maintenance protocols, while high-volume contractors optimize for material throughput and traffic return speed.
Product Type:
Aftermarket service intensity peaks with polymer-modified systems due to specialized pump seals, heated tank components, and emulsion compatibility testing requirements that extend the OEM revenue stream well beyond initial sale.
- Polymer-modified:SBR and SBS binder additives deliver superior elasticity and 90-minute traffic return windows. Arizona DOT specifications now mandate this grade for arterial roads above 10,000 AADT, concentrating demand among Sun Belt municipalities facing thermal oxidation cycles.
- Conventional:Unmodified asphalt emulsion formulations dominate budget-constrained municipal programs where 4-hour cure times remain acceptable. Volume leadership persists in rural counties and secondary road networks across the US Great Plains and Midwest.
- Rubberized:Crumb rubber additives from recycled tires enhance crack resistance for freeze-thaw climates.
- Specialty:Custom binder blends serve airport runway friction restoration and high-carbonate aggregate compatibility.
Conventional formulations hold the largest share; momentum sits with polymer-modified grades as state DOT specifications tighten.
Installation Method:
Cost tier stratification separates premium positioning from fleet-standard equipment, with laser-guided and automated systems commanding 40-60% price premiums over mechanical alternatives.
- Mechanical:Auger and paddle mixing systems with squeegee box distribution dominate contractor fleets for speed and repeatability on standardized urban street widths. Texas and California municipal procurement contracts specify mechanical installation for 80% of slurry seal lane-miles.
- Laser-guided:Real-time grade control achieves FAA surface regularity tolerances for airfield applications. Denver International Airport and Dallas-Fort Worth International specifications now require laser-guided screeds for runway friction restoration contracts.
- Manual:Hand-controlled spreader boxes persist in driveway and small parking lot applications.
- Automated:GPS-integrated paver controls enable single-operator deployment on variable-width rural roads.
Mechanical installation retains volume leadership; laser-guided systems climb the fastest as airport infrastructure spending accelerates.
End User:
Customer type determines specification authority and replacement cycle timing, with municipalities running 7-10 year fleet rotations versus 4-6 year cycles for high-utilization contractors.
- Municipalities:City and county road departments specify equipment through formal RFP processes tied to federal highway formula funding allocations. California and Texas municipal fleets represent the largest installed base in North America.
- Contractors:Regional pavement preservation specialists operating performance-based contracts require maximum daily production rates. Colorado and Texas pilot programs show equipment-heavy contractors capturing 60%+ of 3-5 year warranty work.
- Property Management:Commercial real estate and HOA maintenance programs favor smaller towed units.
- Industrial Facilities:Mining and logistics yards specify heavy-duty frames for high-aggregate-load applications.
Municipalities hold the largest share; momentum sits with contractors as performance-based contracting displaces unit-price bidding.
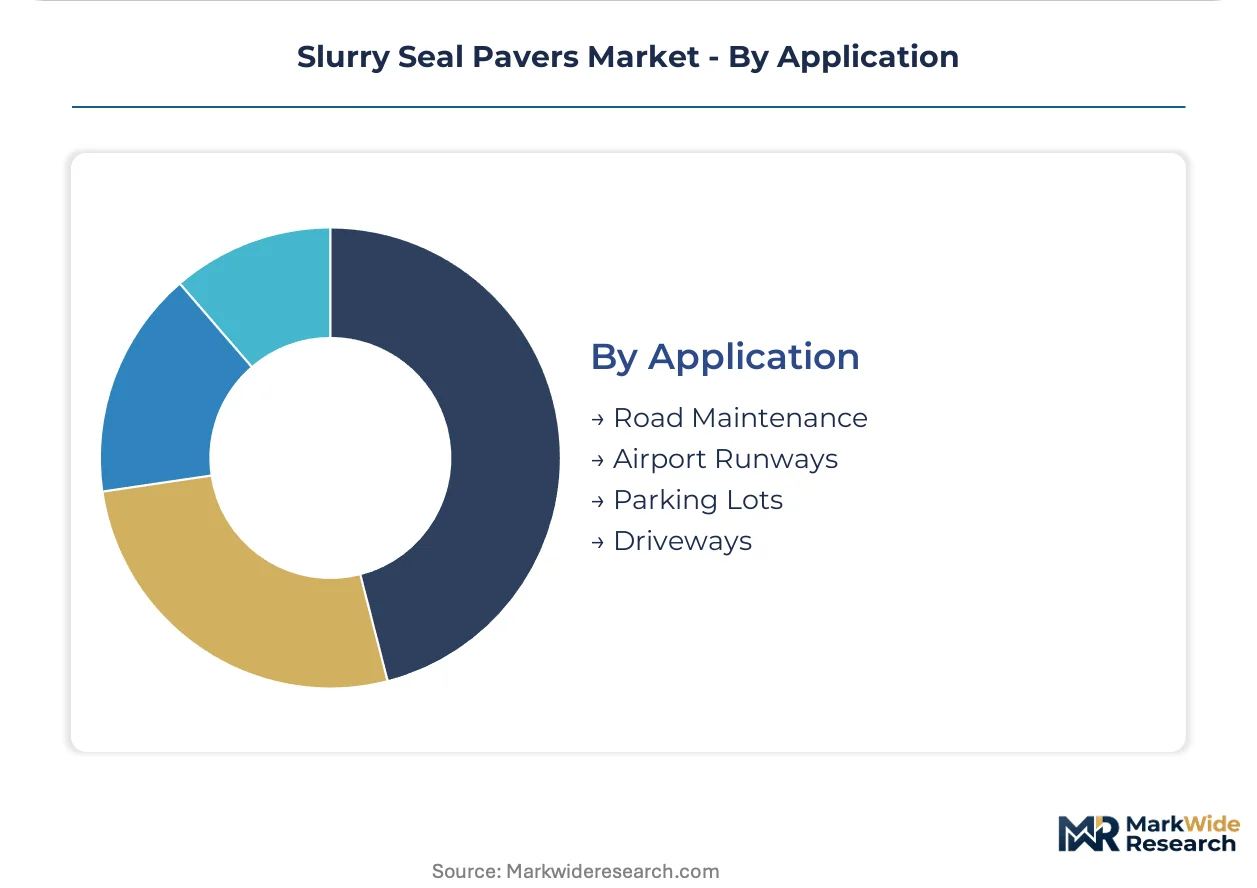
Application:
Application context dictates material specification, equipment sizing, and traffic management requirements, with airport and industrial segments demanding precision unavailable in standard road maintenance configurations.
- Road Maintenance:Arterial and collector street preservation consumes 70%+ of North American slurry seal volume. Florida DOT specifications require annual treatment cycles on state roads in high-UV exposure zones.
- Airport Runways:FAA-grade surface regularity and friction coefficient restoration command premium equipment pricing. Denver and Dallas-Fort Worth specifications drive laser-guided paver adoption for airfield contracts.
- Parking Lots:Commercial retail and distribution center maintenance favors rapid-cure polymer systems for minimal business disruption.
- Driveways:Residential applications concentrate in towed equipment and manual installation segments.
Road maintenance holds the largest share; airport runways gain share fastest as FAA infrastructure aging accelerates precision equipment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sun Belt municipalities in the United States treat arterial roads annually against thermal oxidation, while European operators confront REACH-mandated binder reformulation. Chinese provincial transport bureaus enforce GB/T standards that favor domestic equipment procurement.
United States
Arizona DOT mandates polymer-modified slurry seal for roads exceeding 10,000 AADT, concentrating equipment demand in Phoenix and Tucson metropolitan corridors. The Federal Highway Administration's pavement preservation guidelines direct IIJA infrastructure funding toward qualified paver purchases. Texas municipal fleets in Dallas-Fort Worth and Houston represent the largest installed base of continuous paver designs.
Germany
French and German municipal specifiers now require PAH-content declarations on emulsion certificates under REACH restrictions. The KBA's influence on road construction equipment standards shapes cross-border tender requirements. Equipment manufacturers in Bavaria and North Rhine-Westphalia redesign tank heating systems for lower-temperature bio-binder storage.
China
Ministry of Transport GB/T standards for micro-surfacing constrain import eligibility for non-domestic slurry seal pavers. Provincial transport bureaus in Jiangsu and Shandong prioritize domestic equipment procurement in infrastructure tenders. XCMG leverages integrated manufacturing scale from its Xuzhou headquarters to control component costs.
Canada
Health Canada's environmental assessment protocols for bitumen emulsions influence municipal procurement specifications in Ontario and Quebec. Provincial transportation ministries in British Columbia pilot performance-based contracting models for pavement preservation. Alberta's oil sands region generates specialized demand for heavy-duty paver frames in industrial facility applications.
Australia
State road agencies in New South Wales and Victoria specify slurry seal for preventive maintenance on high-UV exposure zones. The TGA's absence from road construction regulation leaves standards development to Austroads and state-level authorities. Brisbane and Sydney municipal fleets concentrate demand for telematics-enabled equipment monitoring systems.
Slurry Seal Pavers Market Competitive Landscape
Capability concentration sits with specialized manufacturers of continuous paver designs; scale advantage sits with integrated construction equipment conglomerates. The market structures around three tiers: polymer-modified system specialists, municipal fleet standard-setters, and emerging regional fabricators. Dominant competitive moves include backward integration into emulsion-compatible component manufacturing and dense dealer network expansion across federal highway funding jurisdictions.
Within the specialized tier, Bergkamp Inc. and VSS Macropaver occupy positions defined by variable-width box technology for irregular urban geometries. Among integrated equipment conglomerates, XCMG and FAYAT Group exemplify scale-driven cost control across the full machine envelope. Etnyre International, Gaoyuan Shenggong, and Xi'an Dagang Road Machinery represent mid-tier regional specialists serving state-level procurement channels.
| Leading Market Players |
|---|
| XCMG |
| FAYAT Group |
| Etnyre International |
| Schaefer-Technic |
| Gaoyuan Shenggong |
| VSS Macropaver |
| Bergkamp Inc. |
| Xi'an Dagang Road Machinery |
| IKOM Construction Machinery |
| Others |
Value Network & Pricing Analysis
Bitumen price volatility tied to crude oil indices compresses contractor margins and forces simultaneous recalibration of equipment pricing tiers and supply chain sourcing strategies across the slurry seal paver value chain. This commodity exposure widens spreads between polymer-modified premium systems and conventional economy-grade equipment while pushing OEMs toward backward integration into component manufacturing.
Pricing Analysis
Project-based municipal procurement contracts dominate slurry seal paver transactions, with multi-year fleet replacement schedules and performance-based warranty terms replacing spot-market purchases. Price differentiation rests on emulsion compatibility certification levels and after-sales service bundling rather than base equipment cost. Cost compression in conventional-grade segments is intensifying because rural counties face budget constraints, while polymer-modified systems command resilience against price pressure due to Arizona DOT and Texas DOT specification mandates. Municipal fleet managers exhibit highest price sensitivity, prioritizing standardized maintenance protocols over throughput optimization.
Supply Chain Analysis
Export-control restrictions on precision guidance technology limit laser-guided screed component flows from German and Japanese suppliers to non-allied manufacturing jurisdictions. Component manufacturing concentrates in China, Germany, and the United States, with heated tank assemblies and polymer-compatible pump seals drawing from specialized foundries in Bavaria and Jiangsu. Single-source vulnerability around emulsion-blender control systems creates procurement risk for contractors scaling polymer-modified programs. Distribution runs through dense dealer networks anchored by FAYAT Group and XCMG across federal highway funding jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The slurry seal pavers market sits in an early-cycle expansion phase as Federal Highway Administration pavement preservation guidelines and IIJA infrastructure allocations accelerate municipal fleet replacement timing across Sun Belt states.
For Market Incumbents: Harden polymer-modified system capabilities through captive manufacturing of heated tank components and emulsion-compatible pump seals to defend against emerging Chinese equipment entrants. Deepen dealer network density across Texas and California municipal procurement channels where specification authority concentrates. For New Entrants and Emerging Players: Establish a beachhead in rubberized slurry seal equipment for freeze-thaw climate applications where incumbent coverage remains thin. Target Colorado and Pacific Northwest municipal markets through telematics-enabled predictive maintenance bundles that differentiate against legacy mechanical fleets. For Investors and Strategic Acquirers: The market sits at a specification-tightening phase that favors equipment-heavy regional contractors with in-house quality control laboratories. Long-term viability hinges on performance-based contracting penetration displacing unit-price bidding. The signal to watch is FAA runway specification adoption rates for laser-guided screed systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emulsion-Compatible Components | XCMG and Bergkamp-style specialists capture margin from pump seal and heated tank manufacturing. |
| Telematics-Enabled Predictive Maintenance Launch | California and Texas municipal fleets mandate OEM-provided connectivity modules on new procurements. |
| Performance-Based Contracting Capability Buildout | Equipment-heavy contractors with in-house QC labs capture 60% of 3-5 year warranty pavement preservation work. |
| Laser-Guided Screed Certification Investment | Denver International and Dallas-Fort Worth specifications now require FAA-grade surface regularity for runway contracts. |
| Dense Dealer Network Expansion | FAYAT Group anchors municipal procurement channel control across European and North American federal funding jurisdictions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal fleet managers, regional pavement preservation contractors, state DOT specification engineers, OEM aftermarket service directors, and emulsion blending plant operators. Secondary validation drew from FHWA pavement preservation guidelines, state DOT material specifications, ASTM D3910 testing protocols, EN 12274 performance class documentation, and customs trade data on bitumen emulsion imports. Bottom-up equipment shipment tallies triangulated against top-down municipal budget allocation analysis.
Calibration against historical replacement cycles and specification adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, installation method, end user archetype, and application context alongside regional regulatory cluster differentiation. CAGRs were derived from slope analysis of equipment procurement patterns correlated with federal highway formula funding trajectories. Key forecast inputs encompassed polymer-modified emulsion specification mandates and telematics adoption curves in municipal fleet procurement.
Macroeconomic conditions sit as an overlay; deviation in crude oil price indices and federal infrastructure funding allocations would shift the trajectory. Forecasts reflect underlying assumptions about specification tightening continuity and emulsion supply chain stability. Material shifts in REACH bio-binder mandates or IIJA funding reauthorization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Malaysia Building Thermal Insulation Material Market
Construction and Engineering
Mining Machinery Market
Construction and Engineering
Wood Panel Market
Construction and Engineering
Global Snow Making System Market
Construction and Engineering
GCC Concrete Blocks Market
Construction and Engineering
Global Submerged Coil Heat Exchanger Market
Construction and Engineering
Latex Caulk Market
Construction and Engineering
Paint Spray Guns Market
Construction and Engineering
Garage Equipment Market
Construction and Engineering
Norway Transportation Infrastructure Construction Market
Construction and Engineering
Condenser Cleaners Market
Construction and Engineering
Industrial Air Heaters Market
Construction and Engineering
Heavy Duty Heat Pump Market
Construction and Engineering
Metal Structural Insulation Panels Market
Construction and Engineering
Crane Barge Market
Construction and Engineering
Pressure Pumping Services Market