
 Sleepwear Market | 2026-2036
Sleepwear Market Size, Share, and Industry Trends Forecast 2026-2036
Sleepwear Market Intelligence
The EU Green Deal is restructuring procurement priorities across European retail chains, forcing suppliers to certify recycled content and reduce chemical inputs. Hanesbrands Inc. leverages its vertically integrated manufacturing network to control fiber sourcing costs across multiple continents. MAS Holdings Limited anchors production capacity in South Asia while meeting stringent EU buyer compliance protocols. PVH Corporation competes through brand portfolio breadth spanning mass-market and premium sleepwear tiers.
Sleepwear encompasses garments designed specifically for rest periods, typically constructed from breathable, low-friction fabrics with moisture-wicking properties and relaxed silhouettes that accommodate temperature regulation during sleep cycles. Cotton and bamboo materials command expanding shelf space as consumers prioritize natural fiber breathability and antimicrobial performance against synthetic alternatives. The women's segment dominates absolute volume, while children's sleepwear generates disproportionate margin returns due to higher replacement frequency and safety-standard premiums. Online retail channels are capturing the fastest growth trajectory, though brick-and-mortar locations sustain impulse purchase volumes and gift-oriented transactions.
REACH and the EU Green Deal shape chemical compliance and circularity mandates for European market access, while the US Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1615 and 1616 for children's sleepwear. China's GB standards and the EU AI Act's emerging supply-chain disclosure rules will tighten traceability requirements for multinational brands. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmented compliance investments that erode cross-border economies of scale.
Market Dynamics
The EU Green Deal's textile sustainability mandates are forcing manufacturers to reconfigure fiber sourcing and certification protocols, while direct-to-consumer channels capture Millennial and Gen Z purchasing volume away from traditional wholesale relationships.
Growth Catalysts
- EU Green Deal circularity requirements:European retail chains now mandate recycled content verification and chemical input reduction, pulling suppliers toward organic cotton and closed-loop recycling systems to retain market access.
- Direct-to-online channel expansion:Millennial and Gen Z consumers are consolidating purchases through brand-owned digital storefronts, compressing wholesale intermediaries and expanding margin capture for vertically integrated producers.
- Natural fiber performance advantages:Cotton and bamboo materials deliver superior breathability and antimicrobial properties against synthetic alternatives, driving shelf space reallocation in premium and mass-market tiers alike.
Market Restraints
- Raw cotton price volatility:Climate-induced harvest variability and speculative commodity trading create margin compression for manufacturers lacking long-term fiber contracts or captive agricultural supply.
- South Asian production concentration:MAS Holdings and comparable suppliers anchor capacity in Sri Lanka and Bangladesh, exposing brands to geopolitical disruption, port congestion, and single-source dependency risks.
- Children's sleepwear flammability standards:The US Consumer Product Safety Commission enforces 16 CFR Part 1615 and 1616 testing requirements, adding compliance cost layers that disproportionately burden smaller market entrants.
Strategic Opportunities
- United States premium loungewear crossover:American consumers are merging sleepwear and daytime loungewear categories, creating white space for hybrid garment lines that command higher unit economics than traditional nightwear.
- EU AI Act supply-chain disclosure:Emerging traceability mandates will reward early adopters of blockchain-verified fiber provenance, differentiating compliant brands in European retail procurement decisions.
- Temperature-regulating fabric innovation:Phase-change materials and moisture-wicking bamboo blends are converging with smart textile R&D, enabling premium positioning in climate-adaptive sleepwear segments.
Industry Challenges
- REACH chemical compliance timelines:European Chemicals Agency substance restrictions require reformulation cycles that extend product development schedules and strain R&D resource allocation.
- GB standards alignment complexity:China's national standards diverge from EU and US testing protocols, forcing manufacturers to maintain parallel certification tracks that fragment quality assurance systems.
- Legacy ERP integration friction:Closed-loop recycling and fiber traceability systems demand data architecture upgrades that conflict with existing inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleepwear Market |
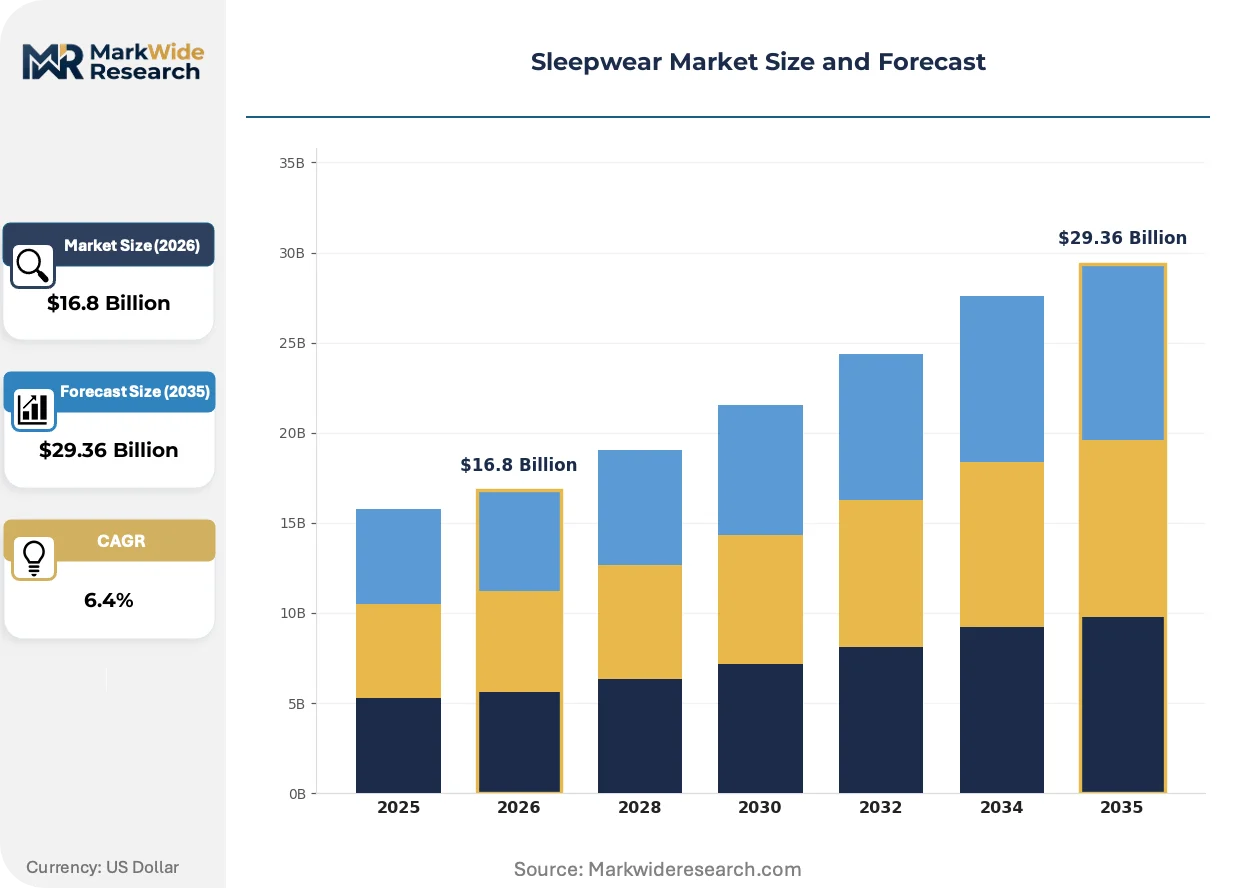
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pajamas, Nightgowns, Robes, Sleep Shirts Material: Cotton, Silk, Polyester, Bamboo Target Audience: Men, Women, Children, Infants Distribution Channel: Online Retail, Brick-and-Mortar, Department Stores, Specialty Shops |
| Companies Covered | Jockey International Inc., American Eagle Outfitters Inc., Hanesbrands Inc., MAS Holdings Limited, Marks and Spencer Group plc, PVH Corporation, Hanky Panky Ltd., Triumph International Holdings GmbH, L Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleepwear Market Strategic Shifts & Innovations
Bamboo-derived viscose and lyocell production methods are displacing conventional rayon manufacturing, while regulatory disclosure mandates and channel fragmentation reshape competitive positioning across premium and mass-market tiers.
Closed-loop lyocell manufacturing is expanding into mainstream sleepwear supply chains as solvent recovery rates exceed 99 percent and fiber tensile strength matches conventional cotton. Premium European and North American brands are adopting Tencel-branded lyocell at accelerated procurement schedules. This technology is expanding into mid-market private-label programs previously locked into petrochemical-based fabrics.
REACH substance restriction amendments are tightening permissible chemical inputs in textile finishing processes, forcing dyestuff and softener reformulation across EU-facing production lines. Manufacturers serving H&M, Zara, and comparable retail chains must recertify supplier portfolios or risk delisting. Children's sleepwear categories face the steepest compliance cost escalation due to skin-contact proximity and flammability additive restrictions.
Millennial buyers are consolidating sleepwear purchases around certified organic and OEKO-TEX Standard 100-labeled products, compressing tolerance for uncertified synthetic alternatives regardless of price positioning. Direct-to-consumer brands are capturing this preference shift through subscription replenishment models that bypass traditional seasonal wholesale cycles. This behavioral pivot is most visible in United States coastal metropolitan markets and comparable affluent European urban corridors.
Sleepwear Market Segmentation
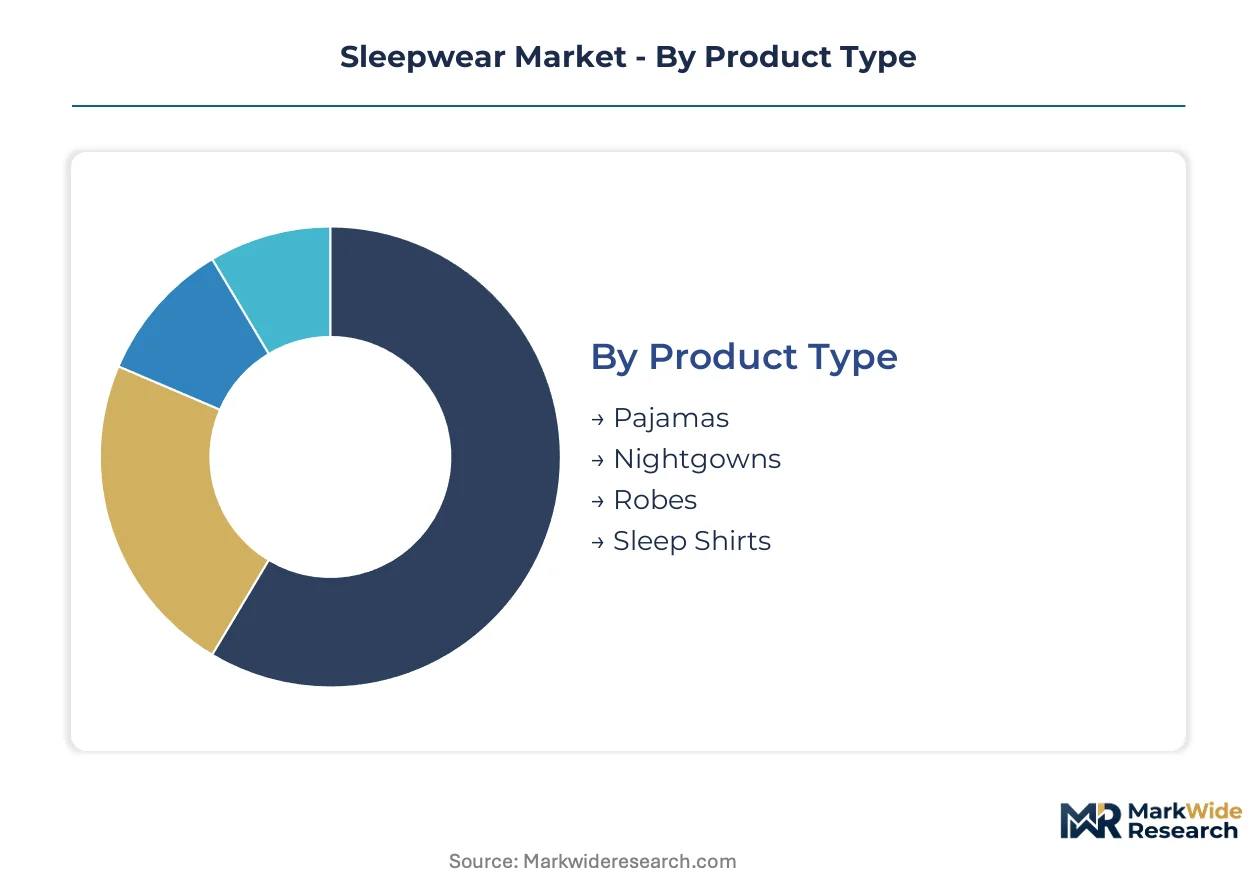
Sleepwear manufacturers calibrate product portfolios around distinct replacement rhythms and seasonal refresh cycles. Material durability, demographic sizing turnover, and channel-specific inventory velocity each dictate divergent production planning and margin structures across segment boundaries.
Product Type:
Pajamas and nightgowns dominate replacement-frequency economics, with average garment lifespans spanning 18-24 months under normal wash-wear cycles.
- Pajamas:Two-piece and one-piece constructions in woven cotton or knit jersey fabrics accommodate the broadest sizing range. United States mass-market retailers rotate inventory quarterly to match back-to-school and holiday gift demand surges.
- Nightgowns:Sleeveless through long-sleeved silhouettes in modal or cotton blends serve maternity and post-surgical recovery niches alongside standard sleep use. European pharmacy chains stock medical-grade nightgowns with front-closure designs for post-operative patients.
- Robes:Kimono and shawl-collar wraps in terry cloth or satin function as crossover loungewear with higher unit economics than core sleep garments. Hotel amenity programs and bridal registry channels sustain above-average margin capture.
- Sleep Shirts:Oversized tunic constructions in breathable cotton or linen blends attract male purchasers seeking simplified wardrobe decisions. Direct-to-consumer subscription services target this segment for automated replenishment.
Volume placements concentrate in Pajamas; the faster expansion belongs to Robes.
Material:
Fiber selection determines certification burden, temperature-regulation performance, and end-of-life disposal pathways for circularity compliance.
- Cotton:GOTS-certified organic grades command shelf-space premiums in EU retail chains facing Green Deal sourcing mandates. Conventional cotton maintains cost advantages in price-sensitive emerging markets.
- Silk:Mulberry silk and washable silk alternatives serve luxury tiers with 3-5x unit economics versus commodity fabrics. Chinese sericulture clusters supply raw material to Italian finishing houses for European luxury distribution.
- Polyester:Recycled PET variants from post-consumer bottle feedstock satisfy corporate sustainability pledges without sacrificing wrinkle resistance. Flammability additive requirements in children's categories complicate formulation.
- Bamboo:Mechanically processed bamboo linen and chemically derived viscose/lyocell variants split between premium natural-fiber positioning and mass-market rayon substitutes. Antimicrobial claims face tightening substantiation standards in United States and EU jurisdictions.
Cotton captures absolute shipment volumes; bamboo-derived fibers are climbing the fastest as lyocell production scales.
Target Audience:
Demographic segmentation aligns with sizing standardization, safety regulation intensity, and gift-purchase occasion density.
- Women:Extended size ranges (XS-4X) and maternity-adaptive designs multiply SKU complexity. United States coastal metropolitan markets show highest per-capita expenditure on certified organic and OEKO-TEX labeled products.
- Children:16 CFR Part 1615/1616 flammability testing and snug-fit requirements impose compliance cost layers that favor large manufacturers with dedicated children's product laboratories. Replacement frequency peaks at 3-4 garments annually for rapidly growing toddlers.
- Men:Simplified silhouette preferences and lower fashion-cycle sensitivity compress design-to-shelf timelines. Big-and-tall sub-segments command margin premiums due to limited competition.
- Infants:Flame-resistant sleep sacks and swaddles replace loose garments for safety compliance. Hospital discharge gift sets and baby registry channels drive concentrated purchase occasions.
Women's segments generate the highest absolute revenue; infants show the steepest expansion trajectory amid safety-product premiumization.
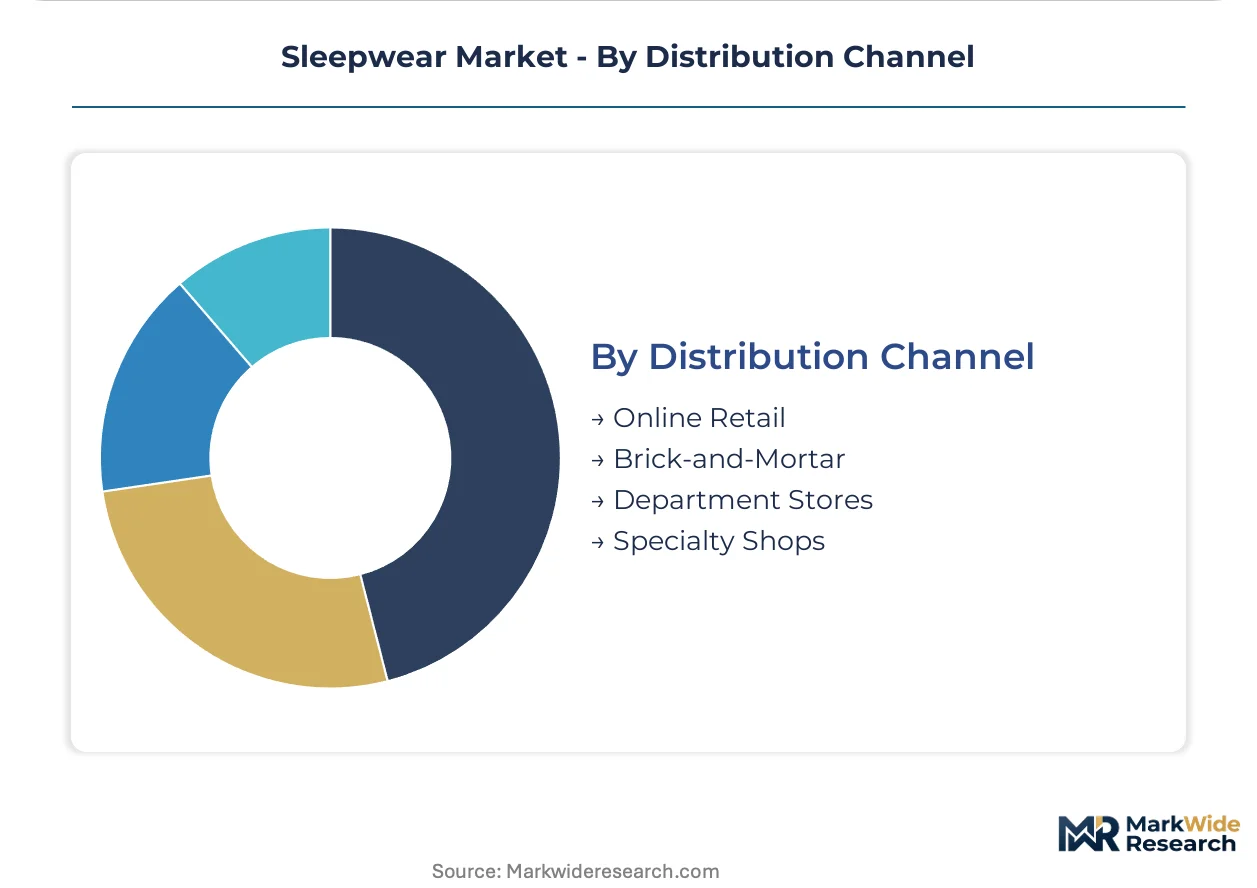
Distribution Channel:
Channel selection determines inventory risk allocation, return-rate exposure, and customer data capture depth for direct relationship building.
- Online Retail:Brand-owned storefronts and marketplace platforms consolidate Millennial and Gen Z purchasing through subscription replenishment and size-prediction algorithms. Return rates run 25-35% versus sub-10% for physical retail.
- Brick-and-Mortar:Impulse purchase velocity and tactile fabric evaluation sustain mass-market volume. United States off-price retailers move excess inventory from full-price channels.
- Department Stores:Curated brand assortments and seasonal visual merchandising support gift-oriented transactions. Consolidation among United States and European department store operators is compressing wholesale account bases.
- Specialty Shops:Lingerie boutiques and maternity-focused retailers command service premiums through fitting expertise. Limited geographic footprint constrains scaling for emerging brands.
Brick-and-Mortar still handles the greatest transaction volume; Online Retail is gaining share fastest through mobile-first purchasing interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City anchors the sleepwear demand concentration in North America, with direct-to-consumer brands clustering in Brooklyn and Manhattan to access design talent and logistics infrastructure. Millennial purchasing power in coastal metropolitan corridors sustains premium loungewear crossover volumes.
United States
Premium loungewear crossover demand concentrates in California and New York metropolitan markets, where consumers merge sleepwear with daytime apparel categories. The US Consumer Product Safety Commission enforces 16 CFR Part 1615 and 1616 flammability standards for children's sleepwear, adding compliance cost layers. Los Angeles hosts the largest concentration of direct-to-consumer sleepwear startups leveraging subscription replenishment models.
Germany
EU Green Deal circularity mandates are restructuring procurement priorities for German retail chains, forcing suppliers toward organic cotton certification. The European Chemicals Agency administers REACH substance restrictions that require dyestuff reformulation across textile finishing processes. North Rhine-Westphalia's textile manufacturing corridor is retooling for closed-loop lyocell production to meet retailer recycled-content verification requirements.
China
Raw material processing and silk finishing operations cluster in Zhejiang and Jiangsu provinces, supplying mulberry silk to European luxury houses. GB national standards diverge from EU and US testing protocols, forcing parallel certification tracks for export-oriented manufacturers. The Pearl River Delta's integrated textile-apparel corridor is upgrading solvent recovery systems for bamboo-derived viscose production.
India
Cotton fiber availability and garment stitching capacity concentrate in Gujarat and Tamil Nadu, serving both domestic consumption and export markets. Bureau of Indian Standards certification requirements are tightening for textile chemical inputs in anticipation of EU alignment. Tiruppur's knitwear cluster is expanding GOTS-certified organic cotton processing to capture European retail procurement shifts.
United Kingdom
Department store consolidation and online channel migration are compressing wholesale account bases for sleepwear suppliers serving British consumers. The UK's post-Brexit regulatory divergence from EU REACH creates parallel compliance obligations for brands operating across both markets. London's design studios are pivoting toward OEKO-TEX Standard 100-labeled product development to maintain continental European market access.
Sleepwear Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tiers and channel control dimensions. The vendor base organizes around vertically integrated manufacturers with captive fiber sourcing, brand-holding conglomerates with portfolio breadth, and direct-to-consumer specialists with digital-native customer acquisition. Three archetypes dominate: integrated producers controlling upstream cotton and lyocell supply, multi-brand licensors spanning mass-market and luxury tiers, and subscription-model disruptors bypassing wholesale intermediaries. Capacity expansion in South Asia and M&A-driven brand portfolio consolidation represent the dominant competitive moves.
Within the integrated manufacturing tier, Hanesbrands Inc. and MAS Holdings Limited exemplify archetypes of upstream supply control. Hanesbrands anchors North American market presence through in-house fiber sourcing networks spanning multiple continents. MAS Holdings occupies a position as a Sri Lanka-based supplier serving stringent EU buyer compliance protocols. PVH Corporation represents the multi-brand portfolio approach, with brand holdings spanning differentiated price tiers. These three companies illustrate how competitive positioning stratifies across supply chain depth, geographic production anchoring, and brand architecture breadth.
| Leading Market Players |
|---|
| Jockey International Inc. |
| American Eagle Outfitters Inc. |
| Hanesbrands Inc. |
| MAS Holdings Limited |
| Marks and Spencer Group plc |
| PVH Corporation |
| Hanky Panky Ltd. |
| Triumph International Holdings GmbH |
| L Brands |
| Others |
Cost & Logistics Intelligence
Closed-loop lyocell manufacturing expansion is compressing unit economics for solvent-recovered fibers while concentrating production capacity in European and South Asian corridors with certified recovery infrastructure. This dual shift simultaneously lowers input costs for compliant producers and raises barriers for manufacturers lacking solvent recovery capabilities or Green Deal-aligned certification pathways.
Pricing Analysis
Certification-grade premiums anchor value-based pricing tiers, with GOTS organic and OEKO-TEX Standard 100 labels commanding 15-40% shelf price premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by fiber provenance verification and chemical input disclosure depth. Pricing pressure stems from raw cotton commodity volatility and REACH-driven reformulation costs that compress margins on EU-facing production lines. Mass-market private-label buyers exhibit highest price sensitivity, while direct-to-consumer subscription purchasers accept premium positioning for verified sustainable sourcing.
Supply Chain Analysis
Single-source vulnerability sits with Sri Lankan and Bangladeshi garment stitching capacity serving EU and North American retail chains. Raw material dependencies draw from Zhejiang silk finishing clusters, Gujarat cotton ginning operations, and Austrian lyocell solvent recovery facilities. Tariff exposure runs through post-Brexit UK-EU regulatory divergence and potential US preferential trade agreement renegotiations. Distribution runs through vertically integrated brand-owned digital storefronts, wholesale department store networks, and off-price clearance channels for excess inventory liquidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sleepwear sector is transitioning from petrochemical-based rayon to bio-derived lyocell and mechanically processed bamboo linen, with solvent recovery rates and antimicrobial substantiation standards replacing legacy cost-plus procurement criteria.
For Market Incumbents:Cement fiber traceability systems through blockchain-verified provenance platforms ahead of EU AI Act disclosure mandates. Capture backward integration into organic cotton ginning or closed-loop lyocell solvent recovery to defend margin position against commodity fiber price spikes. Prioritize R&D investment in phase-change temperature regulation fabrics to differentiate from fast-fashion entrants lacking technical textile capabilities.
For New Entrants and Emerging Players:REACH amendments in Europe and flammability standard complexity in the United States open a window for specialized compliance-as-a-service positioning. Target direct-to-consumer subscription replenishment in male sleep shirts and infant sleep sacks, segments with simplified sizing and concentrated purchase occasions. Lead with OEKO-TEX or GOTS certification as the go-to-market anchor to bypass wholesale gatekeeper resistance.
For Investors and Strategic Acquirers:Exit pathways concentrate in brand portfolio rollup transactions by multi-brand conglomerates seeking loungewear crossover exposure. Five-to-ten year viability favors targets with captive South Asian production and established EU buyer compliance protocols. Watch lyocell solvent recovery rate benchmarks as the inflection signal separating scalable mid-market suppliers from stranded conventional rayon assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Lyocell Capacity Expansion | Solvent recovery rates above 99% satisfy EU Green Deal recycled content verification for H&M and Zara procurement. |
| Direct-to-Consumer Subscription Launch | Automated replenishment bypasses wholesale margin compression while capturing Millennial preference for certified organic labels. |
| Blockchain Fiber Traceability Implementation | EU AI Act supply-chain disclosure mandates reward early adopters with preferred retail placement in German and French chains. |
| Temperature-Regulating Fabric R&D Partnership | Phase-change material integration enables premium positioning in climate-adaptive segments above commodity nightwear tiers. |
| South Asian Production Footprint Consolidation | Captive stitching capacity in Sri Lanka or Bangladesh insulates against port congestion and single-source geopolitical disruption. |
Research Approach
Trade databases, customs filings, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with brand managers, category buyers at department stores, supply planners, and textile certification auditors. Bottom-up shipment data triangulated against top-down retail audit estimates from Nielsen and Circana validated volume assumptions across product type, material, and channel segments.
Historical trendline analysis established baseline growth trajectories across the projection horizon, with CAGRs derived from segment-level elasticity modeling against fiber input cost indices and regulatory implementation timelines. Segmentation dimensions included product construction, fiber certification tier, demographic target, and distribution channel control intensity, with lyocell production scale-up rates and REACH substance restriction amendment schedules serving as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for mechanical bamboo linen versus chemically derived viscose would alter the outlook for antimicrobial claim substantiation and premium pricing sustainability. Deviation in EU Green Deal enforcement timelines or raw cotton harvest variability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
France Denim Jeans Market
Apparel & Footwear
Insulated Jacket Market
Apparel & Footwear
Loungewear Market
Apparel & Footwear
Southeast Asia Lingerie Market
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Women's Sports and Swimwear Market
Apparel & Footwear
Innerwear Market
Apparel & Footwear
Global Apparel Market
Apparel & Footwear
Women's Coats and Jackets Market
Apparel & Footwear
Intimate Wear Market