
 Maternity Apparels Market | 2026-2036
Maternity Apparels Market Size, Share, and Industry Trends Forecast 2026-2036
Maternity Apparels Market Foresight
Aftermarket styling services and postpartum wardrobe consulting is narrowing as a standalone revenue stream, forcing brands to bundle these offerings with core apparel sales. Seraphine leverages its British heritage and royal associations to command premium positioning across European department stores. H&M MAMA sustains volume leadership through its fast-fashion supply chain and accessible price architecture in over 50 markets. PinkBlush Maternity differentiates through direct-to-consumer digital marketing and rapid inventory turnover of trend-driven maternity dresses.
Maternity apparels constitute specialized garments engineered with expandable waistbands, ruched side panels, and stretch recovery fabrics to accommodate gestational body changes while maintaining professional and social wearability. Construction typically employs four-way stretch knits with minimum 15% elastane content to preserve shape through repeated washing and wear cycles. Dresses and tops dominate current revenue pools, though activewear represents the fastest-expanding style category as athletic brands extend sizing into maternity lines. Cotton and spandex blends anchor mainstream production, while linen segments serve premium summer collections with higher unit economics but seasonal demand concentration.
FDA textile contact standards, EU REACH chemical restrictions, and OEKO-TEX certification requirements collectively elevate compliance costs for maternity brands sourcing dyed and finished fabrics. These frameworks particularly restrict formaldehyde levels and azo dyes in skin-proximate garments, pushing manufacturers toward certified organic supply chains and third-party lab testing. Stakeholders must monitor evolving state-level right-to-repair legislation and extended producer responsibility proposals that could reshape returns processing and end-of-life garment collection obligations.
Market Dynamics
EU REACH chemical restrictions and OEKO-TEX certification mandates are forcing maternity apparel manufacturers to abandon conventional dye houses and rebuild supply chains around certified organic cotton and modal-spandex blends.
Growth Catalysts
- Millennial and Gen Z maternal demographics:First-time mothers born 1981-2012 now constitute the dominant purchasing cohort, driving preference for direct-to-consumer digital platforms and rapid inventory turnover models over traditional department store channels.
- REACH-compliant organic textile standards:The European Chemicals Agency's expanded restrictions on formaldehyde and azo dyes in skin-proximate garments are accelerating manufacturer migration toward certified supply chains with third-party lab verification.
- Athleisure crossover demand:Athletic brands extending sizing into dedicated maternity lines are capturing pregnant consumers seeking performance fabrics with four-way stretch recovery for prenatal fitness and workplace wearability.
Market Restraints
- Elastane price volatility:Petroleum-derived spandex input costs fluctuate with crude oil benchmarks, compressing margins on cotton-spandex blend garments that anchor mainstream production volumes.
- Seasonal demand concentration:Linen-based premium summer collections generate higher unit economics but face inventory risk from narrow selling windows concentrated in temperate climate zones.
- Extended producer responsibility proposals:Emerging state-level right-to-repair legislation threatens to impose end-of-life garment collection obligations that would reshape returns processing economics for online maternity retailers.
Strategic Opportunities
- Postpartum wardrobe consulting bundles:Aftermarket styling services are narrowing as standalone revenue streams, creating white space for brands that integrate consulting with core apparel subscriptions through recurring revenue models.
- AI-driven fit prediction:Machine learning algorithms analyzing gestational body measurement data are converging with virtual try-on interfaces to reduce return rates for direct-to-consumer maternity brands.
- India domestic market penetration:Rising urban middle-class birth rates and expanding modern trade retail footprints present underexploited growth potential for international maternity apparel entrants.
Industry Challenges
- Third-party certification timelines:OEKO-TEX and GOTS verification processes extend 12-18 months, delaying product launches and requiring advance capital commitment to undecorated fabric inventories.
- Legacy ERP integration with DTC platforms:Established manufacturers with wholesale-centric systems face technical debt burdens when connecting inventory management to real-time direct-to-consumer fulfillment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternity Apparels Market |
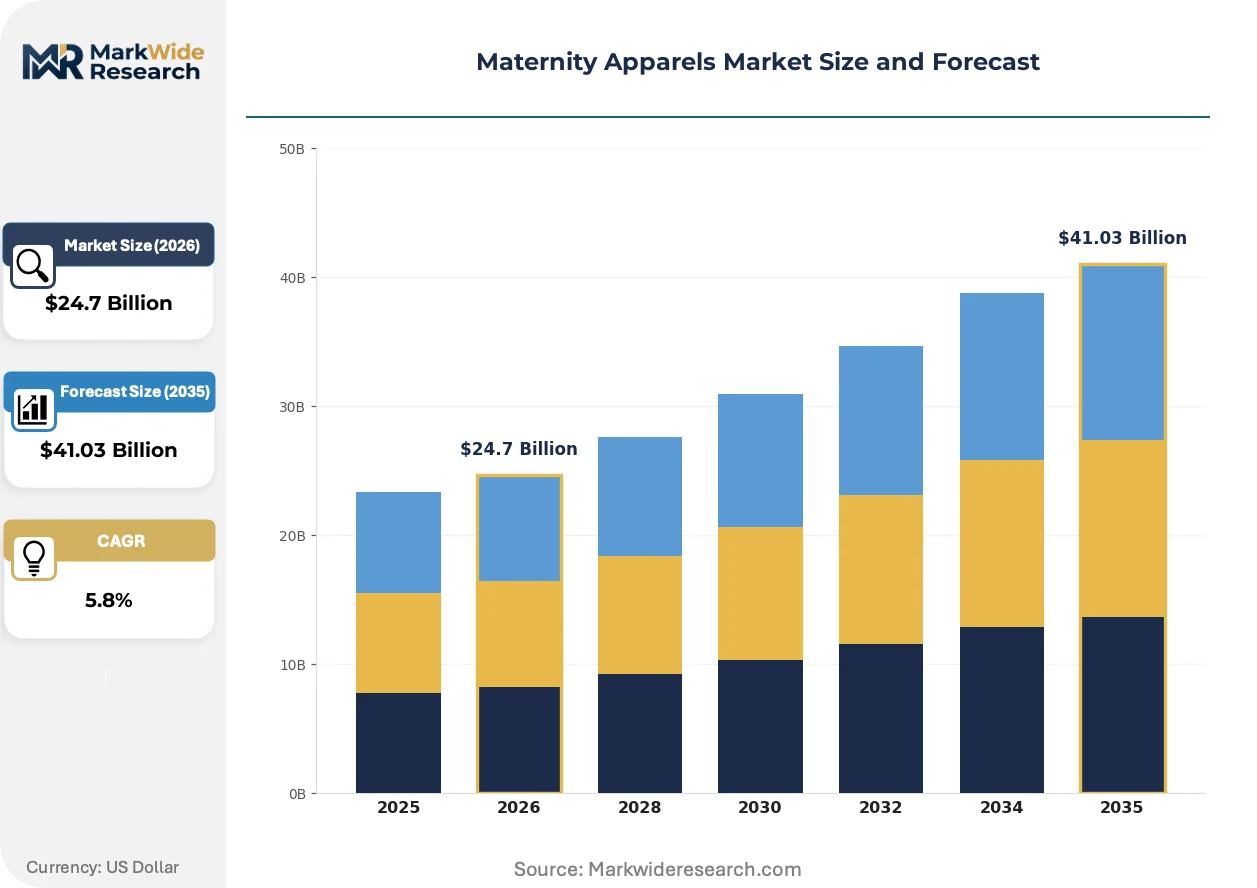
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $41.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dresses, Tops, Bottoms, Sleepwear Fabric Type: Cotton, Linen, Spandex, Rayon End User: Pregnant Women, New Moms, Expecting Couples, Healthcare Professionals Style: Casual, Formal, Activewear, Evening Wear |
| Companies Covered | Hatch, ASOS Maternity, Seraphine, A Pea in the Pod, PinkBlush Maternity, Motherhood Maternity, Isabella Oliver, Ingrid & Isabel, H&M MAMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternity Apparels Market Shifts & Advancements
Digital measurement capture and predictive sizing algorithms are compressing return rates and reshaping how maternity brands architect inventory depth across gestational stages.
3D body scanning paired with smartphone photogrammetry is digitizing the fit prediction process for remote maternity shoppers. Direct-to-consumer brands deploying these tools report reduced size-related returns and improved customer lifetime value metrics. The technology is digitizing traditional size-chart assumptions that failed to account for trimester-specific body morphologies.
EU REACH Annex XVII restrictions on skin-sensitizing chemicals are tightening compliance windows for dyed maternity garments. Manufacturers now face mandatory third-party lab testing for formaldehyde residuals before market entry. Activewear segments with higher elastane content are absorbing disproportionate compliance costs due to chemical finishing requirements on performance fabrics.
Subscription-based maternity wardrobe rental is displacing outright purchase for professional working mothers seeking trimester-appropriate attire without storage burdens. Corporate benefit programs covering rental allowances are emerging as a channel innovation in the United States and United Kingdom. This model concentrates demand among technology and professional services employers competing for female talent retention.
Maternity Apparels Market Segmentation
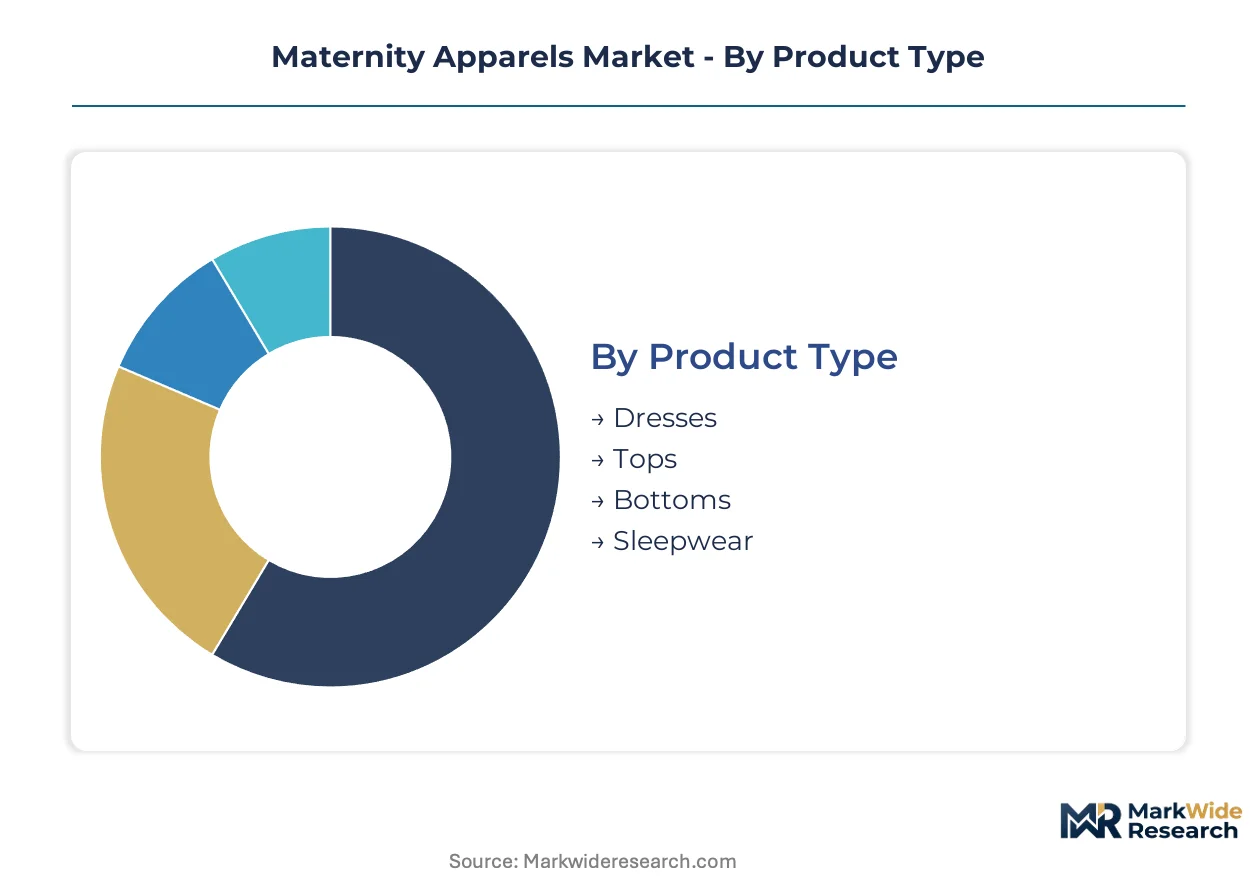
Maternity apparel segmentation reflects distinct gestational use cases spanning professional environments, domestic settings, and clinical contexts. Each category maps to specific fabric performance requirements and trimester-specific body morphologies that shape procurement decisions.
Product Type:
The use-case spectrum spans workplace presentation, sleep comfort, and everyday mobility across gestational stages.
- Dresses:Ruched side panels and empire waist construction accommodate expanding abdominal circumference through second and third trimesters. United States demand concentrates among professional services employees seeking boardroom-appropriate silhouettes without size turnover. E-commerce return rates remain elevated due to gestational-stage sizing mismatches.
- Tops:Stretch recovery fabrics with minimum 15% elastane content anchor mainstream production volumes. China manufacturing clusters dominate cut-and-sew capacity for basic knit tops serving mass-market retailers. Modal-spandex blends are displacing conventional cotton-polyester in direct-to-consumer channels.
- Bottoms:Expandable waistband systems with hidden elastic channels serve workplace and casual segments.
- Sleepwear:Soft modal and bamboo-derived fabrics address temperature regulation during third-trimester sleep disruption.
Established volume favors Tops; emerging adoption favors Dresses as professional return-to-office protocols accelerate.
Fabric Type:
Cost tier differentiation separates certified organic supply chains from conventional petroleum-derived inputs.
- Cotton:Four-way stretch knits with elastane reinforcement preserve shape through repeated washing cycles. United Kingdom retailers emphasize GOTS-certified organic cotton to satisfy ECHA REACH compliance windows. Third-party lab verification extends 12-18 months, delaying product launches.
- Spandex:Petroleum-derived elastane inputs fluctuate with crude oil benchmarks, compressing margins on blend garments. Activewear manufacturers absorb disproportionate finishing costs due to chemical treatment requirements on performance fabrics. OEKO-TEX certification mandates are forcing migration toward certified supply chains.
- Linen:Premium summer collections generate higher unit economics but face narrow selling windows.
- Rayon:Viscose-derived cellulosic fibers serve budget-tier production with drape characteristics mimicking silk.
Procurement is shifting toward Cotton for compliance certainty; Spandex retains cost volatility exposure.
End User:
Customer type stratification separates self-purchasing pregnant women from gift-buying segments and institutional procurement.
- Pregnant Women:First-time mothers born 1981-2012 constitute the dominant purchasing cohort, driving direct-to-consumer platform preference. Digital measurement capture and predictive sizing algorithms are compressing return rates. Subscription-based wardrobe rental is displacing outright purchase for professional working mothers.
- New Moms:Postpartum body transitions create demand for nursing-compatible construction with concealed access panels. Corporate benefit programs covering rental allowances are emerging as a channel innovation in the United States.
- Expecting Couples:Gift purchases concentrate in third-trimester baby shower contexts with lower price sensitivity.
- Healthcare Professionals:Institutional scrubs and uniform programs require antimicrobial finishing and industrial laundering durability.
Pregnant Women anchor volume concentration; New Moms represent the steepest expansion trajectory as postpartum service bundles proliferate.
Style:
Application context separates domestic leisure from professional and social presentation requirements.
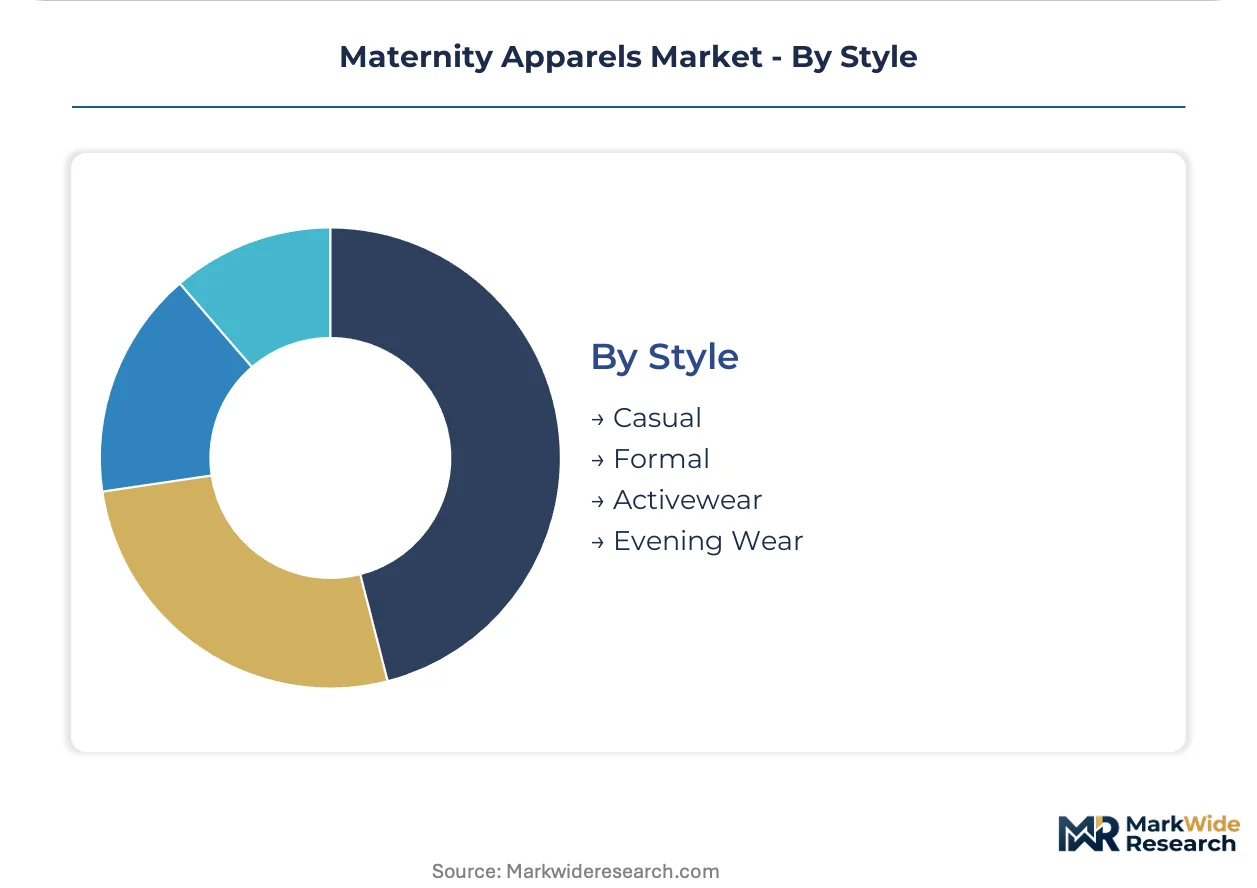
- Casual:Everyday knit construction with ruched detailing serves grocery, school pickup, and domestic mobility contexts. H&M MAMA sustains volume leadership through fast-fashion supply chains in over 50 markets. Accessible price architecture drives repeat purchase frequency.
- Activewear:Athletic brands extending sizing into dedicated maternity lines capture prenatal fitness demand. Four-way stretch recovery fabrics serve workplace wearability crossover. United States and United Kingdom clusters show densest adoption among technology sector employees.
- Formal:Tailored suiting and structured dresses address courtroom, boardroom, and ceremonial occasions.
- Evening Wear:Special-occasion construction with embellished detailing serves wedding guest and holiday party contexts.
Casual commands production scale; Activewear is accelerating fastest as athletic brand maternity extensions multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States buyers absorb premium positioning for workplace-appropriate maternity lines, while Indian consumers gravitate toward accessible price tiers despite rising disposable incomes.
United States
Professional services employees drive boardroom-appropriate maternity dress demand with elevated price tolerance. FDA textile contact standards enforce formaldehyde limits on skin-proximate garments. New York and Los Angeles anchor corporate benefit programs covering subscription-based wardrobe rental allowances.
China
Expanding modern trade retail footprints and urban middle-class birth rates concentrate procurement volume. GB standards and SAMR oversight govern textile safety labeling for domestic distribution. Guangdong and Zhejiang manufacturing clusters dominate cut-and-sew capacity for basic knit tops serving mass-market channels.
United Kingdom
European department store premium positioning leverages heritage branding associations among expectant professionals. ECHA REACH chemical restrictions and OEKO-TEX certification mandates accelerate supply chain migration toward certified organic cotton. London retail density supports direct-to-consumer platform expansion with rapid inventory turnover.
India
Rising urban middle-class birth rates present underexploited growth potential for international maternity entrants with localized sizing. BIS textile standards govern fiber content disclosure and safety labeling requirements. Maharashtra and Karnataka modern trade expansion concentrates distribution infrastructure for organized retail penetration.
Germany
REACH-compliant organic textile preferences elevate procurement standards for skin-sensitizing chemical restrictions. KBA and federal consumer protection frameworks enforce rigorous third-party lab verification protocols. Bavaria and North Rhine-Westphalia industrial clusters absorb disproportionate compliance costs for performance fabric finishing requirements.
Maternity Apparels Market Competitive Landscape
Capability concentration sits with premium heritage specialists; scale advantage sits with fast-fashion supply chain operators. The market structures around three tiers: direct-to-consumer digital natives, multi-channel heritage houses, and mass-market volume leaders. Strategic moves converge on AI-driven fit prediction deployment and postpartum service bundle integration to compress return rates and extend customer lifetime value.
Within the heritage premium tier, Seraphine occupies a position exemplifying British heritage positioning across European department store channels. H&M MAMA anchors the scale-driven mass-market vector through accessible price architecture spanning over fifty markets. PinkBlush Maternity represents the direct-to-consumer digital native archetype with rapid inventory turnover of trend-driven maternity dresses.
| Leading Market Players |
|---|
| Hatch |
| ASOS Maternity |
| Seraphine |
| A Pea in the Pod |
| PinkBlush Maternity |
| Motherhood Maternity |
| Isabella Oliver |
| Ingrid & Isabel |
| H&M MAMA |
| Others |
Supply & Pricing Matrix
Guangdong and Zhejiang manufacturing clusters anchor global cut-and-sew capacity for maternity knit tops, concentrating margin capture among mass-market retailers with scale procurement leverage over tier-one dye houses and fabric finishers.
Pricing Analysis
Postpartum wardrobe consulting bundles now drive lifetime value more than standalone garment margins. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified organic lines from conventional cotton-spandex blends and budget viscose alternatives. Pricing pressure stems from elastane cost volatility tied to crude oil benchmarks, compressing margins on four-way stretch recovery fabrics. Mass-market retailers show highest price sensitivity, while professional services employees absorb premiums for boardroom-appropriate silhouettes.
Supply Chain Analysis
Contract manufacturing concentration sits with vertically integrated textile groups in Bangladesh, Vietnam, and southern China holding GOTS-certified organic cotton finishing capacity. Raw material flows draw from petroleum-derived elastane producers, certified organic cotton gins, and modal-spandex blend specialists. Single-source vulnerability concentrates in OEKO-TEX certified dye houses facing 12-18 month verification timelines. Distribution runs through direct-to-consumer platforms, European department store networks, and modern trade retail footprints in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward millennial and Gen Z first-time mothers consolidating purchasing decisions on direct-to-consumer platforms, fragmenting traditional department store channel control.
For Market Incumbents: Insulate market position by deepening backward integration into certified organic cotton supply chains before REACH compliance windows tighten further. Accelerate AI-driven fit prediction deployment to compress return rates that erode direct-to-consumer margins. Channel control through corporate benefit program partnerships offers defensive leverage against pure-play digital entrants. For New Entrants and Emerging Players: India domestic market penetration presents the most accessible white-space target, with Maharashtra and Karnataka modern trade expansion concentrating distribution infrastructure. Postpartum wardrobe consulting bundles integrated with subscription recurring revenue models offer differentiation against transaction-focused competitors. Localized sizing adaptation for South Asian body morphologies provides essential go-to-market credibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer digital natives holding proprietary gestational body measurement datasets but facing customer acquisition cost inflation. Long-term viability across a 5-10 year window favors platforms with subscription recurring revenue models over transaction-dependent peers. The signal to watch is corporate benefit program adoption velocity as employer-sponsored maternity wardrobe allowances expand.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Fit Prediction Deployment | Machine learning algorithms analyzing gestational body data reduce return rates for direct-to-consumer brands. |
| Certified Organic Supply Chain Migration | GOTS and OEKO-TEX verification timelines force advance capital commitment to undecorated fabric inventories. |
| Postpartum Service Bundle Integration | Aftermarket styling services bundled with core apparel subscriptions extend customer lifetime value metrics. |
| Corporate Benefit Program Partnership | Employer-sponsored wardrobe rental allowances emerge as channel innovation in United States and United Kingdom. |
| India Market Localization | Rising urban middle-class birth rates and modern trade expansion present underexploited growth potential. |
Research Methodology
Cross-validation between primary interviews with brand managers, category buyers at retailers, supply planners, and channel sales heads and secondary validation anchors the qualitative findings. Primary fieldwork draws from maternity apparel brand executives, textile procurement leads, direct-to-consumer platform operators, and European department store buyers. Secondary sources include customs and trade data, OEKO-TEX and GOTS certification databases, SEC filings from publicly traded parent companies, and retail audit data from Nielsen and Circana. Bottom-up sizing of segment volumes triangulates against top-down macroeconomic calibration.
Calibration against historical volume trajectories and elasticity assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, fabric certification tier, end-user archetype, and style application context. CAGRs derive from regression analysis of segment-level growth drivers. Industry-specific forecast inputs incorporate birth rate projections, elastane price indices, and e-commerce penetration curves by geography.
Practitioners should monitor REACH chemical restriction amendments, extended producer responsibility legislation, and elastane price volatility for early signals of forecast revision. Assumptions reflect current regulatory frameworks and supply chain configurations. Quarterly review of certification timeline delays, corporate benefit program adoption rates, and return rate compression metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Press-To-Close Zippers Market
Apparel & Footwear
Womens Swimwear Market
Apparel & Footwear
School Shoes Market
Apparel & Footwear
Football Kits Market
Apparel & Footwear
Smart Wardrobe Market
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Asia Pacific Hats Market
Apparel & Footwear
Global Sleepwear and Loungewear Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Outdoor Apparel Market
Apparel & Footwear
Apparel Dry Wash Spray Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Hats Market
Apparel & Footwear
Yoga Clothing Market
Apparel & Footwear
Maternity Activewear Market