
 France Denim Jeans Market | 2026-2036
France Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
France Denim Jeans Market Insights
Premium selvedge and raw denim specifications is unwinding across the France denim jeans market as consumers trade up from mass-market basics. Levi Strauss & Co sustains brand authority through heritage positioning and controlled wholesale distribution. Kering SA leverages luxury craft credentials to command price premiums in specialty boutique channels. Atelier Tuffery anchors artisanal domestic production with vertically controlled atelier manufacturing in southern France.
France denim jeans denote trousers constructed from twill-woven cotton fabric with a minimum 12-ounce weight, utilizing indigo-dyed warp threads and undyed weft to create characteristic fading patterns through industrial washing or raw wear cycles. The garment serves commercial fashion retail and workwear applications across gendered and age-differentiated consumer bases. Slim fit and skinny silhouettes dominate unit volume in urban retail, while stretch denim incorporating elastane blends captures expanding margin pools through technical performance premiums. Organic cotton and recycled denim materials represent the fastest-ascending structural segment as regulatory pressure and consumer environmental scrutiny intensify procurement specifications.
ANSM and CNIL govern consumer product safety and data privacy frameworks affecting denim e-commerce operations, while REACH and the EU Green Deal impose chemical restriction and circularity obligations on textile supply chains. These regulatory layers elevate compliance costs for imported materials while creating competitive shelter for domestic producers meeting stricter environmental benchmarks. Stakeholders must monitor evolving extended producer responsibility mandates and traceability requirements that will reshape sourcing decisions and channel economics.
Market Dynamics
REACH compliance and the EU Green Deal's textile sustainability mandates are forcing wholesale reformulation of raw material procurement across French denim supply chains. Domestic ateliers and mass-market importers alike face escalating compliance costs that favor regional sourcing clusters.
Growth Catalysts
- EU Green Deal circularity mandates:Extended producer responsibility frameworks accelerate investment in closed-loop denim recycling infrastructure across French manufacturing zones.
- Casual workplace normalization:Technology and creative-sector employers in Paris and Lyon relax dress codes, expanding daily-wear denim demand among young professional cohorts.
- Selvedge craft revival:Heritage shuttle-loom production techniques attract premium positioning in specialty boutique channels concentrated in the Marais and Canal Saint-Martin districts.
Market Restraints
- Organic cotton input cost volatility:Weather-driven yield fluctuations in Turkish and Greek supply basins compress margin structures for mid-tier French labels.
- Asian supplier concentration:Reliance on Bangladeshi and Vietnamese cut-make-trim facilities exposes brands to shipping lane disruptions and tariff uncertainty.
- Technical limitation in elastane recycling:Current mechanical shredding processes cannot cleanly separate spandex blends from cotton fiber, constraining circularity claims.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur underpenetration:Marseille and Nice retail corridors lack dedicated premium denim concepts relative to Parisian saturation.
- Regulatory tailwind from CSRD disclosure rules:Mandatory supply-chain transparency reporting advantages domestic producers with shorter, auditable supplier networks.
- Direct-to-consumer channel innovation:Made-to-measure digital platforms incorporating 3D body scanning reduce return rates and deepen customer lifetime value.
Industry Challenges
- Heritage craft skill scarcity:Master pattern-cutters and indigo dyers with traditional expertise are aging out of the workforce faster than apprenticeship pipelines refill.
- Certification timeline compression:OEKO-TEX and GOTS audit backlogs delay product launches by four to six months for emerging labels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Denim Jeans Market |
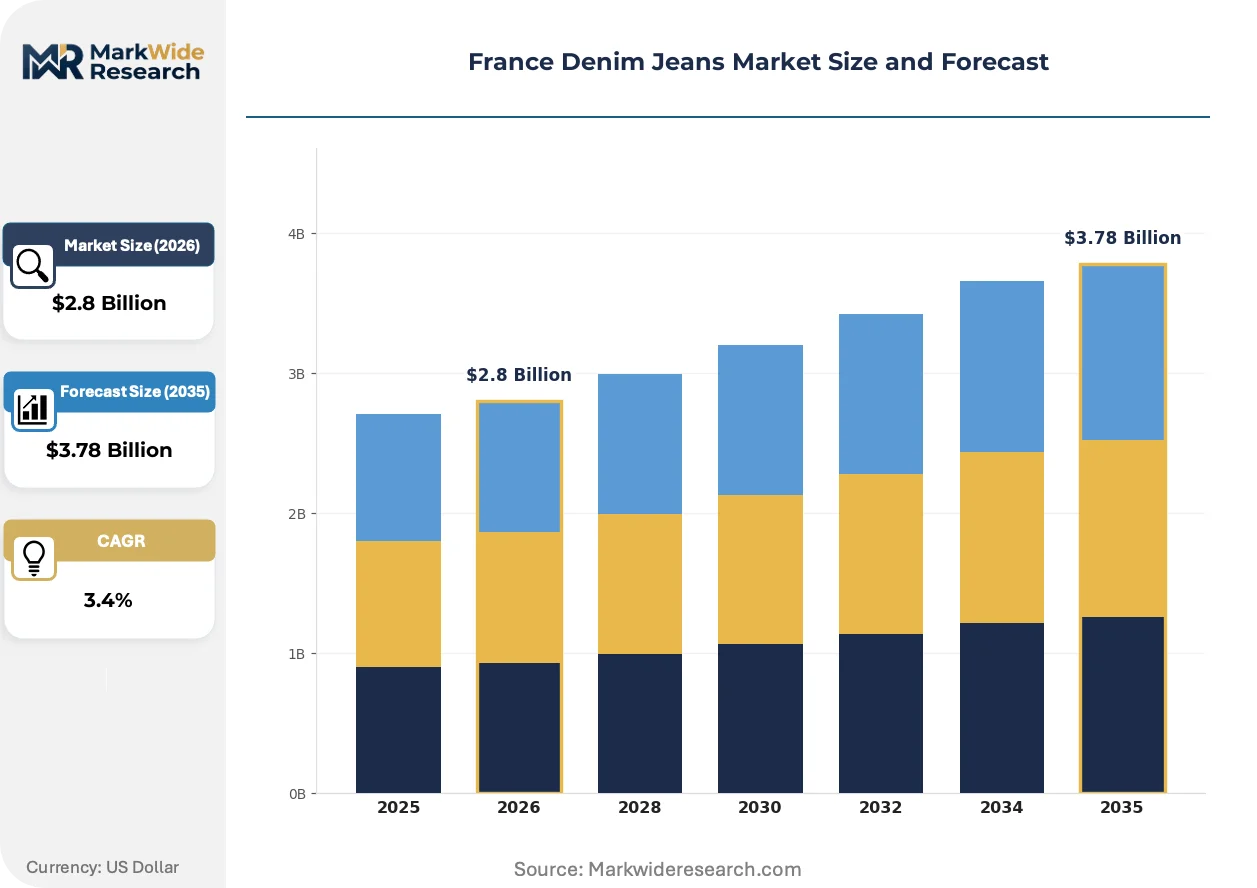
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slim Fit, Regular Fit, Bootcut, Skinny, Straight Leg Material: 100% Cotton, Cotton Blend, Stretch Denim, Organic Cotton, Recycled Denim End User: Men, Women, Teenagers, Elderly, Young Adults Distribution Channel: Online Retailers, Department Stores, Specialty Boutiques, Outlet Stores, Direct-to-Consumer |
| Companies Covered | Gap Inc, Pepe Jeans, Kering SA, Atelier Tuffery, Bestseller, Levi Strauss & Co, Hennes & Mauritz AB, PVH Corp, VF Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Denim Jeans Market Trends and Innovations
Laser finishing and ozone washing systems are displacing traditional water-intensive processes across French denim laundries. Three material and operational shifts define current competitive investment priorities.
Digital laser surface treatment technology is miniaturizing the environmental footprint of vintage-effect production. Atelier-scale operators in Lyon and Nîmes deploy compact fiber-laser units that replicate whiskering and abrasion without potassium permanganate sprays. Young adult consumers reward these transparency credentials with repeat purchase loyalty.
REACH chemical restriction amendments tighten permissible limits on formaldehyde and heavy metal residues in garment finishing. French import inspectors at Roissy-Charles de Gaulle logistics hubs now sample-test denim shipments against updated SVHC candidate lists. Premium positioning brands absorb compliance costs through price architecture while economy-tier distributors face margin compression.
Secondhand authentication and resale platform integration now accompanies primary retail transactions. Paris-based consignment specialists partner with original manufacturers to verify provenance and condition, capturing margin that previously leaked to informal peer-to-peer markets. Young professional buyers in the Île-de-France region treat certified pre-owned selvedge as a distinct asset class.
France Denim Jeans Market Segmentation
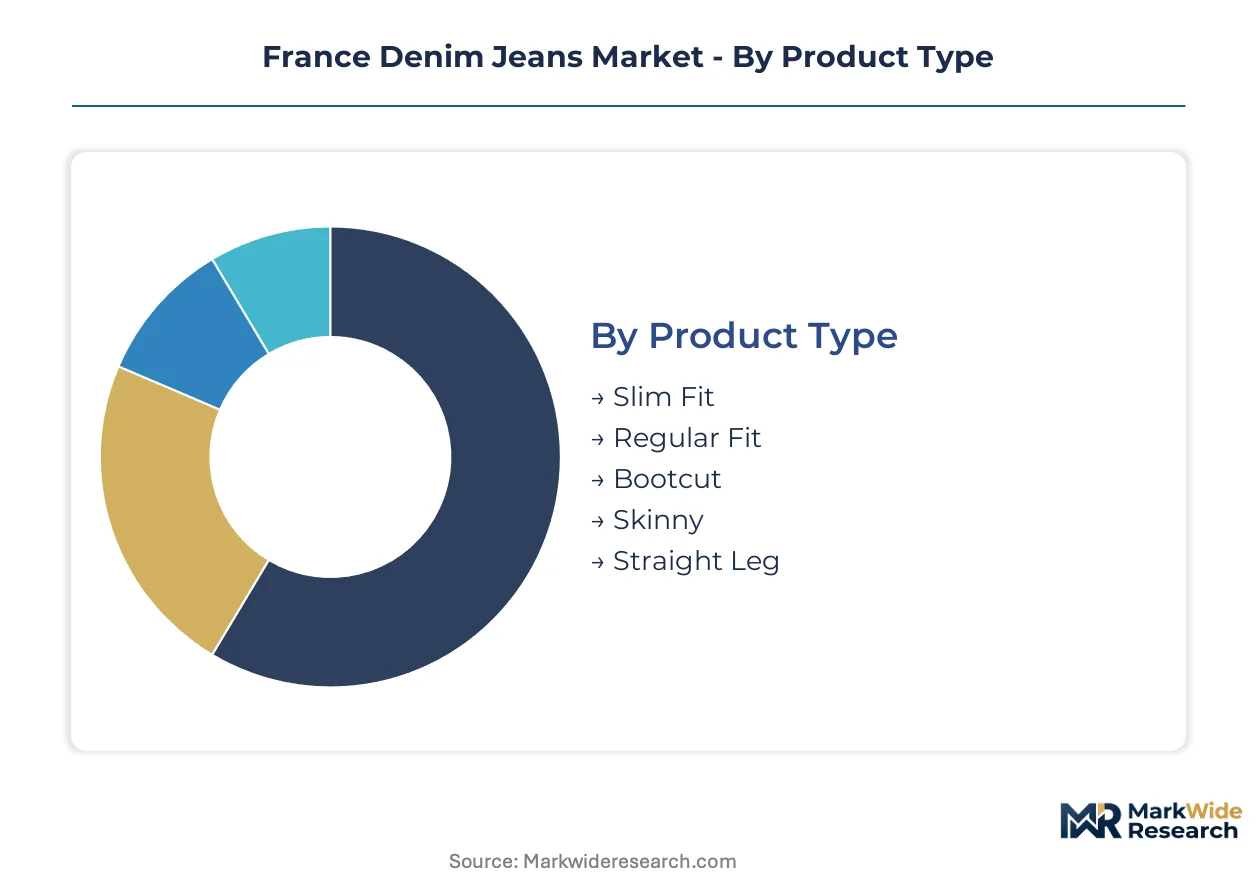
Segmentation in the France denim jeans market reveals how regulatory pressure and channel economics reshape procurement priorities. Distinct material specifications and fit preferences command divergent margin structures across Parisian retail corridors and provincial distribution networks.
Product Type:
Domestic ateliers in Lyon and Nîmes concentrate production on heritage fits requiring shuttle-loom fabrication, while mass-market importers dominate volume-oriented silhouettes through Asian cut-make-trim partnerships.
- Slim Fit:Tapered leg opening with reduced thigh circumference defines this urban-dominant specification. Parisian young professionals drive demand through Canal Saint-Martin specialty retailers, with stretch-integrated variants capturing technical performance premiums.
- Skinny:Second-skin compression fit utilizing high elastane content creates distinct recycling constraints. Marseille and Nice retail corridors show underpenetration relative to Paris saturation, presenting geographic expansion opportunity.
- Regular Fit:Classic straight thigh-to-hem proportion serves aging demographic bases in provincial France.
- Bootcut:Flared leg opening accommodates Western-inspired styling in southern regional markets.
- Straight Leg:Uniform width from knee to ankle appeals to heritage craft enthusiasts seeking vintage reproduction authenticity.
Slim Fit holds the largest share; momentum sits with Skinny as elastane blend innovation expands addressable occasions.
Material:
Cost tier stratification separates premium fiber inputs from commodity denim, with regulatory compliance costs widening the gap between certified and conventional sourcing.
- Stretch Denim:Cotton-elastane blends incorporating 2-5% spandex enable recovery and shape retention. Technical limitation in elastane recycling constrains circularity claims for French brands pursuing EU Green Deal compliance.
- Organic Cotton:GOTS-certified fiber from Turkish and Greek supply basins commands input cost volatility. ANSM and REACH inspection protocols at Roissy-Charles de Gaulle logistics hubs accelerate procurement timeline compression for emerging labels.
- 100% Cotton:Rigid denim specification serves raw denim enthusiasts seeking personalized fade development.
- Cotton Blend:Polyester or Tencel integration reduces garment weight for seasonal transitional collections.
- Recycled Denim:Post-consumer mechanical shredding faces mechanical separation challenges with elastane-contaminated feedstock.
Stretch Denim dominates unit economics; Organic Cotton climbs the fastest as CSRD disclosure rules advantage auditable supply chains.
End User:
Application-based demand concentration varies sharply between workplace-casual normalization in Île-de-France technology employers and traditional gendered purchasing patterns in provincial retail.
- Young Adults:Technology and creative-sector employees in Paris and Lyon offices normalize daily denim wear through relaxed dress codes. This cohort rewards transparency credentials with repeat purchase loyalty toward laser-finished domestic production.
- Women:Higher average unit purchase frequency combines with premium positioning receptivity in Marais district specialty boutiques.
- Men:Heritage brand affinity and longer replacement cycles characterize this established demand base.
- Teenagers:Price-sensitive volume segment concentrated in fast-fashion retail and online marketplace channels.
- Elderly:Comfort-prioritized fits with higher waist rises and relaxed thighs dominate this provincially distributed cohort.
Women generate the highest revenue concentration; Young Adults gain share fastest through workplace normalization tailwinds.
Distribution Channel:
Margin structure and customer lifetime value diverge between inventory-light digital platforms and experiential physical retail requiring fixed cost absorption.
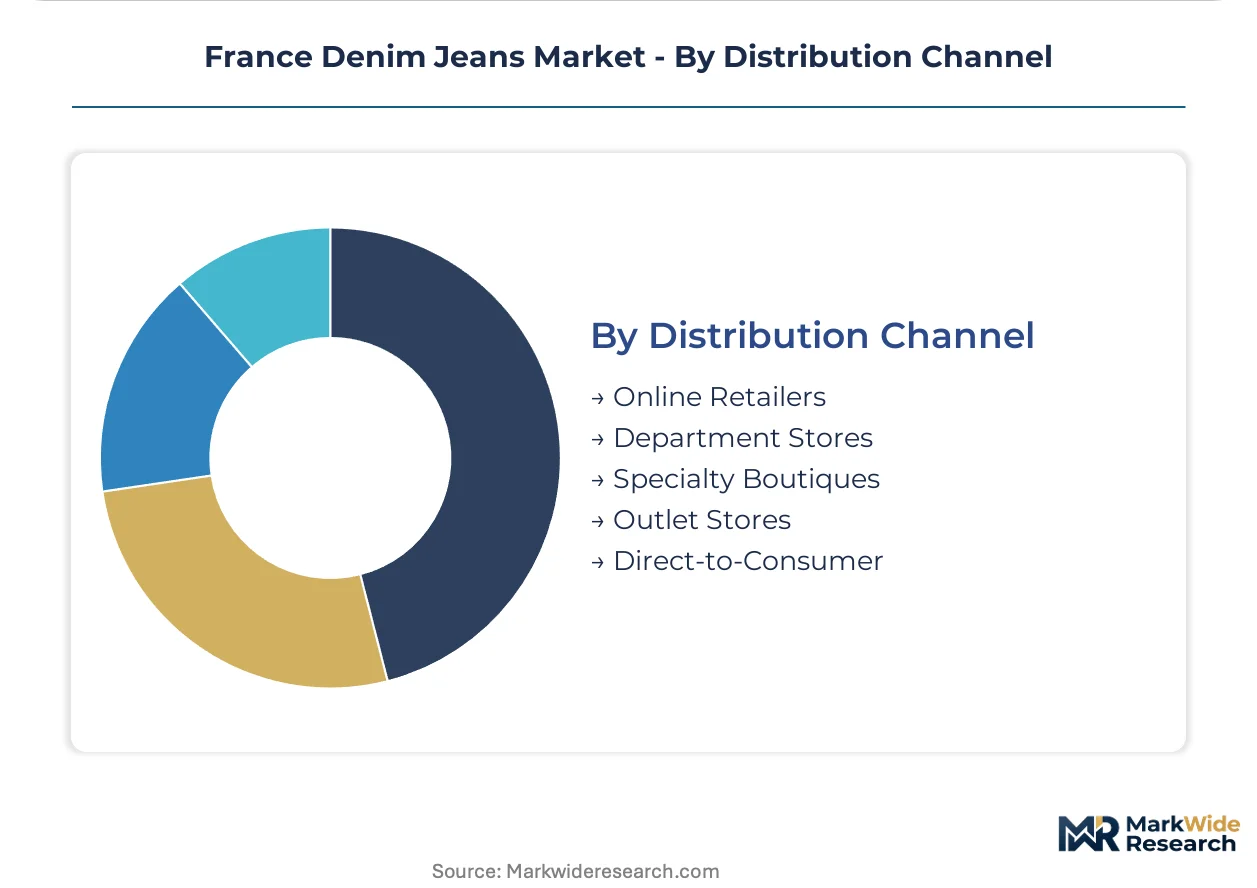
- Direct-to-Consumer:Made-to-measure digital platforms incorporating 3D body scanning reduce return rates. Paris metropolitan concentration enables same-day delivery logistics that deepen customer lifetime value metrics.
- Specialty Boutiques:Curated selvedge and raw denim assortments in Marais and Canal Saint-Martin districts command price premiums through craft narrative authentication.
- Online Retailers:Marketplace aggregation exposes brands to price transparency compression and counterfeit infiltration risk.
- Department Stores:Galeries Lafayette and Printemps Haussmann anchors provide brand discovery for tourist and suburban visitor segments.
- Outlet Stores:Off-price inventory clearance channels manage seasonal overstock from primary retail collections.
Specialty Boutiques capture the highest margin per unit; Direct-to-Consumer shows steepest expansion trajectory as authentication technology reduces fit uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkish denim mills supply raw fabric to ateliers in southern France, while Italian finishing houses process selvedge for Parisian boutiques. This cross-border trade flow concentrates premium sourcing in Mediterranean manufacturing clusters.
Île-de-France
Technology employers in Paris and La Défense normalize casual dress codes, expanding daily-wear denim demand among young professionals. ANSM inspection protocols at Roissy-Charles de Gaulle logistics hubs enforce REACH chemical compliance on imported shipments. The Marais and Canal Saint-Martin districts host specialty boutiques commanding price premiums through craft authentication.
Auvergne-Rhône-Alpes
Lyon's creative-sector workforce drives slim-fit and skinny silhouette demand through relaxed workplace norms. EU Green Deal circularity mandates accelerate investment in laser-finishing equipment across regional laundries. The city's textile heritage cluster deploys compact fiber-laser units that replicate vintage effects without potassium permanganate sprays.
Provence-Alpes-Côte d'Azur
Marseille and Nice retail corridors show underpenetration relative to Parisian saturation, presenting geographic expansion opportunity. CNIL data-privacy frameworks affect e-commerce operations targeting young adult consumers. Regional distributors increasingly partner with direct-to-consumer platforms incorporating 3D body scanning to reduce return rates.
Hauts-de-France
Logistics hubs near Lille and Calais handle inbound Asian cut-make-trim shipments from Bangladeshi and Vietnamese facilities. REACH SVHC candidate list updates trigger sampling protocols at border inspection points. The region's transport infrastructure exposes brands to shipping lane disruption risks from tariff uncertainty.
Nouvelle-Aquitaine
Bordeaux's affluent consumer base rewards transparency credentials in organic cotton and recycled denim procurement. CSRD disclosure rules advantage domestic producers with shorter, auditable supplier networks. Regional retailers face certification timeline compression from OEKO-TEX and GOTS audit backlogs.
France Denim Jeans Market Competitive Landscape
Listed leaders compete with private specialists across channel positioning and material sourcing dimensions. The France denim jeans market structures around heritage brand authority, luxury craft credentials, and artisanal domestic production tiers. Three archetypes dominate: mass-market distributors with controlled wholesale networks, luxury conglomerates leveraging specialty boutique channels, and vertically controlled ateliers. Competitive moves concentrate on direct-to-consumer platform development and circularity infrastructure investment.
Within the heritage brand tier, Levi Strauss & Co and Gap Inc occupy positions anchored in transatlantic denim mythology. Kering SA exemplifies luxury conglomerate strategy through craft narrative authentication. Atelier Tuffery represents the artisanal archetype with vertically controlled manufacturing in southern France. Pepe Jeans and Bestseller sit within mid-market positioning, while PVH Corp, VF Corp, and Hennes & Mauritz AB compete on scale-driven distribution economics.
| Leading Market Players |
|---|
| Gap Inc |
| Pepe Jeans |
| Kering SA |
| Atelier Tuffery |
| Bestseller |
| Levi Strauss & Co |
| Hennes & Mauritz AB |
| PVH Corp |
| VF Corp |
| Others |
Pricing and Supply Chain Analysis
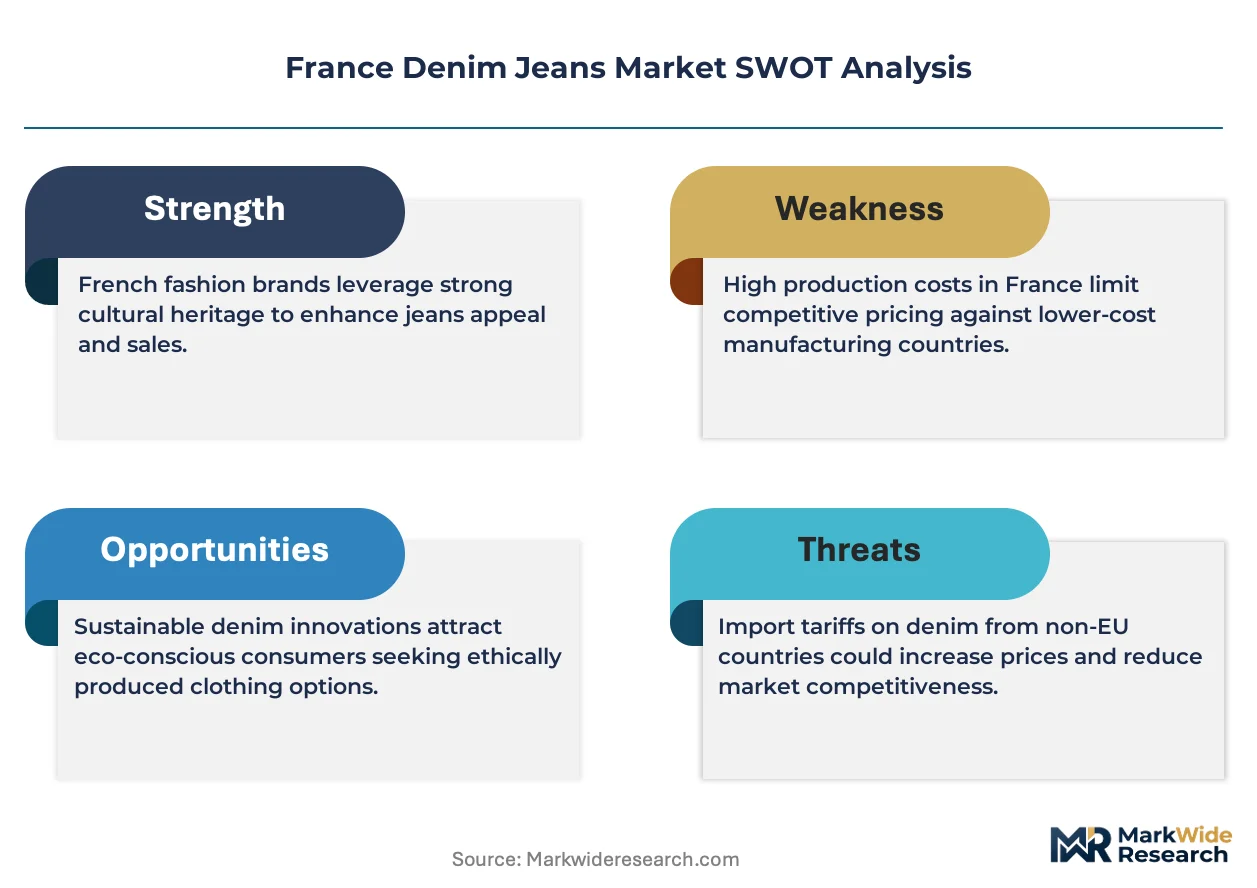
Shuttle-loom capacity utilization in southern French ateliers shapes both supply concentration and price floors for heritage-grade selvedge. Premium positioning absorbs REACH compliance costs through price architecture while economy-tier distributors face margin compression from organic cotton input volatility.
Pricing Analysis
Laser-finishing technology-generation pricing gaps separate atelier-scale operators deploying compact fiber-laser units from legacy laundries using potassium permanganate sprays. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and craft narrative authentication. Cost compression in the mid-tier intensifies because Turkish and Greek organic cotton yield fluctuations compress margin structures. Teenagers in fast-fashion channels exhibit highest price sensitivity; selvedge enthusiasts in Marais boutiques demonstrate least.
Supply Chain Analysis
Roissy-Charles de Gaulle port congestion and container availability constraints on Asian trade lanes elevate inbound logistics costs for Bangladeshi and Vietnamese cut-make-trim shipments. Geographic supply concentration draws from Turkey, Bangladesh, and Vietnam for fabric and finished goods. Raw material dependencies rest on Turkish denim mills, Greek organic cotton basins, and Italian finishing houses. Single-source vulnerability in elastane-blend recycling constrains circularity claims. Distribution runs through Paris metropolitan specialty boutiques and direct-to-consumer platforms with same-day delivery logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master pattern-cutters and indigo dyers with traditional expertise are aging out faster than apprenticeship pipelines refill, creating acute capability scarcity that reshapes competitive positioning.
For Market Incumbents: Consolidate heritage craft credentials through captive atelier acquisitions in Lyon and Nîmes clusters. Absorb REACH compliance costs via price architecture rather than margin sacrifice. Defend against emerging direct-to-consumer platforms by controlling specialty boutique channel relationships in Canal Saint-Martin districts. For New Entrants and Emerging Players: Lead with underpenetrated geography in Marseille and Nice retail corridors where premium denim concepts lag Parisian saturation. Target young adult professionals in Provence-Alpes-Côte d'Azur technology employers normalizing casual dress codes. Deploy made-to-measure digital platforms with 3D body scanning to reduce return rates and build customer lifetime value. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically controlled ateliers with direct-to-consumer channel integration and circularity infrastructure. Long-term viability over a multi-year window favors domestic producers with auditable supplier networks advantaged by CSRD disclosure rules. Target acquisition archetype: artisanal manufacturers with shuttle-loom capacity and laser-finishing equipment installed. Signal to watch: OEKO-TEX and GOTS certification timeline compression easing for emerging labels.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Finishing Equipment Deployment | Compact fiber-laser units in Lyon laundries eliminate potassium permanganate sprays for REACH compliance. |
| Direct-to-Consumer Platform Launch | 3D body scanning integration reduces fit uncertainty and deepens customer lifetime value metrics. |
| Organic Cotton Supply Agreement | GOTS-certified fiber procurement from Turkish and Greek basins hedges input cost volatility. |
| Heritage Craft Apprenticeship Program | Master pattern-cutter and indigo dyer pipeline rebuild addresses aging workforce attrition. |
| Secondhand Authentication Integration | Paris consignment partnerships capture margin leakage from informal peer-to-peer resale markets. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at Galeries Lafayette and Printemps, supply planners, and channel sales heads anchored the qualitative base. Primary interviews combined with secondary validation from customs records, SEC 10-K filings, and Nielsen retail audit data. Bottom-up and top-down triangulation cross-checked volume assumptions against production capacity disclosures and import inspection protocols at Roissy-Charles de Gaulle logistics hubs.
Sensitivity analysis tested forecast robustness across organic cotton price volatility scenarios and elastane recycling technology breakthrough assumptions. Segmentation dimensions modeled include product type, material certification tier, end-user cohort, and distribution channel complexity. CAGRs derived from historical trajectory analysis and forward-looking capacity expansion announcements. Industry-specific inputs incorporated REACH SVHC candidate list updates and EU Green Deal circularity mandate implementation timelines.
Forecasts assume regulatory continuity in REACH and EU Green Deal regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Chest Bags Market
Apparel & Footwear
Maternity Activewear Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Apparel Dry Wash Spray Market
Apparel & Footwear
Europe Jeans Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Women's Trousers Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Lingerie Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Compression and Shapewear Market
Apparel & Footwear
Women's Socks Market
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Electric Heated Shoes Market