
 Innerwear Market | 2026-2036
Innerwear Market Size, Share, and Industry Trends Forecast 2026-2036
Innerwear Market Outlook
Direct-to-consumer platforms is narrowing the path between manufacturers and end buyers, compressing traditional wholesale margins. Hanesbrands Inc. leverages its vertical manufacturing base to sustain cost discipline across cotton basics. Jockey International Inc. anchors its position through heritage branding in men's foundational garments. Victoria's Secret & Co. competes by repositioning its product mix toward inclusive sizing and comfort-forward silhouettes.
Innerwear encompasses body-contact garments engineered with specific fiber compositions—typically cotton blends at 150-200 gsm for breathability, nylon-spandex mixes at 15-20% elastane for shape retention, and moisture-wicking synthetic weaves for performance applications—designed to provide structural support, thermal regulation, and aesthetic contouring beneath outer clothing. Bras and shapewear command the deepest margin pools as technical construction and fit complexity justify premium pricing, while sleepwear extends into lifestyle positioning that transcends functional utility. Cotton dominates material volume due to skin-sensitivity preferences and biodegradability pressures, though spandex integration is accelerating as stretch requirements permeate all product categories.
FDA textile contact standards and EPA chemical discharge regulations govern US manufacturing inputs, while REACH and the EU Green Deal's microplastic restrictions are reshaping synthetic fiber viability across European supply chains. China's GB standards and SAMR labeling requirements create additional compliance layers for brands sourcing from or selling into that market. Stakeholders must monitor how diverging chemical safety regimes between major economies fragment material sourcing strategies and force regional product line differentiation.
Market Dynamics
Athleisure-inspired design is compressing the traditional boundary between performance and everyday innerwear, forcing manufacturers to engineer dual-purpose garments that satisfy both functional and aesthetic demands simultaneously.
Growth Catalysts
- REACH compliance tightening:European chemical safety standards are accelerating R&D investment in bio-based elastane alternatives and natural fiber blends that meet skin-contact thresholds.
- China domestic brand scaling:Localized design capabilities and captive manufacturing clusters are capturing premium positioning previously held by multinational labels.
- Spandex integration acceleration:Stretch requirements across bras, shapewear, and sleepwear categories are expanding addressable applications for nylon-spandex hybrid constructions.
Market Restraints
- Cotton price volatility:Weather-driven supply fluctuations and competing textile demand are compressing margin stability for cotton-dominant product lines.
- Synthetic fiber regulatory friction:EU Green Deal microplastic restrictions are threatening viability of established polyester-spandex supply chains in European markets.
- Technical limitation in seamless construction:Complex bra architecture with underwire integration remains resistant to fully automated production scaling.
Strategic Opportunities
- India underpenetration:Organized retail expansion and rising disposable income in tier-2 cities are opening distribution white space for branded foundational garments.
- Direct-to-consumer channel innovation:Size-algorithm apps and virtual fitting tools are collapsing return rates and enabling made-to-order production models.
- US IRA clean manufacturing incentives:Domestic reshoring credits are creating cost-competitive conditions for US-based textile finishing and cut-and-sew operations.
Industry Challenges
- Technical pattern-making talent scarcity:Specialized skills in 3D-to-2D flattening for complex shapewear construction are concentrating in aging workforce pools.
- Multi-jurisdiction certification complexity:Diverging FDA textile contact standards, REACH substance restrictions, and China GB labeling requirements are fragmenting product line architectures.
- Legacy ERP integration friction:Real-time inventory synchronization between DTC platforms and contract manufacturers is requiring expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Innerwear Market |
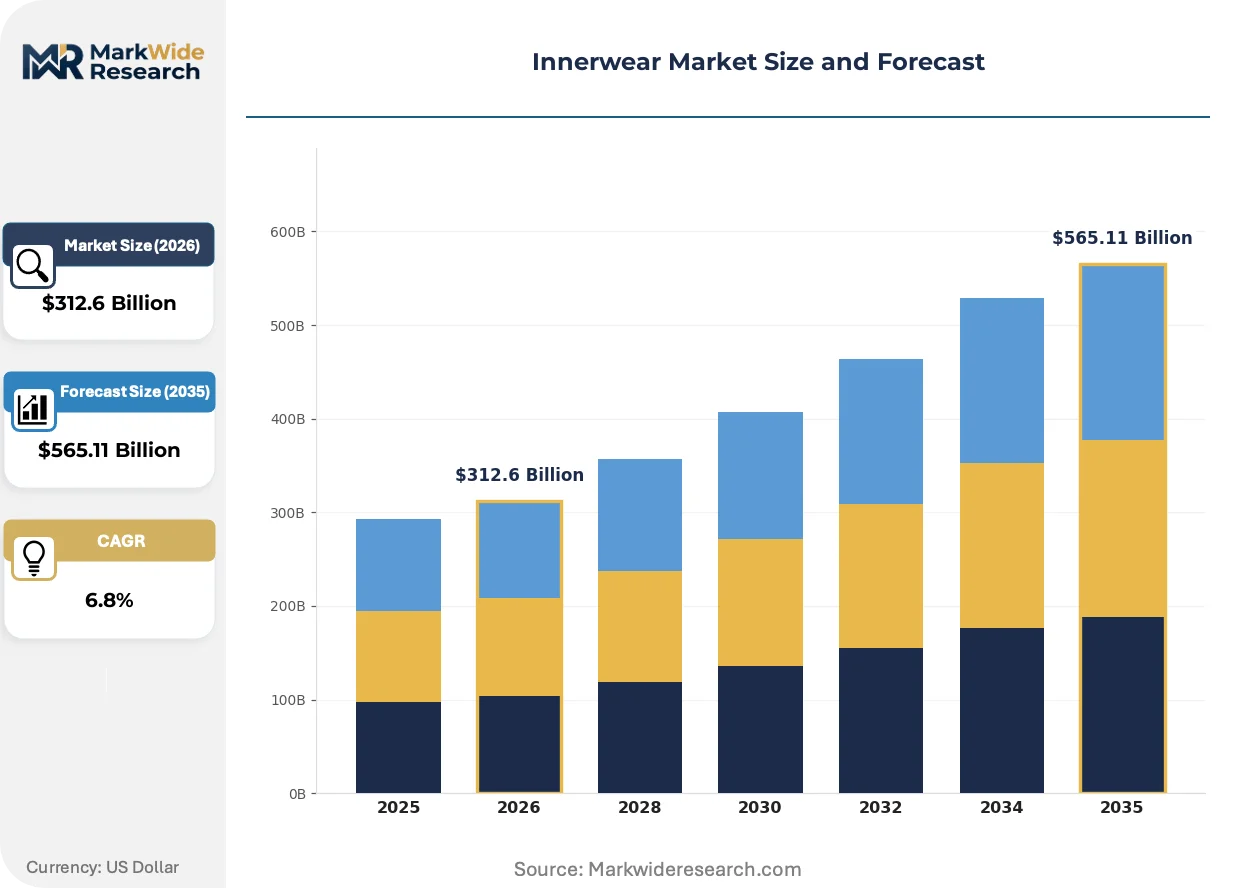
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bras, Panties, Shapewear, Sleepwear Material: Cotton, Nylon, Spandex, Lace Customer Type: Men, Women, Children, Unisex Distribution Channel: Online Retail, Department Stores, Specialty Stores, Discount Stores |
| Companies Covered | Hanesbrands Inc., PVH Corp., Jockey International Inc., Victoria's Secret & Co., Berkshire Hathaway Inc., Ralph Lauren Corporation, American Eagle Outfitters, Inc., Fast Retailing Co., Ltd., H & M Hennes & Mauritz AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Innerwear Market Strategic Shifts
Digital sizing infrastructure and biomaterial science are converging to transform how innerwear is designed, fitted, and manufactured, collapsing traditional batch-production economics.
Seamless knitting technology is collapsing the distinction between cut-and-sew assembly and finished garment production. Premium athleisure brands are adopting whole-garment machines that eliminate side seams and reduce material waste by 30 percent. This compression is enabling micro-factory deployment closer to end markets, shortening replenishment cycles from months to weeks.
REACH substance restrictions and the EU Green Deal's microplastic framework are forcing synthetic fiber substitution strategies. Manufacturers are pivoting toward TENCEL Modal and bio-based polyamide from castor oil feedstocks. European supply chains are most exposed, with German and French distributors now requiring comprehensive chemical disclosure documentation for all elastane-containing imports.
Size-inclusive algorithmic fitting is displacing traditional size-grade assumptions. DTC platforms are deploying body-scan data and machine-learning recommendations to reduce fit-related returns. This behavioral shift is most visible in the US market, where Victoria's Secret and newer entrants are competing on personalization rather than brand heritage alone.
Innerwear Market Segmentation
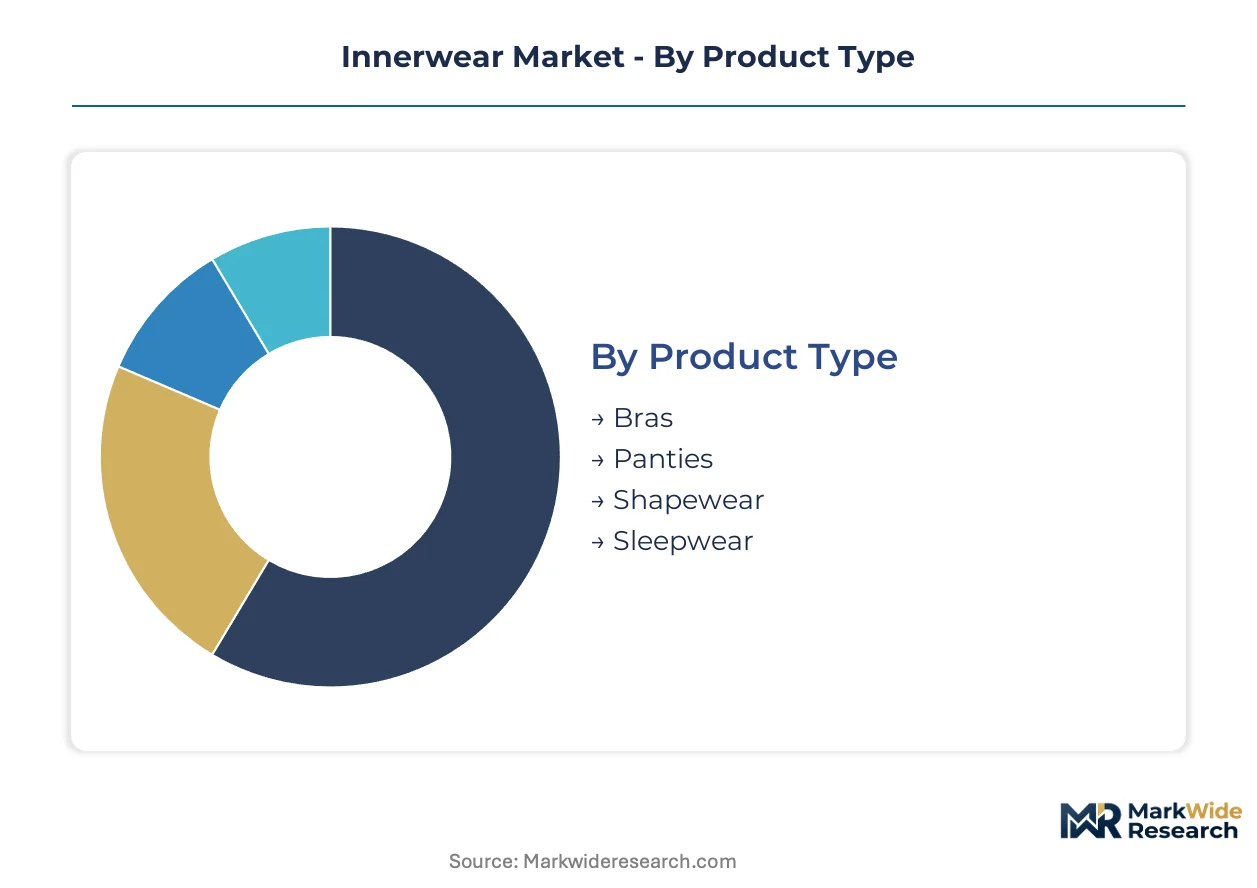
Innerwear segmentation reveals divergent margin architectures and inventory velocity patterns across product categories. Material composition and distribution channel choices determine working capital intensity and price realization potential.
Product Type:
Replacement cycles vary dramatically across categories—daily-use garments turn inventory fastest while occasion-driven segments tie up capital longest.
- Bras:Technical construction with underwire architecture and multi-component assembly commands premium price points. Demand concentrates in developed markets where fit complexity justifies specialized retail service and algorithmic sizing tools reduce return friction.
- Shapewear:Compression engineering using nylon-spandex blends at 20-30% elastane content delivers structural contouring functionality. Expansion concentrates in markets where athleisure aesthetics merge with formal wardrobe requirements, particularly among professional demographics seeking seamless layering solutions.
- Panties:High-volume replenishment category with cotton-dominant composition driving material cost sensitivity.
- Sleepwear:Lifestyle-positioned segment extending beyond functional utility into aesthetic and gifting occasions.
Panties dominate installed base volume. Shapewear is where expansion concentrates.
Material:
Cost tier stratification separates premium natural fibers from mass-market synthetics, with hybrid constructions occupying the fastest-growing middle ground.
- Cotton:Natural fiber dominance in skin-contact applications driven by biodegradability pressures and dermatological sensitivity preferences. Volume concentrates in basic panty and children's segments where breathability specifications outweigh stretch requirements.
- Spandex:Elastane integration at 15-20% blend ratios enables shape retention across bras, shapewear, and performance-oriented sleepwear. Demand is climbing fastest in markets where seamless construction and motion-flexibility specifications permeate all product categories.
- Nylon:Synthetic base for durability and moisture management in active-lifestyle applications.
- Lace:Decorative fiber construction commanding aesthetic premium in occasion and intimate apparel segments.
Cotton dominates raw material volume. Spandex is gaining share fastest.
Customer Type:
Gender-based demand patterns create distinct design and distribution requirements, with women's segments exhibiting higher SKU complexity and margin depth.
- Women:Multi-category purchasing across bras, shapewear, and sleepwear with fit-driven loyalty and subscription-model potential. Expansion concentrates in markets where athleisure-inspired designs merge with everyday comfort needs and inclusive sizing broadens addressable demographics.
- Men:Foundation-focused purchasing concentrated in cotton basics with lower SKU rotation and higher brand stickiness. Demand anchors in heritage-positioned labels with vertical manufacturing discipline.
- Children:Growth-driven replacement cycles with safety-certification sensitivity and parent-mediated purchase decisions.
- Unisex:Emerging positioning in sleepwear and basic layering categories blurring traditional gender segmentation.
Women's segments dominate revenue concentration. Unisex is where positioning innovation concentrates.
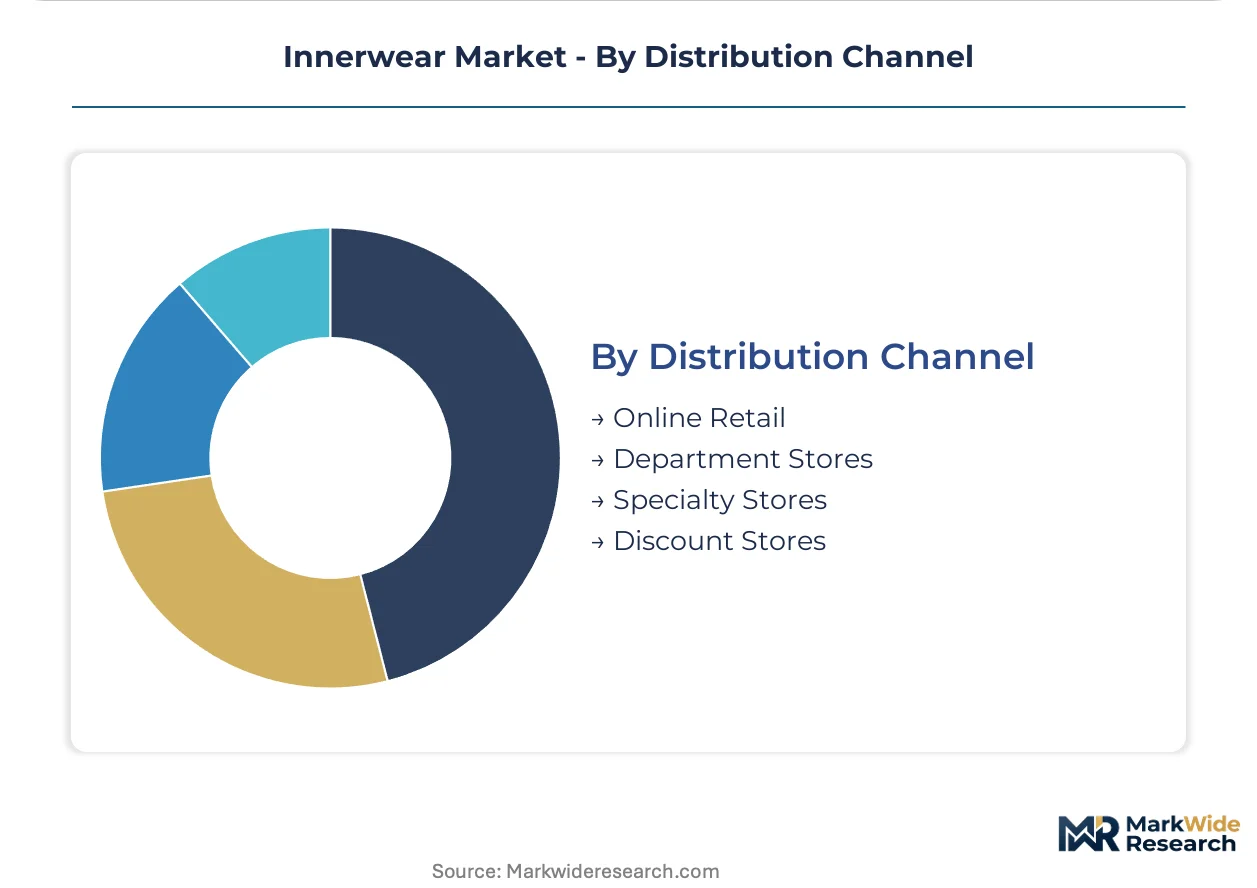
Distribution Channel:
Channel economics fragment between high-touch service requirements for fit-complex categories and velocity-driven mass distribution for replenishment goods.
- Online Retail:Algorithmic fitting tools and virtual try-on technology are collapsing return rates for bras and shapewear. Expansion concentrates in markets with mature logistics infrastructure and size-standardization reducing fit uncertainty.
- Specialty Stores:Professional fitting services and curated brand environments sustain margin premiums for technical categories. Volume anchors in urban centers with concentrated professional demographics seeking personalized consultation.
- Department Stores:Mid-tier brand aggregation serving replenishment purchasing with moderate service levels.
- Discount Stores:Price-driven volume for cotton basics and children's categories with minimal service overlay.
Discount stores dominate unit volume. Online retail is where channel investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRA clean manufacturing incentives are reshaping US-based textile finishing economics while REACH compliance and EU Green Deal microplastic restrictions fragment synthetic fiber sourcing across European supply chains.
United States
Domestic reshoring credits under the IRA are creating cost-competitive conditions for cut-and-sew operations and textile finishing. FDA textile contact standards govern skin-safety thresholds for cotton and spandex blends. North Carolina's Triad region anchors legacy hosiery and intimate apparel manufacturing clusters where automated knitting investments are accelerating.
China
Domestic brands are scaling manufacturing through captive supply chains in Guangdong and Zhejiang provinces. SAMR labeling requirements and GB standards create compliance layers for both local and imported products. The Yangtze River Delta concentration around Shanghai and Suzhou is capturing premium positioning through localized design capabilities and rapid sample-to-production cycles.
Germany
REACH substance restrictions and ECHA disclosure mandates are accelerating R&D investment in bio-based elastane alternatives. The EU Green Deal's microplastic framework threatens established polyester-spandex supply chain viability. Bavaria's technical textile corridor around Munich and Nuremberg hosts specialized seamless knitting machinery suppliers and sustainable fiber innovators.
India
Organized retail expansion in tier-2 cities is opening distribution white space for branded foundational garments. BIS certification requirements and DGFT import policies shape material sourcing economics. Tamil Nadu's Tiruppur cluster dominates cotton knitwear exports while Maharashtra's Mumbai-Pune corridor concentrates lingerie and shapewear design studios.
Japan
Precision manufacturing heritage supports high-value seamless construction and technical shapewear categories. METI sustainability guidelines and JIS standards govern fiber content labeling and chemical safety. The Kansai region around Osaka anchors specialized elastic fiber weaving and premium intimate apparel retail networks.
Innerwear Market Competitive Environment
On the supply side, the industry is moderately consolidated with distinct tiering between mass-market volume players and premium specialists. Heritage brands with vertical manufacturing discipline occupy defensive positions in cotton basics, while direct-to-native platforms disrupt traditional wholesale economics. Three archetypes dominate: scale-driven cost leaders, heritage-positioned specialists, and algorithmic-fitting DTC entrants. Competitive intensity centers on portfolio diversification into adjacent athleisure categories and backward integration into fiber production.
Among US-based incumbents, Hanesbrands Inc., PVH Corp., and Victoria's Secret & Co. represent contrasting strategic postures. Hanesbrands Inc. anchors the cost-discipline archetype through captive manufacturing infrastructure. PVH Corp. occupies a portfolio-conglomerate position spanning multiple price tiers and brand architectures. Victoria's Secret & Co. exemplifies the repositioning challenge facing heritage labels adapting to inclusive sizing and comfort-forward demand shifts.
| Leading Market Players |
|---|
| Hanesbrands Inc. |
| PVH Corp. |
| Jockey International Inc. |
| Victoria's Secret & Co. |
| Berkshire Hathaway Inc. |
| Ralph Lauren Corporation |
| American Eagle Outfitters, Inc. |
| Fast Retailing Co., Ltd. |
| H & M Hennes & Mauritz AB |
| Others |
Value Chain & Pricing Dynamics
Captive cotton spinning clusters in India and Pakistan concentrate raw material leverage for cotton-dominant panty and basic segments, pushing margin pools toward brands with backward integration into fiber production or long-term offtake contracts with ginning cooperatives. Spandex-blend categories command pricing premiums that reflect elastane supply concentration and technical blending capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates algorithmic-fitting DTC brands from heritage-positioned specialists and mass-market volume players. Price differentiation rests on certification grade for skin-contact safety and vertical integration depth in manufacturing. Cost compression in economy cotton basics is intensifying because of weather-driven supply fluctuations and competing textile demand from home furnishings. Discount store buyers exhibit highest price sensitivity, while specialty store customers prioritize fit consultation and brand heritage over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for brands dependent on cut-and-sew finishing in Guangdong province. Manufacturing gravity centers on China for seamless knitting machinery and synthetic fiber production, India for cotton spinning and knitwear assembly, and Vietnam for labor-intensive cut-and-sew operations. Raw material sourcing draws from Texas and India for cotton, Singapore and Germany for spandex polymer, and Belgium for TENCEL Modal. Distribution runs through direct-to-consumer platforms for algorithmic-fitting categories and multi-brand retailers for replenishment basics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment models and virtual fitting services are expanding addressable revenue per customer faster than transactional garment sales, creating service-attach economics that favor platforms with data infrastructure over pure manufacturing scale.
For Market Incumbents: Harden algorithmic fitting capabilities through body-scan database accumulation and machine-learning model refinement to defend against DTC entrants with native digital infrastructure. Deepen backward integration into bio-based elastane R&D to preempt REACH compliance cost escalation in European markets. Anchor manufacturing discipline through captive spinning and knitting capacity in Tamil Nadu or North Carolina to offset cotton price volatility exposure.
For New Entrants and Emerging Players: Mid-market shapewear in India's tier-2 cities represents the most penetrable entry point, where organized retail expansion meets underserved professional demographics seeking seamless layering solutions. Unisex sleepwear positioning blurs traditional gender segmentation and opens distribution through lifestyle retailers outside conventional intimate apparel channels. Deploy size-algorithm apps with virtual try-on technology to collapse return rates and establish data-driven customer relationships before scaling physical retail presence.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive cotton spinning and seamless knitting machinery in low-cost manufacturing clusters. Long-term viability across the analysis window favors assets with demonstrated REACH compliance documentation and bio-based fiber substitution pipelines. Monitor ECHA substance restriction announcements and EU Green Deal microplastic enforcement timelines as inflection indicators for synthetic fiber supply chain viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Captive cotton spinning in India insulates margin stability against commodity price volatility. |
| Direct-to-Consumer Platform Launch | Algorithmic fitting tools collapse return rates and enable made-to-order production economics. |
| Bio-Based Material Substitution | TENCEL Modal and castor oil polyamide preempt REACH restriction cost escalation in Europe. |
| Seamless Knitting Capacity Expansion | Whole-garment machines eliminate side seams and reduce material waste by thirty percent. |
| Size-Inclusive Range Extension | Broadened addressable demographics capture athleisure-inspired demand shifts among professional women. |
Study Parameters
Cross-validation between primary interviews with brand managers, category buyers at multi-brand retailers, supply planners, and technical R&D directors and secondary sources including customs records, SEC 10-K filings, and Nielsen retail audit data anchors the qualitative findings. Bottom-up triangulation from product-level volume assumptions and top-down reconciliation against aggregate market estimates ensures internal consistency. Stakeholder perspectives from seamless knitting machinery suppliers and sustainable fiber innovators in Bavaria's technical textile corridor inform supply-side dynamics.
Calibration against historical replacement cycle patterns and channel shift trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, customer gender, and distribution channel, with regional regulatory clusters capturing REACH, FDA textile contact standards, and China GB requirements. CAGRs derive from fitted trend extrapolation adjusted for identified catalyst and restraint intensities, with cotton price volatility and synthetic fiber regulatory friction as industry-specific forecast inputs.
Practitioners should monitor ECHA substance restriction announcements, EU Green Deal microplastic enforcement timelines, and India organized retail expansion rates for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Insulated Jacket Market
Apparel & Footwear
Plus Size Women's Clothing Market
Apparel & Footwear
Women's Sports and Swimwear Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Southeast Asia Lingerie Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Asia-Pacific Jeans Market
Apparel & Footwear
Maternity Activewear Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
Football Kits Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Alpaca Apparel and Accessories Market