
 Intimate Wear Market | 2026-2036
Intimate Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Intimate Wear Market Outlook
The end-use mix in intimate wear is shifting as teen and young adult segments command greater shelf space and marketing investment. Victoria's Secret leverages its heritage brand equity to navigate this demographic pivot through revised sizing and messaging. Zivame anchors its position in India's digital-first lingerie economy with virtual-fit technology and localized collections. Triumph International sustains manufacturing scale across European and Asian production bases.
Intimate wear encompasses undergarments and loungewear engineered with specific fiber blends, elastic recovery standards, and seam-free construction for daily comfort and aesthetic function. Cotton and modal compositions dominate skin-contact layers due to moisture-wicking and breathability parameters, while lace and nylon variants serve occasion-wear segments with higher margin structures. Bras and panties constitute the volume core, though bodysuits are capturing faster growth as outerwear-adjacent styling blurs category boundaries. Women remain the primary customer type, yet men's intimate wear represents an underdeveloped margin pool with rising brand entry.
REACH in Europe and the EU Green Deal constrain synthetic dye and elastane chemistries, forcing reformulation costs onto suppliers. The US FDA and EPA regulate textile contact substances and wastewater discharge from dye houses, respectively, shaping where brands locate cut-and-sew operations. Stakeholders must monitor how chemical disclosure mandates in multiple jurisdictions cascade through tier-two material suppliers.
Market Dynamics
REACH and EU Green Deal chemical standards are forcing intimate wear suppliers to reformulate synthetic dyes and elastane compositions, accelerating production relocation toward Brazil, India, and Vietnam.
Growth Catalysts
- Teen and Young Adult Demand:Social media platforms normalize body-positive messaging, expanding addressable market for inclusive sizing and adaptive designs across digital-native demographics.
- REACH Compliance Innovation:European chemical disclosure mandates drive investment in bio-based elastane alternatives and waterless dyeing processes among tier-two material suppliers.
- Virtual-Fit Technology:Computer vision and 3D body scanning reduce return rates for online lingerie purchases, unlocking margin recovery for direct-to-consumer channels.
Market Restraints
- Cotton Price Volatility:Weather-driven supply disruptions in major cotton-producing regions compress margin predictability for skin-contact layer manufacturers.
- China Concentration Risk:Lingering dependency on Chinese synthetic fiber and lace production creates exposure to tariff escalations and logistics bottlenecks.
- Technical Limitation in Seam-Free Construction:Bonding adhesive durability thresholds constrain wash-cycle longevity for premium bodysuit segments.
Strategic Opportunities
- Men's Intimate Wear White Space:Underdeveloped category penetration in North America and Western Europe invites brand entry with performance-oriented positioning.
- EU Green Deal Tailwind:Circular textile mandates and extended producer responsibility schemes favor suppliers with closed-loop recycling capabilities.
- AI-Enabled Personalization:Machine learning algorithms predicting size and style preferences are converging with subscription replenishment models to capture lifetime value.
Industry Challenges
- Technical Talent Scarcity:Shortage of textile chemists specializing in bio-elastane formulation delays reformulation timelines for REACH-compliant product lines.
- Multi-Jurisdiction Certification Burden:Simultaneous FDA textile contact substance reviews and ECHA substance registration create compliance timeline conflicts for global launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intimate Wear Market |
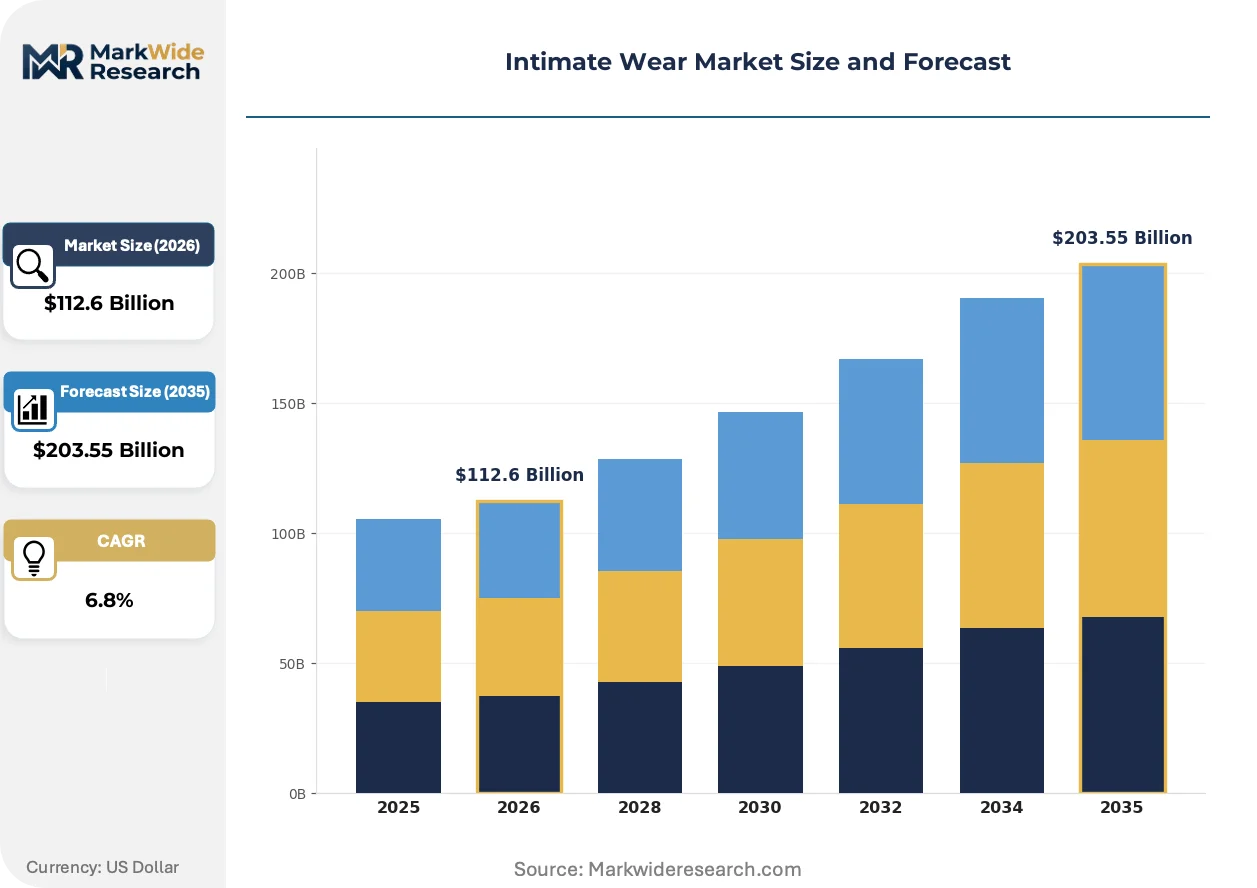
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bras, Panties, Loungewear, Bodysuits Material: Cotton, Lace, Nylon, Modal Customer Type: Women, Men, Couples, Teens Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Triumph International, Gap, Inc., Victoria's Secret, Jockey International, Zivame, PVH Corp, Wacoal Holdings Corp, Chantelle, Hanesbrands Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intimate Wear Market Strategic Shifts
Digital fit technologies and sustainable material science are compressing traditional design-to-shelf cycles while fragmenting distribution toward direct channels and specialized marketplaces.
Seamless knitting technology is unifying structural support and aesthetic layering in single-pass manufacturing. Teen and young adult segments adopt these garments at accelerated pace for outerwear-adjacent styling. This convergence is compressing distinction between lingerie and ready-to-wear categories, forcing retailers to reconfigure floor space allocation.
REACH substance restrictions and EU Green Deal circularity mandates are eliminating legacy azo dyes and phthalate-based softeners from European supply chains. Reformulation costs cascade to Asian cut-and-sew contractors dependent on EU export volumes. Premium lace and occasion-wear segments absorb disproportionate compliance investment as they rely most heavily on restricted chemistries.
Size-inclusive assortment expansion is displacing legacy narrow-band sizing in digital merchandising. Direct-to-consumer brands capture demand from department store lingerie departments through extended size matrices and fit guarantee policies. This rotation is most visible in North American and Western European markets where body-positive social discourse has achieved mainstream commercial penetration.
Intimate Wear Market Segmentation
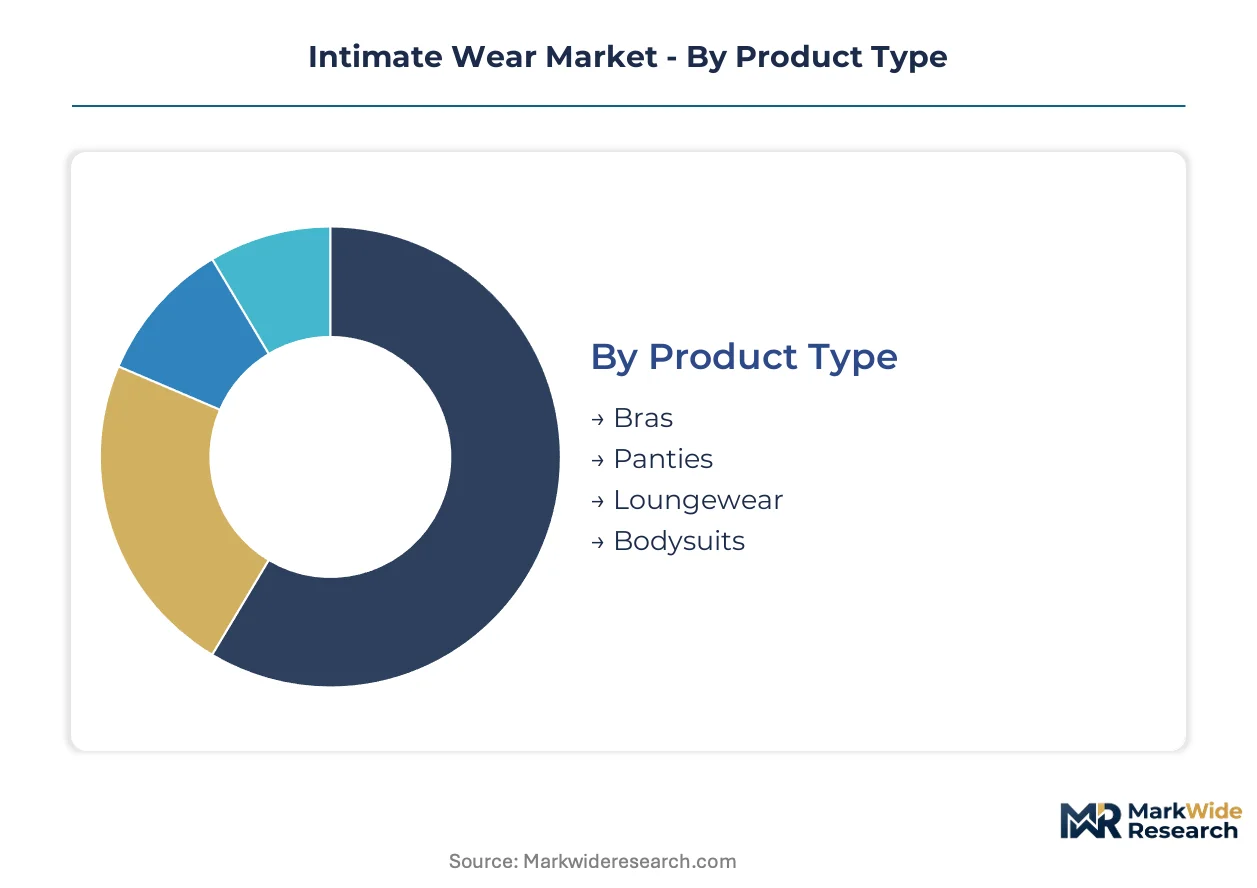
Intimate wear segmentation reveals how product architecture, material science, and channel economics fragment addressable demand. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning across supplier tiers.
Product Type:
Structural support garments operate as standalone wardrobe staples, while bodysuits embed intimate wear into outerwear-adjacent styling systems.
- Bras:Engineered with underwire, wireless, and seamless architectures across 28+ band-cup combinations. Demand concentrates in North America and Western Europe where extended sizing matrices capture body-positive purchasing shifts.
- Panties:Brief, thong, boyshort, and high-waist silhouettes dominate volume throughput. Brazil and Vietnam absorb disproportionate cut-and-sew capacity as brands diversify beyond Chinese synthetic lace suppliers.
- Loungewear:Sleep separates and coordinated sets bridge home and limited public wear contexts.
- Bodysuits:Single-piece construction with snap closures enables tuck-and-layer styling under tailored separates.
Bras lead volumes today; bodysuits are gaining share fastest.
Material:
Cost tier stratification separates premium natural fibers from commodity synthetics, with reformulation costs cascading through REACH-affected supply chains.
- Cotton:GOTS-certified organic and BCI-sourced varieties command skin-contact layer preference for moisture-wicking and breathability. Indian spinning mills and Turkish textile clusters supply major brand replenishment programs.
- Modal:Lenzing TENCEL and proprietary beechwood pulp derivatives offer silk-adjacent drape with lower water intensity. Austrian and Czech fiber production anchors European sustainable positioning.
- Lace:Nylon-cotton blends and Solstiss Leavers looms serve occasion-wear segments with restricted-chemistry compliance burdens.
- Nylon:6,6 and 6 polymer variants provide elastic recovery for performance-oriented construction.
Cotton leads volumes today; modal is expanding most quickly.
Customer Type:
Application concentration varies sharply, with women anchoring replenishment velocity while men represent underdeveloped margin pools.
- Women:Core demographic spanning 18-65 age bands with lifecycle-driven purchase frequency variation. Maternity, post-surgical, and menopause-adjacent subsegments drive specialized fit engineering.
- Men:Boxer brief, trunk, and performance base layer categories show rising brand entry from athletic wear crossovers. North American and Western European markets show steepest penetration acceleration.
- Teens:First-bra and training categories normalize through digital-native discovery on TikTok and Instagram.
- Couples:Coordinated gifting sets and subscription boxes concentrate around Valentine's and holiday purchasing windows.
Women lead volumes today; men are climbing the fastest.
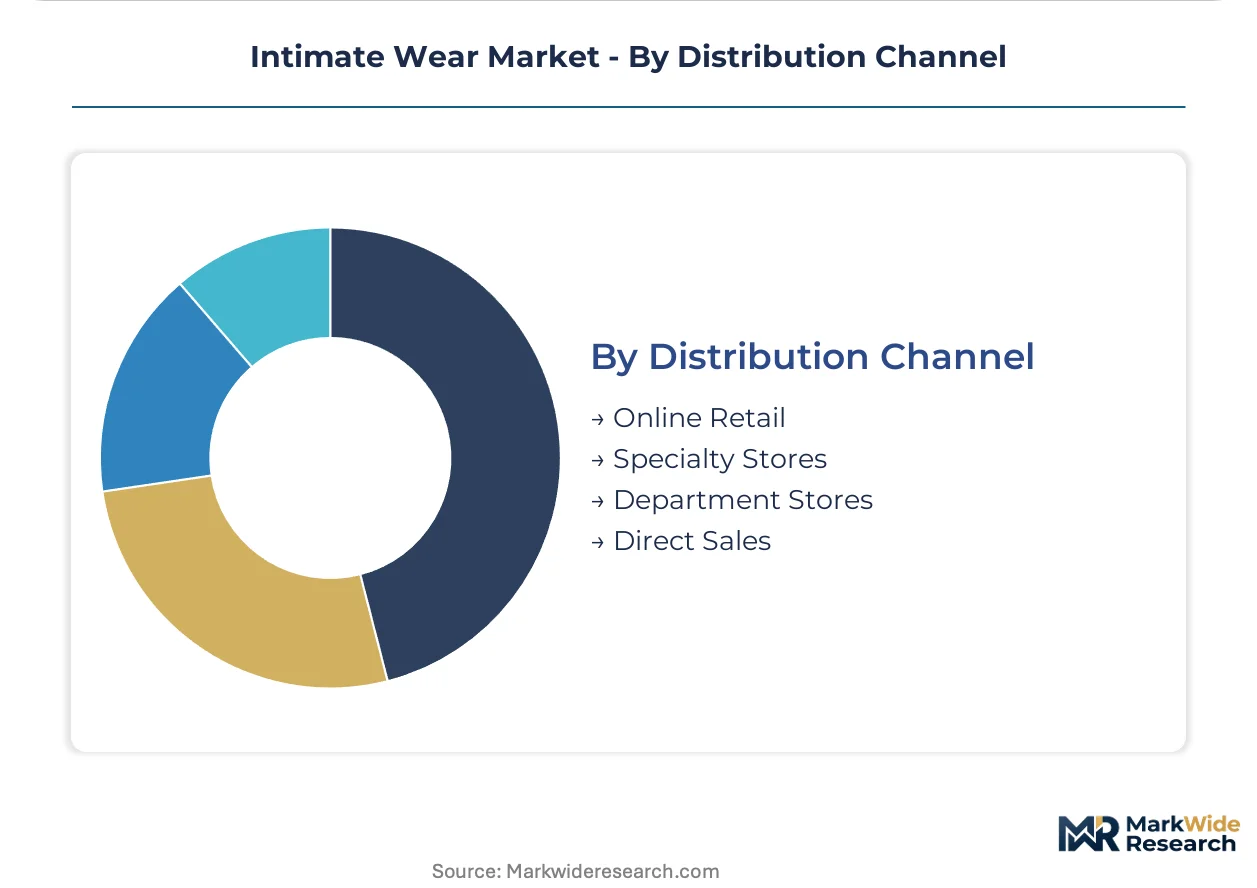
Distribution Channel:
Channel maturity separates legacy physical retail from digitally native fulfillment models with divergent return rate economics.
- Online Retail:Direct-to-consumer brands and marketplace aggregators deploy virtual-fit algorithms to compress return rates. Zivame and ThirdLove anchor proprietary sizing databases.
- Specialty Stores:Victoria's Secret and independent lingerie boutiques sustain high-touch fitting services with trained bra-fit specialists.
- Department Stores:Nordstrom and Galeries Lafayette maintain dedicated lingerie floors with brand shop-in-shop configurations.
- Direct Sales:Avon and independent consultant networks persist in Latin American and Southeast Asian markets.
Online retail leads volumes today; specialty stores are stabilizing share through experiential differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are accelerating production migration toward jurisdictions with lower cost-of-compliance structures. Brazil, India, and Vietnam absorb disproportionate cut-and-sew capacity as REACH and EU Green Deal mandates cascade reformulation costs through European-bound supply chains.
United States
Teen and young adult segments command expanded shelf space as body-positive social discourse achieves mainstream commercial penetration. The FDA regulates textile contact substances under 21 CFR regulations, while EPA wastewater discharge standards from dye houses influence domestic versus offshore production decisions. New York and Los Angeles anchor design and wholesale distribution clusters with showrooms serving North American retail networks.
Germany
REACH substance restrictions and ECHA registration requirements eliminate legacy azo dyes from European-bound intimate wear production. The EU Green Deal circularity mandates favor suppliers with closed-loop recycling capabilities. North Rhine-Westphalia and Bavaria host specialized textile machinery manufacturers supplying seamless knitting equipment to global lingerie producers.
India
Digital-native discovery on TikTok and Instagram normalizes first-bra and training categories among teen demographics. BIS textile standards govern domestic quality compliance while DGFT export promotion schemes support cotton and modal fiber shipments. Tiruppur and Surat concentrate cut-and-sew operations with GOTS-certified organic cotton spinning mills in Karnataka supplying major brand replenishment programs.
Brazil
Synthetic lace and occasion-wear segments absorb disproportionate compliance investment as they rely most heavily on restricted chemistries. ANVISA regulates cosmetic-grade textile finishes while federal tax incentives under the Manaus Free Trade Zone attract fiber processing investments. São Paulo and Santa Catarina states concentrate lingerie manufacturing with established supply relationships to Latin American and North American markets.
Vietnam
China concentration risk drives brand diversification toward Vietnamese synthetic fiber and lace production. The Ministry of Industry and Trade implements technical standards for textile imports while free trade agreements with EU and US markets provide tariff advantages. Ho Chi Minh City and Hanoi anchor export-oriented manufacturing zones with Japanese and South Korean joint venture partners operating seamless knitting facilities.
Intimate Wear Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers establish redundant production footprints across Brazil, India, and Vietnam. The vendor base organizes into three tiers: heritage European houses with design authority, North American mass-market operators with replenishment scale, and Asia-Pacific digital-native entrants with virtual-fit technology. Strategic archetypes include vertical specialists controlling fiber-to-garment supply chains and platform aggregators capturing lifetime value through subscription replenishment. M&A activity and geographic diversification constitute the dominant competitive moves as brands defend margin position against regulatory compliance costs.
Among heritage European specialists, Triumph International and Chantelle exemplify design-led positioning with manufacturing scale across European and Asian production bases. Victoria's Secret occupies a position within the North American mass-market tier, leveraging revised sizing and messaging to navigate demographic pivots toward teen and young adult segments. Zivame anchors the Asia-Pacific digital-native archetype with virtual-fit technology deployment and localized collections serving India's digital-first lingerie economy.
| Leading Market Players |
|---|
| Triumph International |
| Gap, Inc. |
| Victoria's Secret |
| Jockey International |
| Zivame |
| PVH Corp |
| Wacoal Holdings Corp |
| Chantelle |
| Hanesbrands Inc |
| Others |
Value Chain & Pricing Dynamics
Direct-to-consumer brands with replenishment subscription models anchor pricing power in the intimate wear market, compressing legacy department store markups through virtual-fit guarantees and extended size matrices. This buyer concentration forces tier-two suppliers to absorb REACH reformulation costs while maintaining contract pricing for European-bound volumes.
Pricing Analysis
Retailer markup layers dominate the intimate wear value chain, with specialty boutique margins running higher than mass-market department store placements. Three-tier pricing structure across premium lace, standard cotton-modal blends, and economy synthetic basics separates occasion-wear investment pieces from daily replenishment items. Pricing pressure stems from cotton price volatility and elastane reformulation costs cascading through REACH-affected supply chains. Value-conscious teens and young adults exhibit highest price sensitivity, while maternity and post-surgical segments accept premium positioning for specialized fit engineering.
Supply Chain Analysis
Skilled seamstress availability in Vietnamese export zones and Brazilian synthetic fiber clusters determines cut-and-sew capacity expansion timelines. Supply concentrates in Vietnam, India, and Brazil as brands diversify beyond Chinese lace and elastane dependencies. Raw material flows draw from Lenzing's Austrian modal facilities, Indian GOTS-certified cotton spinning mills, and South Korean nylon polymer plants. Single-source vulnerability persists in Solstiss Leavers lace looms concentrated in European heritage manufacturers. Distribution runs through direct-to-consumer platforms, specialty retail fitting services, and department store shop-in-shop configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intimate wear market reads as a late-cycle quality story as teen and young adult demand pivots toward premium sustainable materials and size-inclusive engineering that commands full-price sell-through.
For Market Incumbents: Acquire bio-elastane formulation capabilities or captive dye-house assets to deflect REACH compliance cost inflation away from margin structures. Incumbents must consolidate tier-two supplier relationships in Vietnam and India before capacity constraints harden, while investing in seamless knitting equipment to compress design-to-shelf cycles against digital-native entrants. For New Entrants and Emerging Players: Launch via subscription replenishment models targeting the underdeveloped men's intimate wear white space in North America, where athletic wear crossovers have primed demand for performance-oriented base layers. New entrants should prioritize virtual-fit technology deployment to capture lifetime value through reduced return rates, while sourcing GOTS-certified organic cotton from Indian spinning mills to anchor sustainable positioning. For Investors and Strategic Acquirers: Heritage European lingerie houses with design authority and established Asian manufacturing footprints are the most active acquirer targets in this space, as private equity seeks brands with replenishment velocity and demographic pivot flexibility. Long-term viability hinges on circular textile capabilities and extended producer responsibility scheme compliance. The signal to watch is EU Green Deal implementation pace accelerating closed-loop recycling investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual-Fit Technology Deployment | Computer vision algorithms at Zivame and ThirdLove compress return rates for online lingerie purchases. |
| Bio-Elastane Formulation Investment | REACH-compliant alternatives to phthalate-based softeners eliminate regulatory barriers to European market access. |
| Seamless Knitting Capacity Expansion | Japanese and South Korean joint ventures in Vietnam unify structural support and aesthetic layering in single-pass manufacturing. |
| Men's Category Brand Extension | Performance-oriented positioning captures underdeveloped margin pools as athletic wear crossovers normalize male intimate wear purchasing. |
| Closed-Loop Recycling Integration | EU Green Deal circularity mandates favor suppliers with fiber-to-fiber regeneration capabilities for post-consumer garment recovery. |
Study Parameters
Bottom-up teen and young adult demand modeling reconciled against top-down synthetic fiber and cotton supply tracking forms the analytical core of this study. Primary interviews with brand merchandising directors, tier-two textile mill procurement leads, specialty retail bra-fit specialists, and ECHA regulatory compliance officers combined with secondary validation from customs trade records, GOTS certification databases, and SEC apparel sector filings. Triangulation across stakeholder inputs and published trade data ensures segment-level precision.
Historical trendline analysis of intimate wear volume and value trajectories informs the projection framework across the analysis window. Segmentation dimensions include product architecture, material composition, customer lifecycle stage, and distribution channel economics. CAGRs derive from elasticity modeling against demographic purchasing shifts and regulatory implementation schedules. Forecast inputs incorporate virtual-fit technology adoption curves and REACH substance restriction phase-in timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cotton supply disruption scenarios or accelerated EU Green Deal circularity mandates. Material deviation in regulatory enforcement intensity, synthetic fiber price volatility, or teen demographic social media engagement patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Maternity Activewear Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Global Adaptive Clothing Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Men Jeans Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Plus Size Women's Clothing Market
Apparel & Footwear
Bra Market
Apparel & Footwear
School Shoes Market