
 Gaming Computer Market | 2026-2036
Gaming Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Computer Market Analysis
Taiwanese motherboard and graphics card manufacturing is consolidating around a handful of high-volume foundry partners. ASUS leverages vertical integration across design and fabrication to sustain premium positioning in gaming laptops. NVIDIA Corporation dominates discrete GPU supply for enthusiast desktops, while MSI specializes in thermal engineering for compact form-factor builds.
Gaming computers are high-performance computing systems engineered with dedicated GPUs, advanced thermal architectures, and overclock-capable processors to render real-time interactive graphics at frame rates exceeding 60 FPS. Their primary commercial purpose is enabling immersive gameplay, content creation, and competitive esports participation. Desktop systems anchor the highest-margin segment due to component modularity and upgrade cycles, while laptop demand accelerates fastest among professional gamers requiring portable tournament rigs. Ray tracing capabilities now differentiate premium tiers as game engines adopt real-time lighting pipelines.
The US FCC governs electromagnetic emissions for wireless-enabled gaming peripherals, while the EPA ENERGY STAR program shapes power-supply efficiency benchmarks across pre-built systems. China's MIIT enforces GB standards on electronic product recyclability that affect graphics card PCB design and cooling assembly materials. Stakeholders must monitor how evolving efficiency mandates in multiple jurisdictions interact with thermal performance requirements for next-generation GPUs.
Market Dynamics
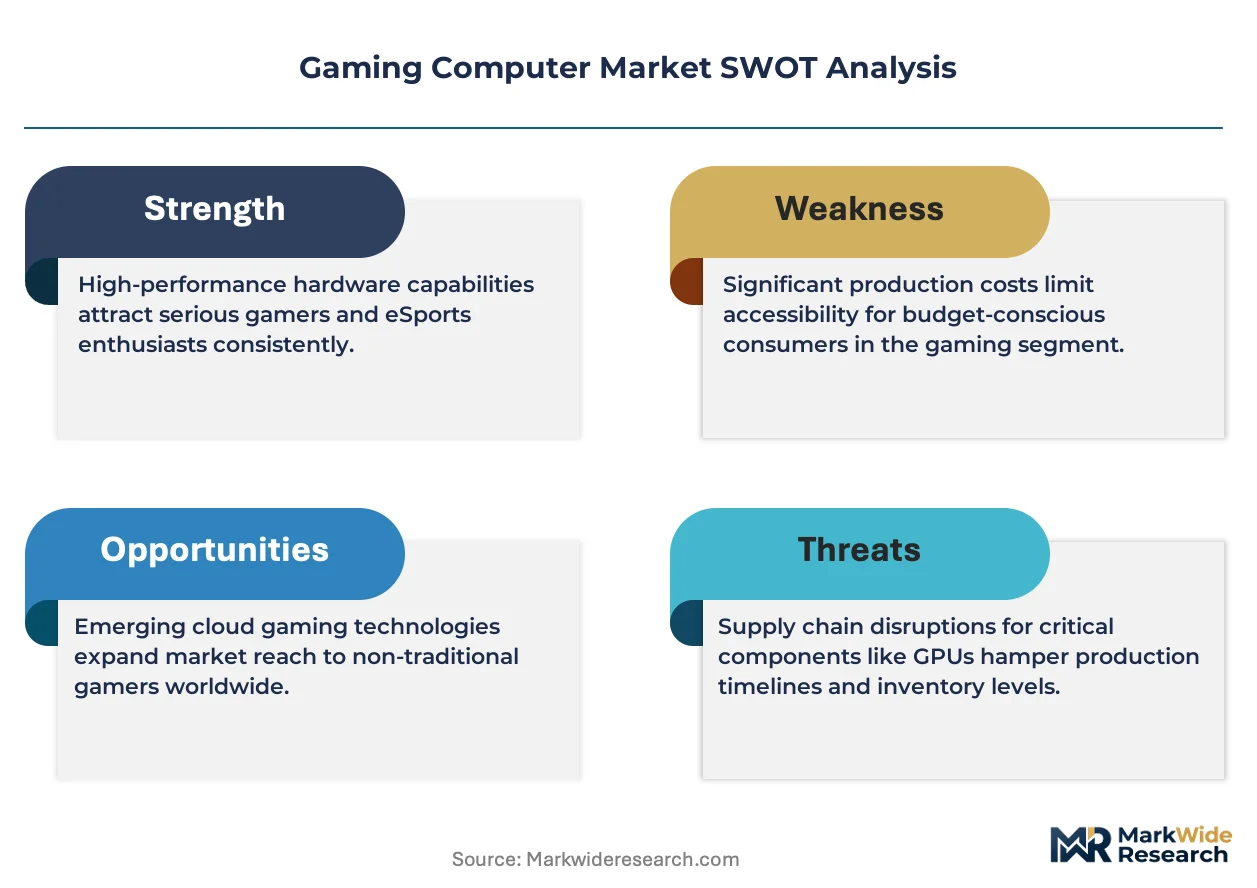
GPU thermal density requirements are forcing wholesale redesigns of chassis airflow and power delivery architectures across the enthusiast desktop segment. Component modularity now competes directly with integrated thermal solutions as the defining axis of vendor differentiation.
Growth Catalysts
- Esports tournament infrastructure:Professional leagues mandate standardized refresh cycles for competition hardware. Tournament organizers procure dedicated GPU workstations under multi-year service agreements.
- EPA ENERGY STAR efficiency tiers:Power-supply certification benchmarks drive pre-built system redesigns toward 80 Plus Titanium compliance in the United States.
- Ray tracing pipeline adoption:Unreal Engine and Unity lighting engines now default to real-time ray tracing. Game developers optimize for RT cores, pulling hardware upgrades from content creators.
Market Restraints
- TSMC foundry concentration:Advanced node GPU wafers concentrate at a single Taiwanese supplier. Geopolitical friction or fab disruption would cascade through discrete graphics card availability.
- GDDR6X memory cost volatility:High-bandwidth memory modules track commodity DRAM pricing. Margin compression hits mid-tier graphics card SKUs when memory spot prices spike.
- China MIIT efficiency mandates:GB standards on electronic product recyclability restrict PCB substrate materials and cooling assembly alloys, complicating thermal design.
Strategic Opportunities
- India BIS certification pathway:Local assembly incentives under PLI scheme attract gaming laptop OEMs to establish captive production for domestic consumption and re-export.
- Cloud gaming edge nodes:Low-latency rendering farms in second-tier cities reduce hardware dependency for casual gamers. Infrastructure providers lease GPU slices on subscription.
- AI training workstation convergence:Consumer RTX cards double as entry-level machine learning accelerators. Research labs and indie developers repurpose gaming hardware for model fine-tuning.
Industry Challenges
- Thermal engineer scarcity:Vapor chamber and liquid metal application expertise concentrates at a handful of ODMs. Brands struggle to replicate MSI's compact form-factor thermal performance.
- FCC pre-certification timelines:Wireless-enabled gaming peripherals face electromagnetic emissions testing bottlenecks. Product launches slip when lab capacity saturates ahead of holiday seasons.
- Legacy socket compatibility fragmentation:Intel and AMD motherboard chipset generations diverge on memory controller support. Upgrade path uncertainty depresses enthusiast build confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Computer Market |
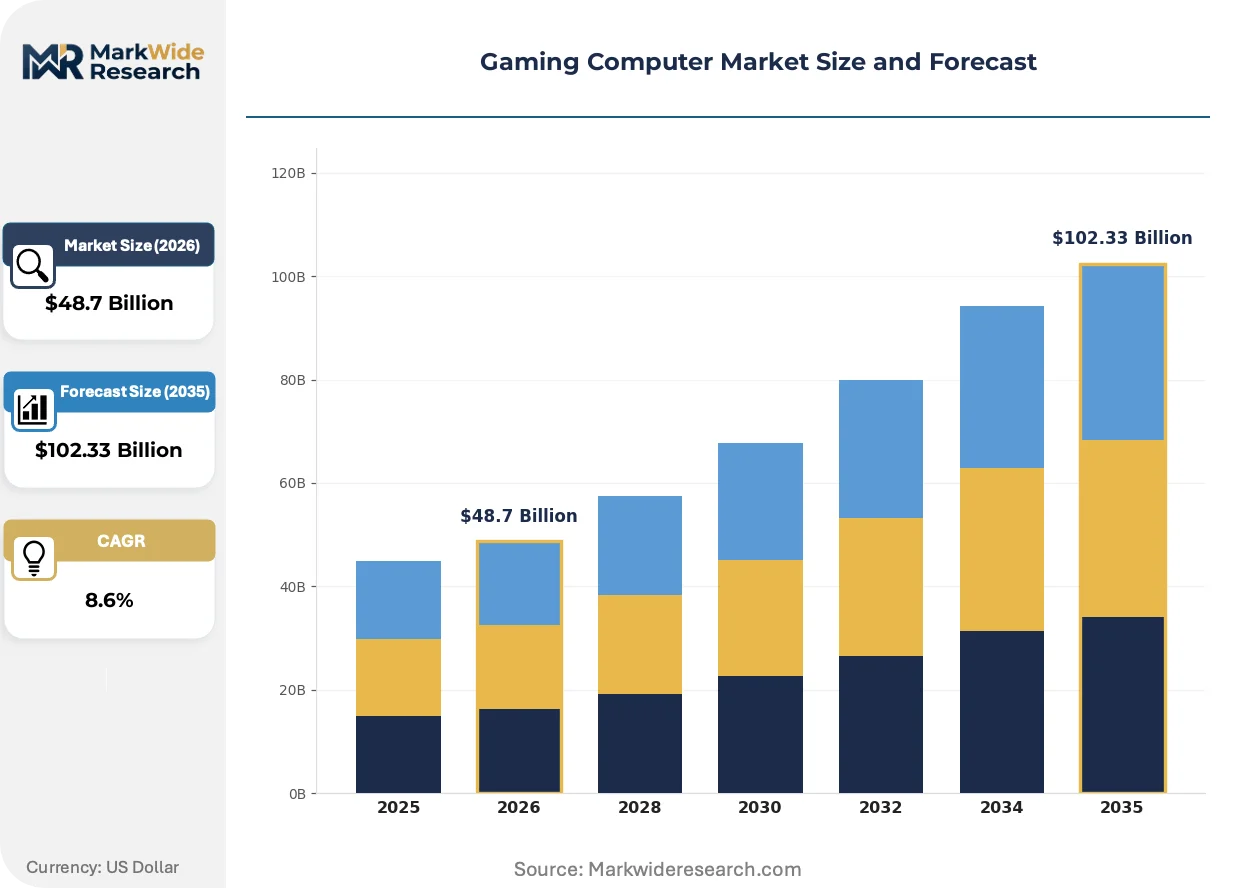
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktops, Laptops, Consoles, Custom Builds Graphics Technology: GPU, Integrated Graphics, Ray Tracing, Dedicated GPUs Distribution Channel: Online Retailers, Physical Stores, Direct Sales, E-commerce Platforms Customer Type: Casual Gamers, Professional Gamers, Streamers, Esports Teams |
| Companies Covered | Dell Technologies, ASUS, HP, Lenovo, Acer, MSI, Alienware, Corsair Gaming, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Computer Market Emerging Trajectories
Real-time rendering pipelines and efficiency mandates are compressing hardware refresh cycles while fragmenting the supplier base. Three distinct vectors are reshaping how gaming computers are engineered, certified, and procured.
Liquid cooling infrastructure is modularizing across the enthusiast desktop segment. Custom loop components—pumps, radiators, quick-disconnect fittings—now ship as standardized subassemblies. System integrators assemble boutique builds without in-house machining. This modularity is compressing time-to-market for high-thermal-density configurations while lowering the skill barrier for premium positioning.
China's MIIT is tightening GB standards on electronic product recyclability ahead of broader dual carbon goals. Graphics card PCB designs must eliminate specific halogenated flame retardants. Cooling assembly materials face revised disassembly requirements. Premium tier vendors with captive supply chains absorb compliance costs more readily than mid-tier assemblers sourcing generic heatsink extrusions.
Streamer infrastructure demands are rotating procurement toward pre-validated, broadcast-ready systems. Twitch and YouTube content creators purchase complete workstation packages rather than component bundles. Specialized retailers bundle capture cards, lighting, and acoustic treatment with core hardware. This shift concentrates most visibly in the United States, where platform monetization infrastructure supports professional content creation as a primary occupation.
Gaming Computer Market Segmentation
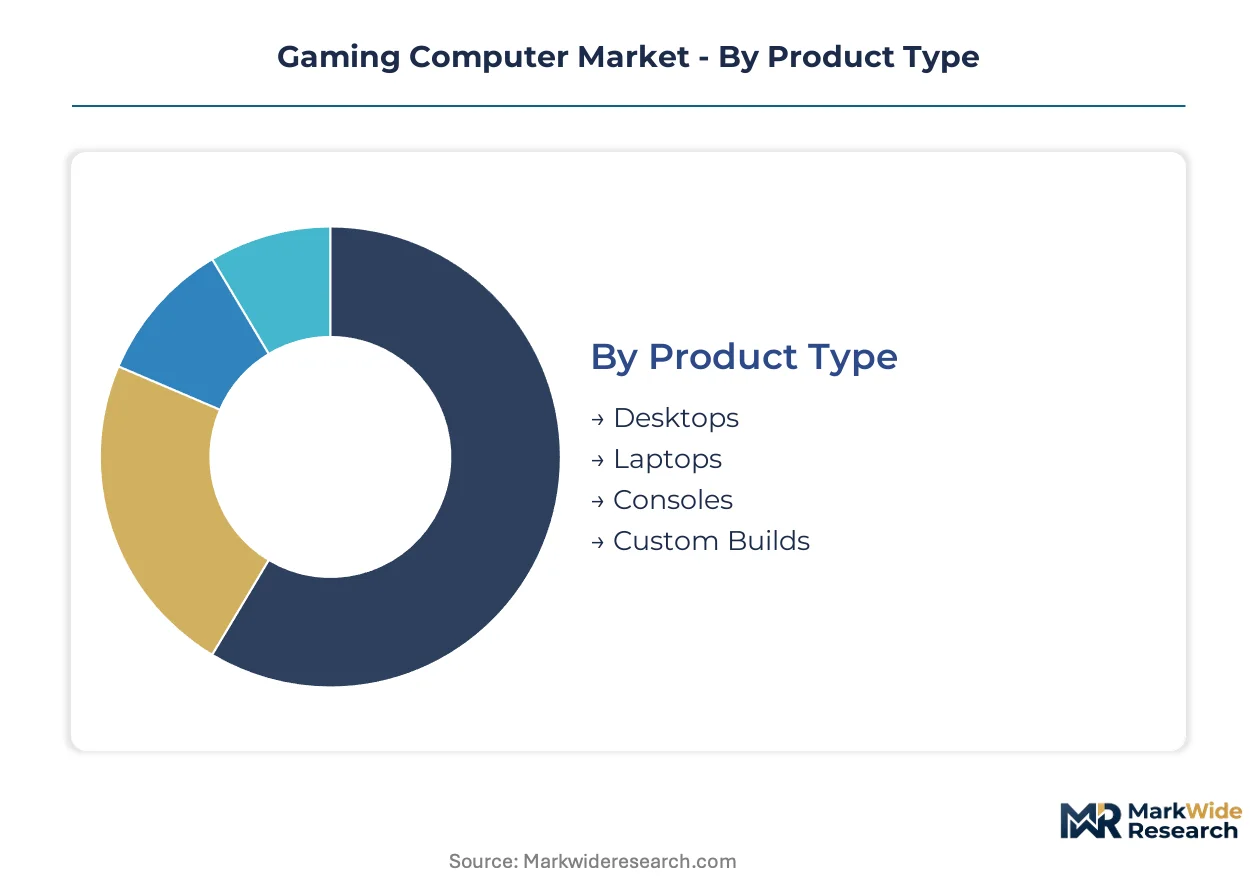
Gaming computer segmentation reveals how hardware specialization fragments across performance tiers and procurement channels. Component modularity versus integrated thermal solutions defines competitive positioning within each category.
Product Type:
Customization intensity varies from fully configurable tower chassis to sealed portable systems with soldered components.
- Desktops:Modular tower configurations accommodate full-length graphics cards and custom liquid cooling loops. Demand concentrates in the United States where streamer infrastructure and esports tournament standards drive high-end refresh cycles. Component upgradeability sustains premium pricing across enthusiast builds.
- Laptops:Compact thermal engineering enables portable tournament rigs with vapor chamber cooling and liquid metal interfaces. Professional gamers in Asia-Pacific markets prioritize these systems for international competition travel. MSI and ASUS dominate thermal performance differentiation in this segment.
- Consoles:Fixed-specification living room systems with standardized hardware configurations. Sony and Microsoft control supply through captive semiconductor allocation.
- Custom Builds:Boutique system integrators assemble component bundles for enthusiast DIY markets. Micro Center and specialty retailers serve this fragmented demand channel.
Most installed capacity flows through Desktops. Expansion is steepest in Laptops.
Graphics Technology:
Rendering pipeline sophistication separates entry-level display output from photorealistic real-time lighting.
- GPU:Discrete graphics processors from NVIDIA and AMD render complex shaders through dedicated compute units. Data centers and research labs repurpose consumer RTX accelerators for entry-level machine learning workloads. Thermal density requirements force chassis redesigns across the enthusiast segment.
- Ray Tracing:Real-time lighting pipelines in Unreal Engine and Unity default to RT core acceleration. Content creators upgrade hardware to match game engine optimization targets. This capability now differentiates premium tier positioning from standard rasterization.
- Integrated Graphics:CPU-embedded graphics controllers handle casual gaming without discrete power draw. Intel and AMD APU solutions serve budget-conscious and ultra-portable segments.
- Dedicated GPUs:Removable graphics cards with independent memory subsystems and thermal solutions. GDDR6X memory cost volatility compresses margins in mid-tier SKUs when commodity DRAM pricing spikes.
Volume concentrates in Dedicated GPUs. Ray Tracing capabilities are gaining share fastest among content creator upgrades.
Distribution Channel:
Channel selection reflects purchase urgency, technical support requirements, and component bundling preferences.
- Online Retailers:Amazon and Newegg aggregate inventory across brands with customer review transparency. Esports teams procure standardized competition hardware through these channels under bulk agreements.
- E-commerce Platforms:Brand-direct storefronts from ASUS, MSI, and Alienware control warranty registration and accessory attachment. Streamer infrastructure demands rotate procurement toward these pre-validated broadcast-ready configurations.
- Physical Stores:Micro Center and Best Buy provide immediate component availability for emergency replacements. Technical staff assist with compatibility verification during high-consideration purchases.
- Direct Sales:Enterprise procurement contracts serve tournament organizers and educational esports programs. Multi-year service agreements include dedicated GPU workstation refresh cycles.
Transaction volume flows predominantly through Online Retailers. Direct Sales channels are expanding most quickly among institutional buyers.
Customer Type:
Performance requirements and procurement budgets diverge sharply across recreational and professional use cases.
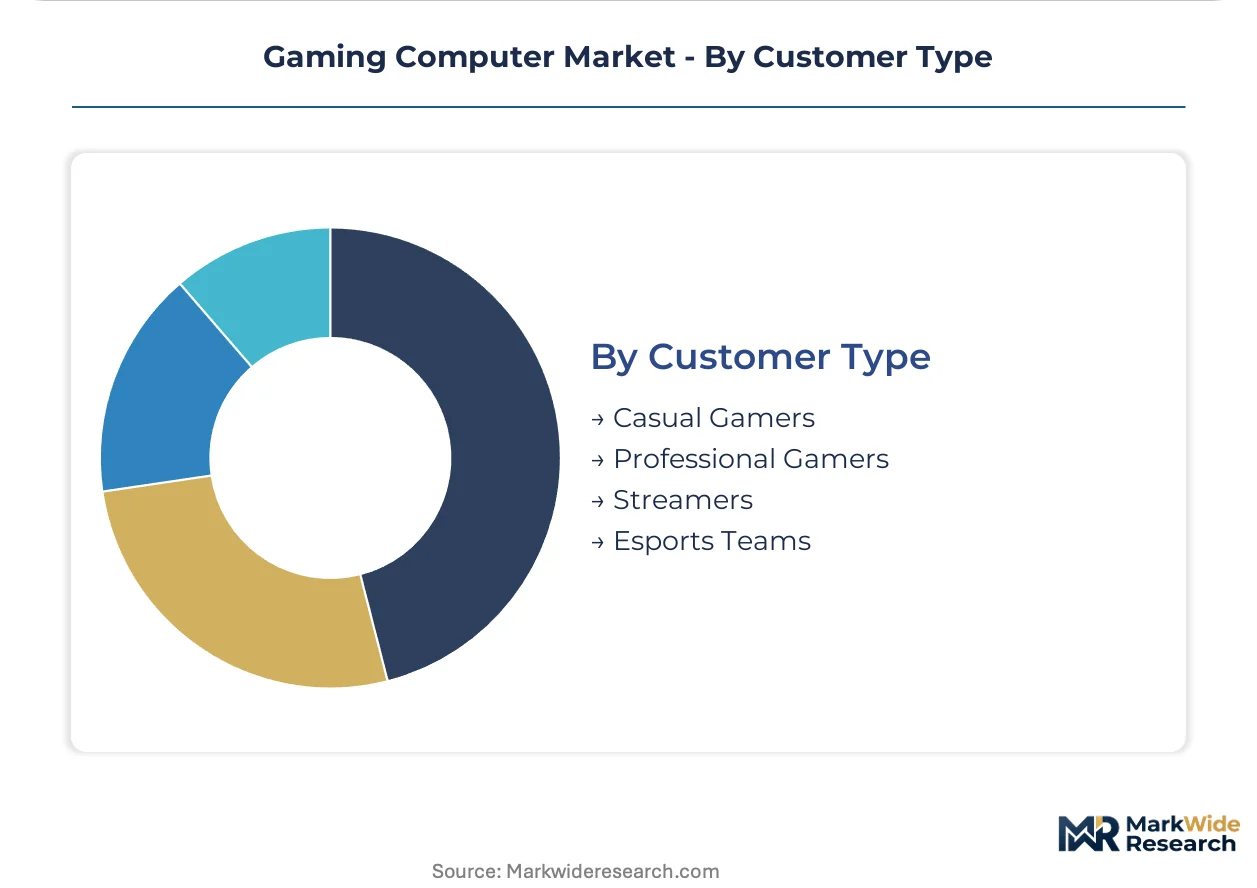
- Professional Gamers:Tournament competitors require frame rates exceeding 144 FPS at competitive settings. Sponsored athletes receive hardware stipends that anchor refresh cycle timing. This segment drives demand for the highest thermal density configurations.
- Streamers:Twitch and YouTube creators purchase complete workstation packages with capture cards and acoustic treatment. United States platform monetization infrastructure supports this as a primary occupation. Specialized retailers bundle lighting and streaming peripherals with core hardware.
- Casual Gamers:Recreational players prioritize value positioning and plug-and-play simplicity. Cloud gaming edge nodes in second-tier cities reduce hardware dependency for this segment.
- Esports Teams:Organized leagues mandate standardized hardware for competition integrity. Multi-year procurement agreements with system integrators ensure component uniformity across player rosters.
Revenue concentration sits with Professional Gamers. Streamer segment expansion is accelerating fastest among content creation monetization platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting assembly capacity toward jurisdictions with favorable efficiency-certification regimes. Component manufacturers migrate production to evade tightening material-content rules while maintaining thermal performance thresholds.
United States
Streamer infrastructure and esports tournament standards drive high-end desktop refresh cycles. The EPA ENERGY STAR program mandates 80 Plus Titanium compliance for pre-built systems, reshaping power-supply procurement. Austin and Seattle anchor system integrator clusters serving content creator demand.
China
Domestic esports leagues and professional gaming academies sustain GPU workstation demand. MIIT enforces GB standards on electronic product recyclability that restrict PCB substrate materials and cooling assembly alloys. Shenzhen and Suzhou concentrate motherboard and graphics card manufacturing around TSMC-adjacent foundry partnerships.
Germany
Enthusiast DIY markets and boutique system integrators sustain premium component demand. EU REACH and RoHS regulations govern chemical substance restrictions in electronics manufacturing. Bavaria hosts specialized retailers serving Central European gaming hardware procurement.
India
Professional gamers and emerging esports leagues drive laptop demand for portable tournament rigs. BIS certification requirements and PLI scheme incentives attract OEMs to establish captive assembly for domestic consumption. Karnataka and Maharashtra concentrate emerging manufacturing capacity near Bangalore and Mumbai logistics corridors.
Japan
Compact form-factor preferences and space-constrained living environments favor high-performance laptops. METI efficiency standards and JIS certification frameworks shape product design requirements. Tokyo-Osaka corridor anchors distribution networks serving enthusiast and professional segments.
Gaming Computer Market Vendor Landscape
Taiwanese producers anchor the component tier; American specialists hold system integration and brand positioning. Market structure concentrates around semiconductor suppliers with captive fabrication relationships, while downstream assembly fragments across regional OEMs. Three archetypes dominate: vertically integrated design-to-manufacture operators, thermal-engineering specialists, and scale-driven commodity assemblers. Competitive moves center on foundry partnership exclusivity and modular cooling solution licensing.
Within the design-to-manufacture tier, ASUS exemplifies vertical integration across motherboard and laptop fabrication. NVIDIA Corporation anchors discrete GPU supply for enthusiast configurations. MSI occupies a specialist position in compact thermal engineering for portable systems. These three represent distinct competitive vectors: captive supply chain control, semiconductor architecture dominance, and thermal performance differentiation.
| Leading Market Players |
|---|
| Dell Technologies |
| ASUS |
| HP |
| Lenovo |
| Acer |
| MSI |
| Alienware |
| Corsair Gaming |
| NVIDIA Corporation |
| Others |
Supply Flow & Price Mechanics
Streamer infrastructure procurement in the United States mandates pre-validated broadcast-ready configurations, forcing component suppliers to absorb certification costs while system integrators capture bundled-service premiums. This demand-side specification tightening compresses margins at the graphics card tier while elevating workstation ASPs.
Pricing Analysis
Retailer markup layers in the United States channel separate boutique system integrators from mass-market assemblers. Three-tier pricing structure across premium, standard, and economy levels tracks thermal solution sophistication and warranty bundling. Cost compression in mid-tier SKUs is intensifying because GDDR6X memory spot price volatility feeds directly into bill-of-materials pressure. Casual gamers exhibit highest price sensitivity, while esports teams under multi-year service agreements demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from tournament organizers and educational esports programs. Taiwan, China, and South Korea anchor discrete GPU wafer fabrication and memory module packaging. Raw material dependencies center on advanced node silicon, high-bandwidth GDDR6X, and copper-aluminum thermal interface alloys. Single-source vulnerability concentrates at TSMC foundry allocation for NVIDIA and AMD architectures. Distribution runs through brand-direct storefronts and online retailers with bulk procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gaming computer margins expand through thermal engineering premiumization as liquid cooling modularity lowers boutique assembly barriers. Component suppliers capturing vapor chamber and liquid metal application expertise command pricing power absent from commodity assemblers.
For Market Incumbents: Cement foundry partnership exclusivity through multi-year wafer allocation agreements with TSMC-adjacent suppliers. Defend against thermal engineer scarcity by acquiring captive ODM capabilities in Taiwan and establishing in-house vapor chamber fabrication. Vertical integration into cooling subsystem design protects premium positioning as MIIT recyclability mandates fragment mid-tier sourcing. For New Entrants and Emerging Players: India's PLI scheme opens a window for laptop OEMs to establish captive assembly serving domestic tournament infrastructure and re-export markets. White-space targets include portable tournament rigs for Asia-Pacific professional gamers and cloud gaming edge node hardware for second-tier city deployment. A BIS certification-fast-track go-to-market angle accelerates market entry against established brand-direct competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with thermal-engineering specialists possessing liquid metal application IP and compact form-factor vapor chamber designs. Long-term viability hinges on convergence between gaming hardware and AI training workstation demand as consumer RTX cards repurpose for machine learning acceleration. Watch for MIIT efficiency mandate enforcement intensity as inflection indicator for compliance-cost absorption capacity across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Exclusivity | TSMC-adjacent wafer allocation agreements secure advanced node GPU supply against geopolitical disruption. |
| Thermal Engineering Acquisition | Captive ODM capabilities in vapor chamber and liquid metal application replicate MSI's compact form-factor differentiation. |
| India PLI Assembly Buildout | BIS certification and domestic production incentives capture emerging esports league demand across Karnataka and Maharashtra. |
| Cloud Gaming Edge Infrastructure | GPU slice subscription models reduce casual gamer hardware dependency while creating recurring revenue streams. |
| AI Workstation Convergence | Consumer RTX positioning for machine learning accelerators expands addressable market to research labs and indie developers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged GPU architecture leads at NVIDIA and AMD, thermal engineering directors at MSI and ASUS, procurement officers at esports tournament organizers, and system integrator operations heads in Austin and Seattle. Secondary validation drew from EPA ENERGY STAR certification databases, MIIT GB standards filings, FCC pre-certification records, and SEC 10-K disclosures from component suppliers. Bottom-up build from graphics card shipment data and top-down triangulation against pre-built system revenue estimates anchored market sizing.
Segment-weighting approach distributed value across desktops, laptops, consoles, and custom builds by thermal solution intensity and upgrade cycle frequency. Graphics technology segmentation modeled discrete GPU, ray tracing capability, integrated graphics, and dedicated GPU attach rates. Distribution channel splits tracked online retailer volume, e-commerce platform attach rates, physical store emergency replacement demand, and direct sales contract values. CAGR derivation applied logistic diffusion curves to ray tracing adoption rates and esports tournament hardware refresh mandates across the projection horizon. Forecast inputs incorporated TSMC foundry capacity allocation schedules and GDDR6X commodity pricing volatility indices.
Revisions become necessary when TSMC fab disruption, MIIT material-content rule tightening, or EPA efficiency tier advancement materialize ahead of modeled timelines. Forecasts reflect documented assumptions regarding esports league standardization timelines and streamer infrastructure monetization sustainability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Headset Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Mouse Pad Market
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Instant Camera Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Global Home Audio System Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market