
 Consumer Electronics Retail Market | 2026-2036
Consumer Electronics Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Electronics Retail Market Insights
Shenzhen's contract manufacturing base is restructuring how OEMs source inventory for retail channels worldwide. Best Buy leverages its Geek Squad service infrastructure to sustain repeat traffic in physical locations. Amazon competes through logistics density that anchors same-day delivery expectations for consumer electronics buyers.
Consumer electronics retail encompasses the commercial distribution of finished electronic devices to end users through physical and digital storefronts, typically involving inventory turnover cycles of 30 to 90 days for high-velocity categories such as smartphones and wearables. The sector functions as the terminal node in a supply chain where semiconductor content, display panels, and battery assemblies converge into finished goods for immediate consumption. Smartphones and laptops occupy the largest revenue pools within product type segmentation, though wearables generate disproportionate margin contribution per square foot of retail space. Online retailers now capture the fastest-growing transaction volume, while warehouse clubs concentrate on premium-tier bundles that lift average selling prices.
The US Federal Trade Commission scrutinizes subscription practices and warranty restrictions that affect how retailers structure post-purchase revenue streams. The EU's Ecodesign for Sustainable Products Regulation and REACH chemical compliance requirements shape import standards for electronics sold through European retail channels. Stakeholders must monitor how fragmented national repair mandates alter inventory planning and after-sales service economics across their store networks.
Market Dynamics
Right-to-repair mandates and same-day delivery expectations are compressing traditional retail margins while forcing inventory localization and service infrastructure reinvestment across omnichannel networks.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandates extended producer responsibility and repairability scoring, creating certified refurbishment revenue streams for retailers with in-house technical capabilities.
- Smart home device convergence:Interoperability protocols like Matter are bundling lighting, security, and climate control into single-purchase ecosystems that lift average transaction values.
- Tier-one Chinese urban corridors:Shenzhen and Shanghai concentrate high-income households with compressed replacement cycles for flagship smartphones and wearables.
Market Restraints
- Semiconductor input volatility:Foundry capacity constraints for advanced node chips create 60-90 day inventory uncertainty for premium laptop and smartphone SKUs.
- REACH chemical compliance:Restricted substance lists for batteries and displays force supplier recertification that delays European product launches by 4-6 months.
- Modular smartphone substitution:Framework and Fairphone repairable architectures threaten planned obsolescence models underlying carrier subsidy economics.
Strategic Opportunities
- India's metropolitan corridors:Bangalore, Mumbai, and Delhi NCR underpenetration in premium audio and gaming peripherals offers first-mover positioning before organized retail density peaks.
- Trade-in program regulatory tailwinds:French repairability index mandates and US state right-to-repair laws legitimize certified pre-owned channels with formal warranty backing.
- AR-assisted retail convergence:Spatial computing visualization tools are merging physical showrooming with digital inventory depth, reducing square-footage requirements in high-rent districts.
Industry Challenges
- Geek Squad-scale technical talent scarcity:Component-level repair certification programs cannot match demand for microsoldering and board-level diagnostics as warranty obligations expand.
- Multi-jurisdiction compliance capex:Separate inventory pools for EU battery passports, US state repair mandates, and India's BIS labeling fragment working capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Electronics Retail Market |
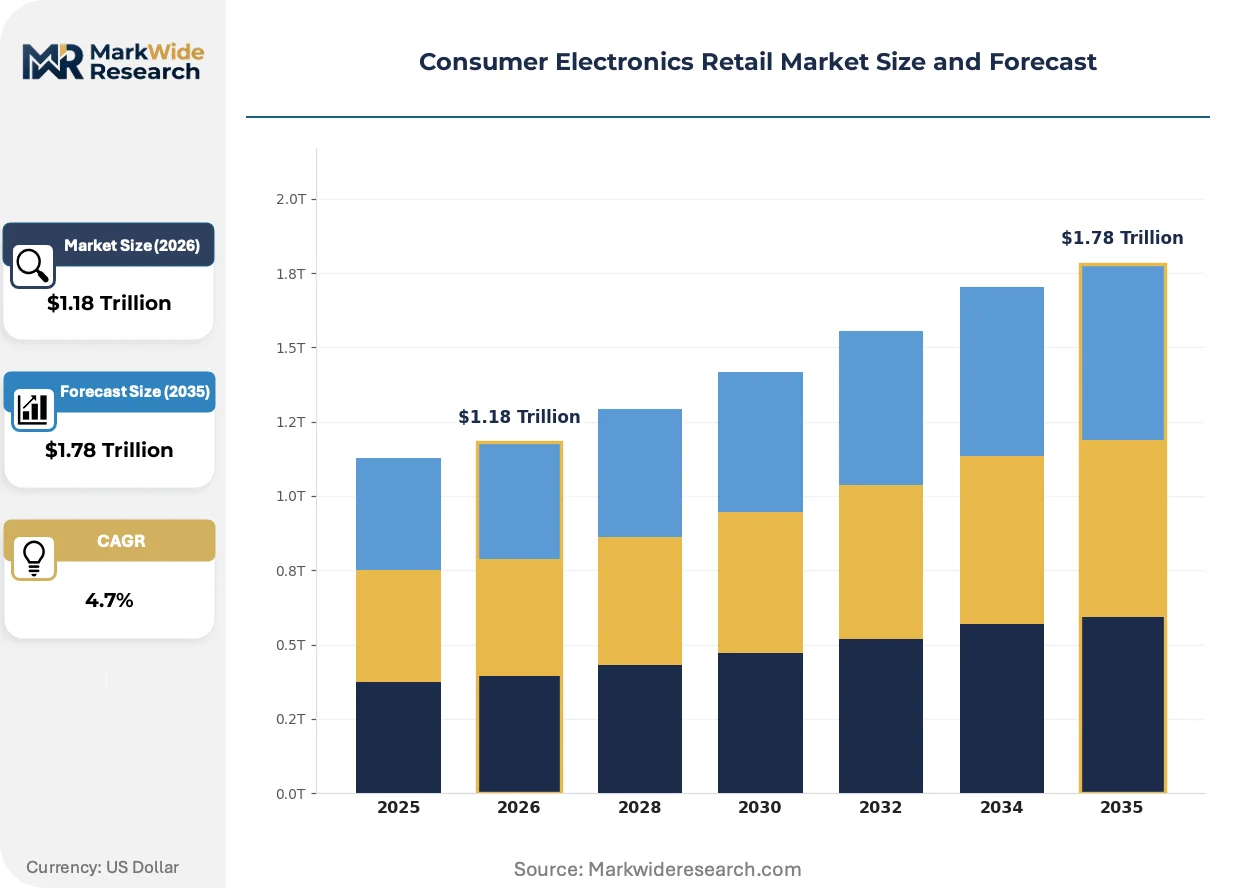
| Market Size in 2026 | $1.18 Trillion |
| Market Size in 2035 | $1.78 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearables Customer Type: Individual Consumers, Businesses, Educational Institutions, Government Agencies Distribution Channel: Online Retailers, Electronics Stores, Supermarkets, Warehouse Clubs Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Walmart, Costco, Apple, Crutchfield, B&H Photo & Electronics, Best Buy, Amazon, ABT Electronics, Arrow Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Electronics Retail Market Trends and Innovations
Retail networks are reconfiguring around predictive fulfillment and circular service models that compress the traditional buy-own-dispose cycle into continuous upgrade loops.
Generative AI-powered shopping assistants are expanding into purchase guidance and technical support functions. Mass-market retailers deploy these tools to reduce staffed service desk hours while maintaining conversion rates. The technology is expanding into post-purchase troubleshooting, displacing traditional call center volume.
EU's Digital Product Passport requirements under the Ecodesign for Sustainable Products Regulation mandate component traceability and end-of-life handling instructions. Retailers must integrate supplier data systems to display repair scores and carbon footprints at point-of-sale. Electronics sold through German and French channels face the earliest compliance deadlines, forcing inventory system overhauls ahead of phased rollout.
Subscription-based hardware access models are displacing outright ownership in premium audio and gaming segments. Retailers bundle devices with cloud storage, extended warranties, and trade-in guarantees into monthly payments. This shift concentrates in US urban markets where credit-accessible consumers prioritize flexibility over asset accumulation.
Consumer Electronics Retail Market Segmentation
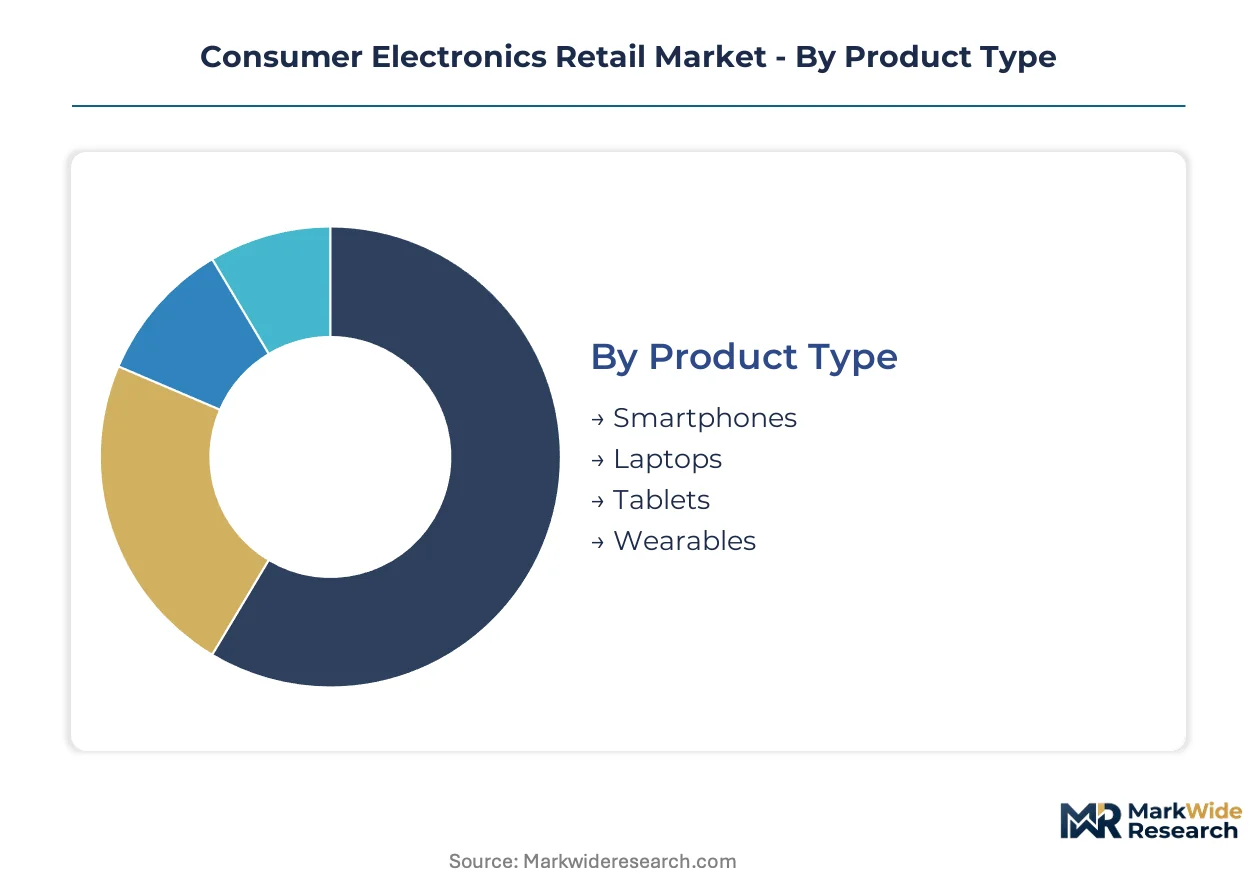
Consumer electronics retail segmentation determines inventory turnover velocity, margin architecture, and service infrastructure requirements across physical and digital storefronts. Distinct product lifecycles and customer procurement patterns force parallel supply chain configurations.
Product Type:
Standardization dominates smartphones and laptops with global SKU consistency, while wearables and tablets fragment across regional feature preferences and carrier compatibility requirements.
- Smartphones:Flagship devices with 5G modems and advanced camera arrays drive the largest revenue pool within retail electronics. Demand concentrates in Shenzhen and Shanghai where compressed 18-24 month replacement cycles outpace global averages, though semiconductor foundry constraints for 3nm chips create 60-90 day inventory uncertainty for premium SKUs.
- Laptops:Enterprise-grade configurations with AI-accelerated processors and extended battery architectures sustain higher per-unit margins than consumer models. Procurement from educational institutions in India's metropolitan corridors is climbing fastest as hybrid learning infrastructure expands, while US businesses defer fleet refreshes amid economic uncertainty.
- Tablets:Stylus-integrated productivity devices and ruggedized field-service variants serve niche professional segments with specialized accessory bundling.
- Wearables:Health-monitoring smartwatches and hearables generate disproportionate margin per square foot through ecosystem lock-in and subscription service attachments.
Leading the category by volume: Smartphones. Expanding most quickly: Wearables.
Customer Type:
Volume procurement patterns separate institutional buyers with formal RFP processes from individual consumers responding to promotional calendars and trade-in incentives.
- Individual Consumers:Price-sensitive purchasers with high responsiveness to seasonal discounting and carrier subsidy structures.
- Businesses:Enterprise accounts negotiate volume pricing with standardized imaging and extended warranty terms, creating predictable replenishment schedules.
- Educational Institutions:K-12 districts and universities procure ruggedized devices with multi-year support contracts, prioritizing total cost of ownership over upfront hardware expense.
- Government Agencies:Federal, state, and municipal buyers face procurement regulations including NIST cybersecurity standards and domestic content requirements that limit vendor pools.
Highest transaction frequency: Individual Consumers. Steepest expansion trajectory: Educational Institutions.
Distribution Channel:
Capital intensity and inventory risk tolerance divide channels between asset-light digital platforms and fixed-cost physical networks with service integration.
- Online Retailers:Algorithmic recommendation engines and logistics density enable same-day delivery expectations with lower customer acquisition costs than physical expansion.
- Electronics Stores:Geek Squad-style technical service infrastructure sustains repeat traffic and high-margin repair revenue streams.
- Supermarkets:Impulse-purchase electronics accessories and entry-level smartphones leverage existing grocery foot traffic with minimal incremental square footage.
- Warehouse Clubs:Premium-tier bundles and extended warranties lift average selling prices through membership-based purchasing psychology.
Dominant by transaction volume: Online Retailers. Gaining share fastest: Warehouse Clubs.
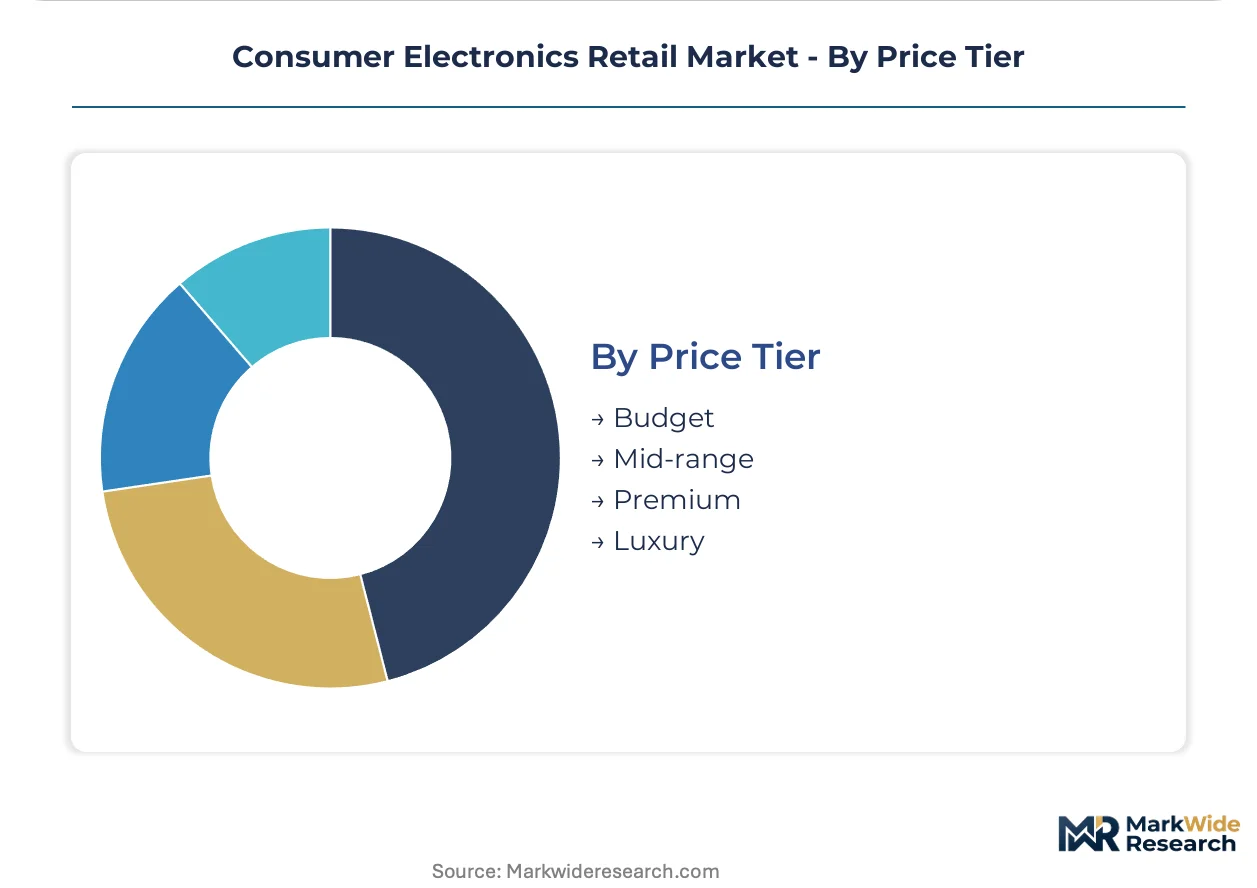
Price Tier:
Margin structure inverts across tiers as budget SKUs compete on procurement efficiency while luxury segments monetize exclusivity and concierge service.
- Budget:Sub-$200 smartphones and entry-level laptops prioritize functional adequacy over performance headroom, serving price-constrained segments in India's tier-two cities.
- Mid-range:$400-$800 devices with flagship-adjacent features capture the largest unit volume through carrier subsidy economics and trade-in program accessibility.
- Premium:$1,000+ flagship smartphones and professional-grade laptops concentrate in China's tier-one urban corridors and US coastal metropolitan areas.
- Luxury:Limited-edition collaborations and precious-material finishes target collectors with inelastic demand and minimal price transparency.
Largest unit volume: Mid-range. Fastest margin expansion: Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-ion cell manufacturing clusters in Jiangsu province anchor Asia-Pacific supply networks for portable electronics retail channels. Semiconductor foundry investments in Arizona and Texas reshape North American inventory localization strategies. Cobalt and rare earth processing facilities in the Democratic Republic of Congo and China concentrate upstream material flows.
United States
Enterprise fleet refresh cycles and consumer trade-in programs drive laptop and smartphone demand across coastal metropolitan corridors. The FTC's warranty restriction enforcement alters how retailers structure post-purchase service revenue. Phoenix and Austin semiconductor fabs reduce lead times for premium device SKUs sold through Southwest distribution centers.
China
Compressed 18-24 month flagship replacement cycles in Shenzhen and Shanghai outpace global smartphone turnover averages. MIIT's GB standards for wireless charging interoperability mandate protocol compatibility across domestic brands. Yangtze River Delta contract manufacturers restructure OEM sourcing relationships for European retail channels.
Germany
EU Ecodesign repairability scoring and battery passport requirements concentrate compliance investment in Berlin and Munich retail networks. REACH chemical substance restrictions force supplier recertification delays for display and battery components. Bavaria's technical service infrastructure supports certified refurbishment revenue streams under extended producer responsibility mandates.
India
Educational institution procurement and hybrid learning infrastructure expansion accelerate laptop demand in Bangalore, Mumbai, and Delhi NCR. BIS labeling requirements and DGFT import certification create regulatory friction for premium audio and gaming peripheral launches. Karnataka's electronics manufacturing zones attract contract assembly for domestic retail distribution.
Japan
Aging demographic demand for health-monitoring wearables and simplified smartphone interfaces sustains niche product development. METI's carbon neutrality roadmaps pressure retailers to disclose supply chain emissions for consumer-facing products. Tokyo-Osaka corridor electronics chains integrate subscription-based hardware access models with technical support services.
Consumer Electronics Retail Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue circular service models and predictive fulfillment infrastructure. The vendor base spans multinational omnichannel platforms, membership-based warehouse clubs, and specialized technical service retailers with in-house repair capabilities. Three archetypes dominate: logistics-density pure-plays, service-integrated physical networks, and ecosystem-locked brand-direct channels. Competitive moves concentrate on trade-in program scaling and AR-assisted showrooming technology deployment.
Within the logistics-density tier, Amazon exemplifies algorithmic fulfillment infrastructure that compresses delivery windows. Best Buy anchors the service-integrated physical network archetype through Geek Squad technical capabilities. Walmart represents scale-driven omnichannel positioning that leverages grocery foot traffic for electronics accessory distribution.
| Leading Market Players |
|---|
| Walmart |
| Costco |
| Apple |
| Crutchfield |
| B&H Photo & Electronics |
| Best Buy |
| Amazon |
| ABT Electronics |
| Arrow Electronics |
| Others |
Pricing and Supply Chain Analysis
Microsoldering technicians concentrated in Shenzhen and Dongguan compress labor-cost spreads between premium and budget electronics tiers, with wage arbitrage in China's Pearl River Delta sustaining margin architecture across smartphone and laptop SKUs.
Pricing Analysis
Warranty bundling separates Geek Squad-style service-inclusive premiums from unbundled transactional pricing at online pure-plays. Three-tier pricing structure across premium, standard, and economy levels tracks semiconductor node advancement and display panel resolution grades. Cost compression in mid-range SKUs is intensifying because carrier subsidy economics face pressure from modular smartphone alternatives. Individual consumers in India's tier-two cities exhibit highest price sensitivity, while enterprise fleet buyers in US coastal metros demonstrate lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for trade-in devices and certified refurbishment create secondary inventory pools that compete with primary channel pricing. Component sourcing concentrates in China, Taiwan, and South Korea for advanced node semiconductors and OLED display panels. Battery cell chemistry rests on lithium carbonate from Chile and cobalt hydroxide from the Democratic Republic of Congo. Single-source vulnerability in 3nm foundry capacity threatens premium SKU availability. Distribution runs through Shenzhen contract manufacturers to regional fulfillment centers anchoring same-day delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consumer electronics retail sector is becoming a vertical-integration race, with players pursuing backward integration into component-level repair certification to capture Ecodesign-mandated refurbishment revenue.
For Market Incumbents: Lock in technical service talent through accredited microsoldering programs before EU repairability mandates expand warranty obligations. Secure exclusive distribution partnerships with Yangtze River Delta contract manufacturers to defend against direct-to-retail OEM disintermediation. For New Entrants and Emerging Players: Right-to-repair legislation in France and select US states opens a window for certified pre-owned channel positioning with formal warranty backing. Target underpenetrated premium audio and gaming peripheral demand in Bangalore and Delhi NCR before organized retail density peaks, leveraging BIS certification expertise as a go-to-market differentiator. For Investors and Strategic Acquirers: Re-rating potential sits with technical-service-integrated retailers given Digital Product Passport compliance deadlines forcing inventory system overhauls. Long-term viability favors players with in-house refurbishment capabilities and Geek Squad-scale repair infrastructure. Monitor EU battery passport rollout timelines and US state repair mandate adoption rates as inflection indicators for certified pre-owned channel legitimacy.| Strategic Initiative | Industry Significance |
|---|---|
| Repair Certification Program Buildout | EU Ecodesign repairability scoring mandates create defensible revenue streams in Berlin and Munich retail networks. |
| Trade-in Program Scaling | French repairability index legitimates certified pre-owned channels with formal warranty economics. |
| AR-Assisted Showrooming Deployment | Spatial computing tools reduce square-footage requirements in high-rent Tokyo-Osaka corridor districts. |
| Subscription Hardware Access Launch | Monthly payment models displace outright ownership in US urban credit-accessible consumer segments. |
| Regional Fulfillment Center Localization | Arizona and Texas semiconductor fabs enable Southwest distribution center inventory compression. |
Research Methodology
Document review covered SEC 10-K filings, EU regulatory impact assessments, and customs trade databases, complemented by interviews with retail operations executives, category buyers at omnichannel platforms, technical service directors, and contract manufacturing sourcing managers. Secondary validation drew from FTC enforcement actions, MIIT GB standard publications, and BIS certification records. Bottom-up SKU-level demand modeling triangulated against top-down retail channel revenue estimates.
Historical shipment trajectories cross-referenced against panel input from procurement leads and supply chain planners across the analysis window. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and price tier alongside regional regulatory cluster variations. CAGRs were synthesized from replacement cycle compression rates and trade-in program adoption curves, with semiconductor foundry capacity utilization and REACH compliance timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path for AR-assisted retail convergence; alternative pathways for spatial computing deployment would alter the outlook for physical showrooming requirements. Forecasts reflect assumptions regarding EU Digital Product Passport phased rollout and US state repair mandate fragmentation. Practitioners should monitor FTC warranty restriction enforcement patterns and India DGFT import certification processing times for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Keycap Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Gun Care Products Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
Smart Phones Market