
 Skin Tag Remover Market | 2026-2036
Skin Tag Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Tag Remover Market Insights
Direct-to-consumer leasing and subscription financing for at-home dermatology devices is fragmenting competitive barriers, enabling smaller brands to challenge established manufacturers. CryoZap leverages specialized cold-applicator technology to differentiate its kit-based offerings. Compound W sustains broad retail shelf presence through pharmacy channel control. Dr. Scholl's anchors consumer trust via brand extension from foot care into broader skin treatment categories.
Skin tag removers encompass topical formulations and mechanical devices designed for benign acrochordon elimination, typically incorporating salicylic acid, tea tree oil, or cryogenic agents that disrupt lesion tissue through chemical keratolysis or controlled freezing at temperatures below minus fifty degrees Celsius. Creams and gels dominate current volume as consumers favor discreet, gradual-application formats over abrupt mechanical removal. Patches represent the fastest-expanding product type, driven by sustained-release delivery systems that reduce user error and improve completion rates. Dermatologists and clinics command premium pricing tiers, while retail consumers absorb the bulk of absolute unit demand through online and third-party retailer channels.
FDA Center for Drug Evaluation and Research governs active ingredient concentrations in over-the-counter skin tag formulations, while EPA regulates volatile organic compounds in spray-based products, collectively elevating compliance costs for new market entrants. ISO 13485 certification requirements for cryogenic medical devices further constrain manufacturing scale-up for kit producers. Stakeholders must weigh regulatory pathway complexity against channel expansion timelines when prioritizing geographic or format entry strategies.
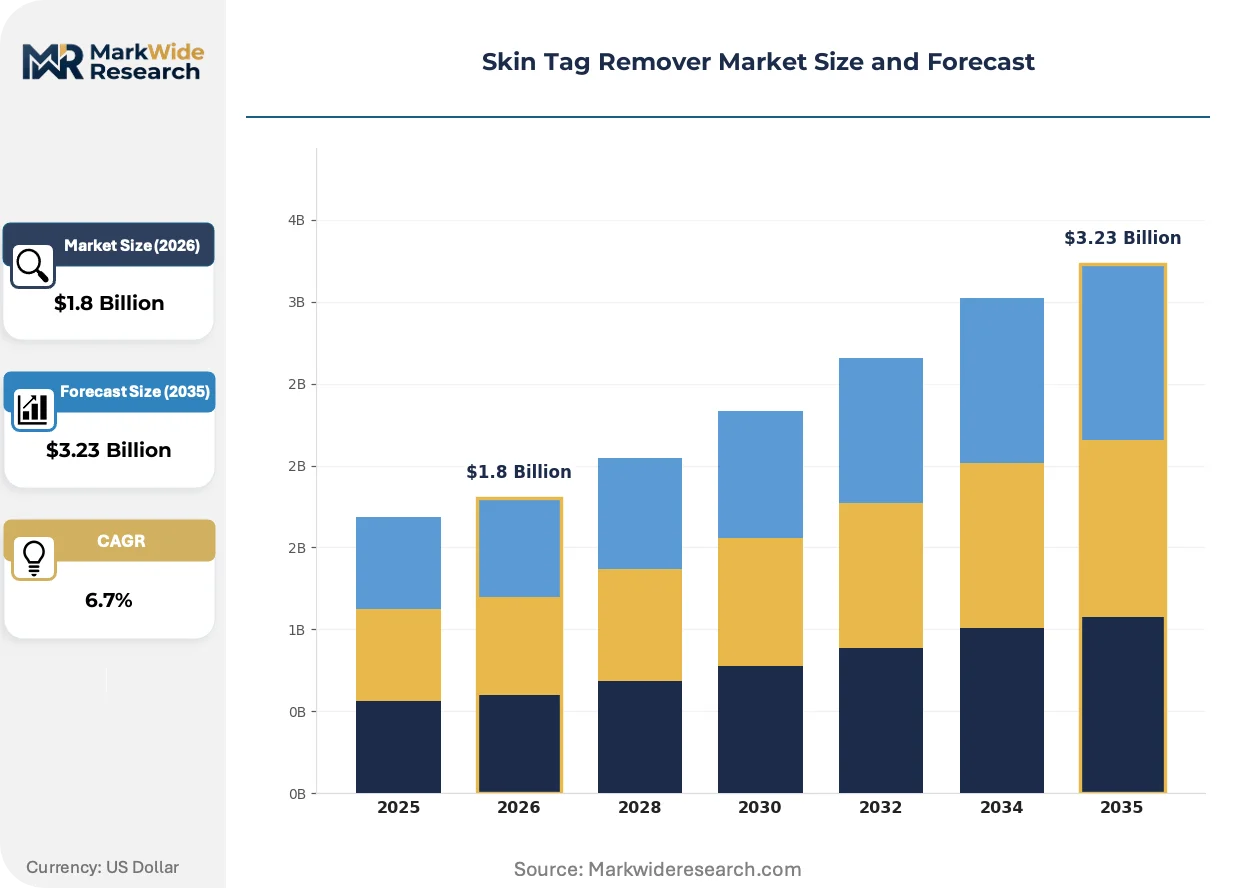
Market Dynamics
Direct-to-consumer financing for at-home dermatology devices is fragmenting competitive barriers, enabling smaller brands to challenge established manufacturers through subscription-based access models rather than upfront purchase requirements.
Growth Catalysts
- FDA OTC Monograph Expansion:The FDA Center for Drug Evaluation and Research continues clarifying active ingredient thresholds for salicylic acid and cryogenic formulations, reducing approval timelines for compliant new entrants.
- Tea Tree Oil Sustained-Release Patches:Australian tea tree oil suppliers are partnering with Korean patch manufacturers to develop 72-hour transdermal delivery systems that improve treatment completion rates among retail consumers.
- Dermatology Clinic Channel Expansion:United States dermatology clinics are adding cryogenic device services to capture patients seeking professional-grade removal without surgical referral.
Market Restraints
- Salicylic Acid Feedstock Volatility:Petrochemical-derived salicylic acid faces price pressure from crude oil fluctuations, compressing margins for high-volume topical producers.
- ISO 13485 Certification Burden:Cryogenic device manufacturers must maintain quality management systems across multiple production facilities, elevating fixed costs for kit producers seeking geographic expansion.
- Home Remedy Substitution:Apple cider vinegar and dental floss ligation methods circulate through social platforms, diverting price-sensitive consumers from commercial formulations.
Strategic Opportunities
- India Retail Pharmacy Penetration:India's fragmented pharmacy network offers first-mover advantage for brands establishing direct distribution outside metropolitan centers.
- CE Marking Convergence with MDR:The EU Medical Device Regulation creates pathway harmonization for cryogenic applicators previously classified as cosmetic devices, opening clinical channel access.
- Telehealth Integration:United States telehealth platforms are adding asynchronous skin lesion screening, creating prescription-fulfillment partnerships for prescription-strength topical kits.
Industry Challenges
- Formulation Chemist Scarcity:Qualified cosmetic chemists with cryogenic compound experience command premium salaries, constraining R&D velocity for mid-tier manufacturers.
- Cold Chain Distribution Complexity:Cryogenic kit components require controlled temperature logistics, complicating third-party retailer fulfillment and increasing damage rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Tag Remover Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Patches, Kits Form: Liquid, Solid, Spray, Balm Customer Type: Retail Consumers, Dermatologists, Clinics, Pharmacies Distribution Channel: Online, Offline, Direct Sales, Third-Party Retailers |
| Companies Covered | CryoZap, Compound W, DermaClear Serum, Alocane, OPHERA, Dr. Scholl’s, DermaLase, NanoPulse, Claritag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Tag Remover Market Trends and Innovations
Product format innovation and regulatory pathway evolution are compressing traditional competitive advantages, while channel restructuring is redistributing margin capture across the value chain.
AI-powered skin lesion classification applications are virtualizing the initial diagnostic step for at-home users. United States telehealth platforms integrate these tools to triage benign acrochordon cases before product recommendation. The technology is virtualizing the role of in-person dermatological assessment, compressing the addressable market for clinic-based first consultations.
EPA volatile organic compound regulations for aerosol-based cryogenic sprays are tightening concentration limits and propellant specifications. Manufacturers reformulate toward non-VOC propellants or pivot to pump-dispensed alternatives. United States retail channels bear the highest compliance burden, with pharmacy chains demanding third-party VOC testing documentation before shelf placement.
Subscription-based replenishment models are displacing one-time purchase patterns among repeat users. Direct-to-consumer brands capture recurring revenue through automated patch or cream resupply, while traditional pharmacy retailers lose foot traffic to locked-in digital relationships. This shift concentrates most visibly in United States urban markets where same-day delivery infrastructure supports just-in-time fulfillment.
Skin Tag Remover Market Segmentation
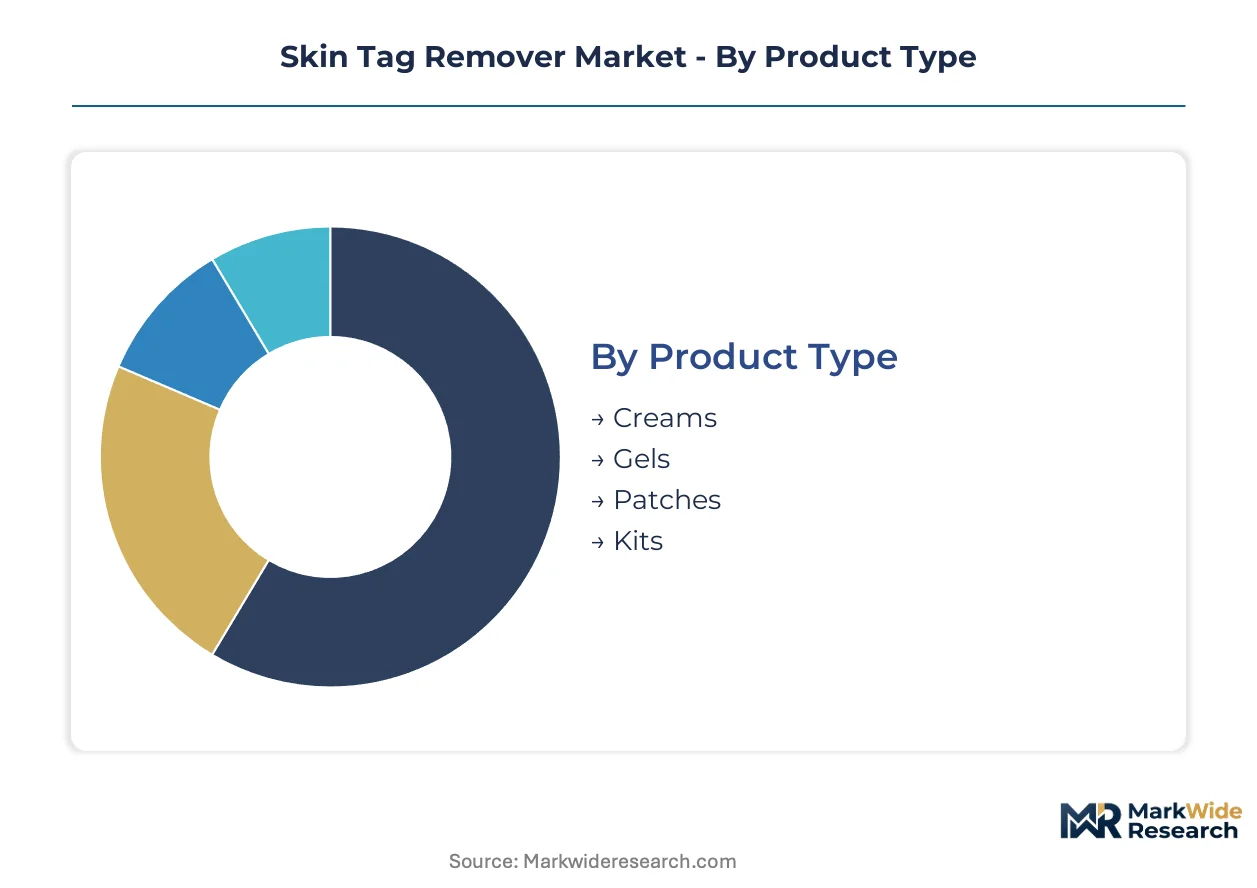
Skin tag remover market segmentation reveals how formulation chemistry, application mechanics, and channel economics partition demand across distinct user workflows. Product type and customer type together determine pricing architecture and regulatory pathway complexity.
Product Type:
Mature formats dominate absolute volume while emerging delivery systems reshape completion economics.
- Creams:Oil-in-water emulsions incorporating salicylic acid at concentrations between 17% and 40% disrupt keratinocyte adhesion through controlled chemical exfoliation. United States retail consumers absorb the bulk of cream demand through pharmacy and mass-market channels where discretion and gradual results align with preference.
- Patches:Occlusive adhesive systems with sustained-release tea tree oil or salicylic acid reservoirs enable 24-to-72-hour continuous delivery without reapplication. Korean contract manufacturers are expanding patch capacity to serve direct-to-consumer brands seeking differentiation through treatment adherence improvement.
- Gels:Hydroalcoholic matrices provide rapid drying and invisible wear properties valued by working-age users.
- Kits:Cryogenic applicator systems with dimethyl ether or nitrous oxide propellants deliver professional-grade freezing temperatures for home use.
Creams handle the majority of throughput; patches are the fastest mover on share.
Form:
Cost tier stratification separates commodity liquids from precision-engineered solid and spray formats.
- Liquid:Alcohol-based solutions with dissolved active ingredients offer the lowest unit economics and highest price sensitivity. Indian retail pharmacies move substantial liquid volume through unbranded generic channels where cost per milliliter drives selection.
- Spray:Aerosolized cryogenic formulations require EPA-compliant propellant systems and pressure-resistant packaging. United States manufacturers face elevated compliance costs for volatile organic compound testing under EPA oversight.
- Solid:Stick formats with waxy matrices enable targeted application without spillage or dosing error.
- Balm:Petrolatum-based occlusives with emollient properties suit users with concurrent dry skin conditions.
Liquid commands the volume base; spray formats capture the steepest expansion trajectory among premium-positioned offerings.
Customer Type:
Application setting determines regulatory classification and margin structure across the value chain.
- Retail Consumers:Self-directed purchasers seeking at-home solutions without clinical consultation represent the absolute unit demand anchor. United States telehealth platforms are adding asynchronous screening tools that validate benign lesion status before product recommendation, expanding the addressable self-treatment population.
- Dermatologists:Board-certified practitioners command premium pricing for cryogenic device services and prescription-strength topical kits. United States clinic networks are adding express removal appointments to capture patients who would otherwise defer to retail alternatives.
- Clinics:Med-spa and aesthetic practice chains standardize cryogenic protocols across location networks.
- Pharmacies:Retail pharmacy staff provide front-of-store recommendation authority that shapes brand selection in impulse purchase contexts.
Retail consumers absorb the majority of absolute units; dermatologist services are climbing the fastest on revenue per procedure.
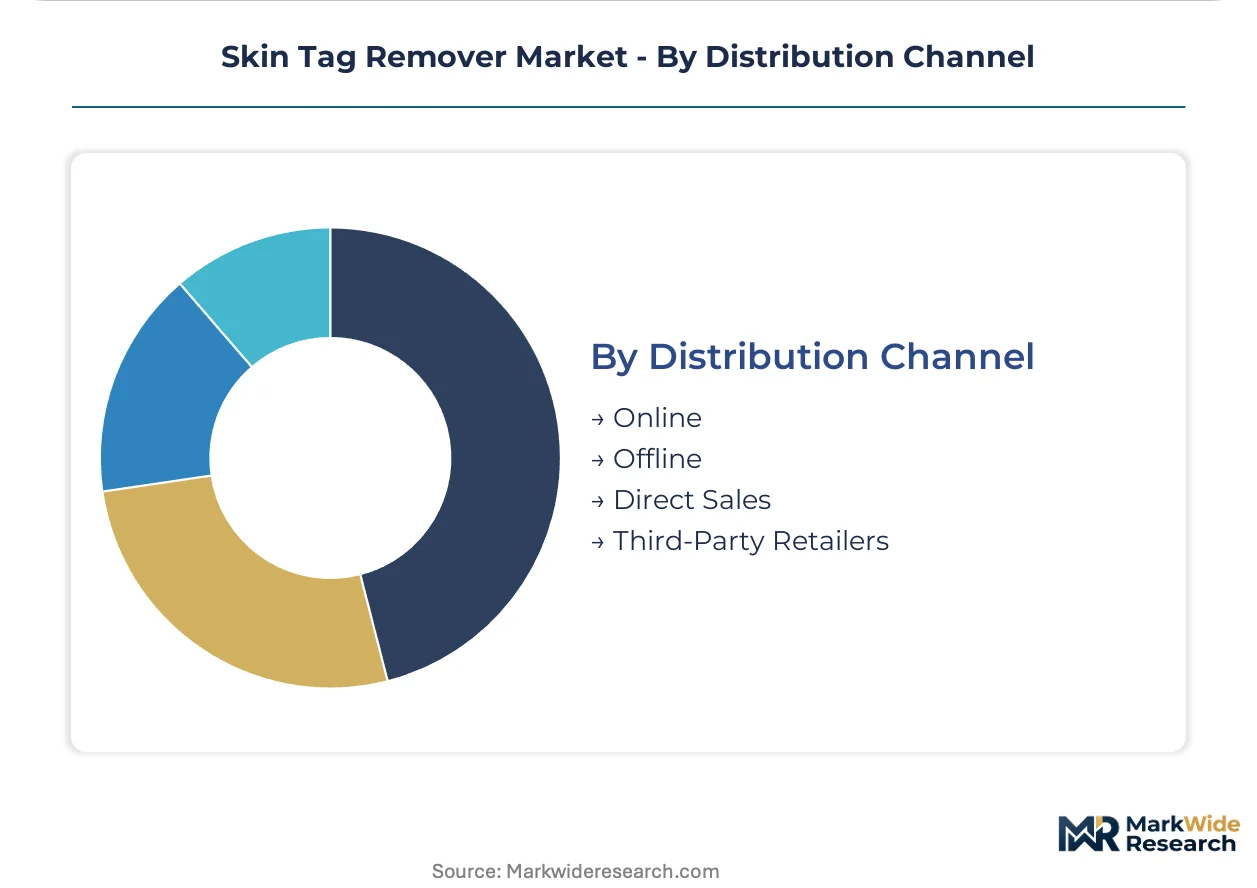
Distribution Channel:
Channel restructuring is redistributing margin capture between legacy retail and direct digital relationships.
- Online:Brand-owned websites and marketplace storefronts enable subscription replenishment models that lock in recurring revenue. United States urban markets with same-day delivery infrastructure support just-in-time patch and cream fulfillment that displaces pharmacy foot traffic.
- Offline:Physical retail including pharmacy chains and mass merchandisers sustains impulse purchase volume through shelf placement and staff recommendation.
- Direct Sales:Dermatology clinic dispensing of professional-grade kits captures margin that would otherwise flow to retail intermediaries.
- Third-Party Retailers:Amazon, Walmart.com, and specialty health platforms aggregate comparison shopping behavior that pressures brand premium positioning.
Online channels are gaining share fastest; offline retains the volume foundation in suburban and rural geographies where digital penetration lags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for cryogenic propellants and tea tree oil feedstocks shapes regional manufacturing economics. Export-oriented patch manufacturers in East Asia supply direct-to-consumer brands in Western markets. Cold chain logistics capabilities determine which geographies can sustain kit-based product distribution at scale.
United States
Retail pharmacy networks and telehealth platforms absorb the majority of at-home device demand. FDA OTC monograph compliance and EPA volatile organic compound testing create dual regulatory entry barriers for spray-based formulations. Austin and Boston clusters host direct-to-consumer brands leveraging subscription replenishment models.
Germany
CE marking convergence with EU Medical Device Regulation reclassifies cryogenic applicators as clinical-grade devices, opening dermatology clinic channels. ECHA chemical safety assessments influence salicylic acid concentration thresholds for topical products. Bavaria-based manufacturers specialize in precision-engineered cold applicator systems for professional use.
South Korea
Sustained-release patch manufacturing capacity concentrates among contract producers serving global direct-to-consumer brands. MFDS cosmetic and medical device classification distinctions shape formulation development pathways. Seoul metropolitan area hosts the dominant cluster of transdermal delivery system specialists.
India
Fragmented retail pharmacy networks outside metropolitan centers present first-mover distribution opportunities for topical liquid and cream formats. CDSCO regulates prescription-strength salicylic acid concentrations, while BIS standards govern over-the-counter cosmetic classifications. Maharashtra and Gujarat house the primary domestic formulation packaging facilities.
Australia
Tea tree oil feedstock suppliers partner with Korean manufacturers on 72-hour transdermal patch development. TGA therapeutic goods classifications distinguish cosmetic skin treatments from medical devices. Queensland agricultural regions anchor global Melaleuca alternifolia oil production for export to formulation partners.
Skin Tag Remover Market Competitive Landscape
On the supply side, the industry is bifurcated between established pharmacy channel incumbents and direct-to-consumer challengers leveraging subscription financing. Three strategic archetypes dominate: legacy foot-care brands extending into adjacent skin treatment categories, cryogenic device specialists differentiating through cold-applicator technology, and patch manufacturers competing on sustained-release formulation science. M&A activity concentrates on telehealth platform integration and Korean contract manufacturing capacity acquisition.
Within the device-specialist tier, CryoZap exemplifies cold-applicator technology differentiation. Compound W and Dr. Scholl's occupy positions as pharmacy-channel incumbents with established retail shelf presence. These three anchors illustrate the competitive tension between technology-driven new entrants and brand-extension strategies from adjacent personal care categories.
| Leading Market Players |
|---|
| CryoZap |
| Compound W |
| DermaClear Serum |
| Alocane |
| OPHERA |
| Dr. Scholl's |
| DermaLase |
| NanoPulse |
| Claritag |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific cold chain corridors linking Korean patch manufacturers to United States direct-to-consumer brands concentrate logistics costs in the premium kit segment, compressing margins for cryogenic device specialists while enabling tea tree oil cream producers to maintain price stability through simpler freight profiles.
Pricing Analysis
Retail consumers anchor a three-tier pricing structure across premium, standard, and economy levels in the skin tag remover market. Price differentiation rests on FDA OTC monograph compliance status and ISO 13485 certification tier, with cryogenic kits commanding premiums over topical creams. Cost compression in the spray format is intensifying because EPA volatile organic compound testing requirements add fixed compliance burdens. Price-sensitive buyers in Indian retail pharmacies gravitate toward unbranded liquid generics, while United States dermatology clinics absorb premium pricing for prescription-strength formulations.
Supply Chain Analysis
Tariff exposure between Australia and South Korea dominates feedstock cost volatility for tea tree oil patch manufacturers. Geographic supply concentration centers on South Korea for transdermal delivery systems, China for dimethyl ether propellants, and India for salicylic acid synthesis. Raw material dependencies include Melaleuca alternifolia oil, petrochemical-derived salicylic acid, and medical-grade nitrous oxide. Single-source vulnerability characterizes Korean contract manufacturing for sustained-release patches. Distribution runs through direct-to-consumer subscription platforms and pharmacy chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with cryogenic compound experience are in critically short supply, constraining R&D velocity and creating acquisition premiums for mid-tier manufacturers with captive technical talent.
For Market Incumbents: Harden pharmacy channel control through exclusive shelf placement agreements with CVS and Walgreens to defend against direct-to-consumer subscription encroachment. Deepen backward integration into tea tree oil sourcing by acquiring Queensland agricultural partnerships, reducing exposure to Australian feedstock price volatility. For New Entrants and Emerging Players: Indian tier-two and tier-three cities present the most penetrable white-space for topical liquid and cream formats, where fragmented pharmacy networks lack national brand presence. Partner with regional distributors in Maharashtra and Gujarat to bypass metropolitan competition. Pursue asynchronous telehealth screening integrations with United States platforms to validate benign lesion status before product recommendation. For Investors and Strategic Acquirers: Korean contract manufacturers with sustained-release patch capacity represent the highest-conviction acquisition archetype, given their technical moats and direct-to-consumer brand relationships. Long-term viability hinges on regulatory pathway diversification across FDA OTC monographs, CE marking under EU MDR, and MFDS cosmetic classifications. Watch for EPA propellant restriction tightening as the inflection signal for pump-dispensed format acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR reclassification opens dermatology clinic channels for cryogenic applicators. |
| Backward Integration | Captive tea tree oil sourcing insulates margins from Australian feedstock volatility. |
| Direct-to-Consumer Launch | Subscription replenishment models lock recurring revenue away from pharmacy retailers. |
| Hospital System Partnership | United States clinic networks add express removal appointments to capture retail-diverted patients. |
| Software Companion Development | AI-powered lesion classification virtualizes diagnostic steps for at-home user triage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic procurement managers, cosmetic formulation chemists, pharmacy category buyers, and direct-to-consumer brand operations leads. Secondary validation drew from FDA OTC monograph filings, EPA volatile organic compound test reports, MFDS cosmetic registration databases, and customs trade records for tea tree oil and salicylic acid feedstocks. Bottom-up unit demand estimates and top-down market sizing were triangulated to reconcile channel-specific volume figures.
Calibration against historical FDA approval timelines and patch manufacturing capacity expansions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, form, customer type, and distribution channel, with additional granularity on regulatory pathway complexity. CAGRs were derived from trend extrapolation of clinic service adoption rates and direct-to-consumer subscription growth patterns. Forecast inputs incorporated ISO 13485 certification lag times and cold chain logistics cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cryogenic device specialists or telehealth platform integrators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Global Health and Wellness Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
OTC Health Products Market
Personal Health
Jet Lag Therapy Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Corporate Wellness Market
Personal Health
Sleeping Aids Market
Personal Health
Sleep Mask Market
Personal Health
Workplace Wellness Market
Personal Health
Infrared Sauna Blankets Market
Personal Health
Global Weight Loss Services Market
Personal Health
North America Workplace Wellness Market
Personal Health
Feminine Hygiene Market