
 Global Weight Loss Services Market | 2026-2036
Global Weight Loss Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Weight Loss Services Market Intelligence
Corporate wellness budgets is decoupling from traditional gym memberships toward structured weight management programs. Herbalife Nutrition leverages its direct-selling infrastructure to sustain distributor-driven penetration across Latin American and Asian markets. Noom Inc. differentiates through behavioral psychology integration, while Johnson Health Tech anchors hardware-software connectivity in commercial fitness settings.
Weight loss services encompass professionally delivered interventions combining nutritional guidance, physical activity programming, behavioral modification, and clinical oversight to reduce adiposity and improve metabolic health outcomes. These services operate through calibrated energy-deficit protocols, biometric tracking systems, and personalized coaching cadences designed to achieve sustained body composition change. Medical weight management and behavioral therapy command premium positioning as payers expand coverage for obesity as a chronic disease, while telehealth platforms capture the fastest expansion as asynchronous coaching models reduce per-session delivery costs. Fitness coaching remains mature with high fragmentation, though margin pools concentrate in subscription-based digital programs with automated content delivery.
FDA oversight of anti-obesity medications and HIPAA privacy requirements shape service integration with pharmacotherapy in the United States, while the EU Green Deal's workplace health initiatives and GDPR constraints on health data processing influence European program architecture. Stakeholders must monitor reimbursement coding evolution and digital therapeutics approval pathways to align service design with emerging payment mechanisms.
Market Dynamics
Telehealth parity legislation and digital therapeutics reimbursement frameworks are compressing delivery costs while expanding covered patient populations, fundamentally restructuring how weight management services reach end-users.
Growth Catalysts
- Employer wellness mandates:Large self-insured employers in the United States are expanding coverage for obesity as a chronic disease, channeling procurement toward structured clinical programs.
- HIPAA-aligned data infrastructure:Privacy-compliant biometric tracking systems enable seamless integration of continuous glucose monitors and wearable activity data into coaching protocols.
- Asynchronous coaching platforms:AI-augmented messaging and automated content delivery reduce per-session labor costs while maintaining engagement cadence.
Market Restraints
- Specialist workforce scarcity:Certified obesity medicine physicians and registered dietitians concentrate in urban United States markets, creating access deserts in rural and international regions.
- Pharmacotherapy integration friction:FDA scheduling requirements for GLP-1 agonists create prescribing barriers that delay service bundling with anti-obesity medications.
- Reimbursement coding lag:CMS and private payers maintain inconsistent coverage for behavioral weight management, forcing cash-pay models in many segments.
Strategic Opportunities
- Germany's DiGA pathway:The national digital health applications framework creates expedited reimbursement for evidence-based weight management software.
- Metabolic health convergence:Integration of sleep architecture monitoring and stress biomarker tracking is differentiating premium service tiers.
- Latin American distributor networks:Direct-selling infrastructure penetrates middle-income demographics underserved by clinic-based models.
Industry Challenges
- Behavioral credentialing bottlenecks:Health coaching certification programs lack standardization, creating quality variance and liability exposure.
- Legacy EHR interoperability:Weight management platforms struggle to exchange data with hospital system electronic health records, fragmenting care continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Weight Loss Services Market |
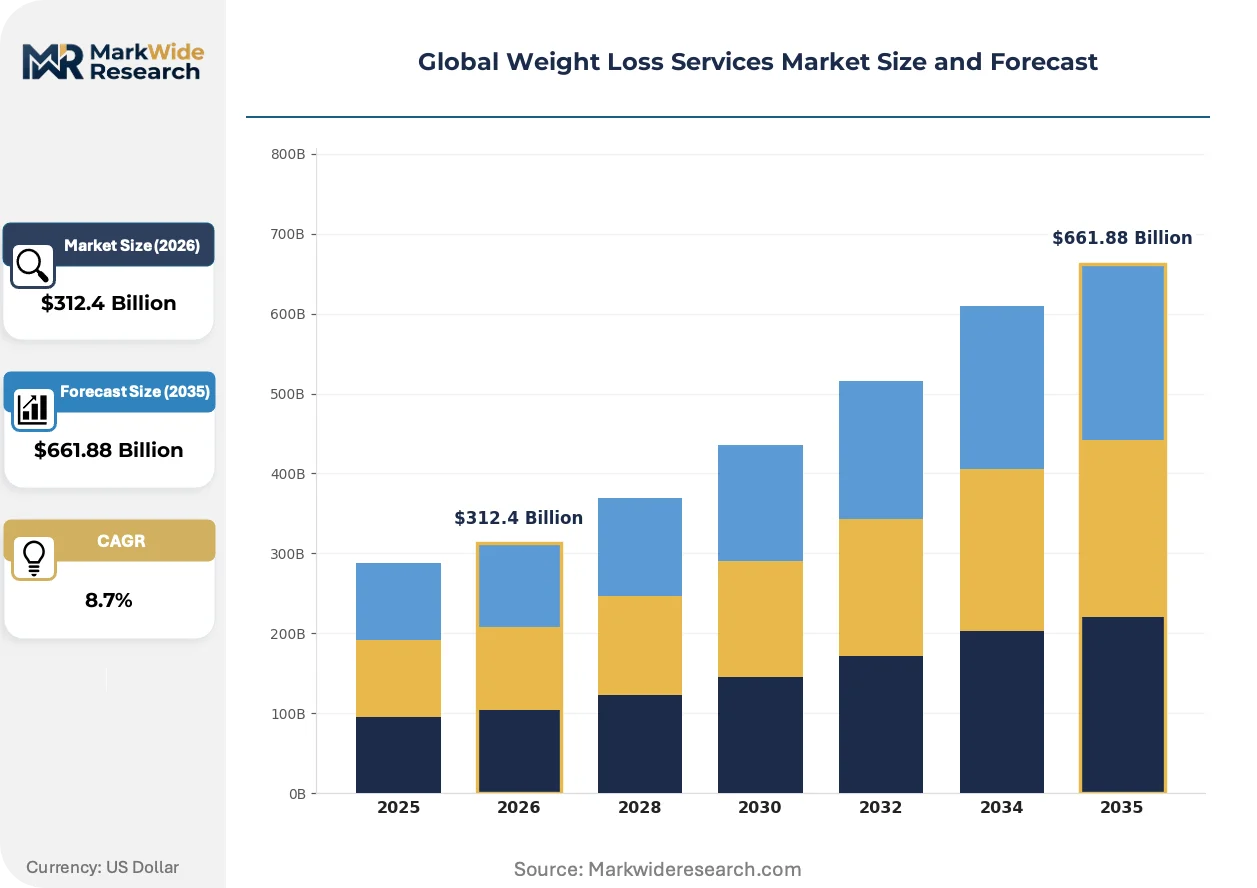
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $661.88 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diet Consultation, Fitness Coaching, Behavioral Therapy, Medical Weight Management, Surgical Intervention Client Type: Adults, Seniors, Adolescents, Postpartum Individuals, Corporate Employees Delivery Model: In-Person Clinics, Telehealth Platforms, Mobile Applications, Home-Based Programs, Corporate Wellness Programs Pricing Model: Subscription Plans, Pay-Per-Session, One-Time Packages, Freemium Models, Custom Pricing |
| Companies Covered | WW International, Herbalife Nutrition, Noom Inc., Nutrisystem, Slimming World, Atkins Nutritionals, Jenny Craig, Medifast, Johnson Health Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Weight Loss Services Market Strategic Shifts & Innovations
Continuous metabolic monitoring hardware and generative AI coaching interfaces are compressing the latency between biometric signal and behavioral intervention, reshaping service architecture across delivery modalities.
Continuous glucose monitoring patches paired with smartphone analytics is electrifying personalized nutrition programming. Self-insured employers and diabetes prevention program administrators are deploying these systems at scale. The technology is compressing the feedback loop between dietary intake and metabolic response, enabling real-time coaching adjustments previously impossible.
The EU AI Act's risk classification framework for health applications is mandating algorithmic transparency and human oversight protocols. Developers of automated coaching systems must document training data provenance and bias testing. European weight management platforms are responding by hybridizing AI-driven content with mandatory human escalation pathways.
Subscription unbundling is fragmenting traditional packaged programs into component services. Consumers increasingly purchase standalone nutrition counseling, fitness programming, and medication management from distinct providers. This pattern concentrates in the United States, where high-deductible health plans and health savings accounts incentivize price shopping across service categories.
Global Weight Loss Services Market Segmentation
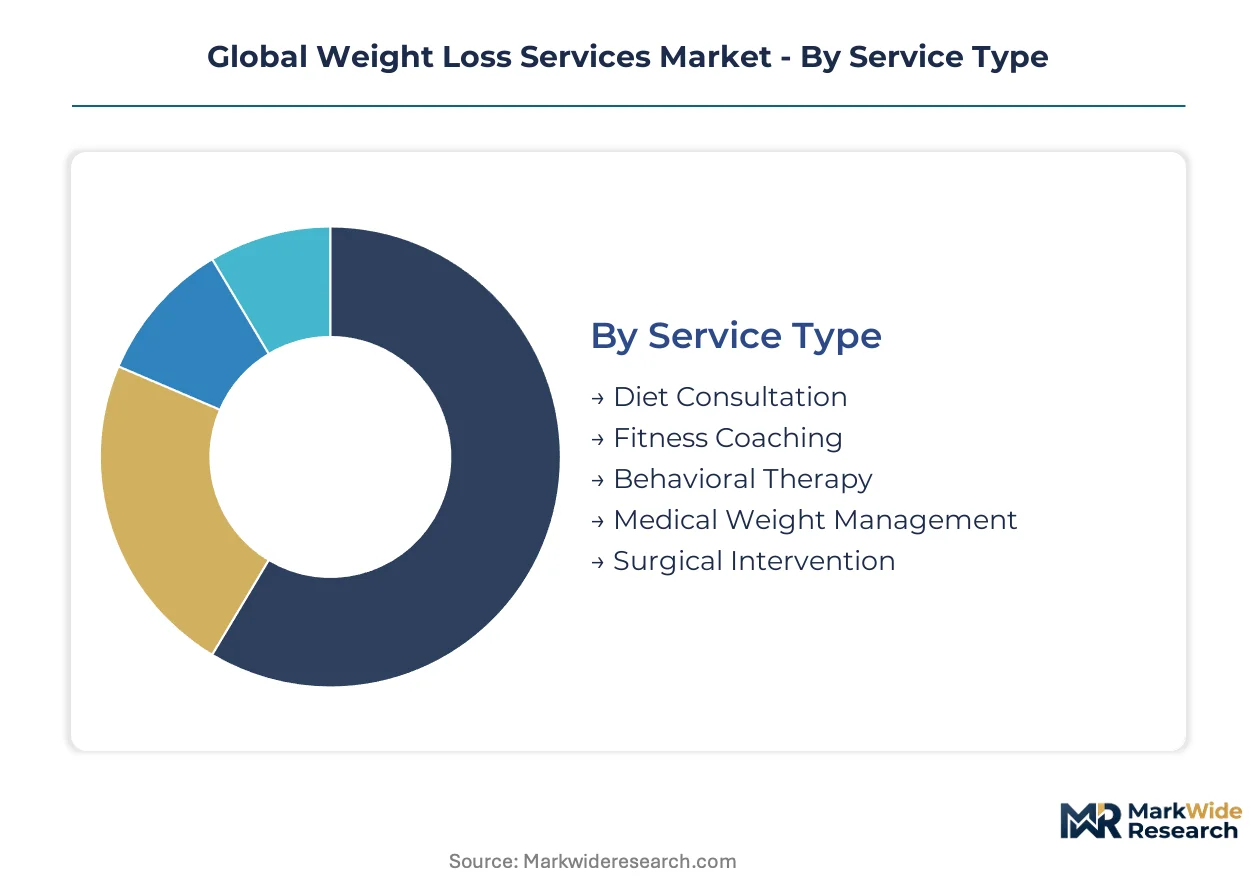
Service architecture in weight management diverges sharply across capital requirements and regulatory exposure. Segment selection determines reimbursement eligibility, workforce composition, and technology infrastructure needs.
Service Type:
Capital intensity peaks where clinical infrastructure and specialist credentialing create the highest barriers to entry.
- Medical Weight Management:Physician-supervised protocols integrate pharmacotherapy, metabolic testing, and chronic disease monitoring. Demand concentrates among self-insured employers in the United States seeking obesity-as-disease coverage under evolving CMS coding frameworks.
- Behavioral Therapy:Licensed psychologist and registered dietitian interventions target sustained habit formation through cognitive restructuring. Germany's DiGA reimbursement pathway accelerates platform adoption by mandating evidence standards that favor established clinical protocols.
- Diet Consultation:Registered nutritionist guidance on macronutrient calibration and meal planning dominates Latin American direct-selling channels.
- Fitness Coaching:Physical activity programming through personal trainers and group instruction retains high fragmentation with low certification standardization.
- Surgical Intervention:Bariatric procedures including gastric bypass and sleeve gastrectomy require hospital-based infrastructure and FDA device oversight.
Most installed capacity flows through Fitness Coaching. Expansion is steepest in Medical Weight Management.
Client Type:
Program design complexity escalates where comorbidity burden and physiological variability demand specialized protocols.
- Corporate Employees:Employer-sponsored wellness mandates channel procurement toward structured clinical programs with biometric tracking integration. United States self-insured plans drive volume through obesity-as-chronic-disease benefit expansion.
- Seniors:Medicare Advantage supplemental benefits cover behavioral weight management for metabolic syndrome prevention. Muscle preservation protocols differentiate programming from standard caloric restriction models.
- Adults:Working-age demographic with employer-sponsored coverage or health savings account purchasing power dominates cash-pay segments.
- Postpartum Individuals:Hormonal transition-focused programming addresses gestational weight retention with lactation-compatible nutrition planning.
- Adolescents:Pediatric endocrinology oversight requirements and family-based intervention models constrain service scalability.
Corporate Employees generate the highest per-capita revenue. Seniors are climbing the fastest as Medicare Advantage penetration deepens.
Delivery Model:
Technology infrastructure requirements separate capital-light coaching from platform-dependent asynchronous models.
- Telehealth Platforms:HIPAA-aligned video consultation and remote monitoring systems enable cross-state practitioner deployment. United States telehealth parity laws compress reimbursement gaps with in-person services.
- Mobile Applications:AI-augmented messaging and automated content delivery reduce marginal coaching costs while maintaining engagement cadence through push notification protocols.
- In-Person Clinics:Physical facility requirements and local specialist concentration create access deserts in rural United States markets and emerging economies.
- Corporate Wellness Programs:On-site programming and subsidized third-party platform access integrate with employer health benefit administration.
- Home-Based Programs:Kit-delivered meal replacements and wearable device pairing serve price-sensitive segments with limited clinic proximity.
In-Person Clinics retain the largest installed base. Mobile Applications are gaining share fastest through subscription unbundling trends.
Pricing Model:
Revenue predictability and customer acquisition economics vary dramatically across payment structure selection.
- Subscription Plans:Recurring revenue models with monthly or annual billing cycles dominate digital-native platforms. Annual prepay discounts improve cash flow and reduce churn exposure.
- Pay-Per-Session:Fee-for-service structures align clinician compensation with direct utilization but create demand volatility and administrative overhead.
- One-Time Packages:Fixed-duration program bundles with upfront payment concentrate in surgical preparation and intensive lifestyle intervention segments.
- Freemium Models:Basic tracking functionality with premium coaching tier upgrades drives user acquisition for mobile-first entrants.
- Custom Pricing:Enterprise contracts with self-insured employers negotiate per-employee-per-month rates with outcomes-based performance guarantees.
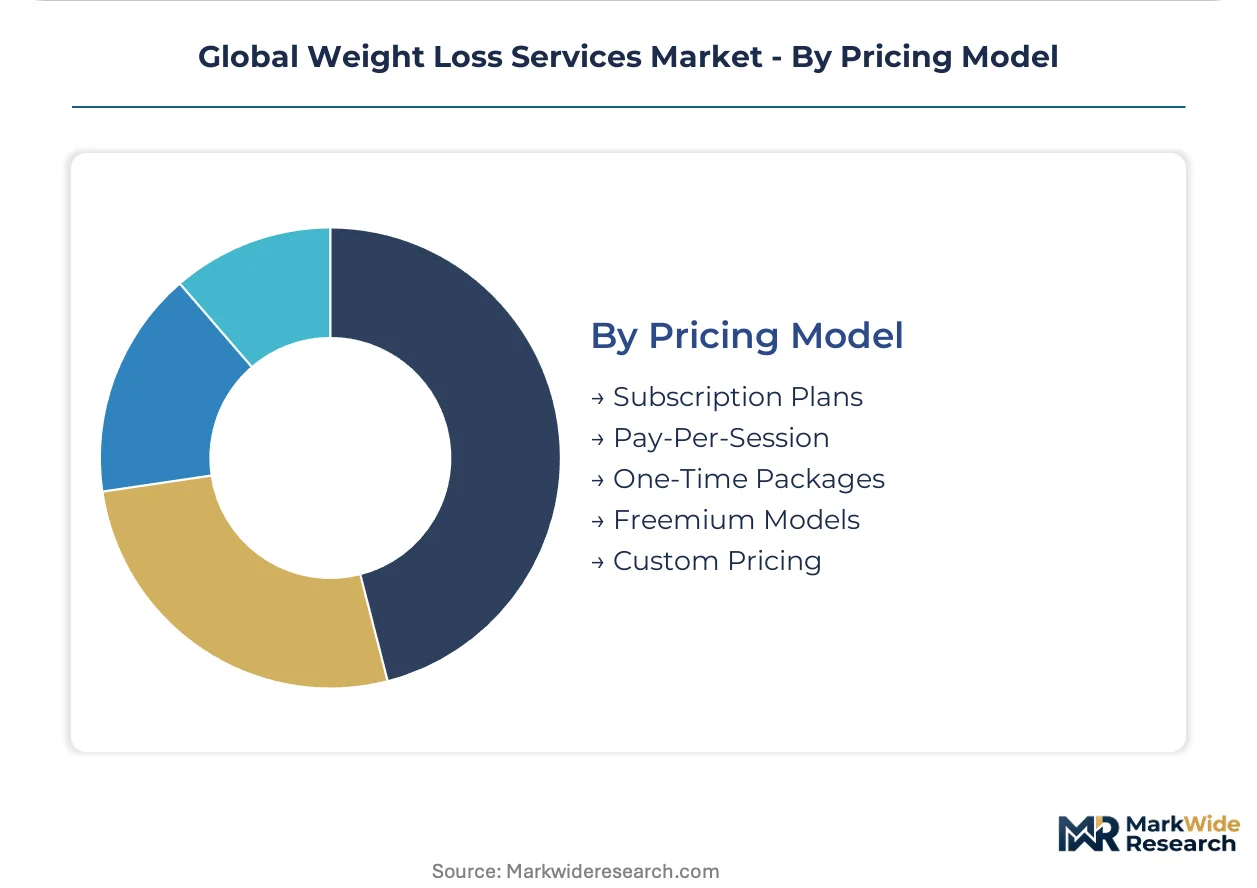
Subscription Plans capture the majority of recurring revenue. Custom Pricing is expanding most quickly as employer wellness procurement matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling weight loss service providers toward jurisdictions with favorable reimbursement frameworks and lower compliance costs. Germany's DiGA pathway and United States telehealth parity laws create distinct operational incentives that reshape geographic deployment strategies.
United States
Self-insured employers drive procurement volume through obesity-as-chronic-disease benefit expansion. HIPAA privacy requirements and FDA oversight of anti-obesity medications shape service integration with pharmacotherapy. The Boston-Cambridge corridor anchors medical weight management innovation, with academic medical centers piloting continuous glucose monitor integration into employer-sponsored programs.
Germany
The national DiGA framework accelerates platform adoption by mandating evidence standards that favor established clinical protocols. EU AI Act risk classification requirements enforce algorithmic transparency in automated coaching systems. Berlin-Brandenburg concentrates digital health startups developing hybrid AI-human weight management applications with mandatory escalation pathways.
United Kingdom
NHS England's diabetes prevention program procurement channels demand toward structured behavioral interventions. GDPR constraints on health data processing influence platform architecture for biometric tracking integration. London's digital health cluster hosts multiple telehealth platforms seeking MHRA compliance for EU market access post-Brexit.
Japan
Metabolic syndrome screening mandates in corporate health examinations sustain demand for structured weight management. PMDA oversight of digital therapeutics creates approval pathways for evidence-based coaching platforms. Tokyo-Osaka corridor concentrates wellness service providers targeting aging workforce demographics with muscle-preservation protocols.
Brazil
ANVISA regulation of medical devices and nutritional supplements shapes product-service bundling strategies. Direct-selling infrastructure penetrates middle-income demographics underserved by clinic-based models. São Paulo anchors distributor network headquarters for Latin American market coordination.
Global Weight Loss Services Market Key Industry Players
Strategic partnerships dominate the current landscape as incumbents seek technology capabilities and distribution reach. The vendor base segments across three tiers: integrated health platforms with clinical credentialing, direct-selling organizations with established distributor networks, and hardware-software hybrid providers with fitness equipment heritage. Two archetypes define positioning: behavioral psychology specialists leveraging asynchronous coaching models, and metabolic health integrators combining continuous monitoring with pharmacotherapy support. M&A activity concentrates on digital therapeutics capabilities and biometric data platforms.
Within the behavioral psychology tier, Noom Inc. exemplifies AI-augmented coaching architectures, while WW International occupies a position bridging community-based accountability with digital tracking tools. Johnson Health Tech anchors the hardware-software connectivity archetype, representing equipment manufacturers extending into subscription content delivery.
| Leading Market Players |
|---|
| WW International |
| Herbalife Nutrition |
| Noom Inc. |
| Nutrisystem |
| Slimming World |
| Atkins Nutritionals |
| Jenny Craig |
| Medifast |
| Johnson Health Tech |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up digital health platforms anchor supply-side consolidation in the United States and Germany, compressing customer acquisition costs while enforcing subscription pricing discipline across employer-sponsored channels. Their ownership structure rewards recurring revenue predictability, tightening margin tolerance for cash-pay behavioral therapy providers and independent dietetic practices.
Pricing Analysis
Distributor margins in Latin American direct-selling networks absorb 35-50% of end-user price, inflating retail premiums against telehealth platform economics. Three-tier pricing structure across premium, standard, and economy levels separates physician-supervised medical weight management from AI-augmented coaching subscriptions and unbundled fitness programming. Pricing pressure stems from CMS reimbursement coding lag forcing cash-pay models in behavioral segments. Corporate wellness buyers exhibit lowest price sensitivity; health savings account purchasers in high-deductible plans drive sharpest price shopping.
Supply Chain Analysis
Certification gating through HIPAA compliance, FDA device oversight, and Germany's BfArM DiGA evidence standards concentrates platform development in the United States, Germany, and United Kingdom. Continuous glucose monitor hardware draws from semiconductor fabrication in Taiwan and sensor assembly in South Korea and China. Single-source vulnerability runs through FDA-cleared glucose monitor suppliers. Distribution runs through employer benefits administration platforms and direct-to-consumer app stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's DiGA reimbursement pathway offers 18-month approval-to-payment velocity versus 3-4 year CMS coding cycles in the United States, creating a regulatory arbitrage window for digital therapeutic developers.
For Market Incumbents: Deepen vertical integration into continuous glucose monitor hardware supply through exclusive sensor partnerships, defending against unbundling trends fragmenting traditional packaged programs. Lock in employer wellness procurement through outcomes-based contracting with biometric performance guarantees. Priority lever: HIPAA-aligned data infrastructure investments that fragment care continuity for competitors lacking hospital EHR interoperability. For New Entrants and Emerging Players: Employer-sponsored wellness procurement channels in mid-market United States companies present the most penetrable white-space, as large self-insured plans concentrate incumbent attention. Latin American distributor networks offer second-tier entry through direct-selling infrastructure acquisition. Go-to-market angle: asynchronous coaching platforms with AI-augmented messaging reducing per-session labor costs below incumbent benchmarks. For Investors and Strategic Acquirers: Valuations sit cheapest among independent registered dietitian networks and cash-pay behavioral therapy clinics facing reimbursement coding lag pressure. Five-to-ten year viability hinges on telehealth parity law permanence and GLP-1 agonist prescribing integration. Signal to watch: CMS obesity-as-disease coding expansion triggering employer benefit redesign.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Pathway Entry | Expedited German reimbursement accelerates platform adoption versus United States coding delays. |
| GLP-1 Integration Partnership | FDA scheduling compliance enables service bundling with anti-obesity pharmacotherapy. |
| Continuous Glucose Monitor Pairing | Hardware-software connectivity compresses metabolic feedback loops for real-time coaching. |
| Employer Outcomes Contracting | Biometric performance guarantees secure multi-year wellness procurement commitments. |
| Latin American Distributor Acquisition | Direct-selling infrastructure penetrates middle-income demographics underserved by clinics. |
Research Approach
Multiple input streams — executive interviews with digital health platform CEOs and employer benefits directors, clinician surveys at academic medical centers, and secondary validation against FDA 510(k) filings and CMS Medicare data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed obesity medicine physicians, registered dietitians, telehealth operations leads, and self-insured employer procurement managers. Secondary sources included hospital procurement databases, GPO contracts, DiGA approval registries, and SEC filings of publicly traded wellness platforms.
Historical growth trajectories were cross-referenced against panel input from reimbursement strategists and regulatory affairs specialists. The forecast framework models across service type, delivery model, client demographic, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Key inputs included telehealth parity law adoption curves, GLP-1 agonist prescribing volume projections, and employer wellness benefit expansion rates.
The model assumes a particular technology adoption path; alternative pathways for generative AI coaching interfaces would alter the outlook if EU AI Act enforcement mandates heavier human oversight than baseline assumptions. Forecasts reflect reimbursement coding evolution and digital therapeutics approval velocity. A model refresh is warranted upon material change in CMS obesity-as-disease coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Biohacking Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Corporate Wellness Market
Personal Health
Jet Lag Therapy Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Reusable Face Mask Market
Personal Health
Menstrual Cup Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Medical Wellness Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Workplace Wellness Market
Personal Health
Sexual Wellness Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
Health Check-Up Market
Personal Health
Disposable Underwear Market
Personal Health
Obesity Treatment Market