
 Workplace Wellness Market | 2026-2036
Workplace Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Workplace Wellness Market Intelligence
Enterprise-grade biometric integration is redrawing competitive boundaries in workplace wellness. Virgin Pulse leverages connected-device ecosystems to sustain engagement across hybrid workforces. ComPsych anchors its position through behavioral health triage services that occupy a distinct tier above basic Employee Assistance Programs. Headspace Health differentiates via meditation-based stress interventions that compete directly with clinical mental health offerings.
Workplace wellness encompasses employer-sponsored programs designed to improve employee physical health, psychological resilience, and occupational performance through structured interventions, biometric monitoring, and behavioral coaching. These programs typically incorporate wearable-derived heart-rate variability data, validated psychometric assessments, and personalized coaching protocols to reduce absenteeism and medical claims expenditure. Health Coaching and Mental Health Workshops command the deepest margin pools as employers seek measurable ROI on stress-related disability costs. Wearable Devices and Telehealth Solutions represent the fastest-expanding technology segments as real-time biometric feedback becomes standard in self-funded health plans.
OSHA workplace mental health guidelines, the US Equal Employment Opportunity Commission wellness program incentive limits, and ISO 45003 psychological safety standards collectively shape program design and vendor liability exposure. The US Department of Labor enforcement posture on wellness program discrimination is forcing employers to rebalance participation incentives against privacy protections. Stakeholders must monitor how emerging state-level biometric privacy statutes alter data collection practices across multi-state employer deployments.
Market Dynamics
Biometric data integration is compressing program design cycles as employers demand real-time health metrics tied to insurance premium adjustments. This technological pull is restructuring vendor capabilities across the competitive landscape.
Growth Catalysts
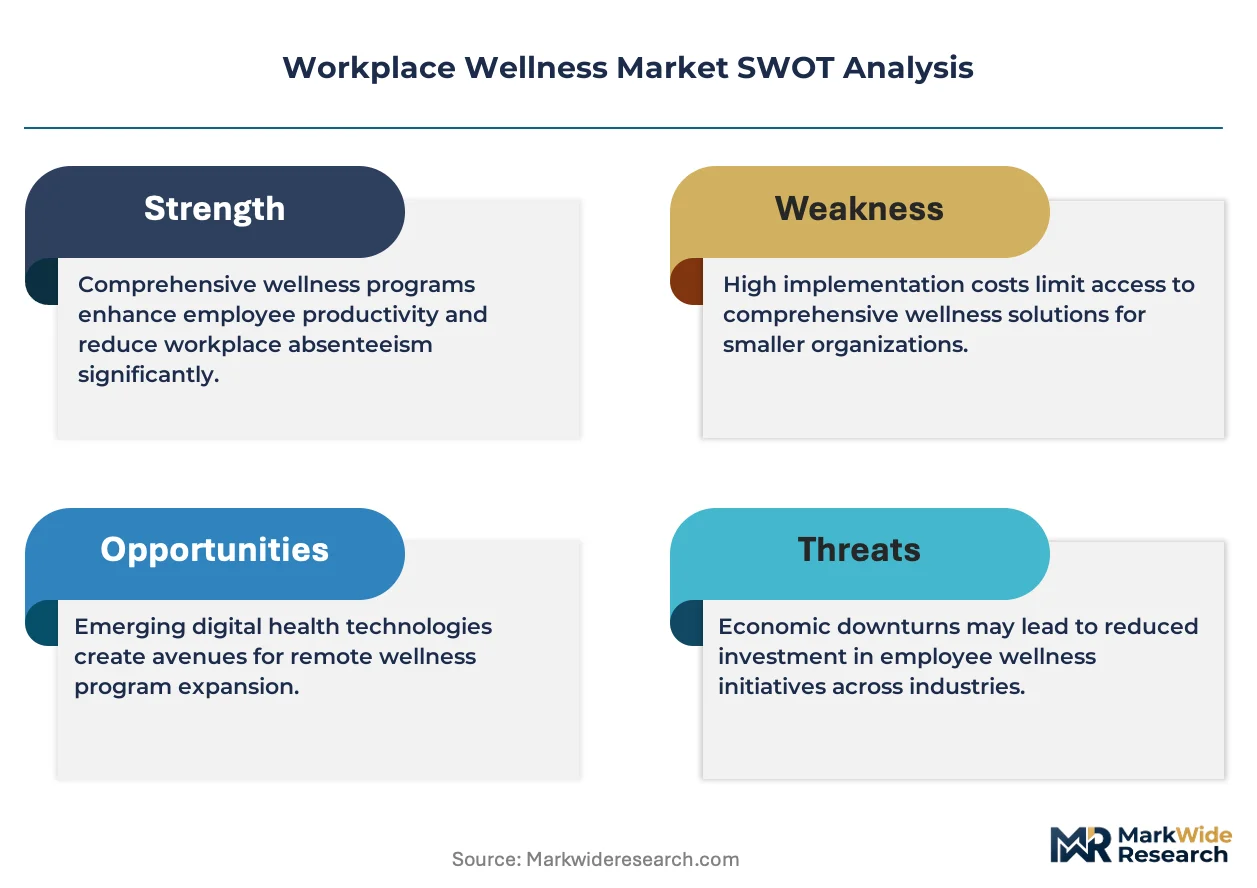
- OSHA mental health enforcement:The US Occupational Safety and Health Administration has elevated psychological safety to inspection priority status, compelling Fortune 500 employers to expand behavioral health budgets beyond traditional Employee Assistance Program baselines.
- Self-funded health plan expansion:Large technology employers with distributed workforces are directly contracting wellness vendors to capture claims data and reduce stop-loss premiums.
- Heart-rate variability monitoring:Wearable-derived physiological stress indicators are becoming standard inputs for personalized coaching protocols, creating measurable engagement hooks that basic wellness portals cannot replicate.
Market Restraints
- Biometric privacy statute fragmentation:Emerging state-level regulations in California, Illinois, and Texas impose conflicting consent requirements that complicate multi-state employer data collection architectures.
- Clinical validation gaps:Meditation-based stress interventions lack randomized trial evidence comparable to cognitive behavioral therapy, limiting reimbursement eligibility under self-funded plans.
- Vendor consolidation risk:Platform specialization in either physical health or mental health creates integration friction for employers seeking unified dashboards.
Strategic Opportunities
- ISO 45003 psychological safety standards:Early certification against this framework allows vendors to differentiate above basic compliance offerings in competitive RFPs.
- Telehealth-mental health convergence:Real-time biometric feedback paired with synchronous video coaching creates intervention intensity that asynchronous apps cannot match.
- Mid-market employer penetration:Self-insured employers with 500-5,000 employees remain underserved by enterprise-grade platforms designed for complex multi-site deployments.
Industry Challenges
- Behavioral health credential scarcity:Licensed clinical social workers and psychologists command premium compensation that compresses coaching margins at scale.
- Legacy HRIS integration complexity:Benefits administration systems from incumbent providers resist API-based data exchange, forcing costly custom development for unified reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workplace Wellness Market |
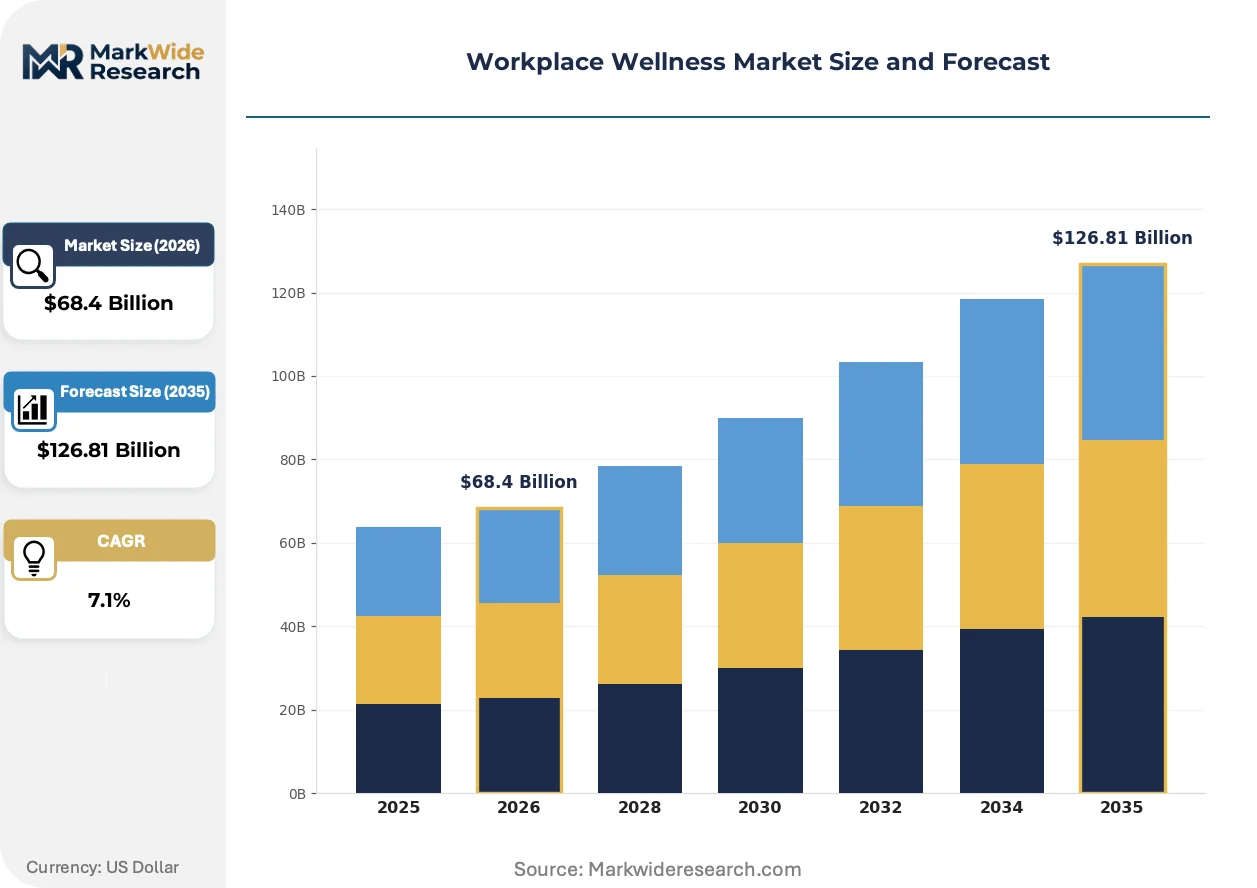
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $126.81 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Health Coaching, Fitness Programs, Mental Health Workshops, Nutritional Counseling Technology: Wearable Devices, Mobile Apps, Online Platforms, Telehealth Solutions Employee Demographics: Age Groups, Job Functions, Gender, Health Status Delivery Model: On-site Services, Remote Programs, Hybrid Approaches, Employee Assistance Programs |
| Companies Covered | Virgin Pulse, ComPsych, Personify Health, Vitality Group, EXOS, Welltok, Aduro, Limeade, Headspace Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workplace Wellness Market Strategic Shifts & Innovations
Real-time physiological monitoring is redefining intervention timing, shifting wellness from scheduled programming to ambient health management. This sensor-driven model is collapsing the distinction between clinical and subclinical support tiers.
Continuous glucose monitoring is fragmenting metabolic wellness offerings as employers pilot diabetes prevention programs using non-invasive biosensors. Technology sector self-insured plans are deploying these devices to pre-diabetic employees within ninety-day onboarding windows. The technology is fragmenting traditional health risk assessment models by replacing annual screenings with longitudinal metabolic tracking.
The US Equal Employment Opportunity Commission wellness program incentive limits are constraining participation rewards to thirty percent of health coverage costs. This ceiling is forcing employers to rebalance financial incentives toward non-monetary recognition and paid time off accruals. Self-funded plans in regulated industries are responding by segmenting incentive structures across job categories to maintain engagement without exceeding thresholds.
Chief Human Resource Officers are demanding outcome-based vendor contracts that tie fees to absenteeism reduction and medical claims savings. This procurement evolution is displacing per-employee-per-month pricing in competitive evaluations. Financial services and professional services employers with measurable disability cost exposure are driving this shift most aggressively.
Workplace Wellness Market Segmentation
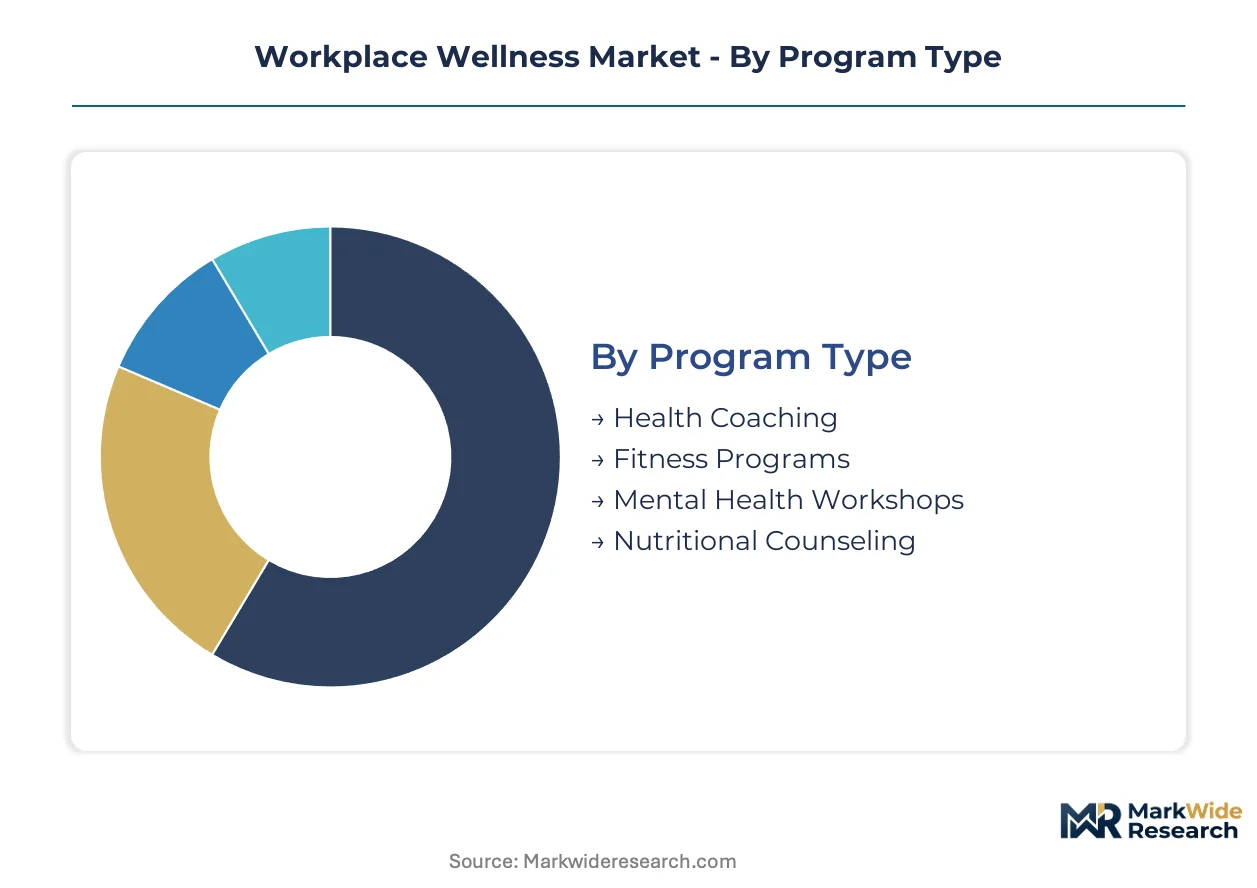
Employers structure wellness investments around measurable intervention outcomes and workforce accessibility. Segment boundaries shift as biometric monitoring collapses distinctions between clinical and preventive services.
Program Type:
Health Coaching faces substitution pressure from automated wellness portals that deliver generic lifestyle content at lower per-employee cost. Mental Health Workshops command premium positioning where OSHA psychological safety enforcement drives compliance budgets.
- Health Coaching:One-on-one behavioral protocols using biometric data inputs to personalize exercise and nutrition guidance. Fortune 500 technology employers with distributed workforces concentrate demand here as they seek claims reduction through sustained engagement.
- Mental Health Workshops:Structured group interventions addressing stress management, resilience training, and psychological safety compliance. Self-funded health plans in regulated industries expand procurement following elevated OSHA inspection priorities for workplace psychological hazards.
- Fitness Programs:Employer-subsidized gym memberships, on-site exercise facilities, and activity challenges tied to wearable-derived metrics.
- Nutritional Counseling:Registered dietitian consultations and meal-planning support, increasingly paired with continuous glucose monitoring for metabolic risk populations.
Health Coaching anchors the volume base while Mental Health Workshops gain share at the steepest rate.
Technology:
Cost tier stratification separates enterprise-grade biometric ecosystems from consumer wellness applications. Telehealth Solutions occupy the premium tier where synchronous clinical interaction justifies per-session pricing.
- Telehealth Solutions:Real-time video coaching platforms integrating heart-rate variability data for immediate intervention adjustment. Large self-insured employers with measurable disability cost exposure drive procurement as they replace asynchronous app subscriptions with clinically intensive alternatives.
- Wearable Devices:Employer-provisioned fitness trackers and smartwatches capturing physiological stress indicators for personalized protocol refinement. Technology sector distributed workforces standardize deployment across onboarding windows to establish longitudinal health baselines.
- Mobile Apps:Meditation and stress-management applications delivered through employer-sponsored subscriptions with usage-based engagement tracking.
- Online Platforms:Web-based wellness portals aggregating health risk assessments, educational content, and incentive program administration.
Wearable Devices dominate current deployment scale while Telehealth Solutions expand most quickly as employers demand synchronous clinical intensity.
Employee Demographics:
Application-driven segmentation aligns intervention intensity with occupational risk profiles and benefit eligibility tiers. Job Functions determine program access where self-funded plans segment offerings across exempt and non-exempt classifications.
- Job Functions:Sedentary knowledge workers receive ergonomic and metabolic interventions; frontline roles access injury-prevention protocols. Professional services employers with high-stress client-facing positions concentrate mental health workshop procurement.
- Health Status:Stratified programs for healthy populations, at-risk employees with pre-diabetic indicators, and chronic condition management cohorts. Continuous glucose monitoring pilots target pre-diabetic segments within ninety-day onboarding windows.
- Age Groups:Generational tailoring addresses retirement planning stress for older cohorts and financial wellness for early-career employees.
- Gender:Specialized maternal health support and men's health screening programs address differential risk profiles.
Job Functions structure the largest addressable base while Health Status segmentation climbs fastest as predictive analytics enable risk-stratified intervention targeting.
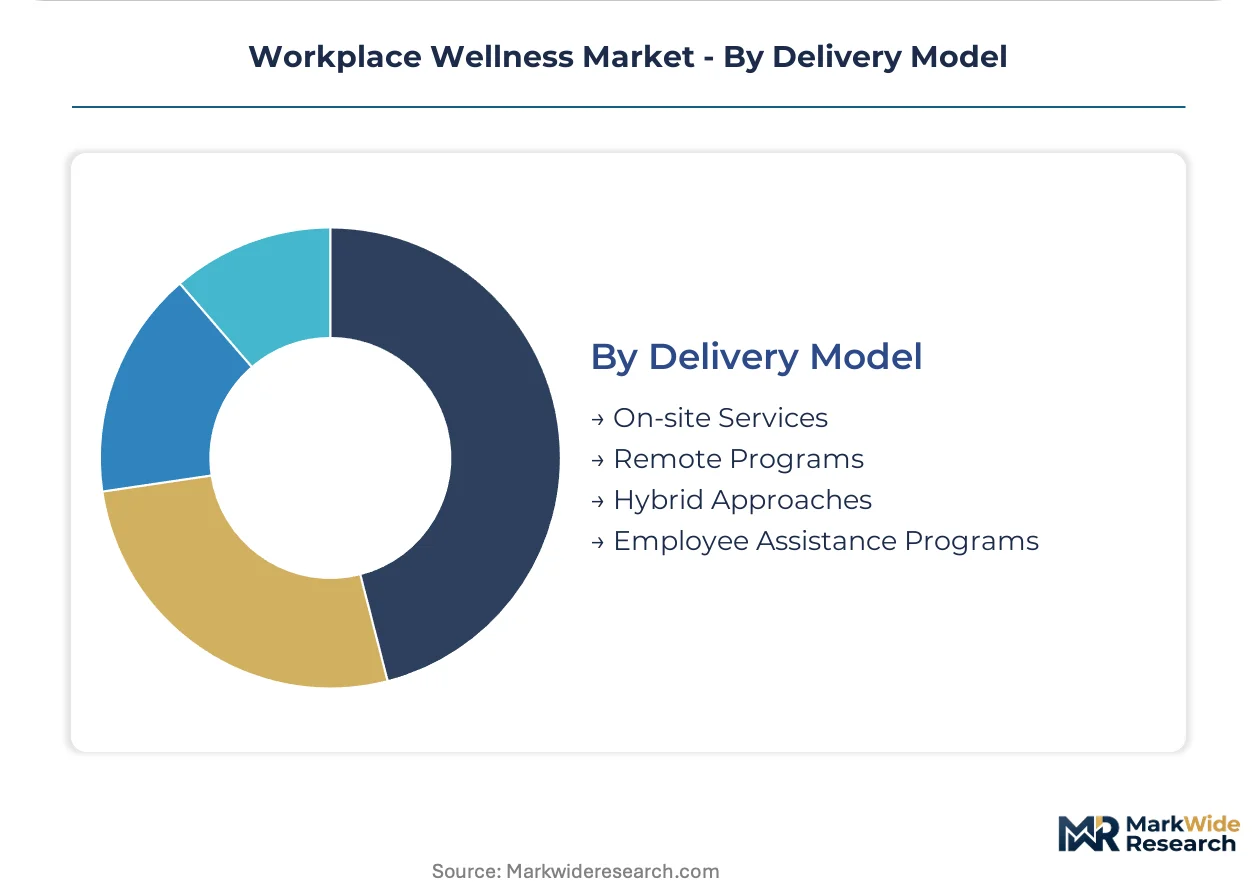
Delivery Model:
Customer-type concentration favors hybrid architectures that preserve on-site clinical presence while extending reach to distributed workforces. Remote Programs face margin compression from commodity video conferencing platforms.
- Hybrid Approaches:Blended delivery combining periodic on-site biometric screenings with continuous remote coaching access. Multi-site employers with headquarters-anchor and satellite-office structures standardize this model to balance engagement depth with geographic coverage.
- On-site Services:Embedded wellness staff, fitness centers, and clinical screening events at employer facilities. Healthcare systems and manufacturing campuses with concentrated headcounts sustain this capital-intensive model.
- Remote Programs:Fully distributed wellness services delivered through digital channels without physical employer presence.
- Employee Assistance Programs:Traditional telephone counseling and referral services, increasingly integrated with broader wellness platform architectures.
Hybrid Approaches capture the majority of new contract value while On-site Services retain share in healthcare and manufacturing verticals with campus-based workforces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor capability concentrates in the United States where enterprise procurement budgets and regulatory enforcement create the deepest market. Self-funded health plan expansion and OSHA psychological safety mandates pull solution development toward North American specifications.
United States
Fortune 500 technology employers with distributed workforces anchor demand through direct vendor contracting for biometric-integrated platforms. OSHA workplace mental health guidelines and EEOC wellness incentive limits reshape program design and liability exposure. San Francisco Bay Area and Seattle metropolitan clusters concentrate vendor headquarters and pilot deployments of continuous glucose monitoring for metabolic wellness.
Germany
Industrial employers with works councils negotiate integrated wellness architectures as co-determination requirements expand. ISO 45003 psychological safety standards and REACH chemical exposure protocols influence occupational health program specifications. Bavaria and Baden-Württemberg manufacturing corridors drive demand for ergonomic interventions and stress management protocols in automotive and machinery sectors.
United Kingdom
Financial services employers in London and Edinburgh prioritize mental health workshop procurement following regulatory scrutiny of workplace culture. GDPR biometric data restrictions and Financial Conduct Authority conduct standards constrain vendor data architectures. The Southeast England corridor concentrates professional services demand where disability cost exposure justifies premium coaching investments.
Japan
Metabolic syndrome screening mandates and aging workforce demographics expand employer-sponsored prevention programs. METI workplace health promotion guidelines and PMDA medical device classifications shape wearable deployment protocols. Tokyo-Osaka-Nagoya metropolitan corridors concentrate technology sector adoption of heart-rate variability monitoring for stress intervention.
Australia
Self-insured mining and professional services employers pilot telehealth-mental health convergence for remote workforce coverage. Safe Work Australia psychological health regulations and TGA medical device standards govern biometric data collection practices. New South Wales and Victoria financial services clusters drive outcome-based vendor contracting tied to absenteeism reduction metrics.
Workplace Wellness Market Key Industry Players
Concentration sits with integrated platform providers that bundle biometric hardware, coaching services, and compliance reporting. The vendor landscape stratifies across enterprise-grade full-stack solutions, specialized behavioral health triage services, and point-solution meditation applications. Three archetypes dominate: connected-device ecosystem orchestrators, clinical-intensity mental health specialists, and automated wellness portal operators. Competitive moves center on ISO 45003 certification races and outcome-based contract structures that displace per-employee-per-month pricing.
Among integrated platform specialists, Virgin Pulse and ComPsych occupy positions at opposite ends of the clinical intensity spectrum, while Headspace Health exemplifies the meditation-based intervention archetype competing for stress-management budgets. These three anchors represent the strategic tension between biometric data depth and behavioral health credential density that shapes procurement evaluations.
| Leading Market Players |
|---|
| Virgin Pulse |
| ComPsych |
| Personify Health |
| Vitality Group |
| EXOS |
| Welltok |
| Aduro |
| Limeade |
| Headspace Health |
| Others |
Cost & Logistics Intelligence
Outcome-based contracting locks in multi-year vendor relationships while capping price exposure for Fortune 500 employers seeking absenteeism reduction guarantees. This structure binds pricing visibility to biometric hardware deployment cycles and coaching credential availability across self-funded health plans.
Pricing Analysis
EEOC wellness incentive limits dictate the pricing tier structure by capping participation rewards at thirty percent of health coverage costs. Three-tier pricing structure across premium, standard, and economy levels separates enterprise biometric platforms from automated portals and basic EAP subscriptions. Cost compression in the mid-market tier is intensifying because behavioral health credential scarcity inflates coaching delivery costs. Self-insured employers with 500-5,000 employees exhibit highest price sensitivity, while regulated industries with measurable disability cost exposure accept premium positioning.
Supply Chain Analysis
Inventory lead times for wearable biometric sensors extend when semiconductor foundry capacity tightens, forcing wellness vendors to pre-position hardware stock ahead of employer onboarding windows. Hardware assembly concentrates in China, Taiwan, and Vietnam, while clinical coaching labor draws from US-licensed provider networks. Cloud infrastructure and API middleware rest on hyperscaler platforms with concentrated geographic availability zones. Single-source vulnerability sits with exclusive wearable OEM partnerships that lock vendors into specific sensor form factors. Distribution runs through direct enterprise sales teams and benefits broker channels serving multi-state employer deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward self-insured employers with distributed workforces as vendor consolidation reduces platform alternatives. Procurement concentration among Fortune 500 technology employers compresses margins for standardized offerings.
For Market Incumbents: Compound platform stickiness through ISO 45003 certification investments that raise compliance barriers for unqualified competitors. Deepen biometric data integration to capture heart-rate variability streams that automated portals cannot replicate. Defend against meditation-app substitution by demonstrating clinical outcome equivalence to cognitive behavioral therapy in employer RFP evaluations.
For New Entrants and Emerging Players: Differentiate on synchronous telehealth intensity paired with real-time physiological feedback, a combination that asynchronous apps cannot match. Target mid-market employers with 500-5,000 employees where enterprise platforms over-serve deployment complexity. Penetrate through benefits broker relationships that control vendor shortlist placement in competitive evaluations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platforms that bundle hardware, coaching, and compliance reporting into single contracts. Long-term viability hinges on outcome-based pricing adoption that aligns vendor economics with employer claims reduction. Acquisition targets should demonstrate biometric API depth and multi-state regulatory compliance infrastructure. Watch for OSHA psychological safety enforcement expansion as the signal indicating accelerated employer procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 45003 Certification Investment | Early certification against psychological safety standards differentiates vendors in competitive RFPs above basic compliance offerings. |
| Biometric-Telehealth Convergence | Real-time heart-rate variability data paired with synchronous video coaching creates intervention intensity that asynchronous apps cannot replicate. |
| Mid-Market Platform Simplification | Stripped-down deployments for 500-5,000 employee employers capture share from over-engineered enterprise solutions. |
| Outcome-Based Contract Structuring | Fees tied to absenteeism reduction and claims savings displace per-employee-per-month pricing in procurement evaluations. |
| Continuous Glucose Monitoring Integration | Non-invasive metabolic biosensors replace annual health risk assessments with longitudinal tracking for pre-diabetic cohorts. |
Research Approach
Cross-validation between primary interviews with CHROs, benefits directors, wellness platform CTOs, and licensed behavioral health providers anchors the qualitative findings. Secondary validation draws from SEC filings of self-insured employers, OSHA enforcement data, EEOC wellness program guidance, and ISO 45003 implementation documentation. Bottom-up triangulation of vendor contract values and top-down employer wellness expenditure estimates converge on segment sizing.
Sensitivity analysis across the projection horizon tests biometric adoption rates, coaching credential inflation, and regulatory enforcement intensity as key variables. Segmentation dimensions modeled include program type, technology tier, employee health status, and delivery model complexity. CAGRs derive from employer expenditure trajectory analysis and vendor revenue visibility across contract backlogs. Forecast inputs incorporate self-funded health plan expansion patterns and OSHA psychological safety inspection priority weighting.
Forecasts assume regulatory continuity in EEOC incentive limits and OSHA enforcement postures; material policy shifts would require re-modeling. State-level biometric privacy statute evolution and clinical validation requirements for meditation-based interventions represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
OTC Health Products Market
Personal Health
Menstrual Cup Market
Personal Health
Interdental Brush Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market
Personal Health
Tick Repellent Market
Personal Health
Feminine Hygiene Market
Personal Health
PTBCHA Market
Personal Health
Menopause Wellness Market
Personal Health
Biohacking Market
Personal Health
Infrared Sauna Blankets Market
Personal Health
Patient Health Management Market
Personal Health
Obesity Treatment Market
Personal Health
Foot Insole Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Sleeping Aids Market
Personal Health
Reusable Face Mask Market