
 Global Cosmetic Products Market | 2026-2036
Global Cosmetic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Products Market Analysis
The EU Green Deal is repositioning cosmetic formulation standards across the European supply base. L'Oréal S.A. leverages its integrated R&D network to reformulate portfolios ahead of REACH deadlines. Procter & Gamble anchors its competitive stance through scale manufacturing of biodegradable surfactant lines. Unilever PLC differentiates via its Living Beauty platform, which prioritizes waterless and concentrated delivery formats.
Cosmetic products encompass chemically formulated preparations applied to human skin, hair, or nails for cleansing, beautification, or protection, typically containing emulsifiers, preservatives, active ingredients, and fragrance compounds in regulated concentration limits. Skin Care commands the largest revenue pool due to premiumization in anti-aging serums and microbiome-targeted treatments, while Fragrance recovers fastest from pandemic-era demand suppression through direct-to-consumer sampling models. Online Retail reshapes margin distribution by compressing intermediary costs and enabling subscription-based replenishment cycles for Hair Care and Makeup categories.
FDA oversight in the United States governs cosmetic safety labeling and prohibits adulterated products under the Federal Food, Drug, and Cosmetic Act, while ECHA enforces REACH substance restrictions that ban or limit specific preservatives and colorants in European formulations. China's NMPA and GB standards mandate animal-testing alternatives and ingredient disclosure protocols that foreign entrants must satisfy for market access. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized or regionalized formulation strategies minimize compliance burden.
Market Dynamics
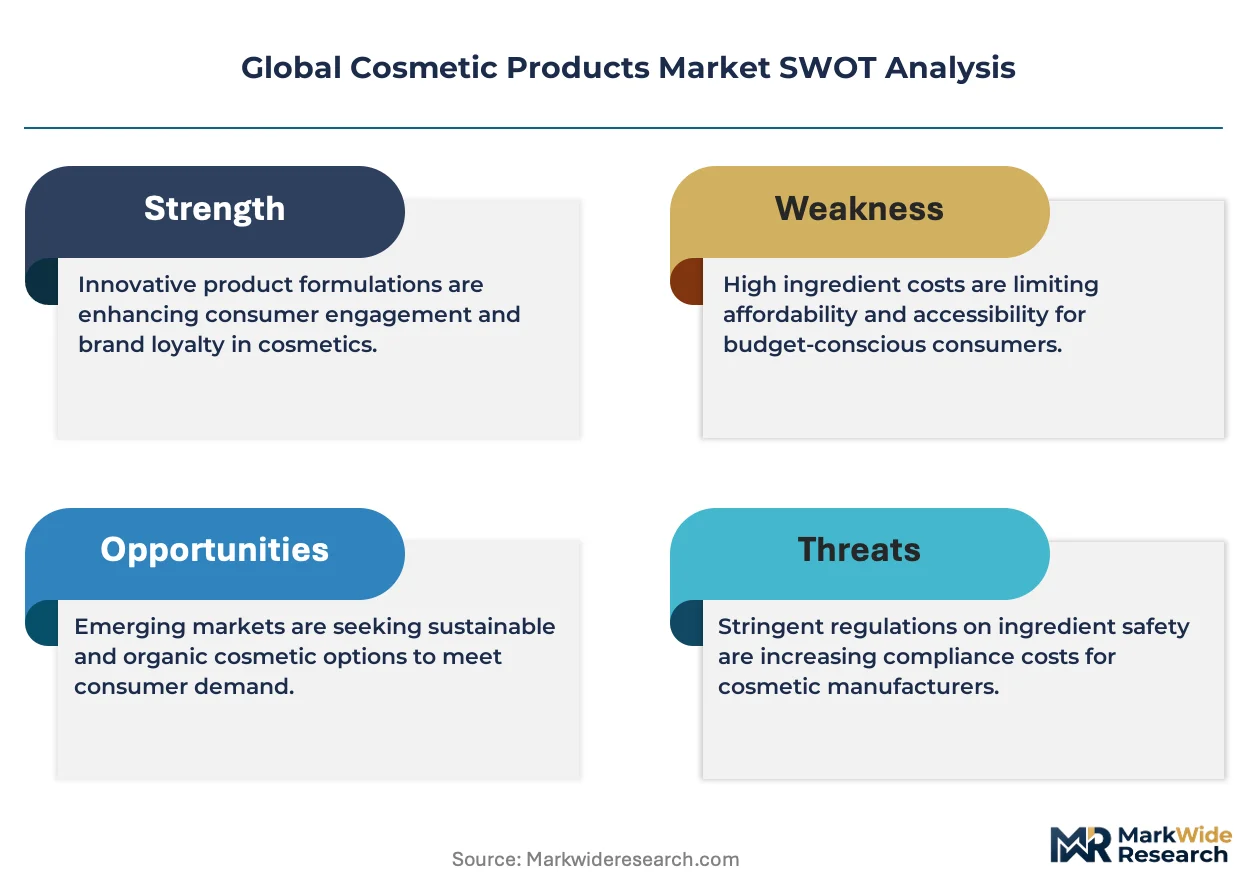
The EU Green Deal's REACH substance restrictions are forcing wholesale reformulation of preservative systems and colorant portfolios across European manufacturing bases, compressing R&D timelines while elevating compliance costs for cross-border suppliers.
Growth Catalysts
- Men's grooming normalization:Social stigma erosion in South Korea and Brazil expands addressable demand for male-targeted skin care and hair styling preparations.
- Biodegradable surfactant breakthroughs:Enzyme-based cleansing technologies from biotechnology suppliers enable palm-oil-free lathering systems that satisfy Ecolabel criteria.
- China's GB standard alignment:NMPA acceptance of animal-testing alternatives accelerates foreign brand entry into Shanghai and Beijing premium retail channels.
Market Restraints
- Petrochemical derivative volatility:Crude-linked feedstock costs for polyethylene glycol emulsifiers and synthetic fragrance precursors squeeze mid-tier manufacturer margins.
- Palm oil supply concentration:Indonesian and Malaysian plantation output disruptions propagate through fatty alcohol and glycerin derivative markets.
- Microbiome claim substantiation:Lack of standardized skin flora testing protocols limits marketing of probiotic-infused topical products in EU and US jurisdictions.
Strategic Opportunities
- India tier-two urbanization:Surat, Jaipur, and Lucknow retail expansion creates first-mover positioning for mass-market color cosmetics and hair oil portfolios.
- Waterless formulation platforms:Solid shampoo bars and anhydrous balm concentrates reduce shipping weights and plastic packaging loads for direct-to-consumer fulfillment.
- SAMR carbon labeling pilots:China's dual carbon goals drive provincial incentives for low-emission manufacturing certifications that differentiate export-ready suppliers.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with REACH-compliant substitution expertise command premium compensation in Basel and Rotterdam hiring markets.
- Legacy ERP integration:Batch record digitization for FDA cosmetic GMP compliance strains mid-cap manufacturers with on-premise MRP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Products Market |
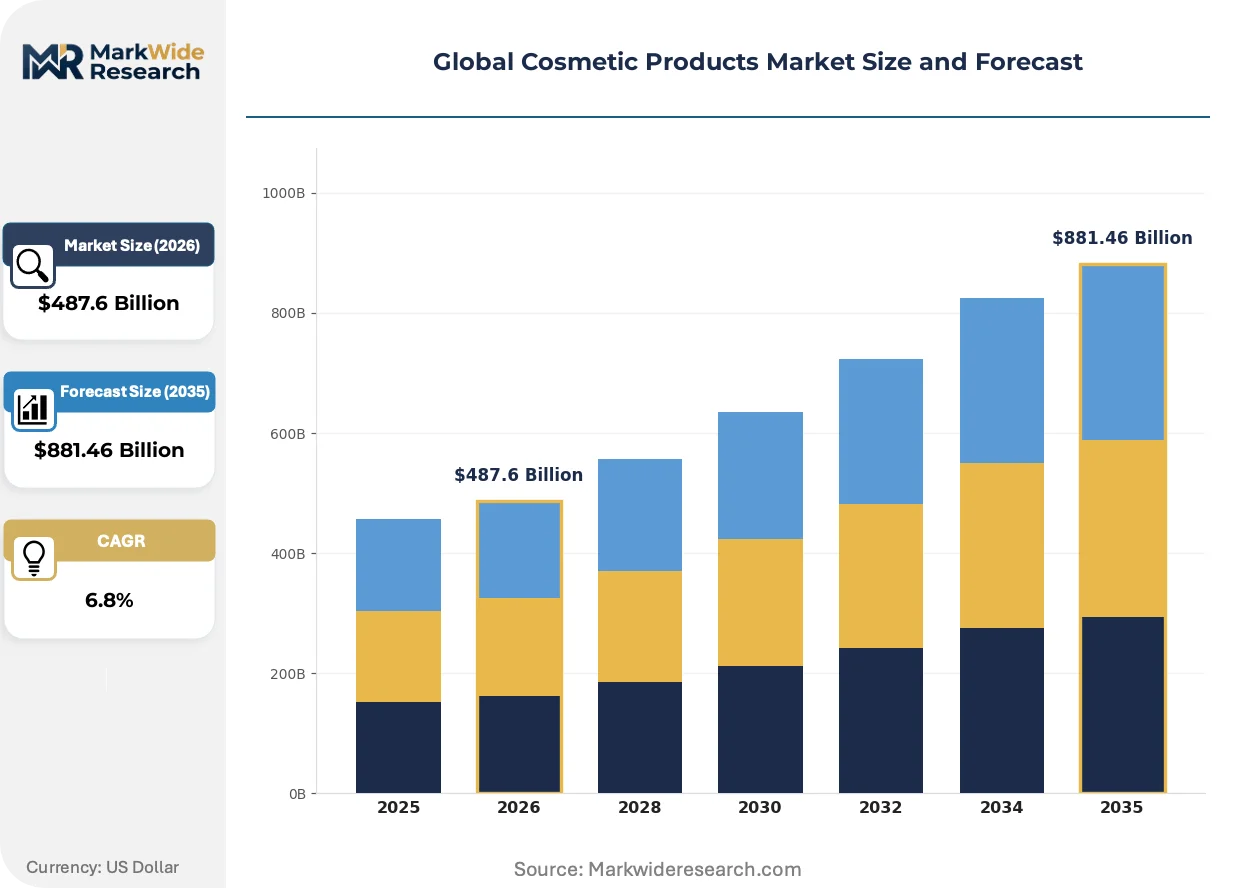
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Makeup, Fragrance End User: Women, Men, Unisex, Teens Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Packaging Type: Tubes, Jars, Pumps, Stick |
| Companies Covered | L'Oréal S.A., Procter & Gamble, The Estée Lauder Companies Inc., Unilever PLC, Shiseido Company Limited, Beiersdorf AG, Coty Inc., Kao Corporation, Revlon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Products Market Emerging Trajectories
Biotechnology-derived actives and artificial intelligence-enabled personalization engines are restructuring how cosmetic products are formulated, manufactured, and distributed to end consumers across premium and mass-market tiers.
Biotechnology fermentation platforms for collagen peptides and ceramide production are consolidating supply chains previously dependent on animal-derived or petrochemical sources. Premium skin care brands in Japan and France are adopting these bio-identical actives at accelerated procurement cycles. The technology is consolidating ingredient sourcing decisions around single-supplier partnerships with dedicated fermentation capacity.
REACH Annex XVII expansion to restrict additional UV filters and per- and polyfluoroalkyl substances compels sunscreen and long-wear makeup reformulation across European manufacturing. ECHA substance evaluation timelines compress product development windows to eighteen-month cycles. Color cosmetics with water-resistant claims face the steepest technical adaptation requirements as film-forming polymer alternatives undergo safety dossier reconstruction.
Subscription-based replenishment models for hair care and skin care categories are displacing traditional retail replenishment cycles in North American and British markets. Direct-to-consumer brands bypass wholesale margin structures through algorithmic consumption forecasting and automated shipping. Urban professional demographics in London, New York, and Toronto exhibit the highest adoption velocity for curated product assortments with personalized regimen sequencing.
Global Cosmetic Products Market Segmentation
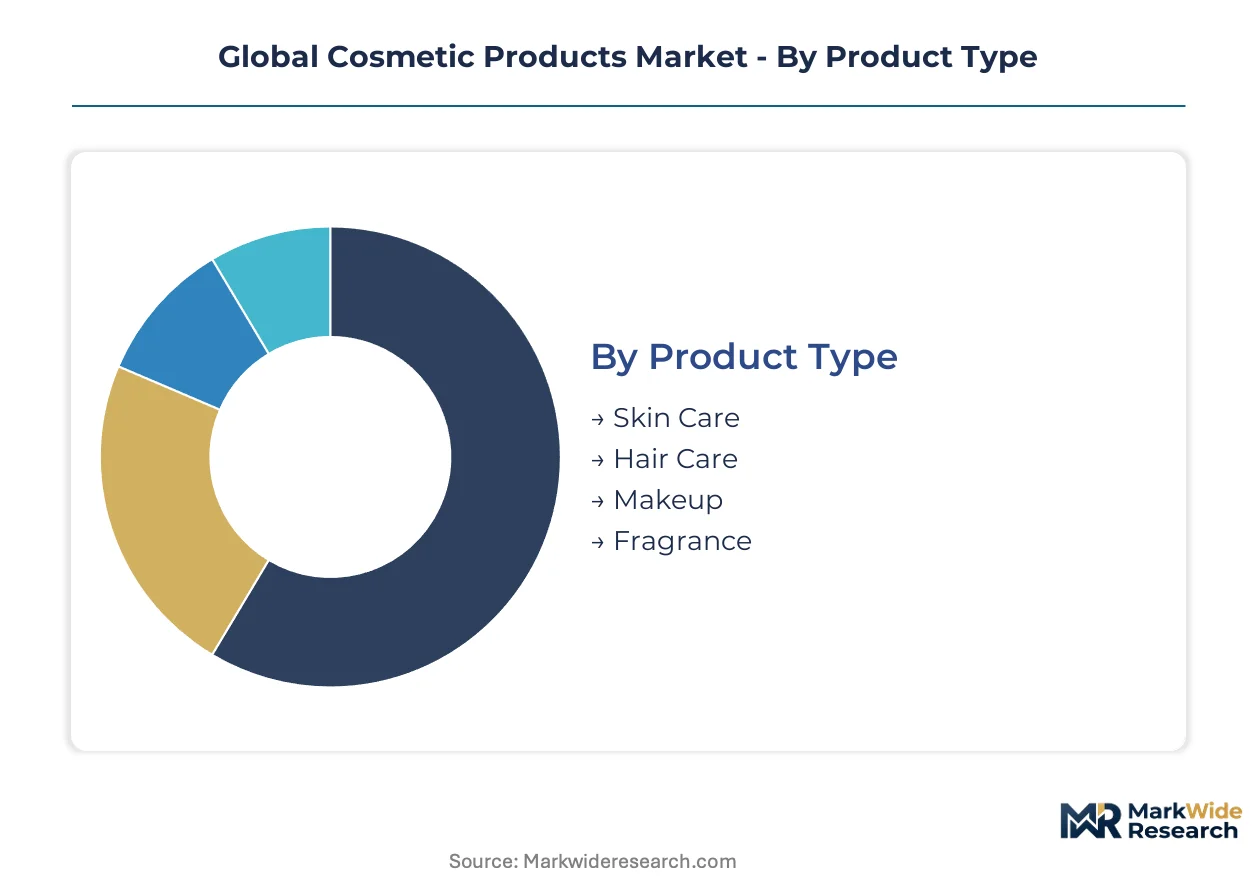
Segmentation in cosmetic products reveals how formulation complexity, channel economics, and demographic targeting create distinct competitive arenas. Each dimension carries unique margin profiles and regulatory exposure that reshape portfolio allocation decisions.
Product Type:
Upgrade cycles vary dramatically across cosmetic categories, with skin care commanding the shortest replacement intervals and fragrance exhibiting the longest inter-purchase gaps.
- Skin Care:Emulsion-based preparations with active concentrations regulated by FDA and ECHA thresholds. Anti-aging serums and microbiome-targeted treatments concentrate demand in China's tier-one cities and Japan's metropolitan corridors, driven by premiumization in dermocosmetic positioning.
- Hair Care:Surfactant systems with conditioning polymers and protein additives. Shampoo and conditioner replenishment accelerates through subscription models in North American direct-to-consumer channels, propelled by personalization algorithms that match scalp condition to ingredient profiles.
- Makeup:Pigment dispersions in cream, liquid, or powder matrices with film-forming polymers for wear longevity.
- Fragrance:Alcohol-based solutions with synthetic and natural aromatic compounds in regulated concentration limits.
Skin Care sits at the top of the volume ranking, with Fragrance climbing the fastest as direct-to-consumer sampling models recover post-pandemic demand suppression.
End User:
Cost tier differentiation separates mass-market accessibility from prestige positioning across user demographics.
- Women:The historical core demographic with established purchase frequency across all product categories. Brazilian and South Korean markets show particular concentration in multi-step skin care regimens.
- Men:Social stigma erosion in South Korea and Brazil expands addressable demand for male-targeted skin care and hair styling preparations.
- Unisex:Gender-neutral formulations with minimalist packaging and universal scent profiles designed for shared household consumption.
- Teens:Entry-priced color cosmetics and acne-targeted skin care with influencer-driven discovery patterns.
Women retains the largest absolute volume position, with Men gaining share fastest as grooming normalization penetrates developing markets.
Distribution Channel:
Channel selection directly determines margin capture and customer data ownership.
- Online Retail:Algorithmic personalization and subscription replenishment with compressed intermediary costs. North American and British urban professionals exhibit highest adoption velocity for curated assortments.
- Specialty Stores:Assisted selling environments with trained consultants and in-situ testing protocols. Concentrated in Paris, Milan, and New York luxury retail corridors.
- Supermarkets:High-velocity mass-market placement with promotional dependency and private-label competition.
- Pharmacies:Dermocosmetic and sensitive-skin positioning with pharmacist endorsement in German and French markets.
Online Retail leads volume expansion, with Specialty Stores maintaining the steepest margin structure.
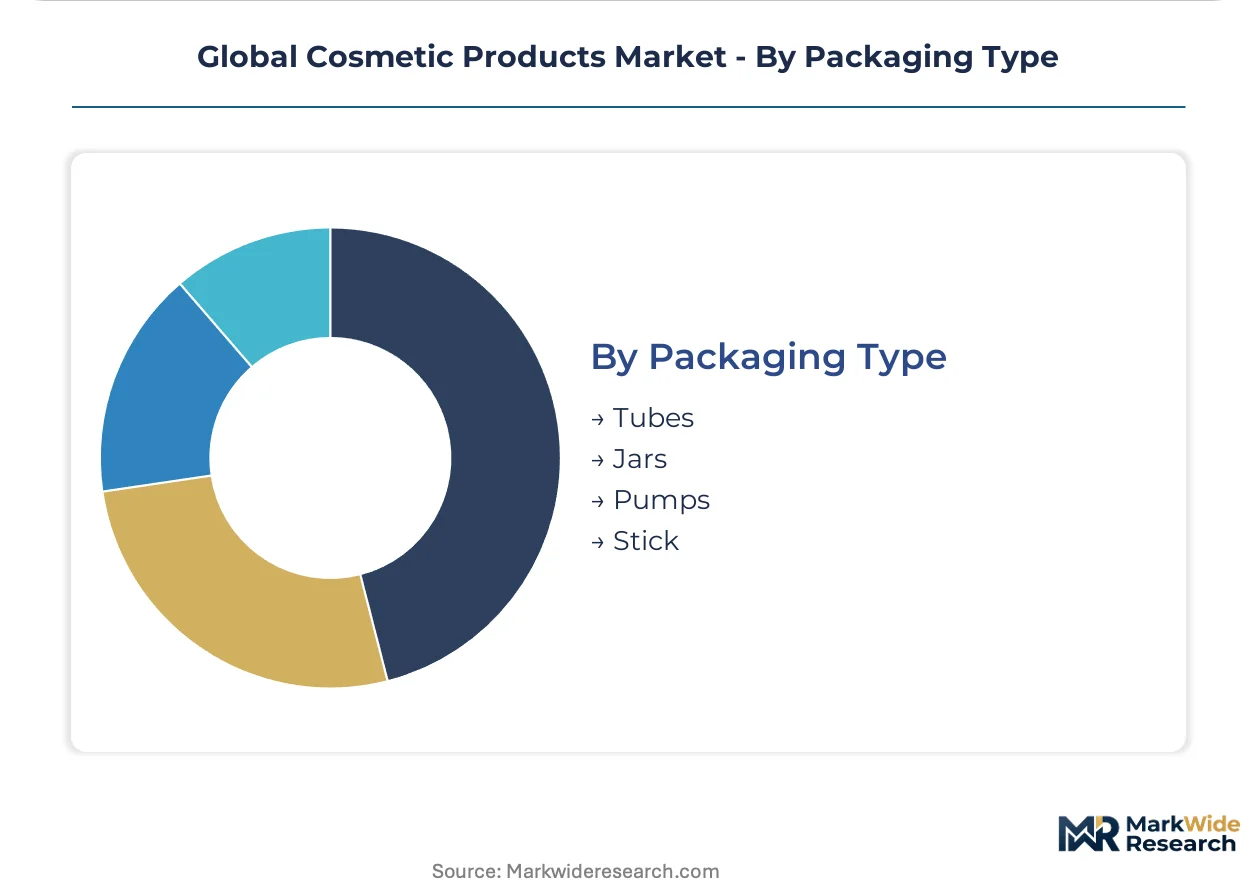
Packaging Type:
Packaging format selection balances formulation protection, dispensing precision, and sustainability credentials.
- Tubes:Collapsible aluminum or laminate structures for viscous creams and cleansers with controlled extrusion.
- Jars:Wide-mouth glass or polypropylene containers for balms and thick emulsions requiring finger application.
- Pumps:Metered-dose dispensing systems for lotions and serums with airless protection of oxidation-sensitive actives.
- Stick:Solid formats for deodorants, lip balms, and anhydrous concentrates with waterless formulation compatibility.
Pumps dominate premium skin care volume, with Stick formats expanding most quickly as waterless and concentrated delivery systems gain regulatory favor under EU Green Deal criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic chemistry scaled from European perfumeries in Grasse and pharmaceutical laboratories in Basel, establishing formulation science that now diffuses through manufacturing bases across three continents. Regulatory divergence between FDA, ECHA, and NMPA jurisdictions forces multinational portfolios into regionalized variants.
United States
Premium skin care demand concentrates in New York and Los Angeles metropolitan corridors, driven by dermatologist-endorsed dermocosmetic positioning. FDA cosmetic GMP compliance requirements under the Modernization of Cosmetics Regulation Act compel batch record digitization investments. Greater Boston hosts biotechnology fermentation startups supplying bio-identical ceramides to prestige brands.
China
Shanghai and Beijing tier-one cities accelerate premium beauty consumption through duty-free retail expansion and social commerce livestreaming. NMPA acceptance of animal-testing alternatives under GB standards enables foreign brand entry previously blocked by regulatory barriers. The Yangtze River Delta manufacturing cluster around Suzhou specializes in waterless formulation contract production for export markets.
Germany
Pharmacy-channel dermocosmetic sales anchor mass-market demand in Berlin and Munich, with pharmacist endorsement driving sensitive-skin positioning. ECHA REACH Annex XVII restrictions on UV filters and PFAS substances force eighteen-month reformulation cycles for sunscreen manufacturers. The Rhine-Ruhr industrial corridor houses concentrated surfactant production capacity serving biodegradable cleanser supply chains.
Japan
Multi-step skin care regimens sustain category depth in Tokyo and Osaka metropolitan markets, with microbiome-targeted treatments penetrating premium tiers. METI carbon labeling pilots under the GX League initiative differentiate low-emission manufacturing certifications. The Kansai region's Kobe pharmaceutical cluster integrates fermentation-derived collagen peptide production for domestic and export supply.
Brazil
Men's grooming normalization expands addressable demand in São Paulo and Rio de Janeiro, eroding historical social stigma around male-targeted skin care. ANVISA ingredient disclosure protocols align with Mercosur harmonization efforts for cross-border trade. The São Paulo state industrial belt concentrates hair oil and mass-market color cosmetics manufacturing for Latin American distribution.
Global Cosmetic Products Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across formulation, manufacturing, and distribution functions. The market structure consolidates around integrated multinationals with captive R&D networks, mid-tier regional specialists with flexible contract manufacturing, and direct-to-consumer insurgents with algorithmic personalization engines. Strategic archetypes separate scale-driven incumbents, biotechnology-forward innovators, and sustainability-positioned challengers. Dominant competitive moves include REACH-compliant reformulation acceleration and waterless format portfolio diversification.
Within the integrated multinational tier, L'Oréal S.A. and Unilever PLC exemplify archetypes of centralized R&D with regionalized manufacturing footprints. Procter & Gamble occupies a position at the scale-driven end with biodegradable surfactant line concentration. Among Japanese-origin specialists, Shiseido Company Limited and Kao Corporation sit within the biotechnology-forward cluster, representing fermentation-derived active integration. These named entities anchor competitive dynamics without exhausting the full participant set.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Procter & Gamble |
| The Estée Lauder Companies Inc. |
| Unilever PLC |
| Shiseido Company Limited |
| Beiersdorf AG |
| Coty Inc. |
| Kao Corporation |
| Revlon Inc. |
| Others |
Supply Flow & Price Mechanics
Biotechnology fermentation platforms for collagen peptides and ceramides are consolidating supply chains previously dependent on animal-derived or petrochemical sources, simultaneously elevating input costs for premium formulations while compressing margins for legacy surfactant-dependent mass-market portfolios. This production-method transition concentrates pricing power among dedicated fermentation capacity holders in Japan and France while forcing mid-tier manufacturers into commodity surfactant procurement exposed to palm oil volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates dermocosmetic positioning with pharmacist endorsement from mass-market supermarket placement and private-label competition. Price differentiation hinges on certification grade under ECHA REACH compliance and brand premium anchored in R&D heritage. Cost compression in the standard tier is intensifying because petrochemical derivative volatility squeezes polyethylene glycol emulsifier costs. Mass-market supermarket buyers exhibit highest price sensitivity, while specialty store dermocosmetic purchasers accept substantial premiums for microbiome-targeted treatments.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for finished goods fulfillment to retail channels. Manufacturing concentration rests on Germany, China, and Japan for surfactant production, fermentation-derived actives, and precision dispensing packaging respectively. Raw material dependencies draw from Indonesian and Malaysian palm oil plantations, Chinese glycerin derivative processors, and Swiss fragrance precursor specialists. Single-source vulnerability in Southeast Asian plantation output propagates through fatty alcohol markets. Distribution runs through direct-to-consumer subscription platforms and pharmacy-channel wholesalers in differentiated downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cosmetic products rests on waterless formulation adoption reducing shipping weights and packaging material costs, alongside premium-tier shift toward biotechnology-derived actives commanding dermocosmetic positioning premiums.
For Market Incumbents: Extend REACH-compliant reformulation timelines by consolidating R&D partnerships with Basel and Rotterdam green chemistry specialists ahead of Annex XVII expansions. Anchor capacity addition in China's Yangtze River Delta waterless formulation cluster to capture export-market regulatory favor under EU Green Deal criteria. Certification investment in SAMR carbon labeling protocols differentiates supply positioning for provincial incentive access.
For New Entrants and Emerging Players: Enter via algorithmic personalization engines targeting North American and British urban professional subscription replenishment, where incumbent wholesale margin structures create white-space opportunity. Focus penetration on solid shampoo bars and anhydrous balm concentrates as fastest-expanding packaging formats with regulatory tailwinds. Deploy direct-to-consumer sampling models for fragrance recovery post-pandemic demand suppression, bypassing traditional retail intermediary costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap contract manufacturers with legacy ERP systems strained by FDA cosmetic GMP batch record digitization requirements. Long-term viability across the analysis window favors biotechnology-forward innovators with captive fermentation capacity and REACH substitution expertise. Watch NMPA animal-testing alternative acceptance velocity as inflection indicator for foreign brand entry acceleration into Shanghai and Beijing premium retail channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterless Formulation Platform Launch | Solid shampoo bars and anhydrous concentrates reduce plastic packaging loads for direct-to-consumer fulfillment under EU Green Deal criteria. |
| Biotechnology Active Integration | Fermentation-derived collagen peptides consolidate supply chains away from petrochemical and animal-derived sources for premium skin care. |
| REACH-Compliant Reformulation Acceleration | Eighteen-month development cycles for sunscreen and long-wear color cosmetics adapt to ECHA UV filter and PFAS restrictions. |
| Direct-to-Consumer Channel Expansion | Algorithmic personalization engines bypass wholesale margin structures through subscription replenishment in North American and British markets. |
| Carbon Labeling Certification Investment | SAMR provincial incentives under China's dual carbon goals differentiate low-emission manufacturing for export-ready suppliers. |
Methodological Framework
Direct dialogue with brand managers, category buyers at retailers, channel sales heads, and supply planners grounded qualitative insights in operational realities across formulation, manufacturing, and distribution functions. Secondary validation drew from Nielsen retail audit data, customs records for surfactant and active ingredient trade flows, SEC filings for integrated multinational performance, and ECHA substance restriction announcements. Bottom-up procurement pattern analysis triangulated against top-down market sizing across product type, end user, distribution channel, and packaging format segmentation.
Bottom-up volume modeling tracked replenishment cycles by demographic cohort and channel economics, while top-down value estimates calibrated against disclosed revenue segments and regional production cluster output. Segmentation dimensions spanned skin care, hair care, makeup, and fragrance categories crossed with women's, men's, unisex, and teen end users, further split by online retail, specialty stores, supermarkets, and pharmacy channels. CAGRs were derived from trend extrapolation of premiumization velocity and regulatory compliance cost trajectories, with biotechnology adoption curves and REACH implementation timelines as industry-specific forecast inputs.
The model holds under steady ECHA enforcement timelines and NMPA regulatory alignment; deviation in EU Green Deal acceleration or China GB standard revision would shift reformulation investment schedules and market entry feasibility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Beauty and Personal Care Products Market
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
United Kingdom Cosmetics Products Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Powdered Hand Soap Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Facial Care Products Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Australia Facial Care Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
Lip Care Products Market
Beauty & Personal Care
Hairstyling Products Market