
 Hairstyling Products Market | 2026-2036
Hairstyling Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hairstyling Products Market Analytics
European contract manufacturing for aerosol-based hairstyling products is hardening as regional producers expand solvent-handling capacity. L'Oréal S.A. leverages its integrated fragrance and polymer labs to control formulation pipelines from raw material to finished goods. Henkel AG & Co. KGaA sustains manufacturing scale through concentrated production in Düsseldorf-area facilities serving EMEA salon channels. Kao Corporation anchors Asian supply with biopolymer research directed at humidity-resistant styling films.
Hairstyling products encompass aerosolized, emulsion, and gel-based formulations that employ film-forming polymers, hydrocarbon propellants, and conditioning agents to shape, hold, or texturize hair; these products serve consumer vanity and professional service revenue streams through performance claims measured by hold duration, humidity resistance, and removability. Hair Spray occupies the largest volume position due to universal salon adoption and retail familiarity, while Pomade generates disproportionate margin contribution from barbershop channels and male grooming specialization. Professional Use applications outpace Daily Use in value intensity because stylists purchase concentrated back-bar sizes and replenish on shorter cycles than household consumers.
REACH restricts volatile organic compound thresholds in aerosol propellant systems across European formulations, while FDA oversight governs cosmetic labeling and ingredient safety claims in United States commerce; EPA regulations further shape manufacturing site compliance for volatile solvent emissions in North American production facilities. Stakeholders must monitor polymer feedstock cost volatility and regional regulatory divergence when allocating R&D budgets between aerosol innovation and water-based alternative platforms.
Market Dynamics
Clean-label polymer chemistry is forcing rapid retooling of aerosol propellant systems as REACH and EU Green Deal mandates compress formulation timelines and redirect R&D budgets toward water-based alternatives.
Growth Catalysts
- REACH VOC Thresholds:European aerosol reformulation is accelerating solvent substitution research, pulling investment into hydrocarbon-free propellant platforms.
- K-Beauty Export Engine:South Korean humidity-resistant styling films are penetrating Southeast Asian salon channels, creating premium pricing benchmarks.
- Professional Salon Consolidation:Chain expansion in tier-two cities is standardizing back-bar procurement, concentrating volume with contract manufacturers offering formulation flexibility.
Market Restraints
- Petrochemical Feedstock Volatility:Film-forming polymer precursors fluctuate with ethylene and propylene spot markets, squeezing margin predictability for mid-tier producers.
- Aerosol Equipment Concentration:Solvent-handling line builders cluster in Northern Italy and Southern Germany, creating capacity bottlenecks for new market entrants.
- Silicone Substitution Limits:Clean-label claims face performance gaps where dimethicone alternatives fail to match thermal protection benchmarks in heat-styling applications.
Strategic Opportunities
- Barbershop Channel Specialization:Male grooming pomade demand in the United Kingdom and Australia outpaces mass-market growth, rewarding niche texture innovation.
- Biopolymer Film Research:Kao Corporation's humidity-resistant biopolymer patents are expanding into Southeast Asian licensing partnerships, opening regional production partnerships.
- EU Green Deal Incentives:Green chemistry R&D tax credits in France and Germany are offsetting reformulation costs for producers committing to carbon-neutral propellant timelines.
Industry Challenges
- Aerosol Formulation Expertise Gap:Solvent-propellant compatibility testing requires specialized chemists concentrated at legacy manufacturers, constraining talent mobility.
- Dual Certification Timelines:Simultaneous FDA cosmetic labeling and EPA volatile emission compliance for North American launches extends product development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hairstyling Products Market |
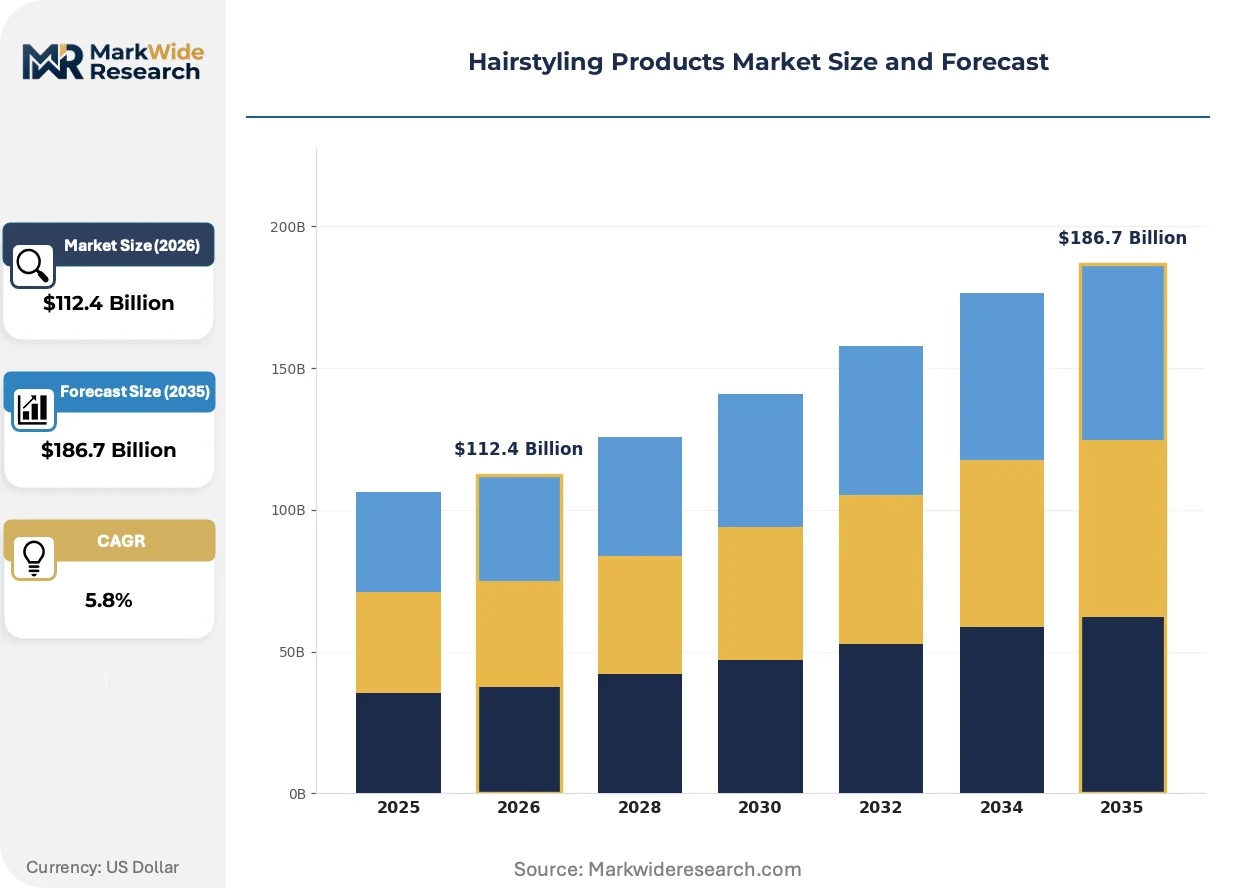
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Gel, Mousse, Hair Spray, Pomade Application: Daily Use, Professional Use, Special Occasions, Fashion Shows End User: Salons, Individual Consumers, Retailers, Online Shoppers Price Tier: Premium, Mid-Range, Budget, Value Packs |
| Companies Covered | L'Oréal S.A., Procter & Gamble, Unilever PLC, Henkel AG & Co. KGaA, Kao Corporation, Shiseido Company, Limited, Amorepacific Corp., Revlon, Inc., Mandom Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hairstyling Products Market Evolving Landscape
Water-based styling platforms are displacing hydrocarbon aerosols as the dominant innovation vector, with polymer chemistry and propellant engineering converging around clean-label performance claims.
Plant-derived film-forming polymers from corn starch and cellulose derivatives are expanding into professional salon back-bars, replacing synthetic acrylates in medium-hold applications. Stylists in Copenhagen and Amsterdam are piloting these formulations for clients with fragrance sensitivities. The technology is expanding into premium retail lines as sustainability credentials become non-negotiable in European purchasing decisions.
REACH Annex XVII restrictions on volatile organic compounds are tightening propellant specifications for aerosol hair sprays sold in Germany, France, and the Netherlands. Manufacturers are reformulating with compressed nitrogen and air-powered dispensing systems to maintain spray performance. Professional distributors in Düsseldorf and Rotterdam are phasing out legacy hydrocarbon stock ahead of enforcement deadlines.
Barbershop direct procurement is compressing traditional distributor margins as male grooming specialists in London and Sydney establish direct relationships with contract manufacturers. Pomade and clay formulations are bypassing wholesale channels through private-label arrangements. This pattern is most visible in Australia, where barbershop chain consolidation has concentrated purchasing power among thirty to forty independent operators.
Hairstyling Products Market Segmentation
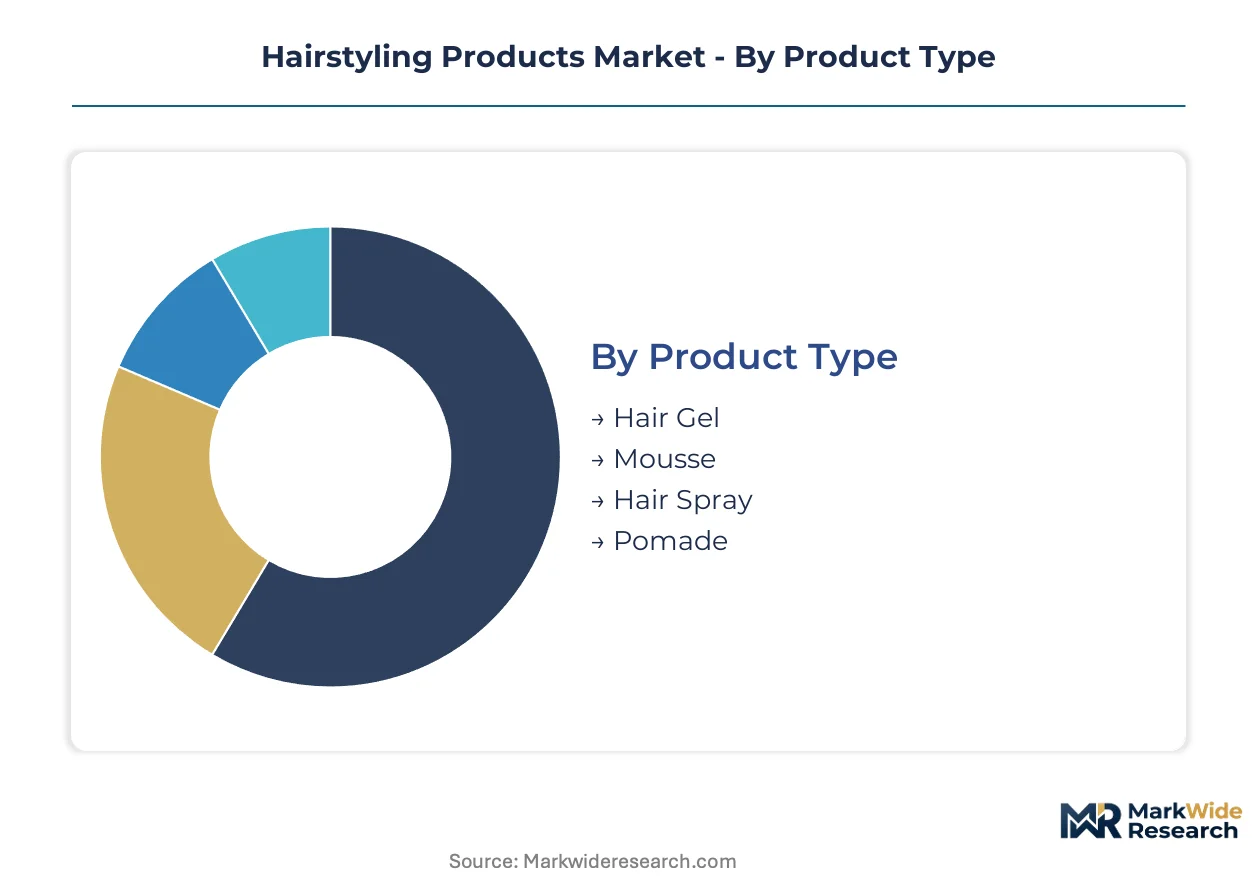
Hairstyling product purchasing patterns diverge sharply between volume-driven household replenishment and premium salon-grade procurement. Segmentation reveals how formulation chemistry, channel economics, and end-user expertise create distinct margin architectures across the value chain.
Product Type:
Volume leadership sits with aerosol formats while premium margin capture concentrates in texture-specialized formulations.
- Hair Spray:Aerosolized formulations employing film-forming polymers and hydrocarbon propellants deliver universal hold performance across humidity conditions. Salon adoption in Seoul and Los Angeles drives concentrated back-bar procurement, though REACH VOC thresholds are forcing accelerated reformulation investment.
- Pomade:Oil-based and water-soluble wax matrices provide reworkable hold for precision styling in barbershop environments. Male grooming specialists in London and Sydney are expanding direct procurement relationships, bypassing traditional wholesale channels.
- Hair Gel:Polyvinylpyrrolidone and carbomer-thickened aqueous systems dominate mass-market retail shelves.
- Mousse:Aerosolized foam delivery systems condition while adding volume for home styling routines.
Today's leader: Hair Spray. Tomorrow's challenger: Pomade.
Application:
Professional service revenue streams command value intensity multiples above household consumption through concentrated formulation requirements and shorter replenishment cycles.
- Professional Use:Stylists purchase concentrated back-bar sizes with performance specifications measured by hold duration and thermal protection benchmarks. Chain consolidation in tier-two cities is standardizing procurement around contract manufacturers offering formulation flexibility.
- Daily Use:Household consumers select from retail-facing SKUs with removability and fragrance profile as primary decision factors. Mass-market penetration in German drugstore channels sustains volume throughput for aerosol platforms.
- Special Occasions:Event-driven purchasing spikes around wedding seasons and holiday calendars in India and the Middle East.
- Fashion Shows:Runway styling demands extreme-hold formulations with instant reworkability for backstage conditions.
Professional Use commands the steepest expansion trajectory as salon chain consolidation concentrates purchasing power.
End User:
Channel intermediation is fragmenting as direct procurement relationships reshape traditional distribution economics.
- Salons:Licensed establishments purchase through professional distributors or direct contract manufacturing arrangements. Copenhagen and Amsterdam stylists are piloting plant-derived polymer formulations for fragrance-sensitive clients.
- Individual Consumers:Household purchasers select from mass-market retail and e-commerce platforms with sustainability credentials becoming non-negotiable in European purchasing decisions.
- Retailers:Drugstore and specialty beauty chains curate assortment based on clean-label claims and regional regulatory compliance.
- Online Shoppers:Direct-to-consumer platforms enable subscription replenishment and personalized texture matching.
Salons currently dominate value capture. Individual Consumers are gaining share fastest through premium e-commerce penetration.
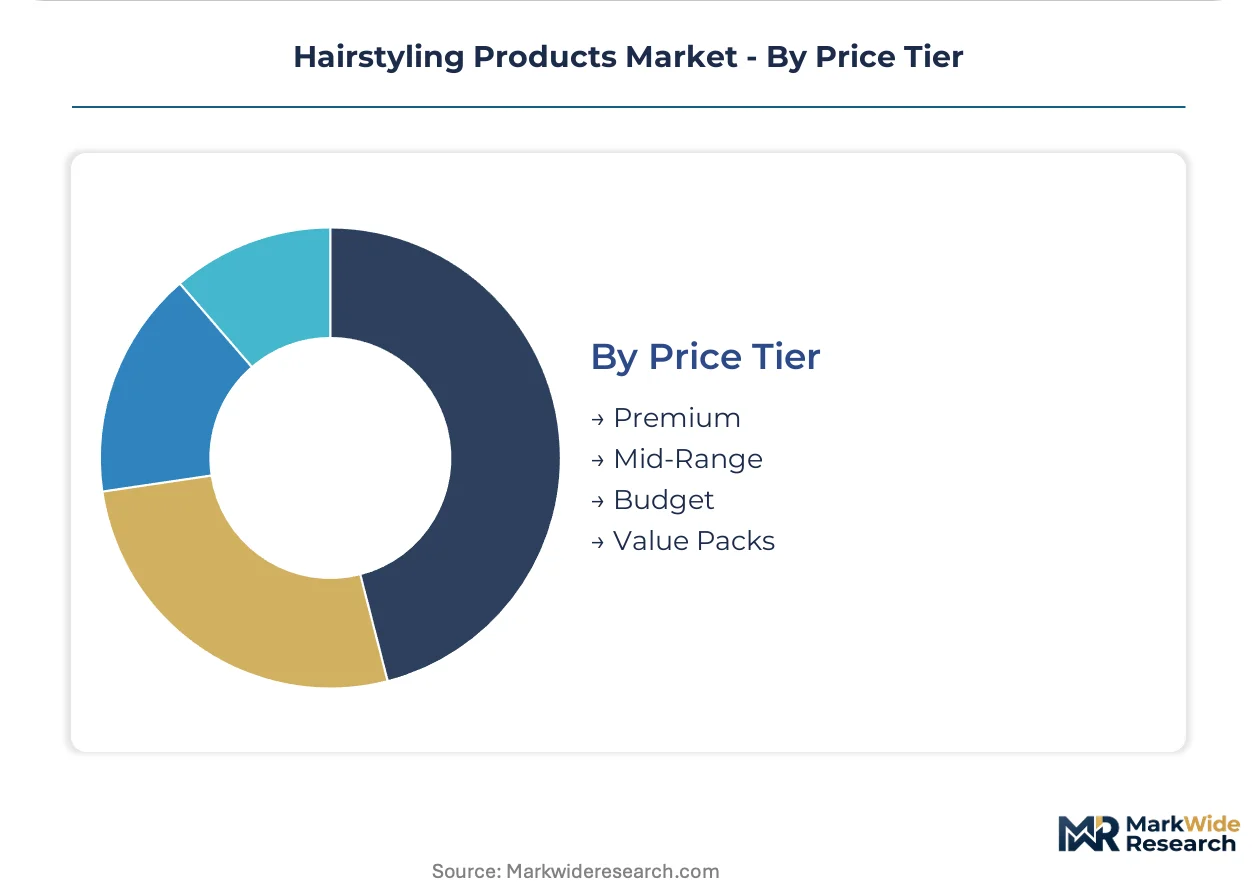
Price Tier:
Margin architecture stratifies across performance claims, ingredient provenance, and channel positioning rather than pure formulation cost.
- Premium:Biopolymer and plant-derived formulations command shelf space through sustainability certification and professional endorsement. Kao Corporation's humidity-resistant patents are expanding into Southeast Asian licensing partnerships.
- Mid-Range:Synthetic polymer platforms balance performance benchmarks with accessibility for mainstream salon and retail channels.
- Budget:Commodity formulations compete on unit economics in high-frequency replenishment markets.
- Value Packs:Multi-unit bundling reduces per-ounce cost for predictable consumption patterns.
Premium tier leads absolute margin contribution. Mid-Range faces compression as clean-label requirements elevate formulation costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea commands premium styling film innovation while Germany enforces the tightest aerosol reformulation deadlines under REACH Annex XVII amendments.
United States
Professional salon chains in Los Angeles and New York Metro are consolidating back-bar procurement around contract manufacturers with formulation flexibility. FDA cosmetic labeling requirements govern ingredient disclosure, while EPA volatile emission standards shape manufacturing site compliance for solvent-handling facilities. Houston-area production clusters are expanding water-based platform capacity to serve mass-market retail channels.
Germany
Düsseldorf-area facilities anchor European manufacturing scale for EMEA salon distribution, with concentrated production serving professional channels. REACH VOC thresholds are compressing formulation timelines and accelerating hydrocarbon-free propellant research. Professional distributors in Düsseldorf are phasing out legacy hydrocarbon stock ahead of enforcement deadlines.
South Korea
K-beauty hair trends drive premium styling product consumption, with humidity-resistant biopolymer films penetrating Southeast Asian salon channels. MFDS cosmetic safety standards govern ingredient registration and manufacturing practice certification. Seoul-based research labs are expanding into regional licensing partnerships for biopolymer patent portfolios.
United Kingdom
Barbershop direct procurement is compressing traditional distributor margins, with male grooming specialists in London establishing direct contract manufacturing relationships. UK cosmetic regulations align with REACH frameworks while maintaining separate MHRA notification requirements for novel ingredients. Birmingham manufacturing clusters are retooling for water-soluble pomade and clay formulations.
Australia
Barbershop chain consolidation has concentrated purchasing power among thirty to forty independent operators, bypassing wholesale channels through private-label arrangements. TGA cosmetic ingredient standards and ACCC consumer protection frameworks govern product claims and labeling. Sydney and Melbourne distribution hubs are expanding direct-to-barbershop logistics infrastructure.
Hairstyling Products Market Competitive Landscape
European producers anchor one tier; Asian specialists hold premium biopolymer innovation capacity. The vendor base stratifies across integrated fragrance-polymer laboratories, concentrated regional manufacturing facilities, and contract formulation specialists. Three archetypes dominate: multinational conglomerates with captive R&D infrastructure, regional scale producers serving EMEA salon channels, and niche biopolymer patent holders licensing technology into Southeast Asian partnerships. Competitive moves concentrate on aerosol reformulation partnerships and direct barbershop channel bypass strategies.
Within the integrated conglomerate tier, L'Oréal S.A. and Henkel AG & Co. KGaA exemplify European anchoring positions through captive laboratory and manufacturing infrastructure. Kao Corporation occupies a distinct position representing Asian biopolymer research specialization, with patent portfolios directed at humidity-resistant styling films. These three entities collectively illustrate the geographic split between European manufacturing scale and Asian formulation innovation.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Procter & Gamble |
| Unilever PLC |
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Shiseido Company, Limited |
| Amorepacific Corp. |
| Revlon, Inc. |
| Mandom Corporation |
| Others |
Value Network & Pricing Analysis
Professional salon chain consolidation in tier-two cities concentrates purchasing power with contract manufacturers, shifting pricing leverage toward volume-based contract structures that reward formulation flexibility and shorter replenishment cycles over spot-market transactions.
Pricing Analysis
Capacity additions in Germany and South Korea are reshaping price floors for biopolymer-based formulations as regional producers expand solvent-handling and film-forming polymer capacity. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient provenance and certification tier, with REACH-compliant clean-label formulations commanding measurable premiums. Pricing pressure stems from petrochemical feedstock volatility in ethylene and propylene spot markets, squeezing margin predictability for mid-tier synthetic polymer platforms. Budget-tier household consumers exhibit highest price sensitivity, while professional salon channels prioritize performance benchmarks and regulatory compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from professional distributors in Düsseldorf and Rotterdam mandate multi-supplier qualification for aerosol propellant systems, compelling manufacturers to qualify alternative hydrocarbon-free platforms ahead of REACH enforcement deadlines. Geographic supply concentration centers on Germany for EMEA salon distribution, South Korea for biopolymer research and humidity-resistant film innovation, and the United States for mass-market water-based platform capacity. Raw material dependencies rest on film-forming polymer precursors, hydrocarbon propellants, and plant-derived cellulose derivatives. Single-source vulnerability in Northern Italian and Southern German solvent-handling line builders creates capacity bottlenecks for new market entrants. Distribution runs through professional distributors, direct-to-barbershop logistics, and mass-market retail channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hairstyling products market functions as a stable compounder, with professional salon service revenue streams and recurring back-bar replenishment cycles providing predictable demand visibility across economic conditions.
For Market Incumbents: Lock in aerosol reformulation partnerships with Northern Italian and Southern German equipment builders to secure solvent-handling capacity ahead of REACH enforcement deadlines. Deepen upstream control over fragrance-polymer laboratory infrastructure to maintain formulation pipeline autonomy. Water-based platform R&D investment represents the critical lever for defending margin position against clean-label regulatory compression.
For New Entrants and Emerging Players: Capture barbershop direct procurement relationships in London and Sydney where male grooming specialists are bypassing traditional wholesale channels. Private-label pomade and clay formulations for Australia's thirty to forty consolidated independent operators offer the most penetrable white-space target. Lead with texture innovation and direct contract manufacturing arrangements rather than distributor intermediation.
For Investors and Strategic Acquirers: Consumer goods conglomerates with captive salon distribution infrastructure are the most active acquirer in this space, seeking biopolymer patent portfolios and regional manufacturing scale. Acquisition target archetypes include niche biopolymer research specialists with humidity-resistant film patents and contract manufacturers with REACH-compliant aerosol capacity. Watch for inflection in European enforcement timelines for hydrocarbon propellant phase-outs as the signal to reassess platform exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Aerosol Reformulation Partnership | REACH Annex XVII compliance in Germany and France requires hydrocarbon-free propellant qualification by enforcement deadlines. |
| Biopolymer Patent Licensing | Kao Corporation's humidity-resistant film patents are expanding into Southeast Asian regional production partnerships. |
| Direct-to-Barbershop Channel Bypass | London and Sydney male grooming specialists are consolidating purchasing power through private-label direct procurement. |
| Plant-Derived Polymer R&D Investment | Copenhagen and Amsterdam stylists are piloting corn starch and cellulose formulations for fragrance-sensitive clients. |
| Professional Salon Chain Consolidation | Tier-two city expansion is standardizing back-bar procurement around contract manufacturers with formulation flexibility. |
Research Methodology
Coverage spans Germany, South Korea, the United States, the United Kingdom, and Australia, with primary inputs from each market cluster. The analysis combines structured interviews with professional salon owners, contract manufacturing procurement leads, regulatory affairs specialists at formulation houses, and professional distribution channel managers with secondary validation from REACH Annex XVII filings, MFDS cosmetic safety registrations, FDA cosmetic labeling databases, and customs trade records for polymer precursor flows. Bottom-up volume triangulation across product type, application, and end-user segments is cross-referenced with top-down value estimates derived from regional salon service revenue data.
Granularity-level modeling disaggregates volume and value across the projection horizon by aerosol versus water-based platform chemistry, professional versus daily use application intensity, salon versus individual consumer channel economics, and premium versus mid-range versus budget price tier positioning. CAGRs are derived from segmented trend extrapolation with regulatory timeline adjustments and channel consolidation scenario weighting. Industry-specific forecast inputs include REACH enforcement phase-in schedules for VOC thresholds and professional salon chain expansion rates in tier-two cities.
Underlying measurement precision varies by segment; hair spray volume estimates carry tighter precision due to established salon adoption patterns, while biopolymer-based premium tier projections reflect greater uncertainty around clean-label conversion rates. Forecasts reflect documented assumptions regarding regulatory enforcement timing, feedstock cost trajectories, and channel intermediation fragmentation. Deviation in REACH Annex XVII implementation strictness or hydrocarbon propellant substitution technology readiness would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
US Skincare Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Gua Sha Tools Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Personalized Beauty Devices Market
Beauty & Personal Care
Global Beauty and Personal Care Products Market