
 Electronic Wet Chemicals Market | 2026-2036
Electronic Wet Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Wet Chemicals Market Analysis
A chronic shortage of semiconductor process chemists is unwinding capacity expansion timelines at multiple suppliers. Entegris leverages its contamination control expertise to anchor long-term supply contracts with leading foundries. BASF SE sustains European chemical leadership through backward integration into ultra-high-purity precursor manufacturing. Kanto Chemical Co. Inc. dominates Japan's domestic electronics chemical segment with proprietary blending protocols.
Electronic wet chemicals encompass ultra-pure acids, bases, solvents, and cleaning formulations engineered to parts-per-trillion impurity thresholds for substrate processing. These chemicals perform etching, stripping, cleaning, and deposition support functions essential to semiconductor wafer fabrication, photovoltaic cell manufacturing, and printed circuit board metallization. Acids and solvents command the largest volume share within product type segmentation, though cleaners exhibit the steepest growth trajectory as three-dimensional NAND stacking intensifies surface preparation cycles. Semiconductor manufacturing absorbs the dominant value share by application, while photovoltaics represents the fastest-expanding alternative demand vector as cell efficiency targets tighten.
EPA standards in the United States govern hazardous waste discharge from chemical blending facilities, while REACH and the EU Green Deal constrain fluorinated solvent categories across European supply chains. China's MEE enforces wastewater treatment mandates that elevate capital requirements for domestic wet chemical producers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification barriers.
Market Dynamics
Three-dimensional NAND stacking is multiplying surface preparation cycles per wafer, forcing chemical suppliers to scale blending capacity faster than fab equipment lead times allow. This structural mismatch between process intensity and supply response time is compressing qualification windows and consolidating procurement toward vertically integrated partners.
Growth Catalysts
- Advanced node migration:Sub-7nm logic production at Taiwan and South Korea foundries consumes 40% more cleaning cycles per wafer than prior nodes, pulling volume through ultra-high-purity acid and solvent formulations.
- China's dual carbon goals:Domestic photovoltaic cell efficiency mandates under MIIT directives are expanding metallization chemical demand for PERC and TOPCon architectures.
- REACH authorization delays:European fluorinated solvent restrictions are accelerating reformulation investment in aqueous and hybrid cleaning chemistries for EU-based semiconductor packaging facilities.
Market Restraints
- Feedstock volatility:Electronic-grade hydrofluoric acid pricing tracks fluorspar concentrate availability from Chinese and Mexican mining operations, creating margin instability for blenders without captive mineral sources.
- East Asian supply concentration:Over 70% of ultra-pure isopropyl alcohol purification capacity resides in Japan and South Korea, exposing buyers to single-source risk during shipping disruptions.
- Impurity detection limits:Parts-per-quadrillion metal ion specifications for 3nm gate stacks exceed current metrology capabilities at most third-party analytical laboratories, slowing new chemical qualification.
Strategic Opportunities
- India's semiconductor subsidy scheme:PLI scheme disbursements for domestic fabs in Gujarat and Karnataka are creating first-mover advantage for chemical suppliers establishing local blending operations ahead of 2026 production ramps.
- EU Green Deal solvent categories:F-Gas Regulation phase-down schedules are opening substitution windows for bio-based glycol ether formulations in European PCB cleaning applications.
- Photovoltaic metallization chemistry:Silver paste reduction roadmaps at Chinese cell manufacturers are driving demand for nickel-copper seed layer chemistries previously absent from solar supply chains.
Industry Challenges
- Process chemist scarcity:Semiconductor wet bench engineering talent pools in the United States and Europe have not expanded since 2019, extending supplier technical service response times and delaying customer troubleshooting.
- Multi-jurisdiction qualification burden:Concurrent EPA hazardous waste permits, REACH SVHC registrations, and China's GB/T purity certifications require 18-24 month documentation cycles for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Wet Chemicals Market |
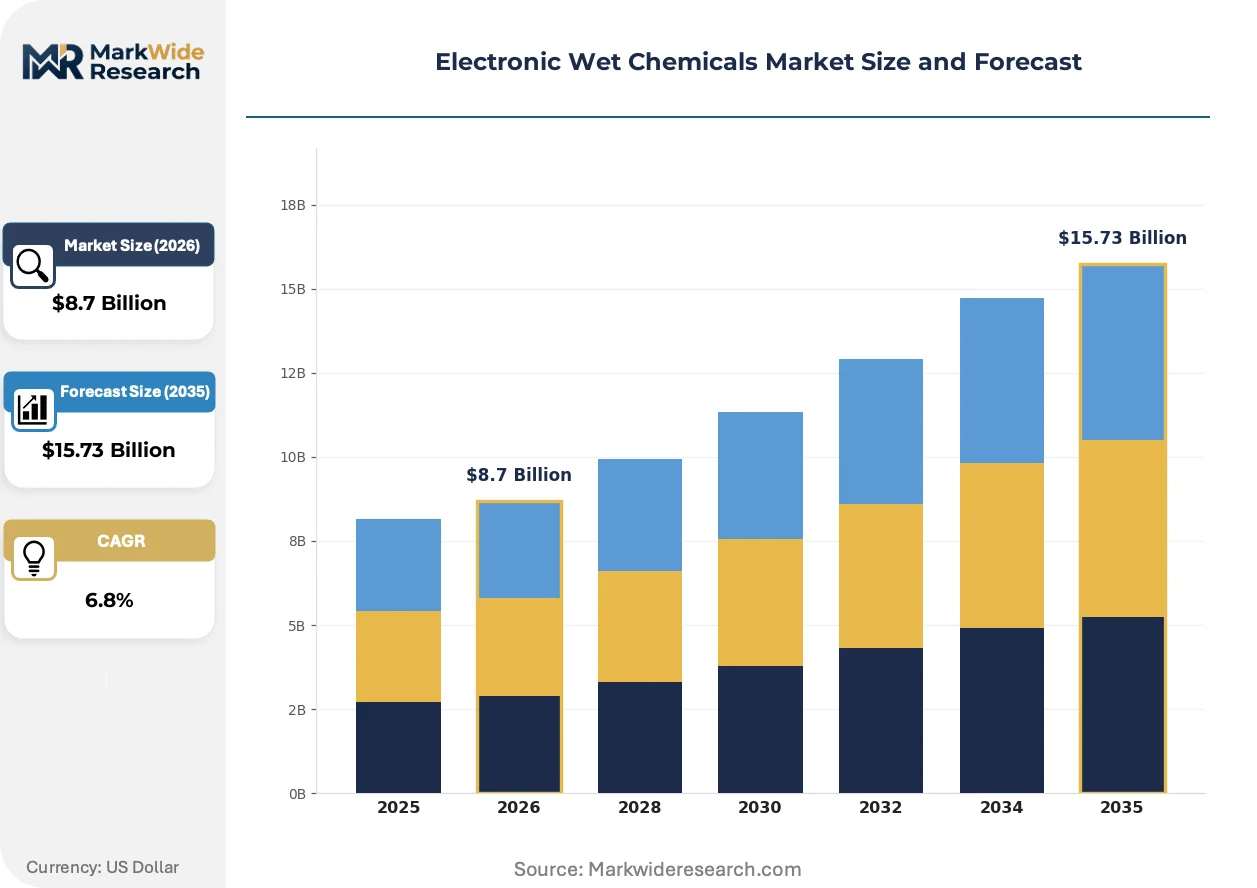
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acids, Bases, Solvents, Cleaners Application: Semi-conductor Manufacturing, Photovoltaics, PCB Fabrication, MEMS End User: Electronics, Solar, Automotive, Medical Device Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Honeywell International Inc., Cabot Microelectronics Corporation, Entegris, Solvay, Eastman Chemical Company, BASF SE, Kanto Chemical Co. Inc., Fujifilm Holdings Corporation, Avantor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Wet Chemicals Market Emerging Trajectories
Process chemistry is splitting into parallel development tracks serving divergent purity requirements. Equipment suppliers and chemical formulators are co-developing closed-loop delivery systems that reduce contamination exposure during transport and dispense operations.
Point-of-use filtration technology is bifurcating the wet chemical supply chain. Advanced logic fabs in Taiwan and South Korea now specify sub-1nm particle filtration at the dispense nozzle, displacing traditional bulk tank filtration models. This shift is compressing chemical shelf-life specifications and enabling regional blending hubs to compete against centralized mega-plants.
REACH and the EU F-Gas Regulation are forcing solvent category transitions across European semiconductor packaging facilities. Restrictions on perfluorinated compounds used in vapor degreasing are accelerating aqueous and semi-aqueous formulation adoption. German and Dutch chemical suppliers are responding with proprietary surfactant blends that match fluorinated solvent drying speeds without SVHC classification.
Captive supply agreements are displacing spot procurement at leading foundries. Taiwan Semiconductor Manufacturing and Samsung Foundry now require 5-7 year chemical supply commitments with volume floors and price collars. This contractual shift is visible across East Asian foundry clusters, where procurement teams prioritize supply security over unit cost optimization during node transitions.
Electronic Wet Chemicals Market Segmentation
Electronic wet chemicals serve divergent purity requirements across fabrication technologies. Segmentation reveals how formulation specifications, delivery modes, and end-use constraints reshape supplier capabilities and procurement patterns.
Product Type:
Domestic blending capacity concentrates acids and solvents in Japan, South Korea, and Taiwan, while cleaners and bases increasingly move through regional hubs serving export markets.
- Acids:Electronic-grade hydrofluoric, sulfuric, and phosphoric formulations etch silicon substrates and strip photoresist at parts-per-trillion metal ion specifications. Demand clusters at Taiwan and South Korea foundries running sub-7nm logic nodes, where EPA discharge permits and REACH SVHC registrations constrain supplier qualification timelines.
- Solvents:Ultra-high-purity isopropyl alcohol, acetone, and N-methyl-2-pyrrolidone dissolve organic residues and dehydrate wafer surfaces. Japan and South Korea control over 70% of purification capacity, exposing buyers to shipping disruption risk during East Asian port congestion.
- Bases:Ammonium hydroxide and tetramethylammonium hydroxide solutions adjust pH during chemical mechanical planarization. Photovoltaic cell manufacturers in China drive volume through metallization paste cleaning applications.
- Cleaners:Surfactant blends and chelating agent formulations remove post-etch particle contamination from three-dimensional NAND architectures. Taiwan foundries specify sub-1nm particle filtration at dispense nozzles, compressing shelf-life windows and enabling regional blending competition.
Acids and solvents command the established base. The steepest expansion runs through cleaners.
Application:
Cost tiers separate captive supply agreements at leading foundries from spot procurement at smaller packaging facilities and solar cell manufacturers.
- Semiconductor Manufacturing:Wafer fabrication consumes ultra-high-purity acids, solvents, and cleaners for etching, stripping, and surface preparation cycles. Taiwan Semiconductor Manufacturing and Samsung Foundry now require 5-7 year supply commitments with volume floors, displacing transactional purchasing during node transitions.
- Photovoltaics:Silver paste reduction roadmaps at Chinese cell manufacturers are expanding metallization chemical demand for PERC and TOPCon architectures. MIIT efficiency mandates under dual carbon goals accelerate chemistry substitution timelines.
- PCB Fabrication:Printed circuit board metallization relies on electroplating chemistries and surface treatment formulations. EU F-Gas Regulation restrictions on perfluorinated compounds are forcing aqueous and semi-aqueous solvent transitions across German and Dutch packaging facilities.
- MEMS:Microelectromechanical systems fabrication employs specialized etchants and release-layer chemistries for sensor and actuator production. Automotive pressure sensor demand pulls volume through foundries in Michigan and Bavaria.
Semiconductor manufacturing absorbs the dominant value share. Photovoltaics climbs the fastest as cell efficiency targets tighten.
End User:
Customer type determines qualification burden intensity, with medical device and automotive sectors imposing the most stringent documentation requirements.
- Electronics:Consumer and industrial semiconductor devices drive the largest absolute volume through logic and memory fabrication. Taiwan and South Korea foundry clusters anchor procurement concentration.
- Solar:Photovoltaic cell and module manufacturers consume metallization pastes, etchants, and cleaning formulations. Chinese domestic capacity expansion under PLI-equivalent schemes reshapes regional supply patterns.
- Automotive:Power semiconductor and sensor fabrication for electric vehicles imposes AEC-Q100 reliability standards on chemical purity documentation. German and Japanese tier-1 suppliers enforce extended qualification protocols.
- Medical Device:Implantable and diagnostic equipment manufacturing requires ISO 13485-traceable chemical supply chains. FDA 21 CFR Part 820 compliance extends supplier audit cycles beyond standard electronics procurement.
Electronics commands the established base. Solar gains share fastest as domestic manufacturing subsidies activate.
Distribution Channel:
Supply concentration favors direct sales at high-volume foundries, while fragmented demand routes through distributors and resellers.
- Direct Sales:Captive agreements with Entegris, BASF SE, and Kanto Chemical Co. Inc. anchor long-term supply security at Taiwan Semiconductor Manufacturing and Samsung Foundry. Technical service integration justifies premium pricing over spot alternatives.
- Distributors:Regional chemical distributors consolidate fragmented demand from smaller PCB fabricators and photovoltaic cell manufacturers. Inventory pooling reduces qualification burden for buyers sourcing multiple formulation grades.
- Online Retail:Standard-grade solvents and acids for research quantities and prototyping move through specialized chemical marketplaces. Limited to non-critical applications given purity documentation gaps.
- Resellers:Secondary market participants arbitrage geographic price differentials for commodity-grade isopropyl alcohol and acetone. Quality consistency risks constrain penetration in semiconductor-qualified supply chains.
Direct sales commands the established base. Distributors expand most quickly serving mid-tier solar and PCB customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT directives under China's dual carbon goals are accelerating photovoltaic metallization chemistry demand while REACH and the EU F-Gas Regulation reshape European solvent categories. Taiwan and South Korea foundry clusters anchor semiconductor-grade consumption, with regulatory divergence creating qualification bottlenecks across jurisdictions.
Taiwan
Sub-7nm logic production at Taiwan Semiconductor Manufacturing consumes elevated cleaning cycle volumes per wafer. The island's EPA-aligned hazardous waste discharge protocols constrain blending facility expansion timelines. Hsinchu Science Park anchors captive supply agreements with 5-7 year commitment structures now standard for advanced node procurement.
South Korea
Samsung Foundry and SK Hynix drive ultra-high-purity acid and solvent demand through three-dimensional NAND stacking intensity. The country's national environmental regulator enforces wastewater treatment mandates elevating capital requirements for domestic producers. Pyeongtaek and Yongin foundry complexes concentrate blending capacity expansion to match process chemistry lead times.
China
Domestic photovoltaic cell efficiency mandates under MIIT are expanding metallization chemical demand for PERC and TOPCon architectures. GB standards for electronic-grade purity tighten supplier qualification thresholds for semiconductor applications. Yangtze River Delta and Pearl River Delta clusters concentrate both solar cell manufacturing and emerging domestic fab capacity under PLI-equivalent subsidy schemes.
Japan
Kanto Chemical Co. Inc. dominates domestic electronics chemical supply through proprietary blending protocols. METI industrial standards govern ultra-high-purity precursor specifications for export markets. Kyushu and Kansai regions concentrate isopropyl alcohol purification capacity controlling over 70% of regional supply.
Germany
BASF SE sustains European chemical leadership through backward integration into ultra-high-purity precursor manufacturing. REACH SVHC registrations and the EU F-Gas Regulation phase-down schedules accelerate aqueous formulation investment. Saxony-Anhalt and Ludwigshafen production sites anchor supply to Dutch and German semiconductor packaging facilities.
Electronic Wet Chemicals Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with contamination control expertise and backward integration into precursor manufacturing separating premium positioning from commodity supply. The structure rewards captive mineral sources and long-term foundry contracts over spot market participation. Three archetypes dominate: integrated chemical conglomerates with upstream raw material control, specialist blenders with proprietary purification protocols, and equipment-chemical hybrids offering closed-loop delivery systems. Competitive moves concentrate on multi-year supply commitment structures and regional blending hub establishment ahead of customer production ramps.
Within the integrated conglomerate tier, BASF SE and Solvay exemplify European chemical leadership through upstream control over ultra-high-purity precursor manufacturing. Among Asia-Pacific specialists, Kanto Chemical Co. Inc. and Fujifilm Holdings Corporation occupy positions defined by proprietary blending protocols and domestic market anchoring. Entegris represents the equipment-chemical hybrid archetype, leveraging contamination control expertise to anchor long-term supply security at leading foundries.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Cabot Microelectronics Corporation |
| Entegris |
| Solvay |
| Eastman Chemical Company |
| BASF SE |
| Kanto Chemical Co. Inc. |
| Fujifilm Holdings Corporation |
| Avantor Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day chemical qualification windows compress inventory turns to twelve-to-fifteen days at Taiwan and South Korea foundries, binding pricing power to blending capacity proximity and captive supply agreement structures. This lead-time compression rewards regional hub operators while penalizing distant suppliers facing REACH and GB standards compliance costs.
Pricing Analysis
Price spreads between Japanese ultra-high-purity isopropyl alcohol and Korean spot alternatives widen during East Asian port congestion events. Three-tier pricing structure across electronic-grade, semi-grade, and industrial-grade purity levels anchors contract structures, with certification tier and volume scale as primary differentiation drivers. Cost compression in semi-grade solvents intensifies as Chinese domestic blending capacity expands. Photovoltaic cell manufacturers exhibit highest price sensitivity; Taiwan foundries running sub-7nm nodes show least sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Just-in-time delivery dominates semiconductor fab procurement, though strategic stockpiling of fluorspar-derived precursors persists among blenders without captive mineral sources. Supply concentrates in Japan, South Korea, and Taiwan for purification capacity; China dominates fluorspar mining and intermediate chemical production. Feedstock volatility in electronic-grade hydrofluoric acid rests on Mexican and Chinese mining output fluctuations. Single-source vulnerability in isopropyl alcohol purification exposes buyers to shipping disruption risk. Distribution runs through direct sales at high-volume foundries and regional distributors for fragmented solar and PCB demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process chemist scarcity constrains technical service response times and extends customer troubleshooting cycles, creating competitive advantage for suppliers with embedded engineering talent pools.
For Market Incumbents: Compound contamination control expertise into closed-loop delivery system offerings that lock in long-term foundry contracts. Deepen backward integration into ultra-high-purity precursor manufacturing to defend margins against feedstock volatility. Expand blending capacity in Gujarat and Karnataka ahead of India's PLI scheme production ramps to preempt emerging entrant positioning. For New Entrants and Emerging Players: Differentiate on aqueous and bio-based glycol ether formulations serving EU F-Gas Regulation substitution demand in German and Dutch packaging facilities. Target India's domestic fab buildout as the most penetrable geography, exploiting first-mover window before 2026 production ramps. Pursue technical partnership routes with equipment suppliers to embed formulations into closed-loop dispense systems. For Investors and Strategic Acquirers: Long-term, this sits as a supply-security play because captive mineral sources and qualified blending protocols create durable moats against commodity competition. Acquisition targets should display backward integration into fluorspar or precursor manufacturing plus established foundry qualification status. Watch for REACH authorization delays accelerating aqueous formulation substitution as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | BASF SE's Ludwigshafen ultra-high-purity production anchors European supply security against import dependency. |
| Regional Blending Hub Establishment | Gujarat capacity additions ahead of PLI disbursements capture India's emerging semiconductor chemical demand. |
| Long-term Supply Agreement Restructuring | Five-to-seven year commitments with volume floors displace spot procurement at Taiwan Semiconductor Manufacturing. |
| Green Chemistry Reformulation Investment | Aqueous surfactant blends match fluorinated solvent performance without EU F-Gas Regulation SVHC classification. |
| Closed-loop Delivery System Co-development | Point-of-use filtration integration with equipment suppliers compresses shelf-life specifications and enables hub competition. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with semiconductor process chemists, foundry procurement directors, wet chemical plant managers, and photovoltaic cell manufacturing executives; and secondary validation through customs trade data, SEMI industry reports, SEC chemical company filings, and MIIT directive documentation. Bottom-up capacity assessments triangulated against top-down consumption models derived from foundry wafer start projections.
Across the analysis window, forecasts model product type, application, end user, and distribution channel dimensions alongside regional production hub clustering. CAGRs derive from segment-level volume trajectories weighted by purity grade pricing differentials. Forecast inputs include three-dimensional NAND stacking intensity, MIIT solar efficiency mandate timelines, and REACH authorization delay probabilities.
The analysis sits within stated boundaries; outcomes outside sustained East Asian foundry expansion or accelerated EU solvent phase-down schedules would require recalibration. Forecasts reflect documented assumptions regarding qualification timeline stability and fluorspar supply continuity. Practitioners should keep alternative scenarios live as regulatory divergence and process chemist availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Chemicals
Global Imaging Chemicals Market
Electronic Chemicals
Printed Electronic Materials Market
Electronic Chemicals
Global 5G EMI Materials Market
Electronic Chemicals
Liquid Soldering Flux Market
Electronic Chemicals
Global Electronic Materials and Chemicals Market
Electronic Chemicals
Global Circuit Materials Market
Electronic Chemicals
Silver Paste Market
Electronic Chemicals
Electronic Chemicals Market