
 Europe Customized Premixes Market | 2026-2036
Europe Customized Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Customized Premixes Market Foresight
Functional beverage formulation is repositioning demand toward clean-label premix systems that reduce ingredient complexity. DSM-Firmenich leverages its combined nutrition and flavor platform to dominate vitamin premix supply for fortified drinks. Glanbia plc anchors its position through dairy-derived mineral systems for sports nutrition. Corbion competes with fermentation-based premix innovations that address shelf-stability challenges.
Customized premixes are precisely blended concentrates of vitamins, minerals, amino acids, or probiotics, manufactured through spray-drying, fluid-bed granulation, or microencapsulation to achieve uniform dispersion and controlled release in finished products. Powder formulations lead volume due to cost-efficient handling and extended stability, while liquid premixes capture faster growth in ready-to-drink applications where rapid solubility matters. Dietary supplements command the deepest margin pools as brands pay premiums for clinically validated premix specifications that support health claims.
EFSA scientific opinions and the EU Nutrition and Health Claims Regulation shape permissible premix dosages and label declarations, forcing reformulation cycles when opinions tighten. ECHA REACH compliance adds burden for mineral and amino acid sourcing, particularly for imports from non-EU suppliers. Stakeholders must monitor evolving EFSA opinions on novel probiotic strains and mineral bioavailability, as these determinations will open or close application pathways before competitors adapt.
Market Dynamics
Clean-label compliance pressure from the EU Green Deal is restructuring premix procurement, forcing manufacturers to consolidate ingredient sourcing and reformulate around additive transparency mandates.
Growth Catalysts
- EU Farm-to-Fork Strategy:Mandatory supply-chain traceability requirements are accelerating premix adoption by functional beverage producers seeking simplified ingredient declarations.
- Spray-drying technology advancement:Enhanced microencapsulation processes now deliver superior vitamin stability in powder premixes for fortified dairy applications.
- Frankfurt-Hamburg ingredient clusters:Concentrated German production infrastructure reduces logistics costs for continental premix distribution.
Market Restraints
- Mineral input cost volatility:Magnesium and zinc price fluctuations squeeze margin structures for mineral-intensive premix formulations.
- ECHA REACH compliance burden:Registration requirements for non-EU amino acid suppliers extend lead times and elevate qualification costs.
- Probiotic strain validation gaps:Pending EFSA scientific opinions on novel bacterial cultures delay product launch timelines.
Strategic Opportunities
- Poland and Czech Republic underpenetration:Eastern European markets show accelerating demand for fortified bakery premixes with limited local supply capacity.
- Ready-to-drink liquid premix convergence:Rapid-solubility formulations are capturing share in convenience beverage channels previously served by powder systems.
- CSRD sustainability disclosure:Premix suppliers with verified carbon footprints gain preferential positioning with ESG-mandated food manufacturers.
Industry Challenges
- Formulation chemist scarcity:Shortage of specialists skilled in bioavailability optimization complicates custom premix development cycles.
- Legacy ERP integration friction:Batch tracking systems struggle to accommodate real-time traceability requirements under Farm-to-Fork mandates.
- EFSA opinion timing uncertainty:Unpredictable regulatory timelines disrupt R&D roadmaps for novel ingredient combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Customized Premixes Market |
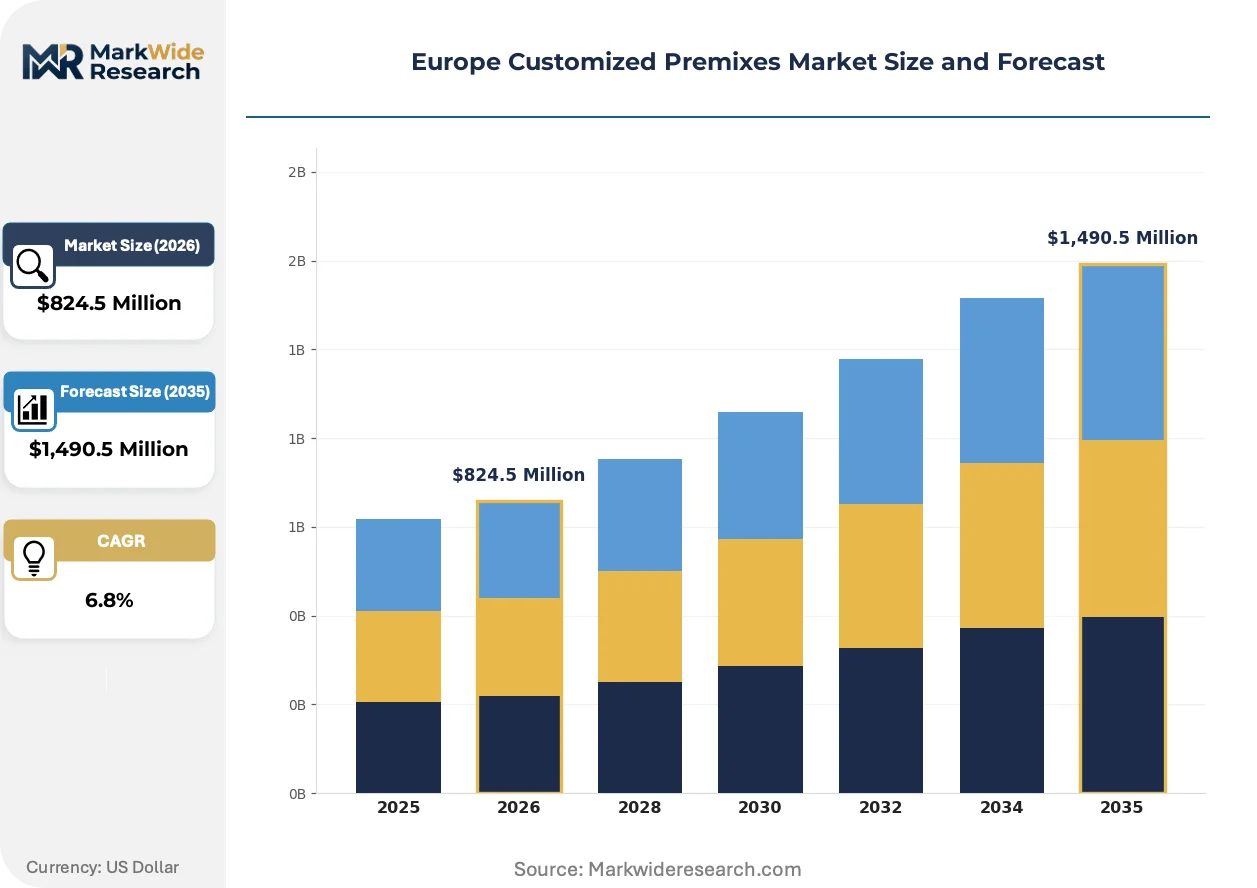
| Market Size in 2026 | $824.5 Million |
| Market Size in 2035 | $1,490.5 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics Application: Food & Beverage, Pharmaceuticals, Animal Nutrition, Dietary Supplements End User: Food Manufacturers, Healthcare Providers, Distributors, Retailers Form: Powder, Liquid, Granules, Capsules |
| Companies Covered | DSM-Firmenich, Glanbia plc, Corbion, Vitablend Nederland, SternVitamin GmbH & Co. KG, Archer Daniels Midland Company (ADM), Nutreco, Barentz International, Prinova Group LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Customized Premixes Market Shifts & Advancements
Microencapsulation advances and regulatory disclosure mandates are converging to reshape premix specification standards across European food and beverage manufacturing.
Fluid-bed granulation is absorbing market share from conventional spray-drying for heat-sensitive probiotic applications. Sports nutrition manufacturers in Germany and the Netherlands are adopting these systems at accelerating rates. The technology is absorbing margin pressure by reducing overage requirements and extending shelf stability.
EFSA's evolving scientific opinions on mineral bioavailability are tightening permissible dosage ranges for health claims. This regulatory trajectory forces reformulation cycles among premix suppliers serving supplement brands. Dietary supplement applications face the steepest compliance burden, with manufacturers preemptively reducing zinc and iron concentrations ahead of anticipated opinion releases.
Direct sourcing contracts between premix suppliers and end-use manufacturers are displacing traditional distributor intermediaries. Large functional beverage producers in France and Italy now negotiate specification-grade agreements that bypass regional chemical distributors. This channel compression concentrates in high-volume powder premix categories where technical consultation requirements have diminished.
Europe Customized Premixes Market Segmentation
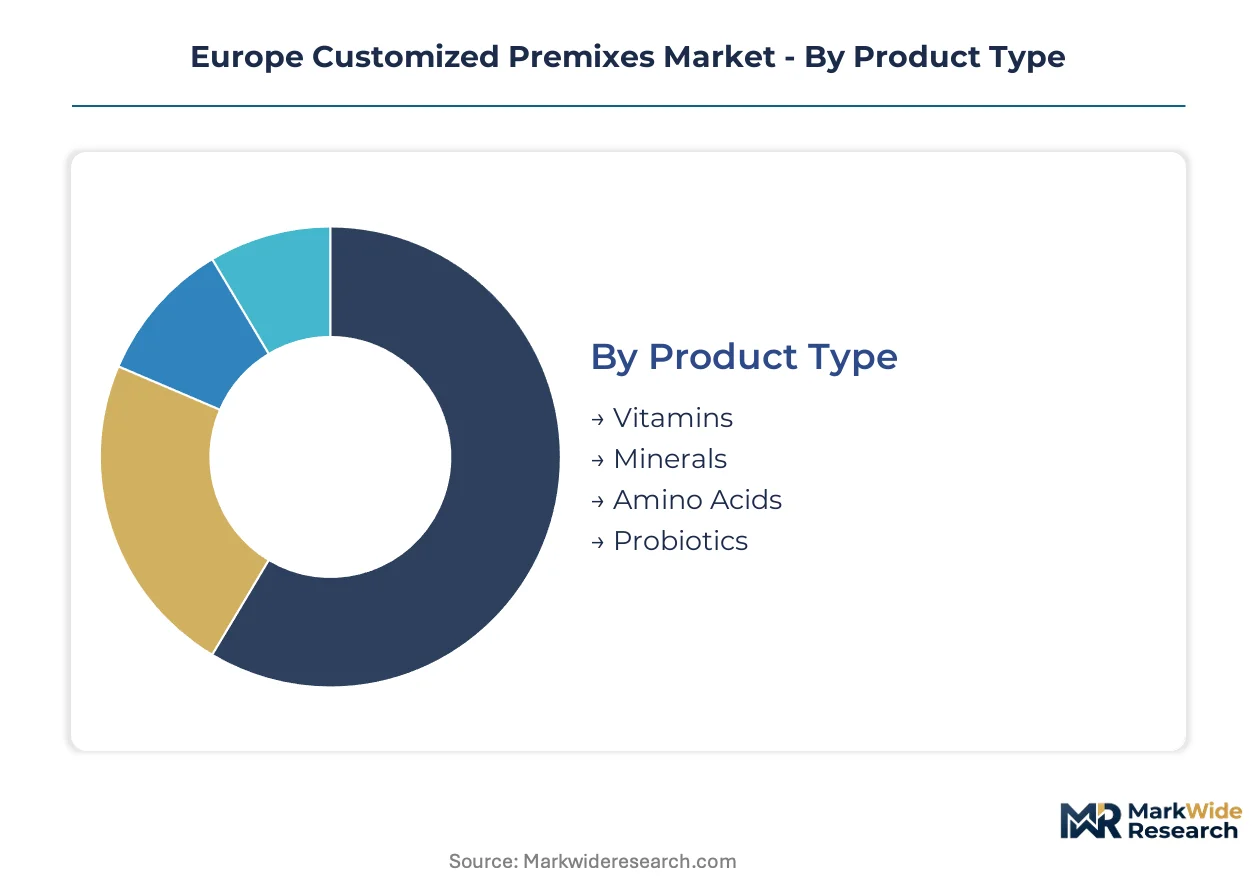
European premix buyers fragment across formulation technologies, end-use specifications, and supply-chain service requirements. Each segmentation axis reveals distinct margin structures and competitive intensity patterns. Understanding these divides exposes where suppliers can defend pricing power versus where commoditization pressures dominate.
Product Type:
Vitamin and mineral premixes anchor volume throughput, while amino acid and probiotic systems command specification premiums and face divergent regulatory validation burdens.
- Vitamins:Spray-dried and microencapsulated concentrates of fat-soluble and water-soluble compounds, formulated for thermal stability in bakery and dairy processing. German fortified beverage manufacturers concentrate demand around DSM-Firmenich supply contracts for label-compliant B-vitamin and vitamin D systems.
- Minerals:Chelated and inorganic salt forms of zinc, magnesium, iron, and selenium, optimized for bioavailability in sports nutrition and infant formula. Glanbia plc anchors continental supply through dairy-derived mineral platforms serving Netherlands-based performance nutrition brands.
- Amino Acids:Branched-chain and essential amino acid premixes for muscle protein synthesis claims. ECHA REACH registration requirements for non-EU suppliers compress available sourcing channels and elevate qualification costs for new market entrants.
- Probiotics:Freeze-dried bacterial cultures requiring strain-specific EFSA validation for health claim eligibility. Pending scientific opinions on novel Lactobacillus and Bifidobacterium species delay product launch timelines across French and Italian supplement markets.
Today's leader: Vitamins. Tomorrow's challenger: Probiotics.
Application:
Food and beverage integration absorbs the deepest volume, yet dietary supplements and pharmaceuticals retain the steepest margin pools where clinical validation commands price premiums.
- Food & Beverage:Fortified dairy, bakery, and convenience beverage applications requiring heat-stable premix systems. Frankfurt-Hamburg ingredient clusters reduce logistics costs for continental distribution of powder premixes into German and Benelux processing facilities.
- Dietary Supplements:Tablet, capsule, and sachet formats demanding clinically validated specifications that support EFSA-permitted health claims. Manufacturers preemptively reformulate zinc and iron concentrations ahead of anticipated bioavailability opinion tightening.
- Pharmaceuticals:Excipient-integrated premixes for OTC and prescription nutritional therapies. EMA quality guidelines and GMP compliance requirements elevate supplier qualification barriers beyond standard food-grade specifications.
- Animal Nutrition:Feed-grade vitamin and mineral fortification for livestock and companion animal applications. Poland and Czech Republic show accelerating demand for fortified premixes with limited local production capacity.
Food and beverage commands current volume leadership. Dietary supplements offer the steepest expansion trajectory for specification-grade suppliers.
End User:
Direct procurement contracts between premix suppliers and large food manufacturers are displacing distributor intermediaries, restructuring channel economics and technical service requirements.
- Food Manufacturers:Industrial-scale buyers negotiating specification-grade agreements that bypass regional chemical distributors. French and Italian functional beverage producers now source directly for high-volume powder categories where formulation consultation needs have diminished.
- Distributors:Traditional intermediaries retaining relevance in fragmented bakery and small-scale supplement channels requiring technical support and smaller minimum order quantities.
- Healthcare Providers:Hospital and clinical nutrition services demanding patient-specific premix formulations with documented batch traceability under EU Farm-to-Fork mandates.
- Retailers:Private-label supplement and fortified food brands outsourcing premix procurement to contract manufacturers with integrated formulation capabilities.
Food manufacturers consolidate procurement power. Healthcare providers emerge as the fastest-growing customer type for validated clinical nutrition systems.
Form:
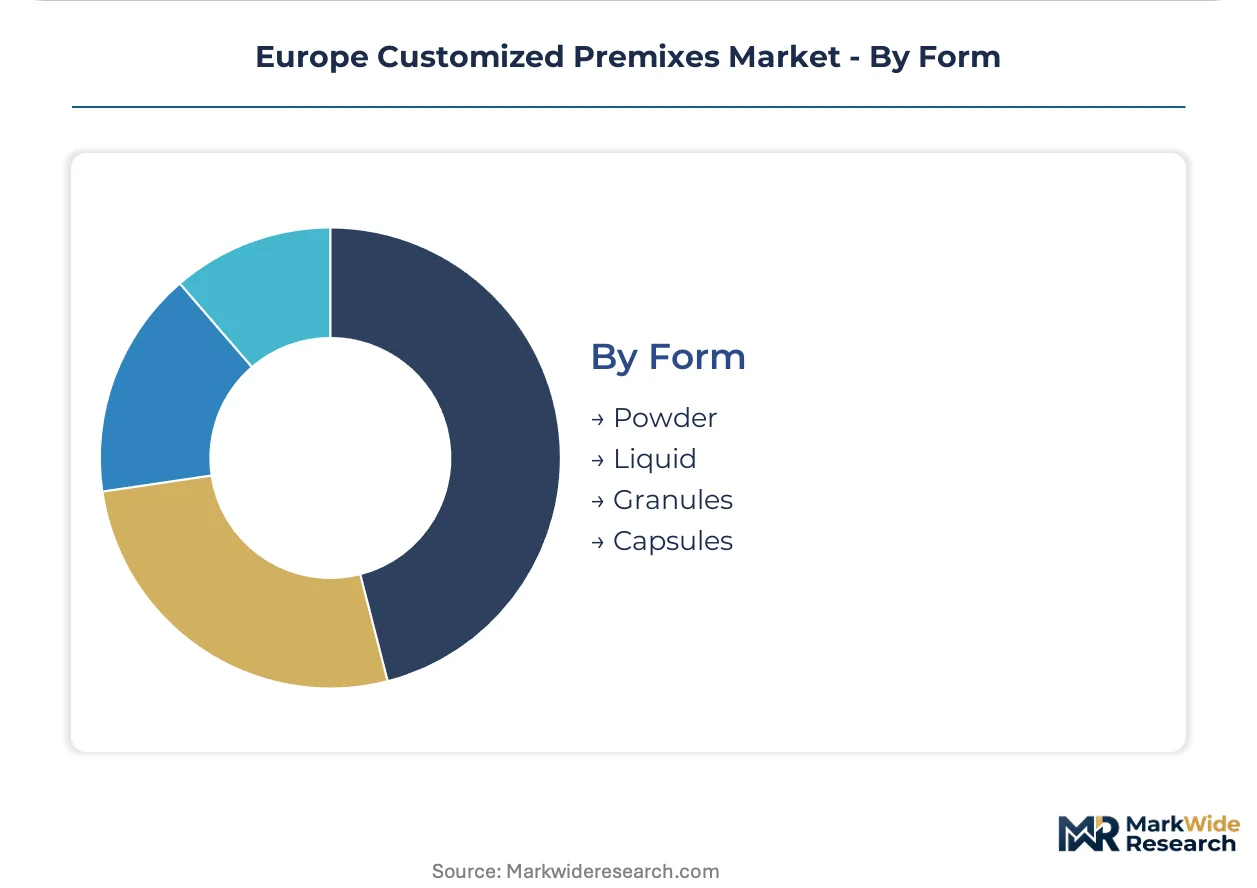
Powder formulations dominate cost-efficient handling and extended stability, while liquid systems gain share in ready-to-drink channels where rapid solubility determines consumer experience.
- Powder:Spray-dried and granulated premixes offering extended shelf stability and economical bulk handling. Fluid-bed granulation absorbs share from conventional spray-drying for heat-sensitive applications among German and Netherlands sports nutrition manufacturers.
- Liquid:Rapid-solubility concentrates for ready-to-drink beverages and liquid supplement formats. Convenience beverage channels in France and Italy increasingly specify liquid premixes over traditional powder systems.
- Granules:Intermediate particle size for controlled dissolution in instant beverage and effervescent applications.
- Capsules:Pre-metered dosage forms for supplement brands seeking manufacturing simplification and reduced handling contamination risk.
Powder retains volume dominance. Liquid forms climb the fastest in convenience-oriented beverage segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography across Europe as premix manufacturers migrate toward jurisdictions with streamlined ECHA REACH compliance pathways and concentrated technical talent pools. Cost-of-compliance gaps between member states now determine where new encapsulation capacity anchors.
Germany
Frankfurt-Hamburg ingredient clusters anchor continental supply for fortified beverage and sports nutrition premixes. EFSA scientific opinion tracking consumes significant regulatory affairs resources among suppliers headquartered here. DSM-Firmenich leverages its combined nutrition and flavor platform to dominate vitamin premix contracts for German functional drink manufacturers.
Netherlands
Dairy-derived mineral systems for performance nutrition concentrate around Glanbia plc's continental operations serving Benelux processing facilities. The Dutch national food safety authority enforces strict additive transparency mandates ahead of EU Farm-to-Fork deadlines. Corbion competes with fermentation-based premix innovations addressing shelf-stability challenges in Amsterdam-Rotterdam logistics corridors.
France
Direct procurement contracts between premix suppliers and large functional beverage producers now bypass traditional distributor intermediaries in Paris and Lyon manufacturing basins. ANSM pharmaceutical-grade oversight elevates qualification barriers for clinical nutrition premix applications. Fluid-bed granulation technology adoption accelerates among heat-sensitive probiotic formulators in the Rhône-Alpes region.
Italy
Specification-grade agreements for high-volume powder premixes concentrate in Milan-Turin food processing corridors where technical consultation requirements have diminished. Pending EFSA opinions on novel probiotic strains delay product launch timelines across Italian supplement markets. Barentz International maintains distribution presence serving fragmented bakery channels requiring smaller minimum order quantities.
Poland
Accelerating demand for fortified bakery premixes outpaces limited local production capacity in Warsaw-Łódź manufacturing zones. Eastern European market underpenetration creates procurement bottlenecks as western suppliers extend distribution networks. CSRD sustainability disclosure requirements now influence supplier selection among ESG-mandated Polish food manufacturers.
Europe Customized Premixes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated nutrition majors dominating high-volume vitamin and mineral categories while fragmented regional blenders retain relevance in customized probiotic formulations. Three archetypes define competitive positioning: integrated nutrition platforms with combined ingredient and flavor capabilities, dairy-derived mineral specialists leveraging upstream raw material access, and fermentation-based innovators addressing stability challenges. M&A activity concentrates on acquiring encapsulation technology capabilities, while capacity expansion focuses on spray-drying and fluid-bed granulation installations near Frankfurt-Hamburg logistics clusters.
Within the integrated nutrition platform tier, DSM-Firmenich represents the archetype of combined ingredient and flavor supply serving fortified beverage manufacturers. Among dairy-derived mineral specialists, Glanbia plc exemplifies upstream integration into sports nutrition premix systems. On the fermentation innovation vector, Corbion occupies a position addressing shelf-stability through bioprocess-derived formulations. These three anchors illustrate how competitive positioning stratifies across technology platforms rather than geographic coverage alone.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Glanbia plc |
| Corbion |
| Vitablend Nederland |
| SternVitamin GmbH & Co. KG |
| Archer Daniels Midland Company (ADM) |
| Nutreco |
| Barentz International |
| Prinova Group LLC |
| Others |
Supply & Pricing Matrix
Formulation chemist scarcity in the Frankfurt-Hamburg corridor widens labor-cost spreads between premium clinical-grade premixes and standard food-grade alternatives. ECHA REACH compliance burdens amplify tier separation as qualification costs concentrate in specification-grade supply.
Pricing Analysis
Distributor margins compress as direct procurement contracts between premix suppliers and large functional beverage producers displace traditional intermediaries. Three-tier pricing structure across premium, standard, and economy levels stratifies by EFSA health claim validation status and mineral chelation grade. Pricing pressure stems from magnesium and zinc input cost volatility squeezing mineral-intensive formulations. Food manufacturers show highest price sensitivity in high-volume powder categories, while dietary supplement brands absorb premiums for clinically validated specifications.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Hamburg, and Amsterdam-Rotterdam anchor hub-and-spoke patterns for continental premix distribution. Supply concentrates in Germany, Netherlands, and France for vitamin and mineral systems, with Poland and Czech Republic dependent on western capacity. Raw material dependencies include Chinese mineral salts, Indian amino acid intermediates, and Nordic fish oil derivatives. Single-source vulnerability runs through ECHA REACH-registered non-EU amino acid suppliers. Distribution runs through direct supplier-OEM contracts for high-volume categories, with fragmented distributor networks serving smaller bakery and supplement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Customized Premixes Market reads as a late-cycle quality story. Functional beverage manufacturers are repositioning procurement toward clean-label premix systems that command specification premiums.
For Market Incumbents: Acquire fluid-bed granulation capacity to defend against spray-drying commoditization in heat-sensitive probiotic applications. Consolidate backward integration into mineral chelation capabilities to offset magnesium and zinc price volatility. EFSA opinion timing uncertainty threatens R&D roadmap stability, demanding preemptive reformulation investment ahead of bioavailability tightening. For New Entrants and Emerging Players: Premium-economy tier gaps in Eastern European fortified bakery premixes offer white-space entry points. Poland and Czech Republic show accelerating demand with limited local production capacity. Target direct sourcing contracts with mid-sized Polish food manufacturers seeking CSRD-compliant suppliers. Fermentation-based premix innovations addressing shelf-stability challenges provide differentiated go-to-market positioning against established spray-dryers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders with customized probiotic formulation capabilities and pending EFSA strain validations. Long-term viability centers on encapsulation technology ownership as microencapsulation becomes table stakes for vitamin stability claims. Acquisition target archetype: mid-cap specialists with fluid-bed granulation assets and established healthcare provider relationships. Monitor EFSA scientific opinion release schedules as inflection indicator for novel probiotic pathway openings.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Acquisition | DSM-Firmenich and Corbion compete through superior vitamin stability in fortified beverages. |
| Direct-to-Manufacturer Contract Expansion | French and Italian functional beverage producers now bypass distributors for powder premix procurement. |
| Eastern European Distribution Buildout | Poland and Czech Republic demand outpaces local supply, creating first-mover positioning. |
| CSRD Carbon Footprint Verification | ESG-mandated food manufacturers in Germany and Netherlands prefer verified suppliers. |
| Fluid-Bed Granulation Capacity Addition | German and Netherlands sports nutrition manufacturers adopt heat-sensitive probiotic processing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research engaged formulation chemists at premix suppliers, procurement directors at functional beverage manufacturers, regulatory affairs specialists tracking EFSA opinions, and distribution channel managers in Frankfurt-Hamburg logistics corridors. Secondary validation drew from EFSA scientific opinion databases, ECHA REACH registration filings, EU Farm-to-Fork Strategy implementation documents, and customs trade data for mineral and amino acid imports. Bottom-up premix volume estimates triangulated against top-down fortified food and supplement production data.
Segment-weighting approaches distributed value across vitamin, mineral, amino acid, and probiotic product types, with further stratification by powder, liquid, granule, and capsule forms. Application splits modeled food and beverage, dietary supplement, pharmaceutical, and animal nutrition end-uses. Geographic clustering captured Germany, Netherlands, France, Italy, Poland, and Czech Republic demand patterns. CAGRs derived from elasticity-adjusted volume projections and specification-premium capture rates across the analysis window. Mineral input cost trajectories and EFSA opinion probability timelines fed scenario-weighted outputs.
Caveats apply where EFSA scientific opinion timing, mineral commodity price spikes, or ECHA REACH enforcement shifts could materially shift the outlook. Forecasts reflect documented assumptions around Farm-to-Fork traceability implementation pace and clean-label reformulation cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Glass Vials Market
Chemicals & Materials
Global Aluminium Wire Rod Market
Chemicals & Materials
Tranexamic Acid API Market
Chemicals & Materials
Household Paper Market
Chemicals & Materials
Arginine Market
Chemicals & Materials
GCC Vinyl Flooring Market
Chemicals & Materials
Polypropylene Filler Sheet Market
Chemicals & Materials
Europe Industrial and Institutional Cleaning Chemicals Market
Chemicals & Materials
Europe Metal Precision Turned Product Manufacturing Market
Chemicals & Materials
Nucleotides Market
Chemicals & Materials
Anti-Settling Agents Market
Chemicals & Materials
Calcium Acetate Market
Chemicals & Materials
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Chemicals & Materials
Global Neodymium Magnet Market
Chemicals & Materials
Metal Casting Market
Chemicals & Materials
Dispersion Adhesives Market