
 Global Circuit Materials Market | 2026-2036
Global Circuit Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Circuit Materials Market Analysis
Modular substrate configurations is pivoting procurement patterns as buyers unbundle copper-clad laminates from pre-preg stacks to optimize inventory and reduce waste. Kingboard Laminates Holdings Ltd anchors Asia-Pacific supply through integrated resin-to-laminate production. Shengyi Technology Co. Ltd differentiates via high-speed low-loss material portfolios for server and base station applications. Panasonic Corporation leverages decades of fluoropolymer expertise to sustain premium positioning in millimeter-wave substrates.
Circuit materials encompass conductive foils, dielectric substrates, bonding adhesives, and protective coatings engineered to precise dielectric constant, loss tangent, and thermal conductivity specifications for signal transmission integrity. These materials form the physical foundation of printed, flexible, and hybrid circuit boards that route electrical signals across virtually all electronic equipment. Substrate formulations lead value generation as halogen-free and high thermal reliability grades command widening premiums over standard FR-4 equivalents. Flexible circuit technology is accelerating fastest as foldable consumer devices and automotive sensor arrays multiply bendable interconnect requirements. Copper foil segments split between electrodeposited and rolled varieties, with ultra-thin grades below nine microns capturing concentrated margin pools in advanced packaging.
REACH substance restrictions and RoHS hazardous substance limits in Europe compel reformulation of flame retardants and resin systems, while China's GB standards and MIIT directives enforce domestic material certification for telecom infrastructure procurement. The US FCC equipment authorization framework indirectly shapes substrate performance thresholds through electromagnetic compatibility testing requirements. Stakeholders must monitor evolving halogen-free mandates and copper sourcing traceability rules as sustainability disclosure obligations tighten across multiple jurisdictions.
Market Dynamics
5G base station deployment and advanced packaging proliferation are compressing dielectric performance requirements, forcing substrate suppliers to bridge halogen-free compliance with sub-3.5 Dk specifications while copper foil makers race below five-micron thickness thresholds.
Growth Catalysts
- Telecom infrastructure buildout:China's MIIT directives mandate domestic material certification for 5G procurement, accelerating high-frequency laminate qualification cycles.
- REACH substance restrictions:ECHA's tightening flame retardant limits compel resin system reformulation, creating first-mover premiums for compliant substrate portfolios.
- Advanced packaging migration:Ultra-thin electrodeposited copper below nine microns captures concentrated margin pools as chiplet architectures multiply interconnect layers.
Market Restraints
- Copper concentrate volatility:Rolled foil production depends on cathode supply tied to Chilean and Peruvian mining output, exposing margin compression during commodity spikes.
- Asian supply concentration:Taiwan and South Korea control over seventy percent of high-grade resin synthesis capacity, creating single-source vulnerability for European laminators.
- Technical performance ceiling:Standard FR-4 substrates hit thermal reliability limits above 150°C continuous operation, blocking adoption in power module applications.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor packaging attract laminate qualification programs from domestic substrate entrants.
- Automotive sensor arrays:Flexible circuit demand from lidar and camera modules creates bendable interconnect specifications beyond consumer electronics scale.
- EU Green Deal alignment:CSRD disclosure obligations favor suppliers with copper sourcing traceability and verified halogen-free supply chains.
Industry Challenges
- RF simulation talent scarcity:Electromagnetic modeling expertise for millimeter-wave substrate design concentrates among Japanese and US engineering pools, constraining European and Chinese product development timelines.
- Multi-jurisdiction certification lag:Parallel FCC equipment authorization, CE marking, and GB standard testing extends new material qualification to eighteen-plus months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Circuit Materials Market |
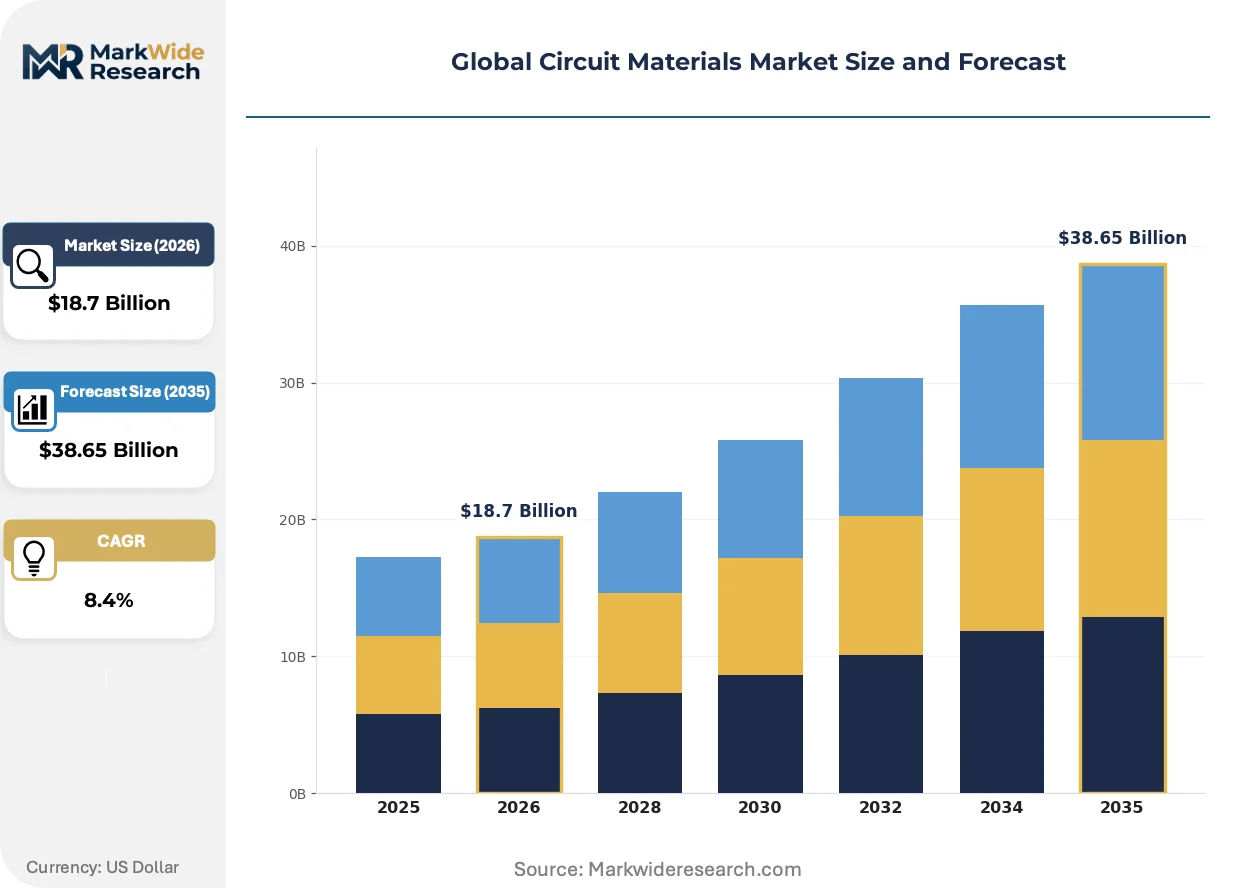
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Foil, Insulation Material, Adhesive, Substrate Technology: Flexible Circuit, Rigid Circuit, Hybrid Circuit, Printed Circuit End User: Consumer Electronics, Automotive, Industrial, Telecommunications Application: Mobile Devices, Home Appliances, Medical Equipment, Aerospace |
| Companies Covered | Kingboard Laminates Holdings Ltd, Shengyi Technology Co. Ltd, Mitsubishi Materials Corporation, Panasonic Corporation, DuPont, Rogers Corporation, Isola Group, Nan Ya Plastics Corporation, Sumitomo Bakelite Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Circuit Materials Market Emerging Trajectories
Substrate engineering is pivoting from standardized laminate stacks toward application-specific dielectric formulations, compressing product lifecycles while opening specialization premiums for compounders with captive resin synthesis.
Modified epoxy systems with thermoplastic toughening agents are consolidating position in high-layer-count server boards. Hyperscale datacenter operators specify these materials for signal integrity at 112 Gbps PAM4 modulation. The technology is consolidating procurement around qualified material lists that exclude commodity FR-4 suppliers.
EU F-Gas Regulation phase-down schedules are forcing fluoropolymer substrate makers to reformulate PTFE-based laminates with lower global warming potential blowing agents. Millimeter-wave base station suppliers in Germany and Scandinavia now require GWP-compliant material certificates. Japanese fluoropolymer specialists are accelerating alternative dielectric development to defend premium positioning.
Buyers are unbundling pre-preg and copper-clad laminate procurement to optimize inventory turns and reduce obsolescence risk. Contract manufacturers in Vietnam and Mexico are adopting consignment models where substrate vendors hold buffer stock at regional hubs. This pattern is most pronounced among automotive tier-one suppliers qualifying multiple laminate sources for single platform awards.
Global Circuit Materials Market Segmentation
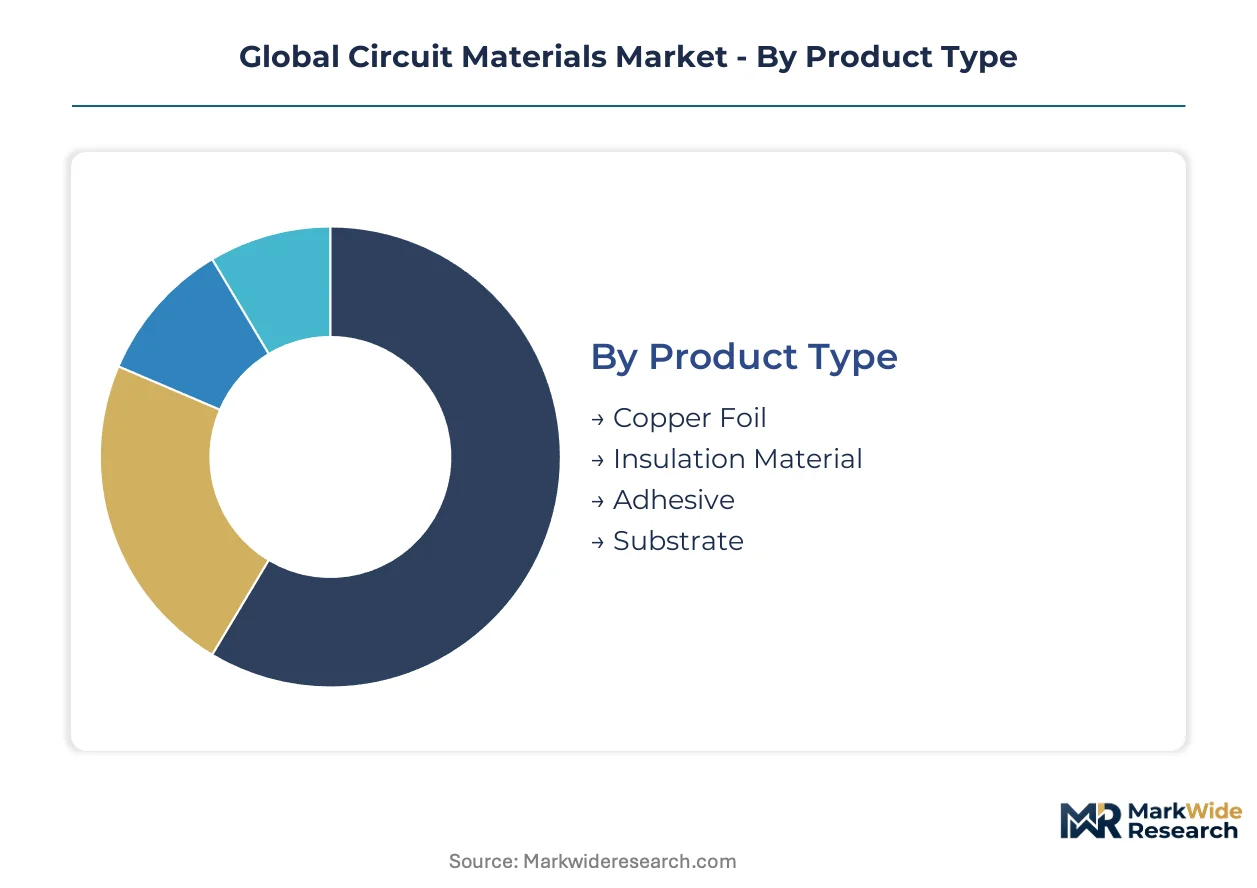
Circuit materials segment by physical function, manufacturing process, and performance tier. Procurement teams route specifications through these categories to match dielectric constant, thermal reliability, and mechanical flexibility requirements against end-use signal integrity demands.
Product Type:
Substrate formulations dominate value pools while copper foil segments split between electrodeposited and rolled varieties across cost tiers.
- Copper Foil:Electrodeposited varieties below nine microns capture concentrated margin pools in advanced packaging applications. Rolled foil production depends on cathode supply tied to Chilean and Peruvian mining output, exposing converters to commodity volatility during supply spikes.
- Substrate:Halogen-free and high thermal reliability grades command widening premiums over standard FR-4 equivalents in 5G base station and server board applications. China's MIIT directives mandate domestic material certification for telecom infrastructure procurement, accelerating qualification cycles for compliant laminators.
- Insulation Material:Modified epoxy systems with thermoplastic toughening agents consolidate position in high-layer-count server boards specified by hyperscale datacenter operators.
- Adhesive:Bonding layers engineered for precise dielectric constant and loss tangent specifications enable signal transmission integrity across flexible and rigid-flex constructions.
Today's leader: Substrate. Tomorrow's challenger: Copper Foil.
Technology:
Manufacturing processes diverge by mechanical flexibility requirements and layer count complexity, with bendable formats expanding most quickly in automotive and consumer applications.
- Flexible Circuit:Foldable consumer devices and automotive sensor arrays multiply bendable interconnect requirements beyond traditional rigid formats. Lidar and camera modules in electric vehicles create specifications that exceed consumer electronics scale for dynamic flex cycling durability.
- Printed Circuit:Standard multilayer boards remain the volume foundation across industrial control systems and home appliances, though procurement is shifting toward application-specific dielectric formulations that compress product lifecycles.
- Rigid Circuit:High-layer-count constructions specified for 112 Gbps PAM4 modulation in hyperscale datacenters exclude commodity FR-4 suppliers from qualified material lists.
- Hybrid Circuit:Rigid-flex combinations integrate multiple mechanical zones within single platform designs for aerospace and medical equipment applications requiring both stability and dynamic flex regions.
Flexible Circuit climbs the fastest as foldable form factors and automotive sensor proliferation reshape procurement specifications.
End User:
Telecommunications infrastructure and automotive electronics are displacing consumer electronics as the primary volume drivers for high-performance material grades.
- Telecommunications:5G base station deployment compresses dielectric performance requirements, forcing substrate suppliers to bridge halogen-free compliance with sub-3.5 Dk specifications. ECHA's tightening flame retardant limits under REACH compel resin system reformulation for European network equipment suppliers.
- Automotive:Sensor arrays for advanced driver assistance systems generate flexible circuit demand with specifications exceeding consumer electronics scale for temperature cycling and vibration resistance.
- Consumer Electronics:Mobile device and wearable procurement concentrates standard laminate volumes, though foldable formats are accelerating migration toward flexible circuit technologies.
- Industrial:Power module applications hit thermal reliability limits above 150°C continuous operation with standard FR-4 substrates, blocking adoption and forcing ceramic and metal-core alternatives.
Telecommunications commands premium pricing power. Automotive represents the steepest expansion trajectory for flexible format adoption.
Application:
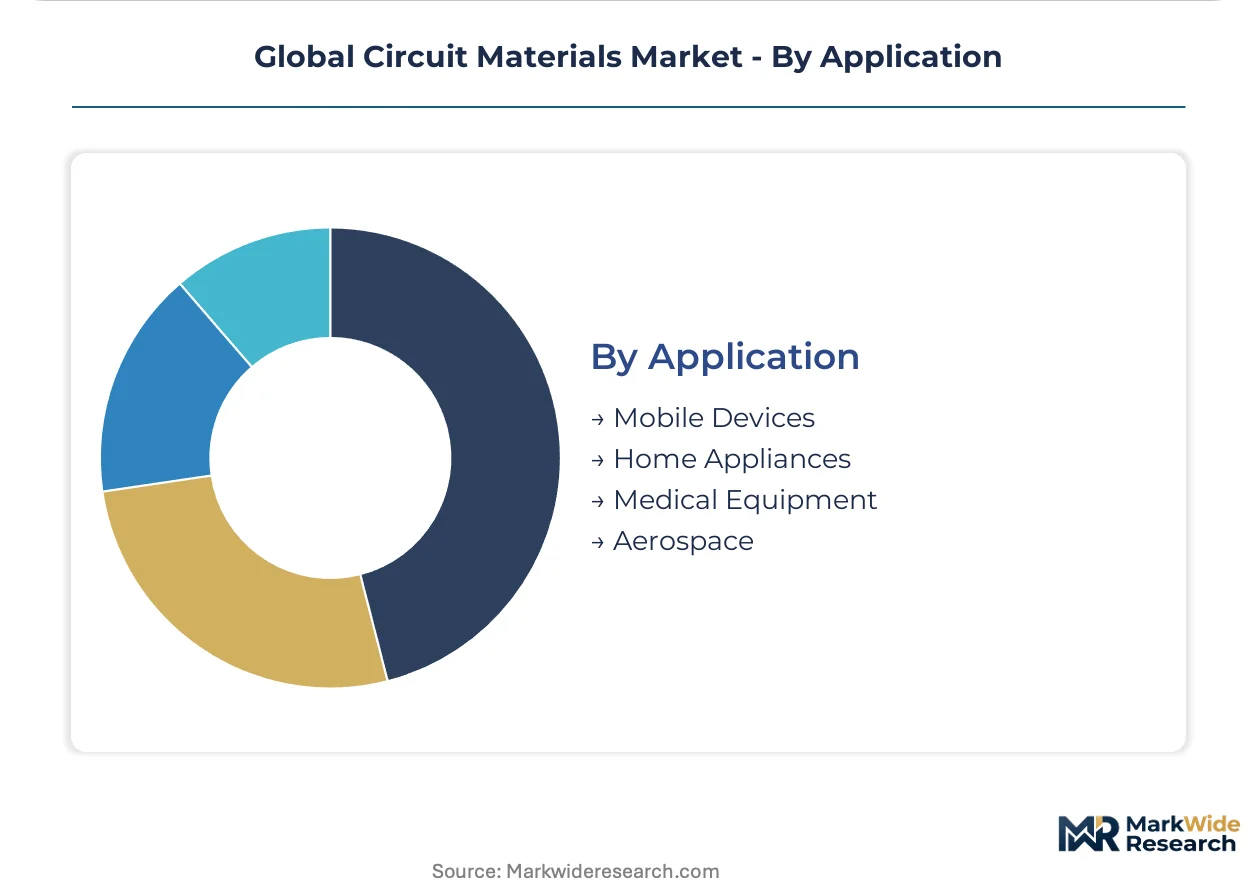
Medical and aerospace applications concentrate the highest certification burdens and longest qualification timelines, while mobile devices drive volume scale.
- Mobile Devices:Smartphone and tablet procurement routes through high-volume laminate specifications, with foldable formats accelerating flexible circuit adoption in flagship product tiers.
- Medical Equipment:Implantable and diagnostic device applications impose biocompatibility and long-term reliability standards that extend material qualification cycles. CE marking and FDA device authorization frameworks indirectly shape substrate performance thresholds through electromagnetic compatibility testing requirements.
- Aerospace:Satellite and avionics applications specify fluoropolymer substrates for millimeter-wave signal integrity at extreme thermal cycling ranges. EU F-Gas Regulation phase-down schedules force PTFE-based laminate reformulation with lower global warming potential blowing agents.
- Home Appliances:White goods and HVAC control systems represent stable volume demand for standard FR-4 and lower-tier laminate specifications with limited performance differentiation.
Mobile Devices anchor current volume. Medical Equipment and Aerospace concentrate margin premiums through qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Circuit materials manufacturing traces its industrial roots to post-war Japan and the subsequent rise of Taiwan's electronics foundry ecosystem. The sector's geographic footprint now spans raw material extraction, resin synthesis, laminate fabrication, and end-use assembly across distinct national clusters.
China
MIIT directives mandate domestic material certification for 5G base station procurement, compressing qualification timelines for local laminators. GB standards enforce halogen-free substrate specifications for telecom infrastructure. The Yangtze River Delta concentrates copper foil rolling capacity and resin synthesis plants serving both domestic and export demand.
Japan
Millimeter-wave base station deployment in Germany and Scandinavia drives fluoropolymer substrate orders with GWP-compliant material certificates. METI oversees chemical substance management aligning with REACH substance restrictions. Osaka-based compounders maintain captive resin synthesis for high-frequency dielectric formulations.
South Korea
Advanced packaging foundries in Seoul Capital Area multiply interconnect layer requirements for ultra-thin electrodeposited copper. The national chemical regulator enforces hazardous substance limits parallel to RoHS directives. Busan-Ulsan corridor hosts integrated laminate production feeding semiconductor packaging houses.
United States
FCC equipment authorization frameworks shape substrate performance thresholds through electromagnetic compatibility testing for network equipment. EPA oversees chemical safety in resin system manufacturing. Arizona and Texas clusters concentrate advanced packaging substrate qualification programs for domestic semiconductor fabs.
Germany
ECHA's tightening flame retardant limits under REACH compel resin reformulation for European network equipment suppliers. KBA automotive certification extends to sensor array substrates for lidar and camera modules. Bavaria hosts millimeter-wave substrate design engineering pools concentrated among specialized electromagnetic modeling firms.
Global Circuit Materials Market Vendor Landscape
Premium-margin players sit above commodity-margin players across dielectric performance tiers, with sub-3.5 Dk specifications commanding widening spreads over standard FR-4 equivalents. The vendor base splits between integrated resin-to-laminate producers and converters dependent on merchant resin supply. Three archetypes dominate: captive resin synthesis specialists, fluoropolymer technology inheritors, and scale-driven copper foil rollers. Competitive moves center on M&A for resin synthesis capacity and strategic partnerships for regional buffer stock positioning.
Among Asia-Pacific-based laminators, Kingboard Laminates Holdings Ltd and Shengyi Technology Co. Ltd exemplify integrated production archetypes with captive resin-to-laminate control. Panasonic Corporation occupies a position within the fluoropolymer substrate tier, leveraging decades of dielectric formulation heritage for millimeter-wave applications. These three anchors represent distinct competitive vectors: scale integration, high-speed material specialization, and premium-frequency positioning.
| Leading Market Players |
|---|
| Kingboard Laminates Holdings Ltd |
| Shengyi Technology Co. Ltd |
| Mitsubishi Materials Corporation |
| Panasonic Corporation |
| DuPont |
| Rogers Corporation |
| Isola Group |
| Nan Ya Plastics Corporation |
| Sumitomo Bakelite Co. Ltd |
| Others |
Supply Flow & Price Mechanics
ECHA's tightening flame retardant limits under REACH gate both qualified supply and premium-tier pricing access, as laminators with compliant resin systems capture widening spreads over standard FR-4 converters while non-compliant suppliers face procurement exclusion from European telecom infrastructure awards.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by dielectric performance grade and certification tier, with sub-3.5 Dk halogen-free substrates commanding substantial premiums over commodity equivalents. Price differentiation reflects REACH compliance status and copper foil thickness grade, with ultra-thin electrodeposited varieties below nine microns capturing concentrated margin pools. Cost compression in standard laminate tiers is intensifying because of cathode-linked copper volatility from Chilean and Peruvian mining output. Contract manufacturers in Vietnam and Mexico exhibit highest price sensitivity, while German millimeter-wave base station suppliers show lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Freight cost differentials between Asia-Pacific production hubs and regional buffer stock locations in Mexico and Vietnam are reshaping consignment model adoption among automotive tier-one suppliers. Supply concentrates in China, Taiwan, and South Korea, with the Yangtze River Delta anchoring copper foil rolling and resin synthesis capacity. Raw material dependencies draw from Chilean cathode supply, Japanese fluoropolymer resin, and South Korean high-grade epoxy systems. Single-source vulnerability pervades Taiwan and South Korea's control over seventy percent of high-grade resin synthesis capacity. Distribution runs through integrated resin-to-laminate producers and merchant-resin-dependent converters serving contract manufacturers and OEM qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Circuit Materials Market functions as a geographic-arbitrage play where European REACH compliance costs and Asian resin synthesis scale advantages create divergent margin structures across regional supply bases.
For Market Incumbents: Anticipate fluoropolymer substrate reformulation pressures from EU F-Gas Regulation phase-down schedules by accelerating alternative dielectric development with lower global warming potential blowing agents. Backward integration into captive resin synthesis defends margin position against merchant supply volatility from Taiwan and South Korea concentration. Prioritize qualification buffer stock positioning in Mexico and Vietnam to capture automotive tier-one supplier consignment model adoption. For New Entrants and Emerging Players: Contract manufacturers in India's PLI scheme semiconductor packaging corridor represent the most penetrable channel partner type for domestic laminate qualification programs. White-space targets include automotive sensor array substrates for lidar and camera modules with bendable interconnect specifications exceeding consumer electronics scale. A qualified material list insertion strategy bypasses direct incumbent competition in hyperscale datacenter procurement. For Investors and Strategic Acquirers: Roll-up economics work for integrated resin-to-laminate specialists because captive synthesis control commands widening premiums over converter-dependent competitors as qualification timelines compress. Long-term viability favors compounders with in-house fluoropolymer or high-speed low-loss material portfolios serving 5G infrastructure and advanced packaging migration. Watch for MIIT domestic certification mandates in China as inflection indicators for regional supply base restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive supply of high-grade epoxy systems insulates margins from Taiwan and South Korea concentration risk. |
| Regional Buffer Stock Positioning | Consignment hubs in Vietnam and Mexico capture automotive tier-one supplier procurement pattern shifts. |
| Alternative Fluoropolymer Development | GWP-compliant PTFE laminate reformulation defends German and Scandinavian millimeter-wave base station positioning. |
| Domestic Certification Qualification | MIIT-compliant substrate portfolios unlock China's 5G telecom infrastructure procurement mandates. |
| Flexible Circuit Capacity Expansion | Automotive sensor array specifications for lidar and camera modules exceed consumer electronics scale requirements. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with substrate procurement managers, resin synthesis plant engineers, laminate technical directors, and contract manufacturing executives with secondary validation from customs trade data, MIIT certification registries, ECHA substance restriction updates, and SEC filings from listed laminators and copper foil producers.
Historical trendline analysis across dielectric performance tiers, manufacturing process categories, and regional production clusters informs the projection framework, with segmentation dimensions spanning physical function, technology format, end-user industry, and application type. CAGRs derive from installed base growth rates in 5G infrastructure, advanced packaging layer counts, and automotive sensor proliferation throughout the forecast period, incorporating copper concentrate price volatility and regulatory compliance timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction expansion, EU F-Gas Regulation phase-down acceleration, and MIIT domestic certification mandate enforcement patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Chemicals
Electronic Wet Chemicals Market
Electronic Chemicals
Printed Electronic Materials Market
Electronic Chemicals
Liquid Soldering Flux Market
Electronic Chemicals
Global 5G EMI Materials Market
Electronic Chemicals
Global Electronic Materials and Chemicals Market
Electronic Chemicals
Silver Paste Market
Electronic Chemicals
Global Imaging Chemicals Market
Electronic Chemicals
Electronic Chemicals Market