
 Printed Electronic Materials Market | 2026-2036
Printed Electronic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Electronic Materials Market Analytics
The EU Green Deal is restructuring procurement criteria for electronics across member states, mandating lower embodied carbon and recyclable material content in public-sector purchasing. DuPont de Nemours, Inc. leverages its materials science portfolio to supply high-performance conductive inks for flexible circuit applications. BASF anchors European supply through its specialty chemicals division, focusing on sustainable polymer formulations for printed electronics substrates.
Printed electronic materials comprise functional inks, flexible substrates, and encapsulation layers formulated for additive deposition processes such as inkjet, screen, and gravure printing, typically achieving layer thicknesses below 50 micrometers for conductive traces. These materials enable the fabrication of lightweight, conformal electronic devices on polymer or paper substrates for applications requiring mechanical flexibility or low-cost disposable circuitry. Conductive inks currently dominate value capture due to silver and copper flake formulations commanding premium pricing, while dielectric inks represent the fastest-expanding category as multilayer printed device architectures proliferate. Inkjet printing technology leads R&D investment intensity, though screen printing sustains volume leadership in RFID antenna and solar cell metallization.
The European Chemicals Agency enforces REACH substance restrictions affecting solvent selection and nanoparticle labeling in conductive formulations, while the EU F-Gas Regulation phases out fluorinated compounds used in certain encapsulation chemistries. China's MIIT establishes GB standards for printed electronics manufacturing that condition market access for imported materials. The US EPA oversees VOC emissions from ink formulation facilities under the National Emission Standards for Hazardous Air Pollutants. Stakeholders must monitor evolving substance restriction schedules and certification requirements to anticipate reformulation costs and qualify alternative material platforms before compliance deadlines tighten.
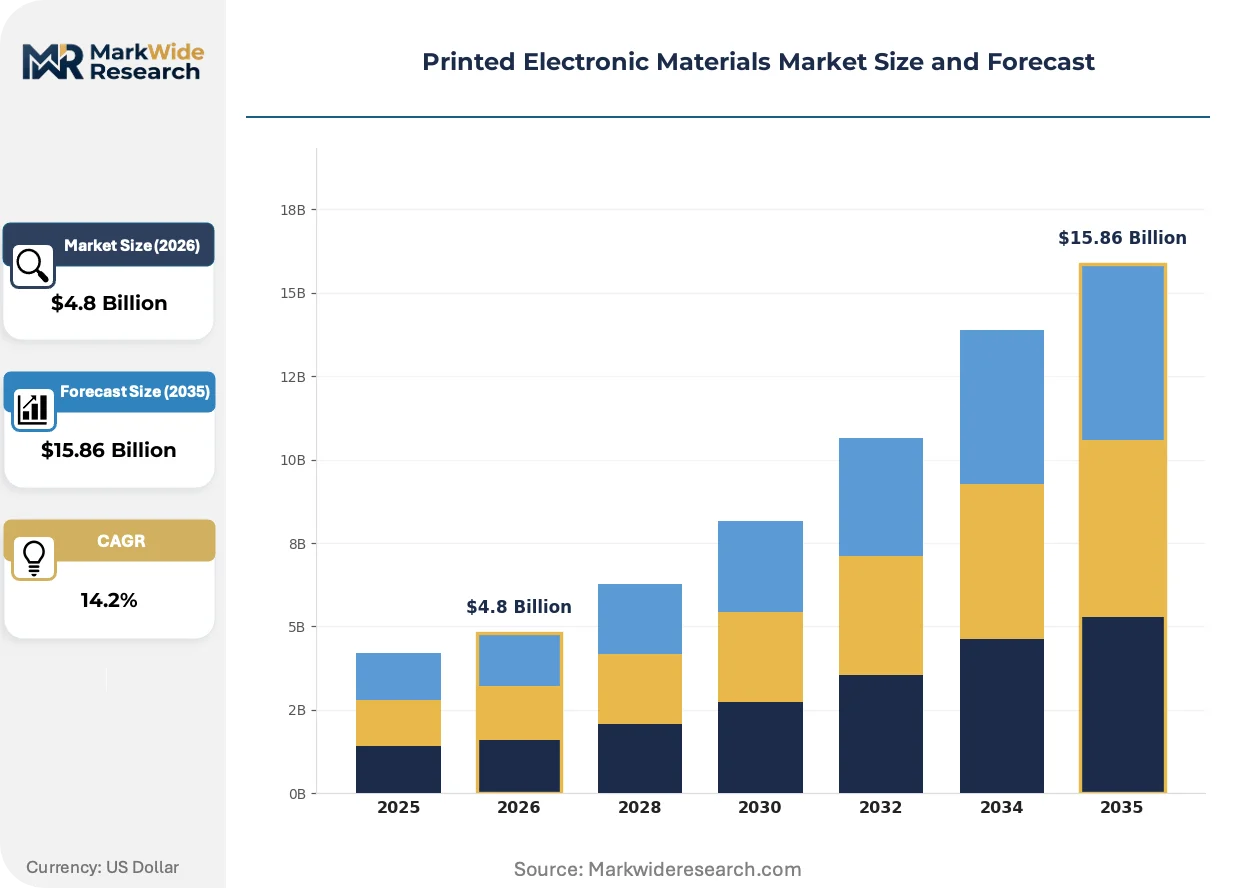
Market Dynamics
Flexible solar cell deployments in utility and building-integrated applications are accelerating material consumption while REACH restrictions in the European Union compel wholesale reformulation of conductive and dielectric inks toward halogen-free and low-VOC chemistries.
Growth Catalysts
- MIIT National Directives:China's Ministry of Industry and Information Technology prioritizes domestic printed electronics supply chains under advanced manufacturing mandates, driving localized capacity expansion and import substitution for functional inks and flexible substrates.
- Building-Integrated Photovoltaics:Utility-scale and architectural solar deployments are consuming printed electronic materials for lightweight, conformal photovoltaic modules that replace rigid silicon panels in facade and roofing applications.
- Inkjet R&D Intensity:Additive deposition technology advancement is integrating precision layer control below 50 micrometers, enabling multilayer device architectures that expand addressable applications in disposable medical sensors and smart packaging.
Market Restraints
- Silver Flake Input Volatility:Conductive ink formulations depend on silver and copper flake commodities subject to precious metal price swings, compressing margins for ink suppliers and constraining pass-through pricing flexibility.
- European Supply Concentration:BASF and specialty chemical anchors in Germany and France control sustainable polymer substrate formulations, creating qualification bottlenecks for new entrants seeking REACH-compliant material platforms.
- Fluorinated Encapsulation Phase-Out:The EU F-Gas Regulation is eliminating fluorinated compounds from certain encapsulation chemistries, forcing premature obsolescence of established barrier layer formulations before alternatives achieve equivalent moisture resistance.
Strategic Opportunities
- India Electronics Manufacturing:Production-Linked Incentive schemes for semiconductor and display fabrication are creating first-mover advantages for conductive ink suppliers qualifying BIS standards for domestic printed circuit integration.
- Healthcare Wearable Convergence:Biosensor patch applications are merging printed electronics with microfluidic structures, opening premium pricing tiers for disposable diagnostic devices in chronic disease monitoring.
- EU Green Deal Procurement:Public-sector purchasing mandates for lower embodied carbon and recyclable material content are rewriting tender specifications, advantaging suppliers with certified circular material flows and regional recycling partnerships.
Industry Challenges
- Formulation Chemist Scarcity:The intersection of materials science, rheology, and printing process engineering requires specialized talent pools concentrated in Germany, Japan, and Massachusetts, limiting scaling velocity for emerging market facilities.
- REACH Compliance Timelines:European Chemicals Agency substance restriction schedules compress reformulation windows to 18-24 months, forcing parallel development tracks that strain R&D budgets and delay product launches.
- Multilayer Registration Accuracy:Achieving sub-micron alignment between successive printed layers demands capital-intensive inspection systems and process control infrastructure that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Electronic Materials Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Ink, Dielectric Ink, Substrates, Encapsulation Materials Application: Wearable Devices, Smart Packaging, RFID Tags, Solar Cells End User: Consumer Electronics, Automotive, Healthcare, Aerospace Technology: Inkjet Printing, Screen Printing, Flexographic Printing, Gravure Printing |
| Companies Covered | DuPont de Nemours, Inc., BASF, Henkel AG & Co. KGaA, NovaCentrix, Agfa-Gevaert Group, DIC Corporation, Sun Chemical, E Ink Holdings Inc., Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Electronic Materials Market Evolving Landscape
Printed electronic materials are converging with sustainability mandates and precision manufacturing requirements, reshaping how functional inks, substrates, and encapsulation layers are formulated, qualified, and deployed across end-use verticals.
Copper-nanoparticle conductive inks are displacing silver flake formulations in cost-sensitive RFID antenna and solar cell metallization applications. Tier-one solar manufacturers in China and South Korea are adopting copper inks at pilot scale for back-contact cell architectures. This transition is integrating lower-material-cost structures into high-volume production lines previously locked into precious-metal supply chains.
REACH substance restrictions are eliminating halogenated solvents and mandating nanoparticle hazard labeling across conductive ink portfolios. Formulators are accelerating water-based and bio-derived carrier fluid development to maintain European market access. Dielectric ink categories face the steepest compliance burden, as multilayer architectures multiply the regulatory exposure points per finished device.
Automotive OEMs are unbundling printed sensor procurement from traditional tiered electronics supply chains, establishing direct material qualification relationships with ink and substrate specialists. This disintermediation compresses specification cycles from 36 months to 18 months for interior human-machine interface applications. German and Japanese vehicle manufacturers are most advanced in this restructuring, driven by cabin electrification and smart surface integration timelines.
Printed Electronic Materials Market Segmentation
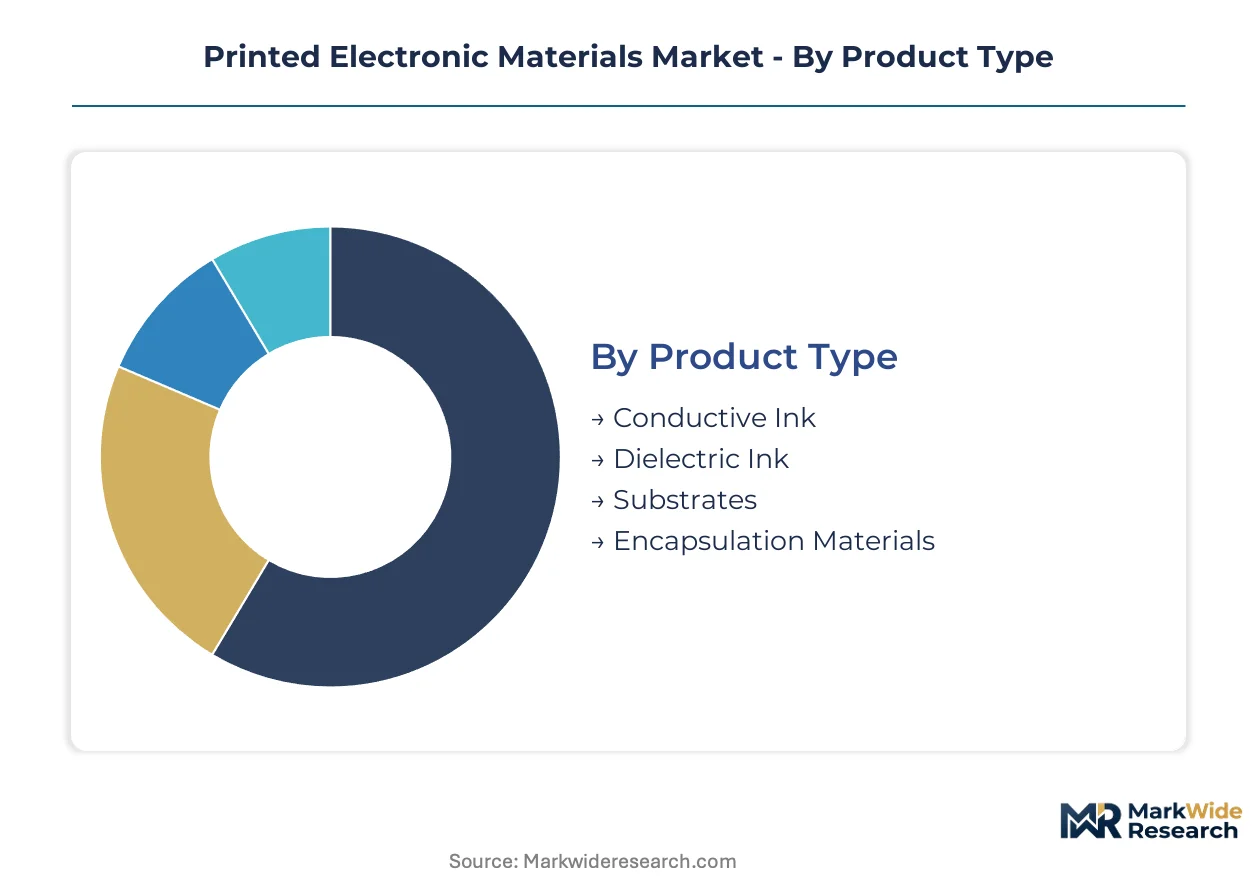
Segmentation in printed electronic materials reveals how functional performance requirements, deposition precision, and end-use durability demands fragment supply chains. Each dimension—product chemistry, application stress factors, user industry specifications, and printing mechanics—creates distinct qualification barriers and margin structures.
Product Type:
Silver flake formulations concentrate value capture in conductive ink supply, while dielectric chemistries face the steepest REACH-driven reformulation costs.
- Conductive Ink:Silver and copper flake suspensions dominate RFID antenna and solar cell metallization, with Chinese solar manufacturers piloting copper-nanoparticle alternatives to reduce precious metal dependency. REACH restrictions on nanoparticle labeling are forcing accelerated water-based carrier development.
- Dielectric Ink:Multilayer printed architectures multiply regulatory exposure points per device, making this category the fastest-expanding by volume while bearing the heaviest compliance burden for halogen-free and low-VOC reformulation.
- Substrates:Sustainable polymer formulations from German and French specialty chemical anchors control European qualification pathways.
- Encapsulation Materials:EU F-Gas Regulation is eliminating fluorinated barrier compounds before moisture-resistant alternatives achieve parity.
Today's leader: Conductive Ink. Tomorrow's challenger: Dielectric Ink.
Application:
Application selection determines mechanical flexibility requirements, environmental exposure tolerance, and device lifetime specifications that cascade through material choices.
- Solar Cells:Utility-scale and building-integrated photovoltaic deployments consume printed materials for lightweight conformal modules replacing rigid silicon in facade and roofing installations. Chinese and South Korean tier-one manufacturers drive copper ink adoption at pilot scale.
- RFID Tags:Cost-sensitive antenna metallization is shifting from silver to copper-nanoparticle inks in high-volume logistics and retail tracking applications.
- Wearable Devices:Biosensor patch convergence with microfluidic structures opens premium pricing tiers for disposable diagnostic platforms in chronic disease monitoring.
- Smart Packaging:Temperature and freshness indicators require low-cost disposable circuitry on paper substrates with limited shelf-life requirements.
Solar Cells anchor current volume. Wearable Devices are climbing the fastest as healthcare convergence accelerates.
End User:
End user industry selection dictates certification depth, qualification cycle length, and direct versus tiered procurement relationships.
- Automotive:German and Japanese OEMs are disintermediating traditional tiered electronics supply chains, establishing direct material qualification with ink specialists and compressing specification cycles from 36 months to 18 months for cabin human-machine interfaces.
- Healthcare:Chronic disease monitoring applications merge printed electronics with microfluidic structures, creating premium disposable diagnostic segments with stringent biocompatibility requirements.
- Consumer Electronics:Smart surface integration and flexible display backplanes drive demand for sub-50-micrometer precision layer control.
- Aerospace:Conformal sensor networks and lightweight wiring applications prioritize reliability certification over cost minimization.
Automotive leads procurement restructuring. Healthcare shows the steepest expansion trajectory as diagnostic disposables scale.
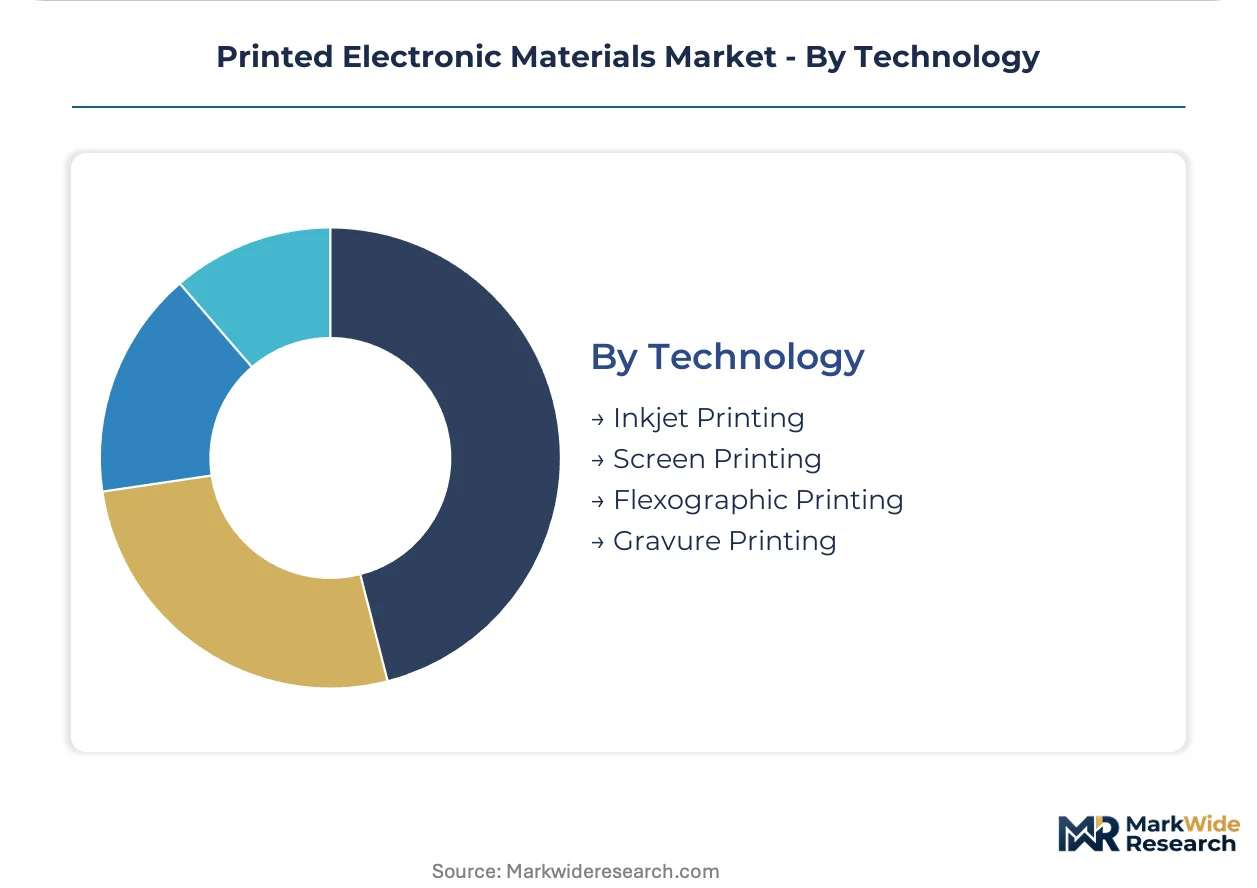
Technology:
Technology selection balances capital intensity, throughput economics, and registration precision requirements for multilayer device architectures.
- Screen Printing:Volume leadership persists in RFID antenna and solar cell metallization where 50-micrometer-plus trace widths suffice and capital barriers remain lowest for emerging market converters.
- Inkjet Printing:R&D investment intensity concentrates here as additive deposition achieves precision layer control below 50 micrometers, enabling multilayer architectures for disposable medical sensors.
- Flexographic Printing:Roll-to-roll throughput economics favor high-volume packaging applications with moderate resolution requirements.
- Gravure Printing:Long-run consistency and ink film uniformity suit security printing and high-value decorative electronics.
Screen Printing holds volume dominance. Inkjet Printing is gaining share fastest as precision requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Printed electronic materials originated in German and Japanese chemical laboratories during the 1980s, where conductive polymer research first achieved screen-printable formulations. Industrial scaling migrated to East Asian manufacturing centers through the 2000s as consumer electronics demand concentrated production capacity in China, South Korea, and Taiwan.
China
Utility-scale solar deployments and building-integrated photovoltaics consume the majority of Asia-Pacific conductive ink volumes. MIIT national directives prioritize domestic supply chains for functional inks and flexible substrates under advanced manufacturing mandates. The Yangtze River Delta hosts the densest concentration of printed electronics converters, with Suzhou and Shanghai anchoring pilot-scale copper-nanoparticle ink adoption for back-contact solar cell architectures.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria disintermediate traditional tiered electronics suppliers, establishing direct qualification relationships with ink specialists for cabin human-machine interfaces. ECHA REACH substance restrictions on halogenated solvents and nanoparticle labeling compress reformulation windows to 18-24 months. The Rhine-Ruhr chemical corridor anchors European supply of sustainable polymer substrates through specialty chemical anchors controlling qualification pathways.
United States
Greater Boston and Massachusetts concentrate formulation chemist talent pools at the intersection of materials science, rheology, and printing process engineering. EPA National Emission Standards for Hazardous Air Pollutants oversee VOC emissions from ink formulation facilities. The Pacific Northwest hosts R&D intensity for inkjet printing precision layer control below 50 micrometers, enabling multilayer architectures for disposable medical sensors.
Japan
Automotive and consumer electronics OEMs in the Kanto and Kansai regions drive demand for sub-50-micrometer precision in flexible display backplanes. METI industrial policy supports domestic printed electronics manufacturing equipment and materials development. Nagoya-area chemical companies supply high-performance encapsulation materials facing transition pressure from fluorinated compound phase-out timelines.
South Korea
Tier-one solar manufacturers in Gyeonggi-do and Chungcheong provinces pilot copper-nanoparticle conductive inks to reduce precious metal dependency in back-contact cell production. MFDS biocompatibility requirements shape qualification protocols for wearable biosensor patches merging printed electronics with microfluidic structures. The Seoul Capital Area concentrates display and semiconductor fabrication driving flexible circuit substrate demand.
Printed Electronic Materials Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory certification depth. The vendor base stratifies between integrated chemical conglomerates with captive raw material positions and specialized ink formulators dependent on merchant silver flake and polymer supply. Three archetypes dominate: diversified materials science conglomerates leveraging cross-divisional R&D, specialty chemical houses focused on sustainable substrate formulations, and precision deposition technology integrators. Competitive moves concentrate on portfolio diversification into adjacent functional material categories and strategic partnerships with automotive OEMs seeking direct supplier relationships.
Among diversified materials science conglomerates, DuPont de Nemours, Inc. and BASF occupy positions spanning conductive inks through encapsulation materials. DuPont exemplifies the premium-tier archetype through its materials science portfolio breadth. BASF anchors European supply chains through its specialty chemicals division. Henkel AG & Co. KGaA represents the adhesive and functional coating integration vector, sitting within the tier pursuing automotive and electronics assembly qualification. These three conglomerates collectively illustrate how cross-divisional R&D scale and geographic manufacturing footprint determine competitive positioning in a market where REACH compliance and MIIT certification create divergent regional qualification barriers.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| BASF |
| Henkel AG & Co. KGaA |
| NovaCentrix |
| Agfa-Gevaert Group |
| DIC Corporation |
| Sun Chemical |
| E Ink Holdings Inc. |
| Mitsubishi Chemical Corporation |
| Others |
Value Network & Pricing Analysis
Captive silver flake sourcing from Japanese and South Korean refiners anchors premium-tier conductive ink pricing power, while outsourced polymer substrate supply exposes mid-tier formulators to BASF and Mitsubishi Chemical margin capture in European and Asian qualification pathways.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant water-based formulations from solvent-borne imports and commodity copper-nanoparticle alternatives. Price differentiation hinges on ECHA certification depth and volume scale, with automotive OEM direct procurement compressing margins in premium tiers while RFID logistics buyers drive cost-down pressure in economy segments. Pricing pressure stems from silver commodity volatility, with solar cell manufacturers in China and South Korea accelerating copper ink substitution. Healthcare wearable buyers show least price sensitivity due to biocompatibility premium requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and French specialty chemical anchors controlling sustainable polymer substrate formulations for European automotive qualification. Raw material dependencies draw from Chinese silver flake refiners, Japanese copper nanoparticle suppliers, and South Korean display-grade substrate manufacturers. Supply chain risk centers on REACH substance restriction timelines compressing reformulation windows before alternative chemistries achieve performance parity. Distribution runs through regional chemical distributors qualified for hazardous materials handling, with direct OEM relationships displacing traditional tiered electronics channels in automotive and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with automotive and healthcare demand shifting toward premium specifications that reward REACH-compliant, water-based formulation capabilities over commodity solvent-borne alternatives.
For Market Incumbents: Hedge silver flake exposure through pilot-scale copper-nanoparticle partnerships with Chinese and South Korean solar manufacturers, while deepening backward integration into bio-derived carrier fluid supply to defend margin position against REACH-driven reformulation cost spikes. Prioritize certification investment in ECHA-compliant halogen-free dielectric portfolios before compliance deadlines tighten.
For New Entrants and Emerging Players: Mid-scale Indian electronics converters underserved by qualified conductive ink supply present immediate white-space opportunity, with Production-Linked Incentive schemes creating first-mover advantages for BIS-standard formulations. Target wearable biosensor patch applications merging printed electronics with microfluidic structures, where premium pricing tiers offset qualification burden. Pursue direct automotive OEM qualification relationships disintermediating traditional tiered supply chains.
For Investors and Strategic Acquirers: Roll-up economics work for specialized dielectric ink formulators because multilayer device architectures multiply regulatory exposure points per finished device, consolidating compliance burden onto scaled platforms. Five-to-ten year viability favors targets with captive water-based chemistry capabilities and established ECHA registration dossiers. Watch copper-nanoparticle ink performance parity in back-contact solar cell architectures as inflection signal for silver flake demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Derived Carriers | REACH halogen-free mandates in Germany and France compel captive supply of sustainable carrier fluids. |
| Copper-Nanoparticle Ink Scale-Up | Chinese and South Korean solar manufacturers pilot alternatives to reduce precious metal dependency. |
| Direct OEM Qualification Programs | Automotive manufacturers in Baden-Württemberg compress specification cycles from 36 months to 18 months. |
| Water-Based Dielectric Portfolio Expansion | Multilayer architectures multiply ECHA regulatory exposure points per finished device. |
| India PLI-Aligned BIS Certification | Electronics manufacturing incentives create first-mover advantages for qualified conductive ink suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with conductive ink formulators, automotive OEM material qualification leads, chemical distribution channel partners, and ECHA regulatory affairs specialists with secondary validation from SEC 10-K filings, Cefic specialty chemical reports, Chinese customs trade data, and MIIT GB standard documentation. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across silver flake consumption data and solar cell metallization line deployments.
Historical reference periods anchored the projection horizon to observed capacity expansion cycles and regulatory compliance timeline patterns across the European Union, China, and Japan. Segmentation dimensions modeled include product chemistry tier, end-use application stress factors, deposition technology precision requirements, and regional qualification pathway clusters. CAGRs derived from fitted growth curves incorporating MIIT domestic supply chain directives, EU Green Deal procurement mandates, and copper-nanoparticle ink adoption rates in tier-one solar manufacturing.
Underlying measurement precision varies by segment; conductive ink volume estimates carry tighter precision than emerging dielectric ink categories where REACH reformulation timelines introduce qualification uncertainty. Forecasts reflect assumptions around ECHA substance restriction schedules and MIIT certification pathway evolution, with silver commodity volatility and fluorinated encapsulation phase-out timelines representing specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Chemicals
Electronic Wet Chemicals Market
Electronic Chemicals
Global Imaging Chemicals Market
Electronic Chemicals
Electronic Chemicals Market
Electronic Chemicals
Global 5G EMI Materials Market
Electronic Chemicals
Global Electronic Materials and Chemicals Market
Electronic Chemicals
Liquid Soldering Flux Market
Electronic Chemicals
Global Circuit Materials Market
Electronic Chemicals
Silver Paste Market