
 Global 5G EMI Materials Market | 2026-2036
Global 5G EMI Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global 5G EMI Materials Market Analysis
Asian polymer compounders is realigning capacity toward high-frequency shielding grades to serve 5G base station OEMs. Laird Performance Materials leverages its ferrite composite expertise to dominate North American telecom supply chains. Henkel AG & Co. KGaA sustains adhesive EMI portfolio leadership through automotive qualification programs. Nitto Denko Corporation anchors Asian consumer electronics shielding with precision film manufacturing.
5G EMI materials encompass electrically conductive substances engineered to attenuate electromagnetic interference across sub-6 GHz and millimeter-wave spectra, typically incorporating nickel-graphite fillers, silver-coated copper particles, or multi-layered ferrite-polymer matrices processed through calendering or vapor deposition. These materials prevent signal degradation in densely packed RF architectures where wavelength compression intensifies crosstalk susceptibility. Composite materials lead product type revenue due to tunable permittivity and thermal stability in antenna-in-package modules. Telecommunications Equipment application demand outpaces other segments as massive MIMO arrays multiply shielding points per installation. Passive EMI Shielding technology occupies the largest technology share while active cancellation coatings represent the fastest-expanding margin pool for specialized suppliers.
FCC equipment authorization rules in the United States mandate demonstrated electromagnetic compatibility for 5G CPE and infrastructure hardware, directly conditioning material selection by OEM designers. ECHA REACH restrictions on halogenated flame retardants and EU RoHS substance limits are forcing reformulation of legacy shielding compounds across European supply chains. China's MIIT radio transmission equipment certification and GB standard compliance requirements shape domestic procurement specifications for base station manufacturers. Stakeholders must monitor evolving spectrum allocations and corresponding shielding effectiveness thresholds as regulatory bodies finalize next-band frameworks.
Market Dynamics
Massive MIMO antenna densification is compressing wavelength tolerances and multiplying shielding points per base station, forcing material suppliers to engineer higher permittivity grades at thinner form factors.
Growth Catalysts
- MIIT certification mandates:China's radio transmission equipment rules require demonstrated electromagnetic compatibility for domestic 5G infrastructure, pulling nickel-graphite composites into base station procurement specifications.
- Millimeter-wave spectrum activation:Sub-6 GHz saturation is pushing carriers toward 28 GHz and 39 GHz bands where ferrite-polymer matrices attenuate interference more effectively than legacy metal enclosures.
- Antenna-in-package integration:Smartphone OEMs are embedding shielding layers directly into RF modules, creating specification pull for vapor-deposited multi-layer films.
Market Restraints
- Silver-coated copper input volatility:Precious metal price swings compress margin predictability for conductive filler compounders serving high-frequency grades.
- East Asian supply concentration:Precision calendering capacity clusters in Japan and South Korea, exposing telecom OEMs to single-source disruption risks during regional logistics constraints.
- REACH substance restrictions:ECHA halogenated flame retardant limits force European compounders to reformulate legacy shielding compounds, extending qualification timelines for RoHS-compliant alternatives.
Strategic Opportunities
- India's delayed 5G spectrum auction completion:Domestic base station deployment acceleration will outpace local EMI material production, opening import substitution windows for qualified suppliers.
- Active cancellation coating convergence:Integration of ferrite composites with real-time adaptive algorithms enables dynamic interference suppression in dense urban small-cell grids.
- Automotive V2X qualification pipelines:NHTSA vehicle-to-everything communication mandates are extending material specifications from telecom into transportation shielding applications.
Industry Challenges
- Millimeter-wave test engineer scarcity:Shielding effectiveness validation above 24 GHz requires specialized anechoic chamber expertise that outstrips current training pipeline output.
- Dual certification timeline compression:FCC equipment authorization and MIIT radio transmission approval cycles must run in parallel to meet synchronized global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 5G EMI Materials Market |
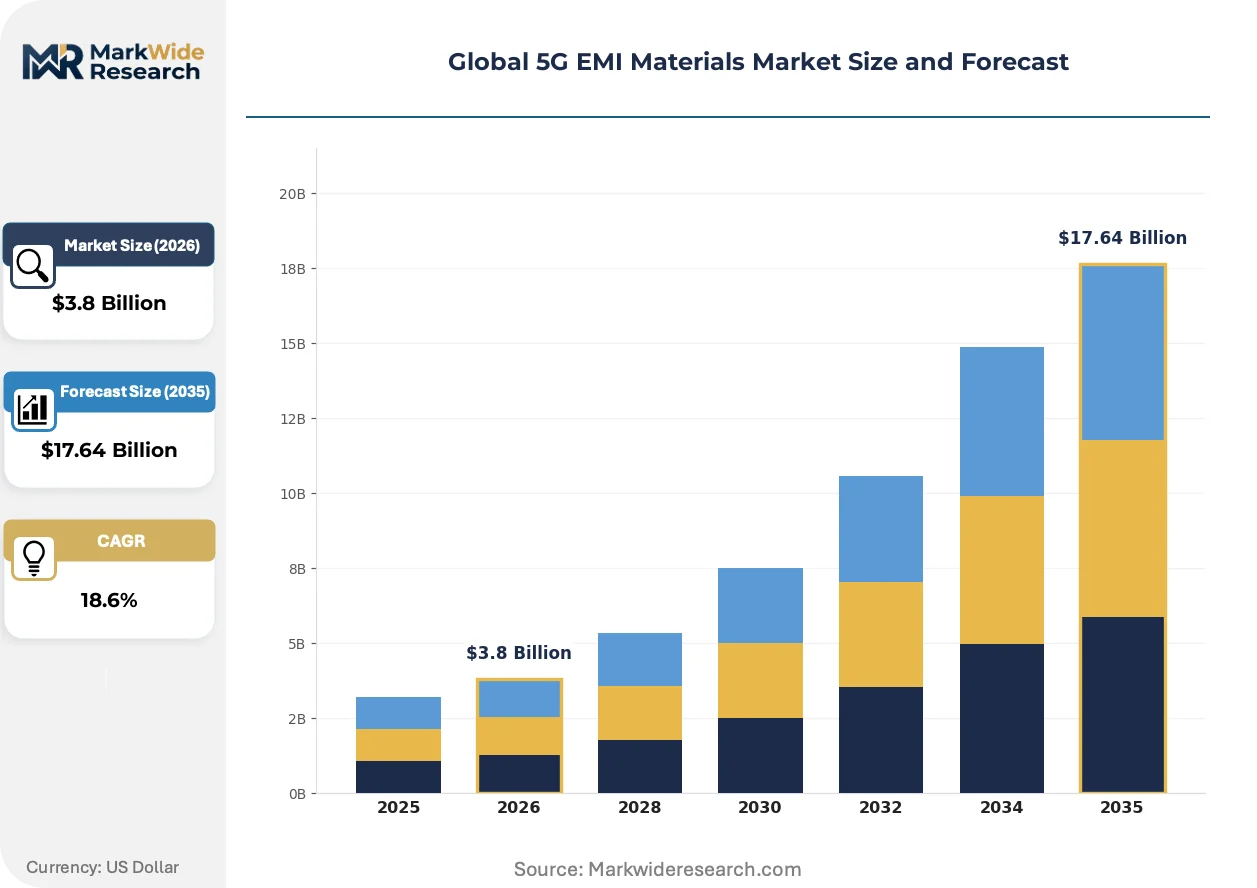
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Polymers, Composite Materials, Metal Foils, Shielding Films Application: Automotive Electronics, Telecommunications Equipment, Consumer Devices, Industrial Solutions End User: Aerospace, Military, Telecommunications, Healthcare Technology: Passive EMI Shielding, Active EMI Shielding, Coatings, Films |
| Companies Covered | Laird Performance Materials, 3M Company, DuPont de Nemours, Inc., Parker Hannifin Corporation, Henkel AG & Co. KGaA, Rohm Semiconductor, Honeywell International Inc., Nitto Denko Corporation, Kitagawa Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 5G EMI Materials Market Emerging Trajectories
Material architectures are bifurcating between ultra-thin conformable films for consumer devices and thermally conductive rigid composites for outdoor infrastructure, with processing methods diverging accordingly.
Multi-layered ferrite-polymer matrices with tunable magnetic permeability are rewriting shielding effectiveness benchmarks in antenna-in-package modules. Smartphone OEMs are qualifying these materials at 18-month compressed cycles versus legacy 36-month metal enclosure approvals. The technology is compressing vertical clearance requirements while maintaining attenuation performance across 28-39 GHz bands.
ECHA REACH restrictions on halogenated flame retardants are forcing compound reformulation across European supply chains. Shielding material producers must substitute brominated additives with phosphorus-nitrogen synergists without degrading thermal conductivity. German automotive and telecom OEMs are responding by tightening supplier qualification protocols and extending pre-production validation periods.
Carrier procurement teams are consolidating qualified material vendors into three-tier performance categories. Direct contracts with compounders are displacing distributor-mediated purchasing for high-volume base station programs. This concentration is most visible in China where MIIT-certified domestic producers capture preferential placement on provincial operator procurement lists.
Global 5G EMI Materials Market Segmentation
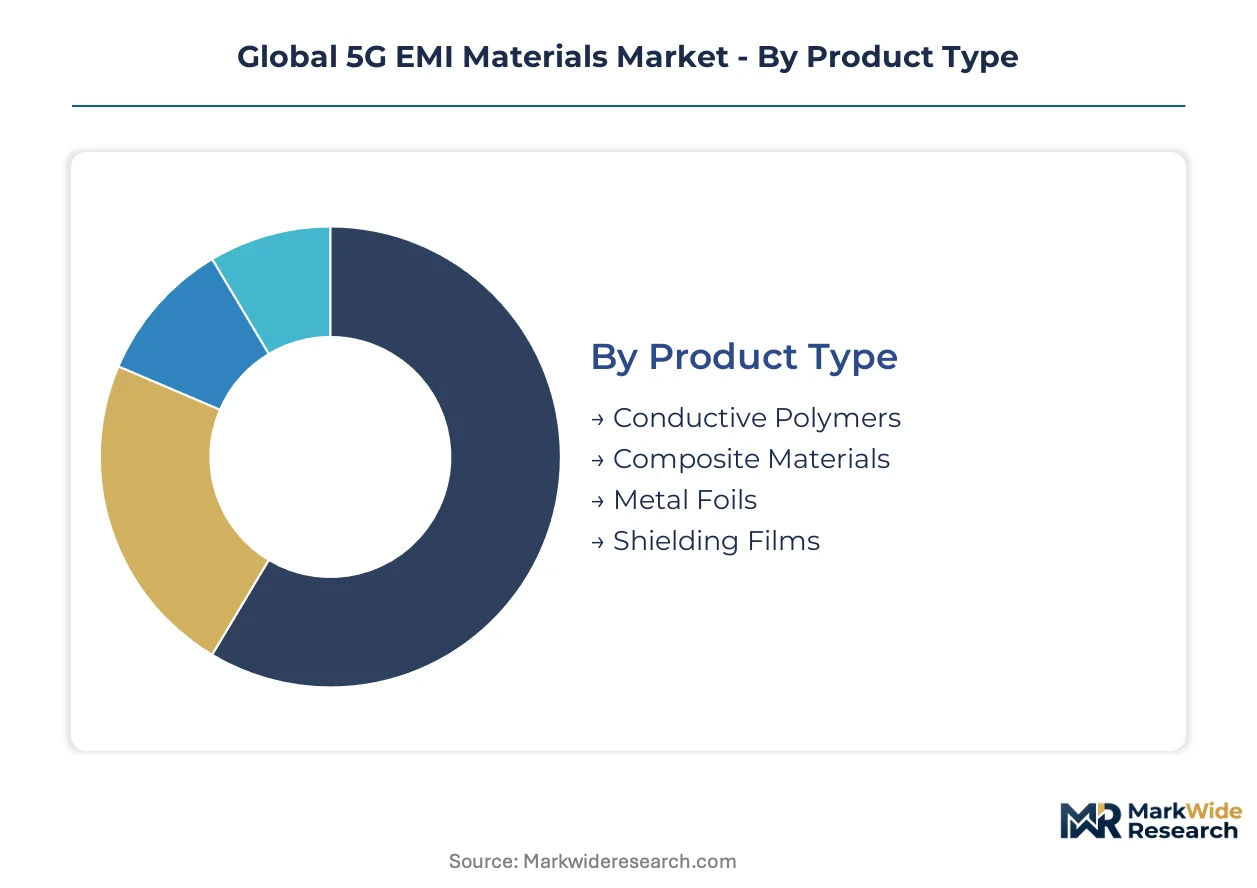
5G EMI materials exhibit divergent specification requirements across deployment contexts. Base station infrastructure demands thermal-mechanical durability while consumer devices prioritize conformability and weight reduction. Understanding these trade-offs clarifies procurement patterns and margin structures.
Product Type:
Customization intensity varies sharply across this category, from commodity metal foils to engineered composite matrices requiring iterative OEM co-development.
- Composite Materials:Multi-layered ferrite-polymer matrices deliver tunable permittivity with thermal stability for antenna-in-package modules. Demand concentrates in Chinese base station manufacturing where MIIT certification mandates specify nickel-graphite formulations for domestic 5G infrastructure deployments.
- Conductive Polymers:Thermoplastic compounds loaded with silver-coated copper or carbon fillers enable conformable shielding for curved device enclosures. Smartphone OEMs in South Korea and Taiwan are pulling these materials into millimeter-wave handset designs as wavelength compression intensifies crosstalk susceptibility.
- Metal Foils:Copper and aluminum sheets provide cost-effective baseline shielding for legacy sub-6 GHz installations.
- Shielding Films:Vapor-deposited multi-layer structures serve ultra-thin consumer electronics applications.
Most installed capacity flows through Composite Materials. Expansion is steepest in Conductive Polymers.
Application:
Cost tier separation distinguishes outdoor infrastructure from indoor consumer deployments, with qualification timelines and volume economics diverging accordingly.
- Telecommunications Equipment:Massive MIMO arrays multiply shielding points per base station installation. China's provincial operators are consolidating procurement around three-tier vendor categories, with direct compounder contracts displacing distributor channels for high-volume programs.
- Automotive Electronics:NHTSA vehicle-to-everything communication mandates are extending material specifications from telecom into transportation shielding applications. German and Japanese automotive OEMs are running parallel FCC and MIIT certification cycles to synchronize global V2X module launches.
- Consumer Devices:Smartphone and wearable manufacturers drive vapor-deposited film specifications.
- Industrial Solutions:Factory automation and smart grid deployments utilize ruggedized shielding enclosures.
Volume concentration sits with Telecommunications Equipment. Margin expansion is strongest in Automotive Electronics.
End User:
Customer type fragmentation separates price-sensitive commercial telecom from specification-rigid aerospace and military procurement channels.
- Telecommunications:Carrier procurement teams are tightening qualified vendor lists across China, Japan, and Germany. Domestic producers with MIIT certification capture preferential placement on provincial operator lists, while European compounders face extended timelines from ECHA REACH reformulation requirements.
- Military:Tempest and MIL-STD-285 shielding effectiveness standards demand specialized ferrite composites with documented supply chain provenance. US and UK defense contractors are qualifying alternative sources as East Asian calendering capacity concentration creates single-source disruption exposure.
- Aerospace:Commercial aviation connectivity systems require flame-retardant shielding meeting FAA fireworthiness criteria.
- Healthcare:MRI and diagnostic equipment manufacturers specify non-magnetic interference solutions.
Procurement scale favors Telecommunications. Specification stringency peaks with Military.
Technology:
Maturity gradients separate established passive architectures from emerging active cancellation approaches requiring embedded sensor integration.
- Passive EMI Shielding:Ferrite composites and conductive enclosures dominate current installations through proven reliability and lower system complexity. Japanese and South Korean precision calendering capacity anchors global supply, though logistics constraints during regional disruptions expose OEMs to allocation risk.
- Active EMI Shielding:Real-time adaptive algorithms integrated with ferrite matrices enable dynamic interference suppression in dense urban small-cell grids. US and Chinese suppliers are converging on this technology for 28-39 GHz millimeter-wave deployments where passive structures face physical size constraints.
- Coatings:Spray-applied conductive layers serve retrofit and repair applications.
- Films:Roll-to-roll processed shielding layers support high-throughput consumer electronics manufacturing.
Revenue share concentrates in Passive EMI Shielding. Technology investment is shifting toward Active EMI Shielding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes nickel-graphite composites at volumes exceeding German procurement by a factor of three, while Japanese precision calendering capacity anchors the high-frequency film segment. Regulatory divergence across MIIT, FCC, and ECHA frameworks conditions material qualification timelines.
China
Provincial operators in Guangdong and Jiangsu consolidate procurement around MIIT-certified domestic compounders. The Ministry of Industry and Information Technology mandates electromagnetic compatibility demonstration for all radio transmission equipment, pulling nickel-graphite formulations into base station specifications. Shenzhen and Dongguan manufacturing clusters host antenna-in-package module producers driving vapor-deposited film demand.
United States
FCC equipment authorization rules mandate demonstrated electromagnetic compatibility for 5G CPE and infrastructure hardware. Carrier deployment of 28 GHz and 39 GHz millimeter-wave bands accelerates ferrite-polymer matrix consumption. Texas and California engineering centers concentrate RF architecture design teams specifying shielding effectiveness thresholds.
Germany
ECHA REACH restrictions on halogenated flame retardants force compound reformulation across European supply chains. German automotive and telecom OEMs tighten supplier qualification protocols and extend pre-production validation periods. Bavarian industrial corridors host precision calendering operations serving automotive V2X module manufacturers.
Japan
METI industrial standards shape domestic procurement specifications for high-frequency shielding grades. Precision calendering capacity clusters in Osaka and Nagoya, exposing telecom OEMs to single-source disruption risks during regional logistics constraints. Domestic compounders realign capacity toward sub-6 GHz and millimeter-wave spectra simultaneously.
South Korea
Smartphone OEMs in Seoul and Suwon pull conductive polymers into millimeter-wave handset designs as wavelength compression intensifies crosstalk susceptibility. Korean precision film manufacturing anchors Asian consumer electronics shielding supply. Domestic base station deployment lags Chinese buildouts, redirecting compounder export volumes toward Southeast Asian markets.
Global 5G EMI Materials Market Vendor Landscape
Japanese and South Korean producers anchor the precision calendering tier; German and American specialists hold formulation and automotive qualification positions. The vendor base organizes around three strategic archetypes: integrated materials conglomerates with polymer expertise, precision film manufacturers with roll-to-roll processing capabilities, and compounders serving telecom-specific MIIT certification requirements. Dominant competitive moves include capacity expansion in ferrite-polymer matrices and strategic partnerships between compounders and antenna-in-package module designers.
Among Japanese precision manufacturers, Nitto Denko Corporation and Kitagawa Industries Co., Ltd. occupy positions within the vapor-deposited multi-layer film segment. Laird Performance Materials represents the North American integrated materials archetype with ferrite composite expertise. Henkel AG & Co. KGaA anchors the European adhesive EMI portfolio tier through automotive qualification program participation.
| Leading Market Players |
|---|
| Laird Performance Materials |
| 3M Company |
| DuPont de Nemours, Inc. |
| Parker Hannifin Corporation |
| Henkel AG & Co. KGaA |
| Rohm Semiconductor |
| Honeywell International Inc. |
| Nitto Denko Corporation |
| Kitagawa Industries Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Precision calendering migration toward sub-6 GHz and millimeter-wave grades is compressing unit economics for high-frequency ferrite-polymer matrices while concentrating production leverage among Japanese and South Korean equipment holders. This dual transformation tightens margin structures for compounders without captive film capacity while rewarding integrated manufacturers with backward control over nickel-graphite filler supply.
Pricing Analysis
Capacity additions in China are reshaping price floors for nickel-graphite composite formulations serving MIIT-certified base station programs. Three-tier pricing structure across MIIT-certified premium grades, automotive-qualified standard tiers, and economy metal-foil alternatives governs procurement negotiations. Cost compression in standard conductive polymers is intensifying because silver-coated copper input volatility compresses margin predictability for compounders. Telecommunications OEMs exhibit highest price sensitivity due to volume procurement protocols, while military contractors accept premium positioning for documented supply chain provenance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for Chinese provincial operator base station programs, displacing distributor-mediated purchasing for high-volume deployments. Geographic supply concentration centers on Japan, South Korea, and China for precision calendering, vapor deposition equipment, and nickel-graphite composite production respectively. Raw material dependencies draw from silver-coated copper particles, ferrite ceramic precursors, and halogen-free flame retardant additives. Single-source vulnerability exposure runs through Japanese precision calendering capacity during regional logistics constraints. Distribution runs through compounder-direct contracts for telecommunications infrastructure and specialty distributors for automotive and military qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's accelerated MIIT certification timelines and Europe's extended ECHA REACH reformulation periods creates procurement cost differentials for qualified suppliers. Compounders with dual-hemisphere qualification capabilities capture margin premiums from synchronized global product launches.
For Market Incumbents: Hedge against silver-coated copper input volatility through backward integration into nickel-graphite filler production or long-term offtake agreements with Australian and Indonesian mining operations. Defend market position by accelerating ferrite-polymer matrix capacity expansion in China ahead of domestic competitor qualification cycles. Prioritize MIIT certification maintenance as provincial operators consolidate vendor lists around three-tier performance categories. For New Entrants and Emerging Players: Enter via India's delayed 5G spectrum auction completion, where domestic base station deployment acceleration will outpace local EMI material production capacity. Target automotive V2X qualification pipelines as NHTSA mandates extend material specifications from telecom into transportation shielding applications with less consolidated vendor structures. Pursue co-development partnerships with antenna-in-package module designers to bypass established compounder-direct procurement relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among precision calendering equipment holders without integrated formulation capabilities, as Japanese and South Korean producers face margin pressure from Chinese composite expansion. Long-term viability over the projection horizon rests on dual-certification capability for FCC and MIIT parallel approval cycles. Monitor active cancellation coating convergence as the inflection signal indicating technology transition from passive to adaptive shielding architectures.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Investment | Domestic compounders with MIIT certification capture preferential placement on Chinese provincial operator procurement lists. |
| Backward Integration into Nickel-Graphite Supply | Captive filler production insulates compounders from precious metal price volatility in silver-coated copper markets. |
| Dual-Certification Capability Buildout | Parallel FCC equipment authorization and MIIT radio transmission approval cycles enable synchronized global product launches. |
| Active Cancellation Coating Development | Integration of ferrite composites with real-time adaptive algorithms addresses physical size constraints in 28-39 GHz millimeter-wave deployments. |
| Automotive V2X Qualification Pipeline Entry | NHTSA vehicle-to-everything communication mandates extend material specifications from telecom into transportation shielding applications. |
Methodological Framework
Direct dialogue with compounder technical directors, telecommunications OEM procurement leads, automotive RF module engineers, and ECHA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from MIIT radio transmission equipment certification databases, FCC equipment authorization filings, SEC 10-K disclosures from listed materials suppliers, and Japanese METI industrial production surveys. Bottom-up and top-down triangulation reconciled shipment volume estimates with end-use consumption patterns across antenna-in-package module production lines.
Bottom-up modeling aggregated individual product-type consumption across composite materials, conductive polymers, metal foils, and shielding films, while top-down verification cross-checked against regional telecommunications infrastructure deployment data. Segmentation dimensions included product type, application category, end-user vertical, and technology architecture across the analysis window. CAGRs were derived from fitted growth curves incorporating millimeter-wave spectrum activation timelines and MIIT certification mandate implementation schedules. Industry-specific forecast inputs incorporated carrier base station procurement cycles and smartphone OEM antenna-in-package integration roadmaps.
Inputs from MIIT certification registries and Japanese precision calendering capacity surveys were available through the study window; gaps in real-time silver-coated copper spot pricing transparency introduce uncertainty bands around conductive polymer margin forecasts. Forecasts reflect assumptions regarding ECHA REACH substance restriction implementation timelines and FCC spectrum allocation finalization. Periodic stress-testing of base assumptions against carrier capex guidance revisions and regional logistics disruption scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Chemicals
Global Electronic Materials and Chemicals Market
Electronic Chemicals
Global Circuit Materials Market
Electronic Chemicals
Electronic Chemicals Market
Electronic Chemicals
Liquid Soldering Flux Market
Electronic Chemicals
Printed Electronic Materials Market
Electronic Chemicals
Silver Paste Market
Electronic Chemicals
Electronic Wet Chemicals Market
Electronic Chemicals
Global Imaging Chemicals Market