
 Chicken Coop Market | 2026-2036
Chicken Coop Market Size, Share, and Industry Trends Forecast 2026-2036
Chicken Coop Market Analytics
Subscription-based maintenance and replacement-part programs is hardening into a core revenue layer for coop manufacturers. Tractor Supply Co. leverages its rural retail footprint to bundle installation services with hardware sales. Omlet specializes in modular, plastic-construction systems that reduce long-term upkeep costs for suburban owners. Carolina Coops anchors its position through handcrafted wood designs targeting premium backyard segments.
A chicken coop constitutes a ventilated, predator-resistant enclosure engineered to house poultry through controlled temperature, nesting, and roosting zones, typically fabricated from pressure-treated lumber, galvanized steel, or UV-stabilized polyethylene. The structure must maintain 2-3 square feet per bird interior floor space with 8-10 inches of roosting bar per hen to satisfy welfare and productivity benchmarks. Fixed coops capture the dominant share of replacement-driven revenue, while portable poultry tractors represent the fastest-expanding category among rotational-grazing homesteaders seeking soil-health benefits. Wood materials retain margin concentration in artisan and heritage segments, though plastic and composite formulations are displacing traditional lumber in moisture-prone climates due to rot resistance and simplified sanitization protocols.
USDA APHIS biosecurity regulations and state-level animal welfare statutes in jurisdictions such as California and Massachusetts are mandating minimum space allocations and predator-proofing standards that elevate product complexity and compliance costs. The National Organic Program certification requirements further restrict treated lumber and synthetic coating usage for producers targeting premium egg markets. Stakeholders must monitor evolving municipal zoning ordinances that alternately restrict or incentivize urban poultry keeping, as these local frameworks increasingly determine addressable market boundaries and channel access patterns.
Market Dynamics
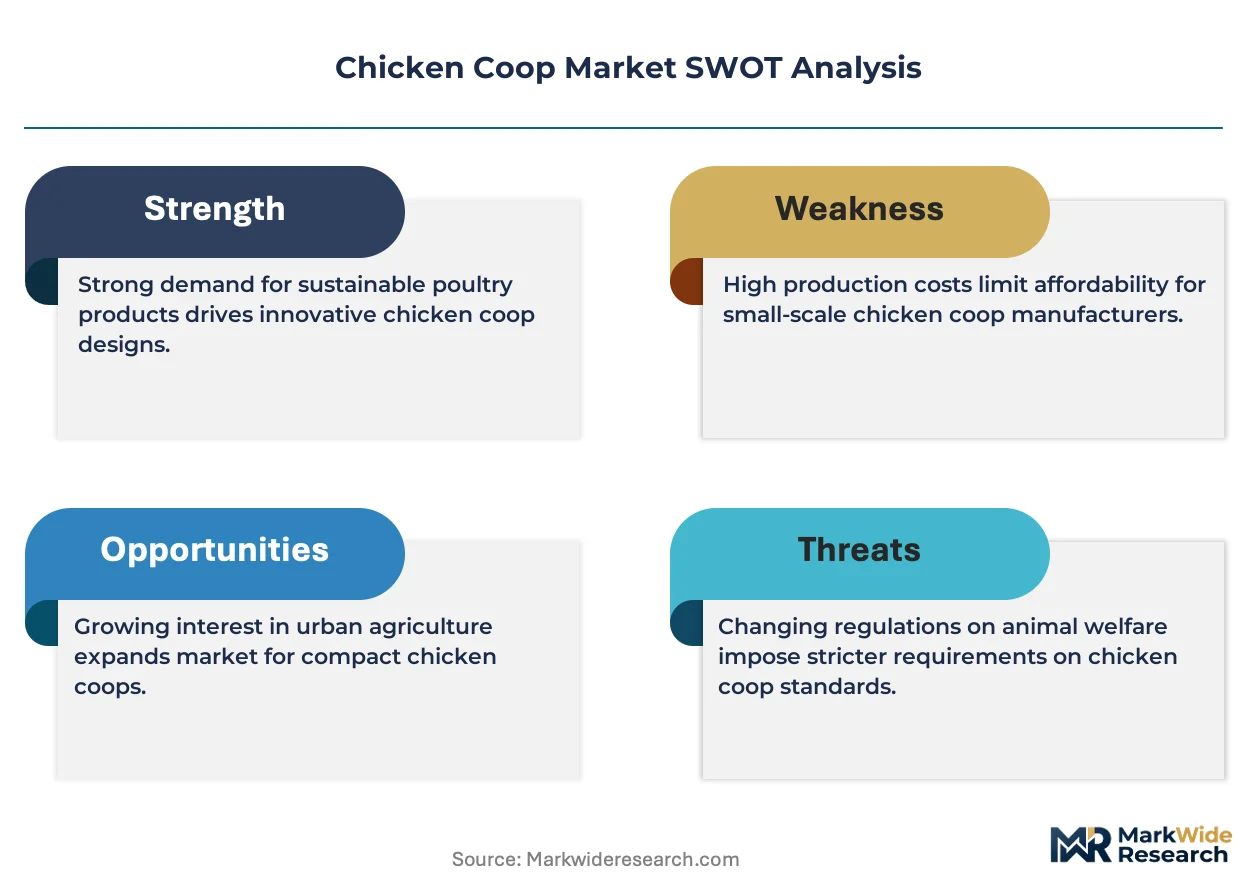
The chicken coop market is experiencing structural pressure from tightening biosecurity mandates that elevate enclosure complexity while urban homesteading creates bifurcated demand between premium handcrafted units and low-maintenance modular systems.
Growth Catalysts
- USDA APHIS Biosecurity Protocols:Federal guidelines mandating predator-proofing and ventilation standards are forcing coop upgrades across existing backyard flocks, generating replacement cycles independent of new flock formation.
- Rotational Grazing Homesteaders:Soil-health-conscious smallholders are adopting portable poultry tractors at accelerating rates, expanding the addressable market beyond fixed-structure traditionalists.
- UV-Stabilized Polyethylene Formulations:Advanced plastic composites are penetrating moisture-prone coastal and southeastern corridors where wood rot previously limited product lifespan.
Market Restraints
- Pressure-Treated Lumber Restrictions:National Organic Program certification bars synthetic coatings and treated wood, forcing certified-egg producers toward premium untreated cedar or cypress that carries 40-60% material cost premiums.
- Municipal Zoning Fragmentation:Local ordinances in jurisdictions like Denver and Austin alternate between restrictive lot-size minimums and permissive urban-agriculture incentives, creating unpredictable addressable market boundaries.
- Predator-Proofing Cost Escalation:Hardware cloth specifications below half-inch mesh and buried apron requirements are adding $150-400 per unit in materials and labor for compliance-grade installations.
Strategic Opportunities
- Subscription Maintenance Programs:Recurring-revenue service models covering seasonal deep-cleaning, predator-barrier inspection, and roosting-bar replacement are penetrating suburban markets where time-constrained owners dominate.
- Modular Expansion Systems:Scalable coop architectures allowing 4-bird base units to expand to 12-bird configurations are capturing growing families and 4H participants in Texas and Pennsylvania corridors.
- California Proposition 12 Alignment:State-level cage-free mandates for commercial operations are spilling into backyard segment expectations, creating premium positioning for spacious enclosure designs exceeding federal minimums.
Industry Challenges
- Artisan Labor Scarcity:Handcrafted wood coop manufacturers in North Carolina and Virginia face shrinking pipelines of skilled joiners capable of executing mortise-and-tenon construction at commercial scale.
- Cross-Border Compliance Complexity:Canadian import requirements under Health Canada's PMRA for treated lumber components create documentation burdens for US manufacturers serving Ontario and British Columbia markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chicken Coop Market |
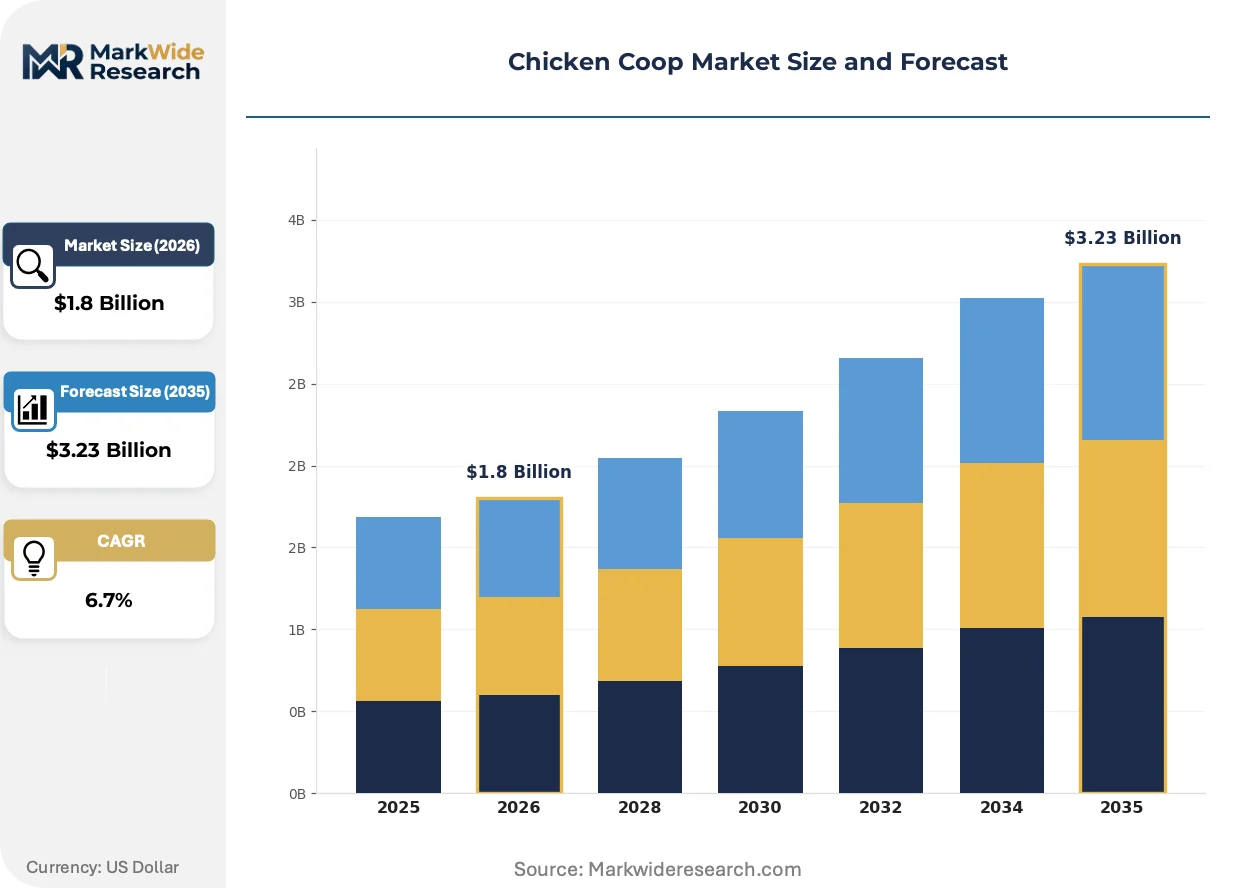
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Coop, Fixed Coop, Poultry Tractor, Multi-Container Coop Material: Wood, Metal, Plastic, Composite Size: Small, Medium, Large, Extra Large End User: Backyard Farmers, Commercial Farmers, Hobbyists, Agritourism |
| Companies Covered | Omlet, Tractor Supply Co., Rural King, Petmate, SnapLock Chicken Coops, Backyard Coop Company, Carolina Coops, The Clever Coop Company, Sunrise Pet Structures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chicken Coop Market Evolving Landscape
Automation and material science are converging to redefine enclosure functionality, while regulatory layering and buyer sophistication are segmenting the market into distinct performance tiers.
Smart monitoring systems integrating temperature sensors, automated door actuators, and predator-detection cameras are unifying previously discrete functions into single-platform coop management. Tech-forward homesteaders in Austin and Portland metro areas are adopting these systems at twice the rate of rural counterparts. This convergence is compressing the traditional divide between basic shelter and precision livestock management, forcing mid-market manufacturers to develop firmware capabilities or cede premium positioning.
REACH chemical restrictions in the European Union are banning specific wood preservatives and galvanized coatings containing hexavalent chromium, compelling export-oriented manufacturers to reformulate surface treatments. Dutch and German coop producers are transitioning to thermal modification and acetylated wood processes that eliminate chemical inputs entirely. North American suppliers targeting EU distribution channels must now dual-certify products or maintain separate production lines.
Direct-to-consumer assembly models are displacing traditional retail distribution for modular plastic coop systems. Urban buyers in Denver, Seattle, and Atlanta are purchasing flat-pack configurations through manufacturer websites, bypassing Tractor Supply and agricultural co-ops entirely. This channel migration is most pronounced among millennial homesteaders aged 28-42 who prioritize video-guided assembly support over in-person sales consultation.
Chicken Coop Market Segmentation
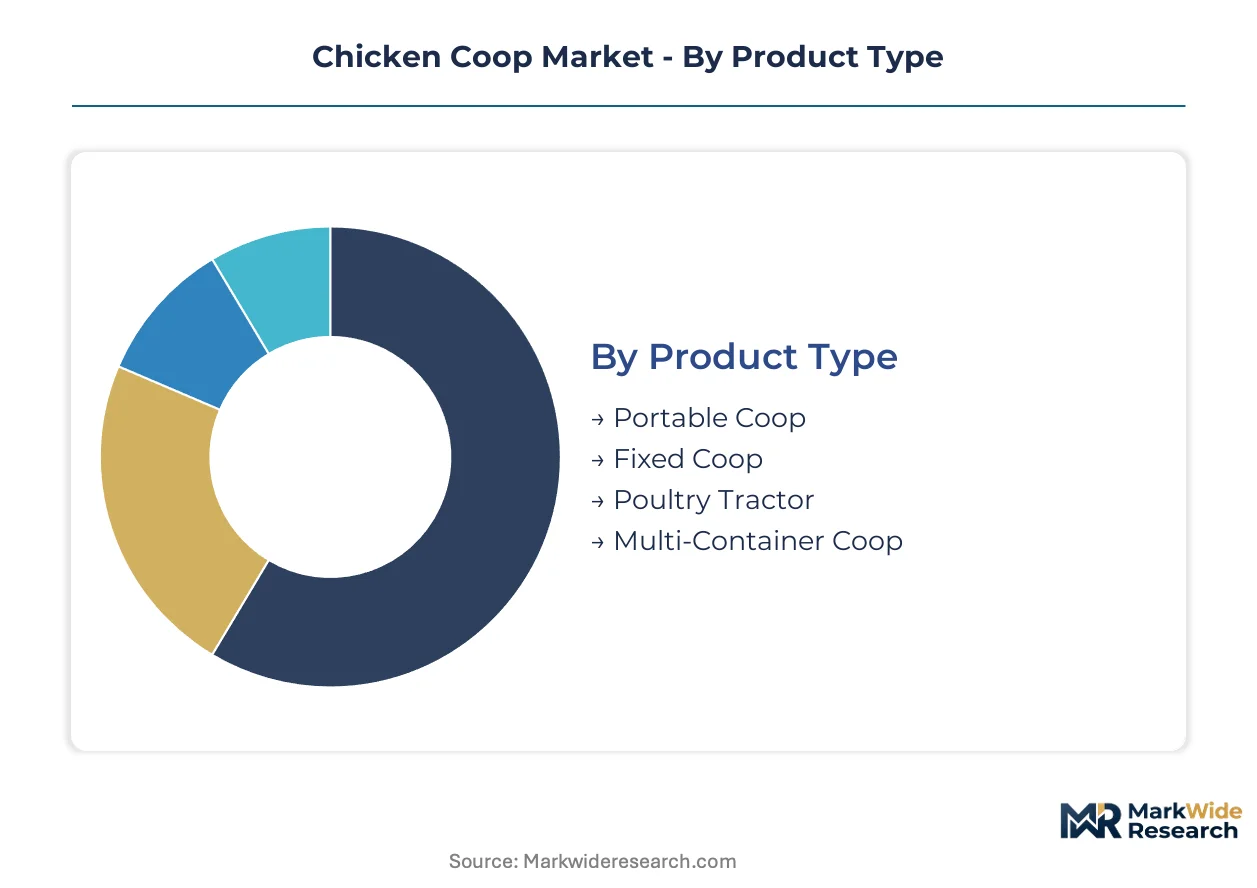
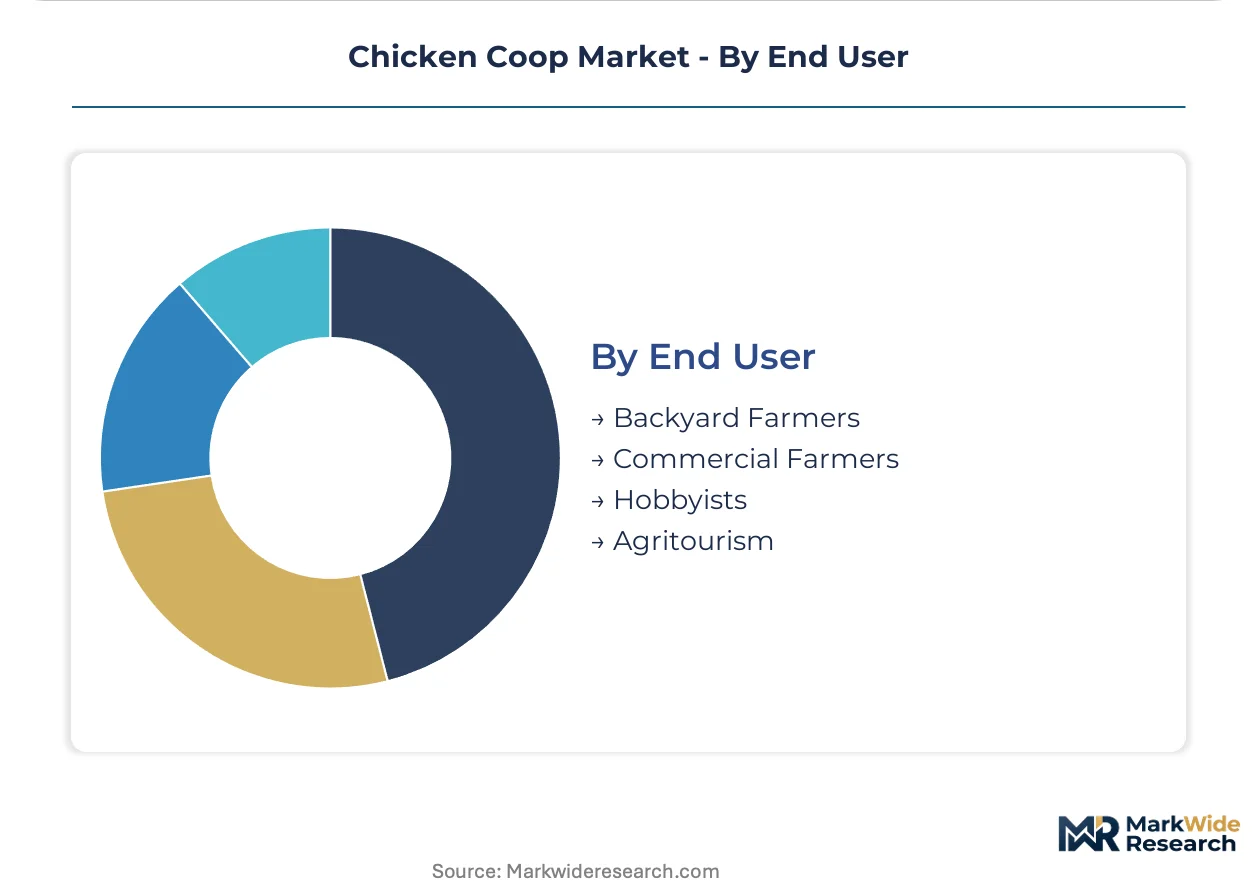
Chicken coop buyers fragment sharply between heritage woodcraft enthusiasts and maintenance-averse suburban owners, creating parallel premium and volume tiers with distinct channel and margin profiles. Material selection, mobility requirements, and flock scale further subdivide addressable demand into configurations with incompatible manufacturing economics.
Product Type:
Fixed structures dominate replacement revenue cycles while portable formats capture rotational-grazing expansion among soil-health homesteaders.
- Portable Coop:Lightweight frame assemblies mounted on skids or wheels enable seasonal relocation across pasture paddocks. Rotational-grazing practitioners in Pennsylvania and North Carolina corridors are adopting these units to distribute manure loading and break parasite cycles without permanent infrastructure investment.
- Fixed Coop:Permanent foundation-mounted structures with integrated runs and storage annexes anchor backyard installations. Texas poultry-keeping clusters drive replacement demand here as USDA APHIS biosecurity upgrades force enclosure renovations independent of flock expansion.
- Poultry Tractor:Floorless mobile shelters designed for daily repositioning across lawn or cropland. Daily-movement protocols appeal to permaculture homesteaders seeking concentrated fertility deposition without fixed fencing costs.
- Multi-Container Coop:Segregated housing systems permitting brooder, grower, and layer populations within unified structures. 4H participants and multi-flock breeders in suburban Austin and Denver markets favor these configurations for biosecurity compartmentalization.
Today's leader: Fixed Coop. Tomorrow's challenger: Poultry Tractor.
Material:
Traditional lumber commands artisan premiums while synthetic formulations penetrate moisture-corrosion zones where wood rot previously limited product lifespan.
- Wood:Pressure-treated pine, cedar, and cypress constructions retain margin concentration in heritage segments. National Organic Program restrictions on synthetic coatings are pushing certified-egg producers toward untreated cedar and cypress carrying substantial material cost premiums.
- Plastic:UV-stabilized polyethylene and polypropylene systems eliminate rot and simplify sanitization protocols. Coastal southeastern corridors from Florida to Louisiana are displacing traditional lumber fastest here due to humidity-driven decay failure modes.
- Metal:Galvanized steel framing with aluminum cladding delivers predator resistance and fire safety for commercial-scale installations. Wildfire-prone California foothill counties specify non-combustible materials in municipal poultry-keeping permits.
- Composite:Wood-plastic and fiber-cement formulations balance thermal mass with moisture immunity. REACH chemical restrictions in EU export markets are accelerating thermal modification and acetylated wood alternatives that eliminate preservative inputs entirely.
Heritage positioning favors Wood. Volume scaling favors Plastic.
Size:
Flock scale determines enclosure economics, with municipal zoning lot-size minimums creating hard boundaries between urban micro-flocks and rural production units.
- Small:2-4 bird capacity units designed for balcony and small-yard compliance. Denver and Seattle municipal ordinances permitting 3-hen maximums concentrate demand in this tier among millennial first-time owners.
- Medium:5-8 bird configurations serving family egg consumption and occasional surplus sales. This tier captures growing-family expansion trajectories in Texas and Pennsylvania 4H corridors.
- Large:12-20 bird installations supporting commercial egg sales and farmer's market distribution. Proposition 12 spillover effects in California are elevating space-per-bird expectations that push commercial backyarders into this category.
- Extra Large:50+ bird systems approaching commercial operation thresholds requiring zoning variance or agricultural land use designation. Agritourism operations in North Carolina and Virginia wine country deploy these for u-pick egg experiences and educational farm tours.
Regulatory ceiling: Small. Revenue ceiling: Extra Large.
End User:
Time availability and production intent separate subscription-service candidates from self-sufficient homesteaders with divergent maintenance tolerance.
- Backyard Farmers:Suburban and exurban households maintaining 3-12 birds primarily for household egg consumption. This segment is expanding most quickly as urban homesteading gains traction among time-constrained professionals seeking local food security without agricultural labor commitment.
- Commercial Farmers:Licensed egg producers selling through retail, wholesale, or direct-to-restaurant channels. USDA Organic and Animal Welfare Approved certification requirements force capital-intensive enclosure investments that smaller competitors cannot replicate.
- Hobbyists:Breed enthusiasts and exhibition poultry keepers prioritizing genetic preservation and show quality over production economics. Rare breed societies and national poultry shows sustain demand for specialized housing accommodating breeding pens and isolation protocols.
- Agritourism:Farm-stay operations, educational venues, and petting zoos integrating live poultry into visitor experiences. Liability insurance requirements and health department regulations mandate predator-proofing and sanitization standards exceeding typical backyard installations.
Volume anchor: Backyard Farmers. Margin anchor: Agritourism.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for predator-resistant enclosures outpaces Canadian adoption by a factor of five, while European regulatory layering accelerates material transitions absent in North American markets.
United States
Texas, North Carolina, and Pennsylvania poultry-keeping corridors concentrate replacement-driven demand as USDA APHIS biosecurity protocols force enclosure upgrades. Municipal zoning in Denver and Austin alternates between restrictive lot-size minimums and permissive urban-agriculture incentives, fragmenting addressable boundaries. Carolina Coops anchors handcrafted wood production in North Carolina, serving premium backyard segments with mortise-and-tenon construction.
Canada
Ontario and British Columbia backyard flocks drive import demand for US-manufactured modular systems. Health Canada's PMRA documentation requirements for treated lumber components create cross-border compliance burdens that elevate landed costs. Toronto and Vancouver metro areas concentrate millennial homesteading populations seeking low-maintenance plastic constructions over traditional wood.
Germany
REACH chemical restrictions banning hexavalent chromium in galvanized coatings compel surface treatment reformulation for export-oriented manufacturers. Thermal modification and acetylated wood processes eliminate chemical inputs entirely, satisfying Dutch and German producer transitions. Bavarian and North Rhine-Westphalia smallholders favor predator-proofing standards exceeding federal minimums, elevating product complexity.
United Kingdom
Defra biosecurity guidelines and urban hen-keeping permits in London, Bristol, and Manchester metro areas structure demand toward compact modular units. Omlet's flat-pack direct-to-consumer model captures millennial buyers aged 28-42 prioritizing video-guided assembly over agricultural co-op consultation. Southeast England garden-center retail maintains heritage woodcraft positioning for affluent suburban owners.
Australia
Predator pressure from foxes and snakes in Victoria and New South Wales drives hardware cloth specifications below half-inch mesh, adding materials cost premiums. Queensland humidity accelerates plastic and composite displacement of traditional lumber in coastal corridors. Melbourne and Sydney municipal frameworks increasingly permit urban poultry, expanding addressable markets for small-capacity balcony-compliant units.
Chicken Coop Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage woodcraft artisans commanding margin premiums while volume producers scale modular plastic systems. The vendor base organizes into three strategic archetypes: rural retail bundlers leveraging installation services, direct-to-consumer modular specialists, and handcrafted premium woodworkers. Competitive moves concentrate on geographic expansion through regional distributor partnerships and portfolio diversification into subscription maintenance programs.
Among rural retail bundlers, Tractor Supply Co. exemplifies the installation-service-integrated model, while Omlet occupies a position within the direct-to-consumer modular tier emphasizing flat-pack distribution and video-guided assembly support. Carolina Coops anchors the handcrafted woodcraft archetype, representing premium backyard positioning through artisan construction methods. These three players collectively illustrate the market's tripartite segmentation across convenience, modularity, and heritage positioning.
| Leading Market Players |
|---|
| Omlet |
| Tractor Supply Co. |
| Rural King |
| Petmate |
| SnapLock Chicken Coops |
| Backyard Coop Company |
| Carolina Coops |
| The Clever Coop Company |
| Sunrise Pet Structures |
| Others |
Value Network & Pricing Analysis
Backward integration into pressure-treated lumber milling anchors pricing power for Carolina Coops and similar heritage manufacturers, while outsourced plastic resin sourcing leaves modular producers exposed to petrochemical volatility. This integration divergence separates margin-defensible woodcraft artisans from volume-scaling competitors tethered to commodity input cycles.
Pricing Analysis
Capacity additions in Chinese UV-stabilized polyethylene production are reshaping price floors for plastic coop systems, compressing entry-level positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by material certification and installation bundling. Cost compression in standard-tier modular units is intensifying because direct-to-consumer channel migration eliminates retail margin stacking. Backyard farmers in Denver and Austin municipal zones exhibit highest price sensitivity, while agritourism operators absorb premium positioning for liability-compliant predator-proofing.
Supply Chain Analysis
Galvanized steel hardware cloth supply rests on Mexican and Turkish metalworking clusters, with domestic wire-forming capacity concentrated in Pennsylvania and Ohio. Cedar and cypress lumber draws from Pacific Northwest and Appalachian sawmill networks, while UV-stabilized polyethylene resin feeds from Gulf Coast petrochemical complexes. Single-source vulnerability in half-inch mesh specifications creates bottleneck exposure for USDA APHIS-compliant producers. Distribution runs through Tractor Supply rural retail footprints, direct-to-consumer flat-pack logistics, and regional agricultural co-op networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chicken coop market reads as a late-cycle quality story. Backyard farmer demand is shifting toward premium handcrafted units as municipal biosecurity standards harden and replacement cycles accelerate.
For Market Incumbents: Anchor market position through captive cedar milling capacity in North Carolina and Virginia to offset National Organic Program material cost premiums. Defend against modular plastic entrants by embedding subscription maintenance programs that exploit suburban owner time constraints. Certification investment in Animal Welfare Approved standards creates channel control for commercial backyard segments.
For New Entrants and Emerging Players: Enter via coastal southeastern corridors where humidity-driven wood rot displaces traditional lumber fastest. Target millennial homesteaders aged 28-42 in Denver and Seattle through video-guided assembly support that bypasses agricultural co-op dependence. White-space concentration in multi-container brooder-grower-layer systems for 4H participants offers penetrable positioning.
For Investors and Strategic Acquirers: Roll-up economics work for handcrafted woodcraft specialists because artisan labor scarcity in mortise-and-tenon construction prevents rapid capacity replication. Long-term viability hinges on 5-10 year municipal zoning liberalization trajectories. Acquisition target archetype: regional premium wood coop manufacturers with established installation service networks. The signal to watch is California Proposition 12 spillover into backyard segment space-per-bird expectations.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Maintenance Program Launch | Recurring revenue locks in suburban backyard farmers with limited time availability. |
| Backward Integration into Cedar Milling | Captive lumber supply defends margin position against National Organic Program material premiums. |
| Modular Expansion System Development | Scalable 4-to-12 bird architectures capture growing-family trajectories in Texas 4H corridors. |
| Direct-to-Consumer Channel Expansion | Flat-pack distribution with video assembly support bypasses Tractor Supply margin extraction. |
| California Proposition 12 Alignment | Spacious enclosure designs exceed federal minimums for premium backyard positioning. |
Research Methodology
Bottom-up backyard farmer demand modeling reconciled against top-down coop manufacturer production tracking forms the analytical core. Primary interviews with heritage woodcraft artisans, modular plastic system producers, Tractor Supply category managers, and municipal zoning officers combined with secondary validation. Secondary sources include USDA APHIS biosecurity guideline documents, National Organic Program certification standards, municipal poultry-keeping ordinances from Denver, Austin, and Seattle, and SEC 10-K filings from rural retail bundlers. Triangulation across these inputs ensures segmentation integrity.
Historical trendline analysis of replacement cycle timing and flock formation rates informed projection modeling across the analysis window. Segmentation dimensions include product type (fixed, portable, poultry tractor, multi-container), material (wood, plastic, metal, composite), flock size tier, and end-use archetype. CAGRs were derived from regression against USDA poultry inventory data and urban homesteading demographic shifts. Industry-specific forecast inputs incorporate municipal zoning liberalization trajectories and biosecurity standard evolution.
Inputs from primary stakeholder interviews were available through the study window; gaps in longitudinal municipal ordinance tracking introduce uncertainty bands around addressable market boundary assumptions. Forecasts reflect documented assumptions regarding regulatory layering pace and material substitution elasticities. Specific risk factors include REACH chemical restriction spillover into North American markets and Canadian PMRA documentation burden escalation. A small set of named triggers warrants ongoing watch: municipal zoning reversals, predator-proofing standard federalization, and artisan labor pipeline contraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Cattle Supplies Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Horse Bunk Feeder Market
Livestock Equipment
Starter Feed Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Europe Livestock Monitoring Market