
 Seaweed Biomass Waste Market | 2026-2036
Seaweed Biomass Waste Market Size, Share, and Industry Trends Forecast 2026-2036
Seaweed Biomass Waste Market Analytics
Buyer concentration among bioplastics compounders is pivoting toward specialty fermentation houses seeking standardized seaweed feedstock. Acadian Seaplants Ltd. anchors Atlantic Canadian supply through backward integration into cultivation. Sea6 Energy leverages tropical seaweed strains optimized for rapid biomass accumulation. The Seaweed Company competes via controlled supply agreements with Nordic cosmetic formulators requiring traceable provenance.
Seaweed biomass waste comprises residual fronds, stipes, and holdfasts discarded after alginate, carrageenan, or agar extraction, typically retaining 40-60% organic carbon and significant potassium and micronutrient loads suitable for downstream valorization. Its primary commercial purpose centers on recovering value from otherwise discarded marine biomass through biological or thermochemical transformation. Dry seaweed dominates volume flows to animal feed compounders seeking consistent protein content, while wet seaweed feeds fastest-growing anaerobic digestion installations capturing methane for grid injection. Processed seaweed extracts command premium positioning in pharmaceutical-grade hydrocolloid applications where purity certifications gate market access.
EU REACH and F-Gas Regulation frameworks constrain synthetic fertilizer alternatives, indirectly elevating seaweed-derived soil amendments as compliant replacements. EPA biosolids regulations in the United States and EFSA feed additive standards across Europe shape product specifications and cross-border trade eligibility for animal feed applications. Stakeholders must monitor evolving carbon accounting methodologies that could reclassify seaweed waste valorization pathways as eligible or ineligible for offset crediting.
Market Dynamics
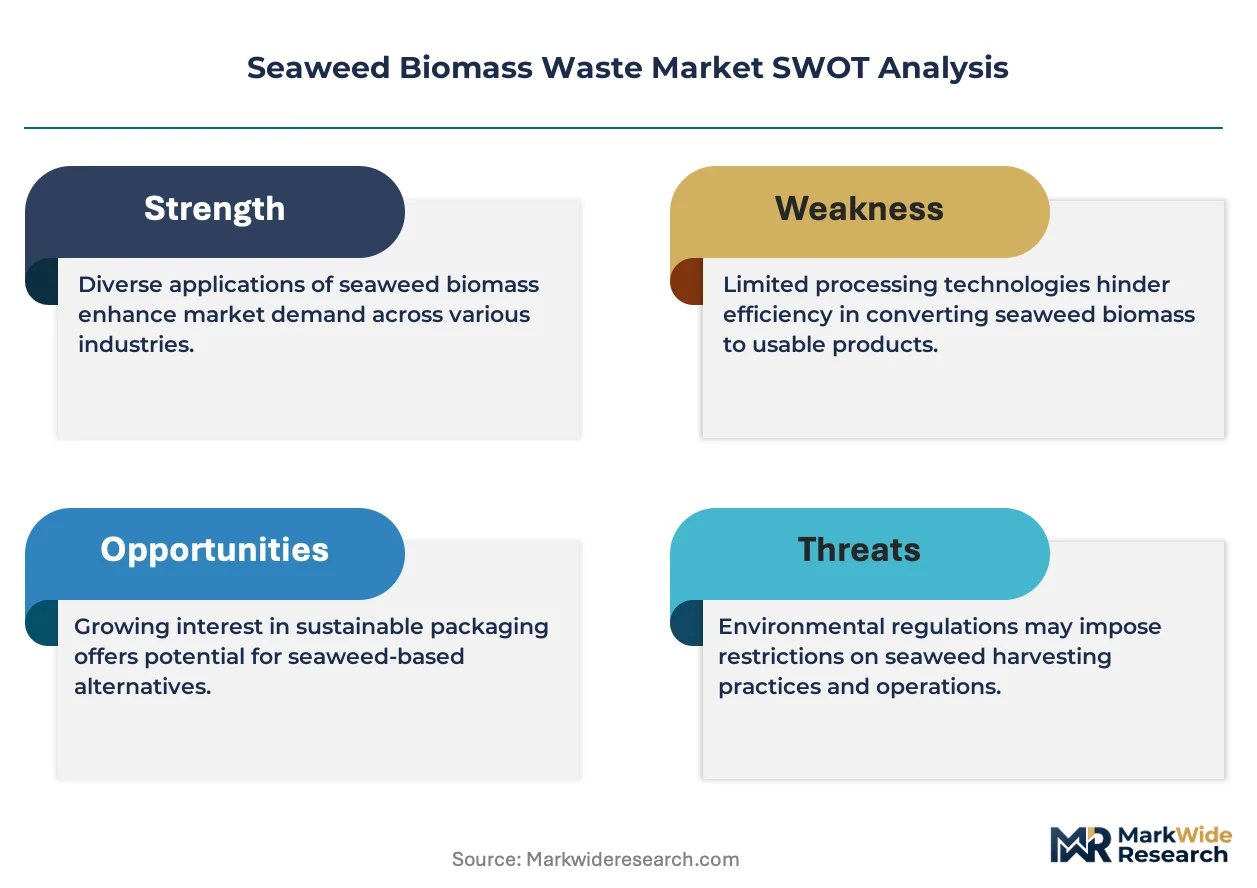
Bioplastics compounders now drive demand concentration as EU Green Deal mandates systematically phase out petroleum-derived packaging substrates, redirecting procurement toward marine biomass feedstocks.
Growth Catalysts
- EU Green Deal packaging mandates:Binding reduction targets for fossil-based plastics elevate seaweed-derived polymers to preferred substitute status among formulators seeking compliance pathways.
- Anaerobic digestion technology maturation:Commercial-scale wet waste-to-biogas systems unlock energy recovery from residual biomass previously relegated to landfill disposal.
- Norwegian cultivation-processing integration:Concentrated offshore farming operations in North Atlantic waters secure captive feedstock supply for integrated biorefinery development.
Market Restraints
- Harvest seasonality and weather volatility:North Atlantic storm patterns interrupt collection cycles, creating supply discontinuities for processors requiring year-round feedstock throughput.
- Alginate extraction residue variability:Inconsistent polysaccharide recovery rates across batch processing generate unpredictable organic carbon loads for downstream valorization units.
- Petroleum-based polymer price competition:Sustained low-cost virgin plastics from Middle Eastern petrochemical complexes compress margin structures for bio-alternatives.
Strategic Opportunities
- Pharmaceutical-grade hydrocolloid certification:EMA purity standards create premium positioning for processors achieving GMP-compliant extraction and waste-stream segregation.
- Carbon accounting methodology alignment:Evolving ISO 14064 frameworks for marine biomass crediting could reclassify anaerobic digestion pathways as eligible offset generators.
- Tropical strain optimization:Sea6 Energy's rapid-accumulation cultivars demonstrate biomass doubling cycles that temperate-zone competitors cannot replicate.
Industry Challenges
- Marine bioprocessing talent scarcity:Specialized expertise in halophilic fermentation and seaweed-specific enzymatic hydrolysis remains concentrated among Nordic and Japanese research institutions.
- Multi-jurisdictional feedstock traceability:EFSA, FDA, and FSSAI divergent documentation requirements for ocean-sourced inputs complicate cross-border shipment logistics.
- Legacy petrochemical equipment retrofit costs:Converting solvent-based extraction infrastructure for aqueous seaweed processing demands capital outlays that mid-scale operators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seaweed Biomass Waste Market |
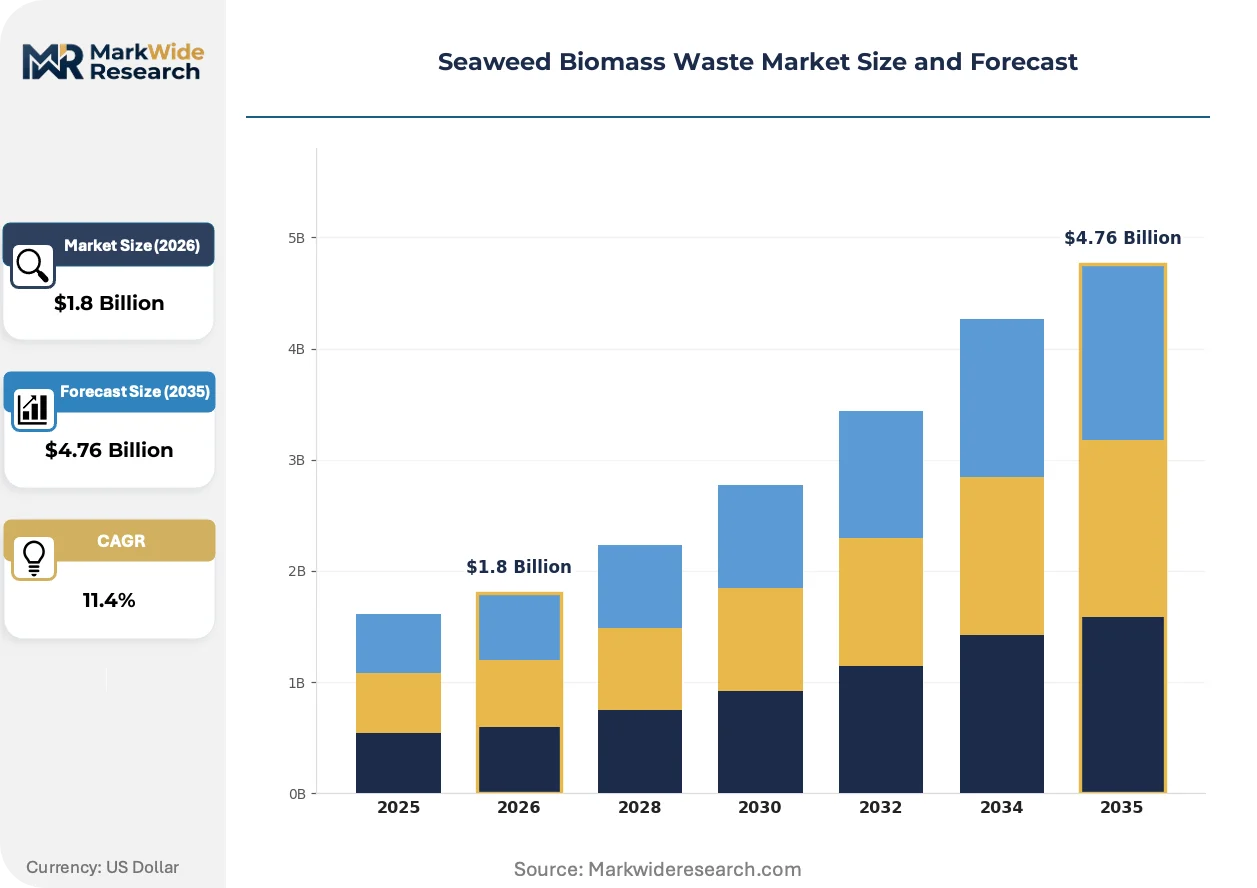
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Seaweed, Wet Seaweed, Processed Seaweed, Seaweed Extracts End Use Industry: Agriculture, Food Processing, Pharmaceuticals, Cosmetics Technology: Fermentation, Anaerobic Digestion, Composting, Nutrient Recovery Application: Soil Amendment, Biopesticides, Animal Feed, Bioplastics |
| Companies Covered | Acadian Seaplants Ltd., Ocean Rainforest, The Seaweed Company, Oceans 2050, Cascadia Seaweed, Seaweed Energy Solutions, Seagreens, The Cornish Seaweed Company, Sea6 Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seaweed Biomass Waste Market Evolving Landscape
Processing architectures are fragmenting into distributed, smaller-scale units that co-locate with cultivation sites rather than centralizing at legacy port-based refineries.
Enzymatic hydrolysis systems for cell-wall disruption are modularizing. Biorefinery operators in Norway and Ireland deploy containerized units that relocate seasonally following harvest fleets. This mobility compresses transport costs for high-moisture biomass that spoils rapidly. Equipment suppliers now engineer skid-mounted configurations rated for offshore platform installation.
REACH authorization requirements for synthetic polymer additives are tightening. ECHA's expanded restriction candidate list pushes formulators toward seaweed-derived plasticizers and film-forming agents. Cosmetic and food packaging segments in Germany and France face the most immediate substitution deadlines, accelerating qualification timelines for marine-derived alternatives.
Compounders now specify origin-certified feedstock with chain-of-custody documentation. Nordic cosmetic formulators reject anonymous biomass pools, instead contracting directly with named cultivation operations. This disintermediation bypasses traditional hydrocolloid traders. Procurement teams in Oslo and Copenhagen now conduct site audits of offshore farms before contract execution.
Seaweed Biomass Waste Market Segmentation
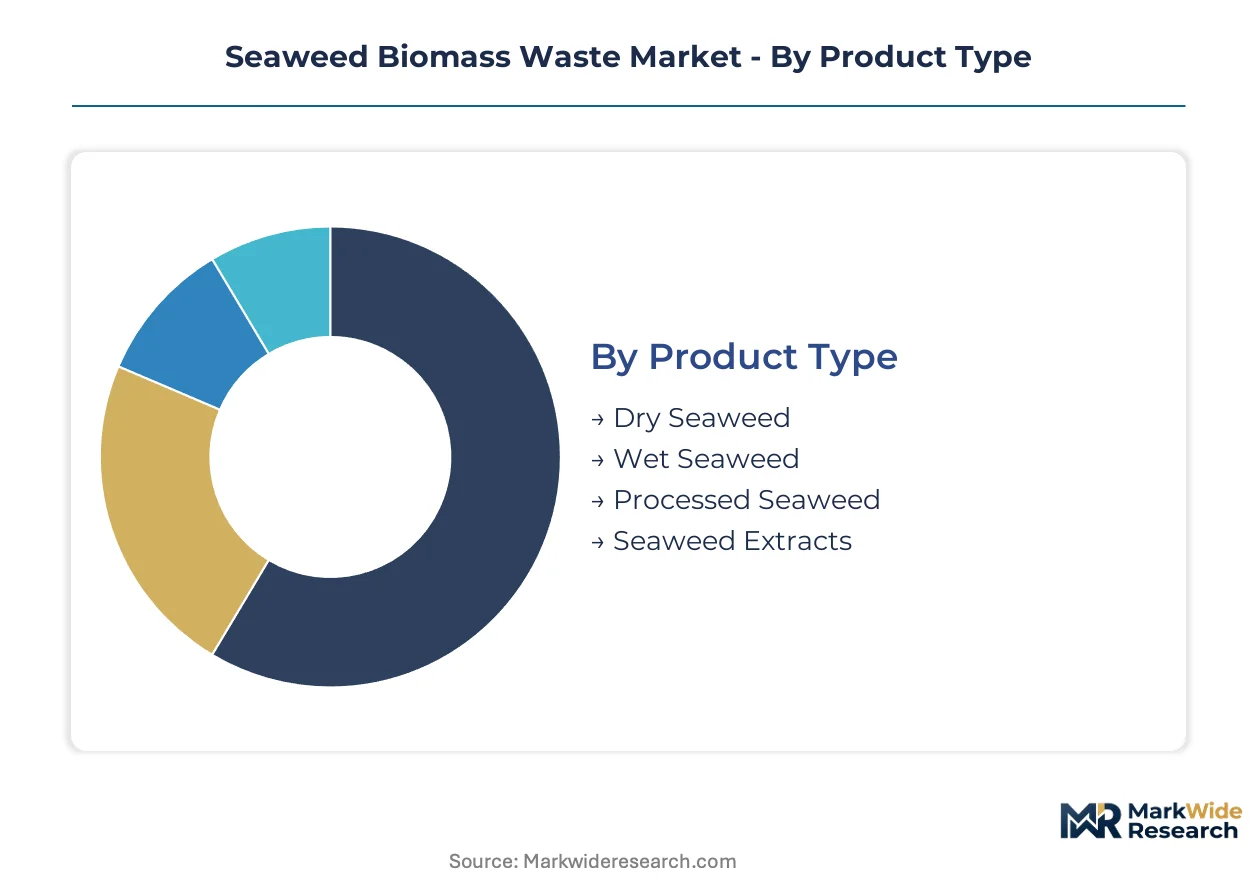
Seaweed biomass waste valorization requires precise feedstock matching to downstream conversion pathways. Each segment category reflects distinct moisture profiles, carbon densities, and regulatory compliance thresholds that dictate equipment selection and end-market access.
Product Type:
Upgrading from raw harvest residue to standardized feedstock formats follows a clear replacement cycle driven by processor capital investment and end-use certification requirements.
- Wet Seaweed:Retains 80-90% moisture content post-harvest, requiring immediate processing or rapid spoilage. Norwegian biogas operators at Ocean Rainforest and Seaweed Energy Solutions anchor demand through integrated offshore-to-digester pipelines that eliminate drying costs. EU renewable energy certificates for grid-injected biomethane sustain procurement premiums.
- Dry Seaweed:Stabilized biomass with 10-15% moisture enables year-round storage and intercontinental shipment. Animal feed compounders in Ireland and France concentrate procurement here, drawn by consistent protein content specifications that wet formats cannot guarantee. Drying energy costs compress margins during fossil fuel price spikes.
- Processed Seaweed:Milled or pelletized material standardized for industrial handling. Biofuel cofiring trials at Danish power utilities create niche offtake.
- Seaweed Extracts:Concentrated hydrocolloid fractions retaining functional properties for high-value applications. Pharmaceutical-grade batches command strict heavy metal documentation.
Volume placements concentrate in Dry Seaweed; the faster expansion belongs to Wet Seaweed.
End Use Industry:
Cost tier stratification separates commodity absorption from premium valorization, with regulatory compliance costs acting as the primary sorting mechanism.
- Agriculture:Soil amendment and biofertilizer applications dominate tonnage offtake. French and German viticulture cooperatives specify seaweed-derived potassium sources to meet EU Farm-to-Fork synthetic reduction targets. EFSA feed additive approvals gate cross-border trade eligibility.
- Bioplastics:Compounders seeking EU Green Deal compliance drive fastest-growing demand concentration. German packaging formulators in Hamburg and Munich now mandate marine-derived feedstock for rigid container applications. Certification costs exclude smaller compounders.
- Food Processing:Hydrocolloid recovery for texture modification. Carrageenan and alginate extraction residues feed circular loops.
- Cosmetics:Nordic formulators in Oslo and Copenhagen require chain-of-custody documentation for marine-derived active ingredients. Traceability premiums reward named-cultivation contracts.
Agriculture absorbs the heaviest volumes; bioplastics climb the fastest.
Technology:
Application maturity determines capital deployment patterns, with proven pathways attracting institutional financing and novel routes remaining venture-dependent.
- Anaerobic Digestion:Commercial-scale wet waste-to-biogas systems now operate at positive unit economics across North Atlantic installations. Irish operators leverage existing agricultural digester infrastructure retrofitted for halophilic feedstock. Grid injection tariffs in Germany and Denmark stabilize revenue visibility.
- Fermentation:Specialty chemical and bioplastic precursor production via engineered microbial platforms. Acadian Seaplants Ltd. and Sea6 Energy pilot succinic acid and lactic acid routes. Strain optimization for saline tolerance remains concentrated among Nordic research consortia.
- Composting:Low-capital aerobic decomposition for local soil amendment markets. Seasonal throughput limits scale.
- Nutrient Recovery:Membrane and precipitation systems extracting potassium, magnesium, and trace elements. Fertilizer blenders in the Netherlands pilot integration.
Capital deployment concentrates in Anaerobic Digestion; steepest expansion trajectory belongs to Fermentation.
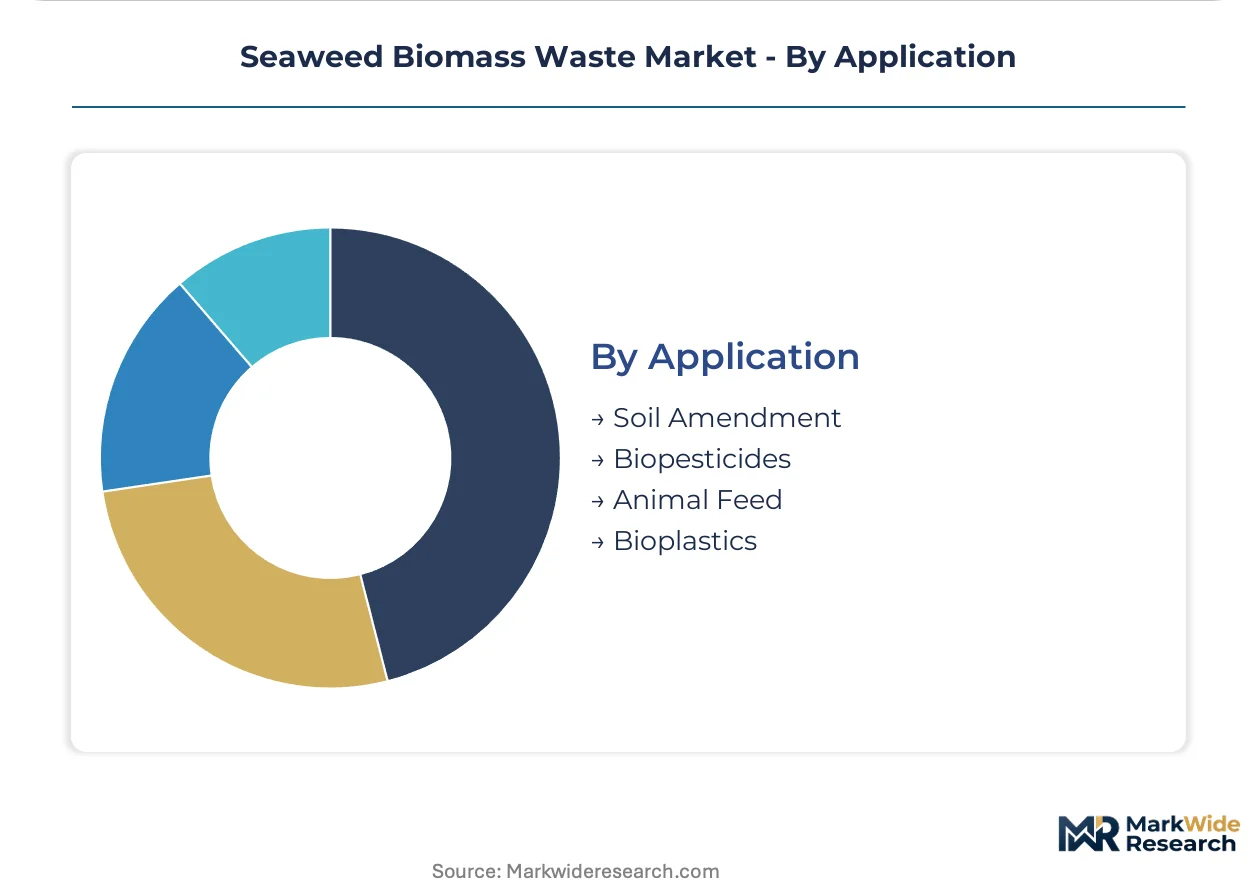
Application:
Customer type differentiation separates bulk commodity buyers from specification-driven formulators, with certification requirements determining contract structures.
- Animal Feed:Protein and mineral supplementation for ruminant and aquaculture diets. Norwegian salmon farming operations specify seaweed-derived feed ingredients to reduce terrestrial crop dependency. EFSA and FDA divergent documentation requirements complicate transatlantic supply.
- Soil Amendment:Carbon-rich soil conditioners improving water retention and microbial activity. French organic viticulture certification bodies recognize seaweed-derived inputs as compliant amendments. REACH authorization constraints on synthetic alternatives elevate competitive positioning.
- Biopesticides:Extract-based crop protection with elicitor properties. Regulatory registration timelines in Germany and France extend commercialization horizons.
- Bioplastics:Polymer feedstock for packaging and disposable applications. EU single-use plastic directives accelerate qualification timelines.
Tonnage concentrates in Soil Amendment; premium expansion belongs to Bioplastics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Atlantic kelp forests anchor the raw-material base, with Norwegian fjords and Irish coastal waters supplying the densest biomass flows for integrated biorefinery development.
Norway
Offshore cultivation leases and integrated digester pipelines drive deployment. The EU Green Deal packaging mandates redirect German compounder procurement toward Norwegian supply. Bergen and Trondheim harbor clusters host Ocean Rainforest and Seaweed Energy Solutions operations with captive feedstock pipelines.
Ireland
Agricultural digester retrofits for halophilic feedstock unlock capacity expansion. EPA biosolids regulations shape cross-border shipment protocols for soil amendment products. Cork and Galway processing hubs concentrate wet-to-biogas infrastructure serving UK grid injection contracts.
Germany
Packaging formulators in Hamburg and Munich mandate marine-derived feedstock for rigid container compliance. REACH authorization constraints on synthetic polymer additives elevate seaweed-derived alternatives. ECHA restriction candidate list updates accelerate substitution timelines for cosmetic and food packaging segments.
France
Viticulture cooperatives specify seaweed-derived potassium to meet Farm-to-Fork synthetic reduction targets. ANSM traceability requirements for cosmetic actives enforce chain-of-custody documentation. Brittany and Normandy coastal clusters supply hydrocolloid processors serving Parisian formulator demand.
India
Tropical strain optimization programs target rapid biomass accumulation cycles. FSSAI feed additive standards and DGFT export documentation requirements structure trade eligibility. Tamil Nadu and Gujarat coastal zones pilot cultivation-to-fermentation integration for succinic acid precursor production.
Seaweed Biomass Waste Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and carbon crediting alignment. The supplier base fragments across cultivation-integrated operators, independent processors, and compounder-captive supply arrangements. Three archetypes dominate: Nordic offshore farming operations with backward integration into biogas, tropical strain specialists leveraging rapid accumulation genetics, and Atlantic Canadian hydrocolloid processors with named-cultivation traceability. Competitive moves concentrate on strategic partnerships with bioplastics compounders and geographic expansion into EU compliance-driven demand clusters.
Within the cultivation-integrated tier, Ocean Rainforest anchors Norwegian offshore operations with captive digester pipelines. Sea6 Energy exemplifies the tropical strain optimization archetype through rapid-accumulation cultivar development. Acadian Seaplants Ltd. occupies the Atlantic Canadian position with backward integration into named-cultivation supply for traceability-dependent formulators.
| Leading Market Players |
|---|
| Acadian Seaplants Ltd. |
| Ocean Rainforest |
| The Seaweed Company |
| Oceans 2050 |
| Cascadia Seaweed |
| Seaweed Energy Solutions |
| Seagreens |
| The Cornish Seaweed Company |
| Sea6 Energy |
| Others |
Value Network & Pricing Analysis
Captive integration into offshore cultivation and onshore biogas processing anchors both supply security and pricing power for Norwegian operators. Ocean Rainforest and Seaweed Energy Solutions leverage this structure to command premiums from German bioplastics compounders facing EU Green Deal compliance deadlines, while wet-to-dry format arbitrage creates tiered value capture across moisture-content specifications.
Pricing Analysis
Chain-of-custody documentation bundling separates premium-grade feedstock contracts from anonymous biomass spot purchases. Pricing stratifies across pharmaceutical-grade hydrocolloid certification, EFSA-compliant animal feed tiers, and standard biogas-input grades, with EU renewable energy certificate values compressing differentials in the wet-seaweed segment. Cost compression in standard-grade animal feed inputs is intensifying as Irish agricultural digester retrofits expand halophilic capacity. Bioplastics compounders exhibit the lowest price sensitivity due to regulatory substitution mandates, while local composting operations remain most exposed to energy-driven drying cost volatility.
Supply Chain Analysis
Dual-sourcing requirements from German packaging formulators mandate named-cultivation contracts with both Norwegian and Irish suppliers to mitigate North Atlantic storm disruption. Raw material flows draw from kelp forests in Norwegian fjords, Irish coastal waters, and Atlantic Canadian leases, with alginate extraction residue and carrageenan processing byproducts feeding circular valorization loops. Single-source vulnerability concentrates in specialized halophilic fermentation expertise clustered among Nordic research institutions. Distribution runs through integrated offshore-to-digester pipelines for wet biomass and pelletized intermodal shipment for dry formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Seaweed Biomass Waste Market sits at a technology-transition inflection as anaerobic digestion displaces landfill disposal for wet residue streams. This shift reconfigures competitive positioning around captive cultivation-processing integration rather than trading-based supply arbitrage.
For Market Incumbents: Cement backward integration into offshore cultivation leases to lock feedstock supply against tropical strain competitors. Prioritize GMP-compliant extraction infrastructure investment to capture pharmaceutical-grade hydrocolloid premiums before EMA purity standards harden. Defend against Sea6 Energy's rapid-accumulation genetics by co-locating enzymatic hydrolysis units with harvest fleets. For New Entrants and Emerging Players: Capture the fermentation pathway expansion for bioplastic precursor production, where succinic acid and lactic acid routes remain underdeveloped relative to mature anaerobic digestion. Target Indian tropical cultivation zones with FSSAI-compliant feedstock for export qualification to EU compounders. Lead with named-cultivation traceability contracts that bypass legacy hydrocolloid trader intermediation. For Investors and Strategic Acquirers: Exit pathways concentrate in bioplastics compounder acquisition of cultivation-integrated processors seeking captive supply security. Long-term viability hinges on carbon accounting methodology alignment that reclassifies anaerobic digestion as offset-eligible. Watch for ISO 14064 marine biomass framework finalization as the signal for institutional capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Offshore Cultivation | Ocean Rainforest demonstrates captive feedstock pipelines eliminate spot market exposure for Norwegian operators. |
| GMP-Compliant Extraction Certification | EMA purity standards gate pharmaceutical-grade hydrocolloid premiums for processors achieving waste-stream segregation compliance. |
| Containerized Enzymatic Hydrolysis Deployment | Seasonal relocation following harvest fleets compresses transport costs for high-moisture biomass subject to rapid spoilage. |
| Named-Cultivation Direct Contracts | Nordic cosmetic formulators in Oslo and Copenhagen bypass traditional traders through site-audited offshore farm agreements. |
| Tropical Strain Optimization Programs | Sea6 Energy's rapid-accumulation cultivars demonstrate biomass doubling cycles temperate competitors cannot replicate. |
Research Methodology
Independent corroboration across biogas plant operators, bioplastics compounder procurement leads, and hydrocolloid extraction engineers underwrites the qualitative findings. Primary interviews with Norwegian cultivation managers, Irish agricultural digester retrofit specialists, German packaging formulator R&D directors, and EFSA regulatory affairs consultants combined with secondary validation from EU renewable energy certificate registries, ECHA restriction candidate list updates, and SEC filings from publicly traded marine biotechnology firms. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth from price realization and mix-shift effects. Segmentation dimensions modeled include moisture-content format, end-use industry application, conversion technology pathway, and regional regulatory cluster. CAGRs derive from installed biogas capacity buildout trajectories, EU Green Deal packaging mandate implementation schedules, and fermentation platform commercialization timelines. Industry-specific forecast inputs incorporate alginate extraction residue yield variability and tropical strain biomass accumulation rates.
The model holds under sustained EU regulatory enforcement of petroleum-based packaging phaseouts; deviation in carbon accounting methodology eligibility would shift anaerobic digestion pathway economics materially. Forecasts reflect assumptions regarding North Atlantic cultivation lease availability and halophilic fermentation strain development progress. Deviation in REACH authorization timelines for synthetic polymer alternatives would compress substitution demand for marine-derived feedstocks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Renewable Solvent Market