
 Bio-Based Ethylene Market | 2026-2036
Bio-Based Ethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Ethylene Market Outlook
Petroleum-derived ethylene is hardening as a cost benchmark against which bio-based alternatives must compete. Braskem S.A. anchors the sector through its Brazilian sugarcane ethanol-to-ethylene complex at Triunfo. TotalEnergies leverages European refining expertise to pilot bio-naphtha cracking pathways. BASF SE sustains polymer science leadership through dedicated biopolymer R&D platforms in Ludwigshafen.
Bio-based ethylene refers to C2H4 produced from renewable feedstocks via dehydration of bioethanol or gasification of lignocellulosic material, typically achieving polymer-grade purity above 99.9 percent to substitute seamlessly in conventional steam crackers. Its primary purpose centers on decarbonizing the base chemical layer of plastics, solvents, and synthetic rubber production without retrofitting downstream polyethylene infrastructure. Sugarcane feedstock dominates current commercial output due to mature fermentation economics and established Brazilian supply chains. Polyethylene applications capture the largest value pool given direct drop-in compatibility with existing blown film and injection molding equipment. Cellulosic biomass represents the fastest-growing feedstock category as second-generation pretreatment technologies reduce enzyme costs and expand beyond food-crop competition.
The EU Green Deal and REACH framework mandate renewable content thresholds in packaging, directly steering brand-owner procurement toward certified bio-based polyethylene. EPA renewable fuel standards and state-level low-carbon fuel programs in California create parallel demand signals for ethanol dehydration capacity. Brazil's national biofuel policy and BIS standards in India for bioplastics labeling together fragment compliance requirements across major demand centers. Stakeholders must monitor feedstock certification scheme interoperability and cracking yield parity to determine capital allocation between first-generation and cellulosic pathways.
Market Dynamics
Feedstock certification mandates under the EU Green Deal are compressing supply timelines for bio-based polyethylene, forcing brand-owners to pre-commit to certified volumes before downstream conversion capacity scales.
Growth Catalysts
- REACH renewable content thresholds:EU packaging regulations mandate minimum bio-based shares, redirecting procurement budgets toward certified polyethylene films.
- Sugarcane fermentation economics:Brazilian ethanol infrastructure delivers cost-competitive feedstock for dehydration pathways, anchoring commercial output.
- Blown film compatibility:Drop-in polymer-grade purity above 99.9 percent eliminates equipment retrofit barriers for converters.
Market Restraints
- Petroleum ethylene cost benchmark:Fossil-derived C2H4 pricing sets a ceiling that bio-based alternatives struggle to undercut at scale.
- First-generation feedstock competition:Food-crop sugarcane faces land-use scrutiny that constrains expansion beyond existing Brazilian cultivation zones.
- Cellulosic enzyme costs:Second-generation lignocellulosic pathways remain economically uncompetitive due to pretreatment expense.
Strategic Opportunities
- Indian bioplastics labeling:BIS standards create compliance-driven demand for certified bio-based polyethylene in South Asian packaging.
- California LCFS credits:State-level low-carbon fuel programs generate parallel revenue streams for ethanol dehydration investments.
- Gasification-pyrolysis convergence:Hybrid thermochemical platforms unlock forestry residue feedstocks outside agricultural geographies.
Industry Challenges
- Feedstock certification interoperability:Misaligned schemes between EU, US, and Brazilian auditors delay cross-border shipment approvals.
- Cracking yield parity:Bio-naphtha pathways struggle to match steam cracker efficiency rates of conventional naphtha feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Ethylene Market |
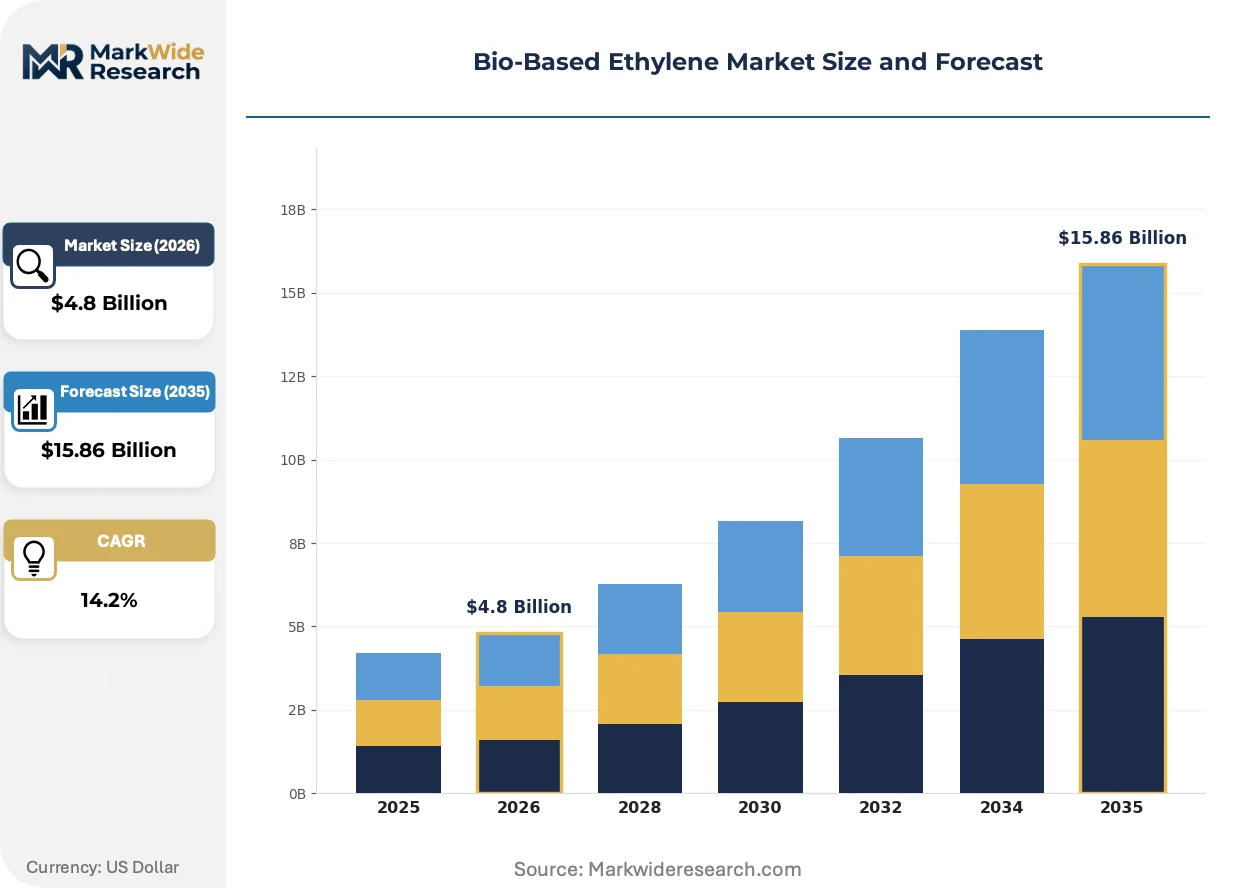
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Ethylene Glycol, Ethanol, Bio-Butylene Feedstock: Corn, Sugarcane, Cellulosic Biomass, Waste Biomass Application: Packaging, Automotive, Construction, Textiles End User: Consumer Goods, Industrial Manufacturing, Agriculture, Healthcare |
| Companies Covered | SABIC, TotalEnergies, Braskem S.A., BASF SE, Enerkem, The Dow Chemical Company, Shell Global, Cargill, LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Ethylene Market Strategic Shifts
Technology maturation is splitting competitive advantage between first-generation sugarcane ethanol and emerging cellulosic platforms, while regulatory fragmentation forces multi-jurisdictional compliance architectures.
Cellulosic gasification is decentralizing feedstock sourcing by enabling forestry and agricultural residue conversion outside traditional sugarcane belts. European refiners are piloting bio-naphtha cracking to diversify beyond Brazilian supply concentration. This technology is compressing the geographic monopoly of fermentation-based production.
REACH sustainability mandates are tightening certification requirements for bio-based content claims in packaging applications. Brand-owners must now secure chain-of-custody documentation from feedstock origin through polymer conversion. Food and beverage multinationals with EU manufacturing footprints face the steepest compliance ramps.
Long-term offtake contracting is replacing spot purchasing as the dominant procurement mechanism for certified bio-based polyethylene. Converters are locking three- to five-year supply agreements to secure allocation ahead of capacity buildouts. This pattern is most pronounced among German and French packaging groups with net-zero commitments under CSRD disclosure rules.
Bio-Based Ethylene Market Segmentation
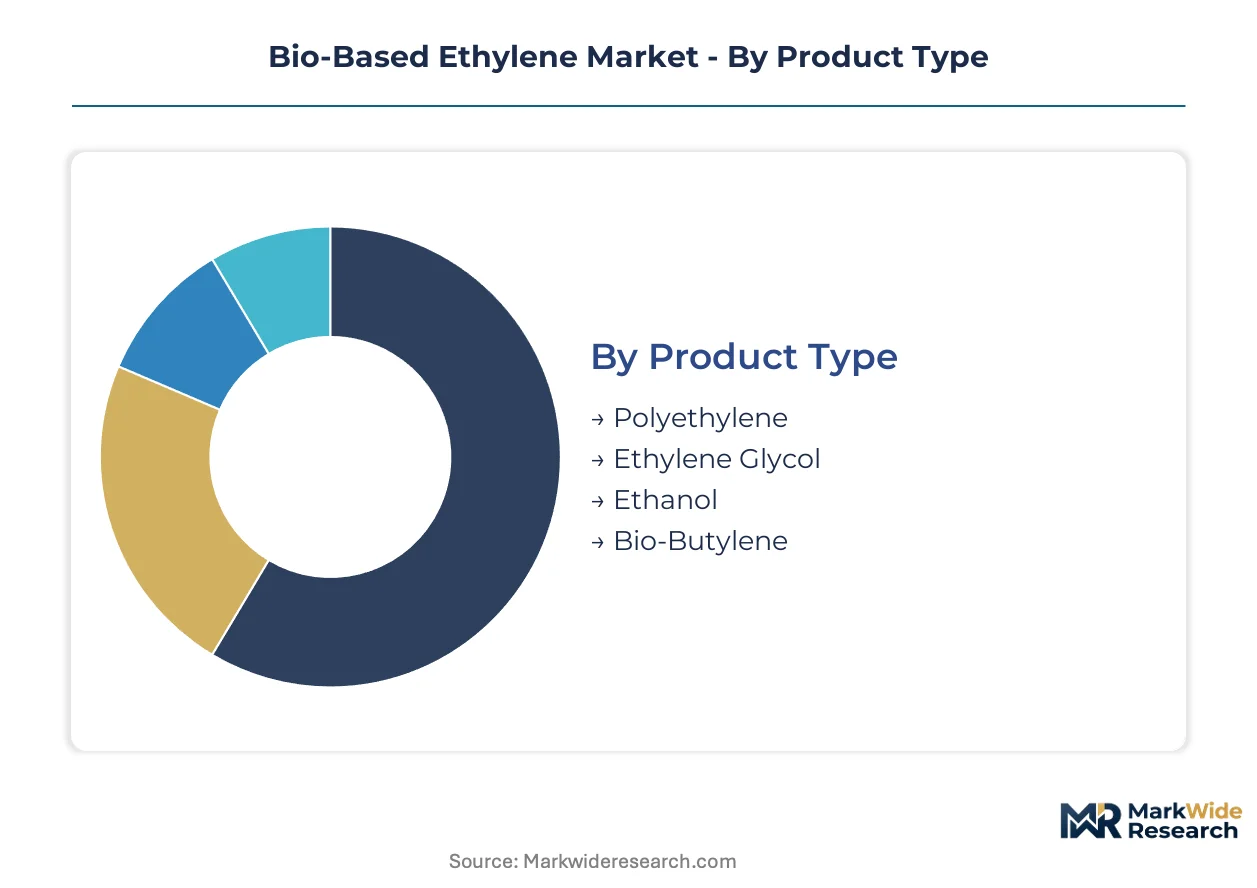
Segmentation in bio-based ethylene reveals how capital deployment, feedstock access, and regulatory pressure intersect to determine competitive positioning. Each dimension exposes distinct margin structures and barriers to entry that shape investment decisions across the value chain.
Product Type:
Capital intensity varies sharply across derivatives, with polymerization infrastructure demanding the heaviest upfront commitment.
- Polyethylene:Polymer-grade bio-ethylene undergoes catalytic polymerization to produce high-density and linear low-density grades compatible with existing blown film lines. Packaging converters in Germany and France are locking long-term offtake agreements to secure allocation under EU Green Deal compliance timelines.
- Ethylene Glycol:Oxidation of bio-ethylene yields monoethylene glycol for polyester fiber and bottle resin production. Textile manufacturers in India are sourcing certified volumes to meet BIS bioplastics labeling requirements for export-oriented apparel.
- Ethanol:Dehydration-grade bio-ethanol serves as both intermediate and fuel oxygenate, with California LCFS credits supporting project economics at dehydration facilities.
- Bio-Butylene:Co-product streams from sugarcane fermentation chemistry enable butylene output for specialty polymer modifiers.
Polyethylene absorbs the bulk of installed capacity; ethylene glycol is expanding most quickly.
Feedstock:
Cost tier stratification separates established agricultural pathways from emerging residue-based alternatives still scaling pretreatment economics.
- Sugarcane:First-generation ethanol from Brazilian crushing mills delivers the lowest delivered cost for dehydration units, anchored by Triunfo's integrated complex.
- Cellulosic Biomass:Enzymatic hydrolysis of agricultural residues unlocks C5 and C6 sugar streams without food-crop competition. Forestry waste collectors in Scandinavia are aggregating feedstock for pilot gasification platforms.
- Corn:US Midwest grain ethanol supplies dehydration capacity with established logistics, though EPA renewable fuel standards create competing offtake demand.
- Waste Biomass:Municipal and industrial organic waste streams provide distributed feedstock for small-scale pyrolysis units.
Sugarcane commands the dominant share of operating capacity; cellulosic biomass is gaining share fastest as enzyme costs decline.
Application:
Customer type concentration determines contract structure, with consumer-facing sectors demanding certified chain-of-custody documentation.
- Packaging:Flexible films and rigid containers represent the primary demand sink, with REACH renewable content thresholds redirecting procurement budgets toward certified polyethylene.
- Automotive:Interior trim and under-hood components utilize bio-based ethylene derivatives for lightweighting and emissions reduction claims.
- Construction:Geomembranes and insulation materials absorb volumes where durability specifications tolerate slight premium pricing.
- Textiles:Polyester fiber applications in apparel and home furnishings are climbing the fastest as brand-owners pursue recycled and renewable content targets.
Packaging captures the dominant share of current offtake; textiles are climbing the fastest on brand-owner sustainability commitments.
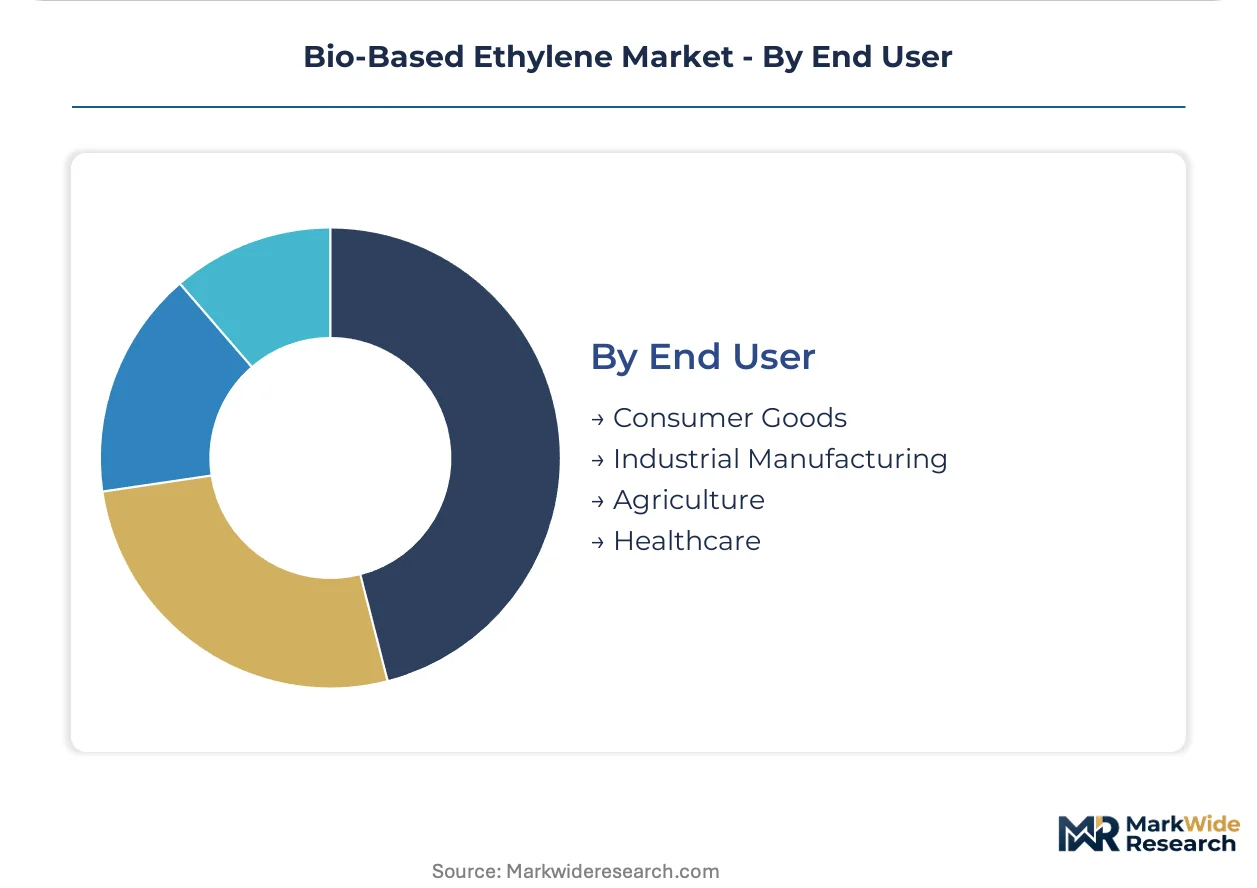
End User:
Supply concentration aligns with geographic clusters where certification infrastructure and disclosure mandates are most developed.
- Consumer Goods:Food and beverage multinationals with EU manufacturing footprints face the steepest compliance ramps under CSRD disclosure rules.
- Industrial Manufacturing:Chemical intermediates and synthetic rubber producers value drop-in compatibility to avoid cracker retrofit costs.
- Agriculture:Mulch films and controlled-release coatings utilize bio-polyethylene for soil contact applications where biodegradability claims add value.
- Healthcare:Medical packaging and device components demand polymer-grade purity above 99.9 percent with full batch traceability.
Consumer goods directs the largest procurement volumes; healthcare is expanding most quickly on traceability premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil due to Braskem's integrated sugarcane-to-ethylene complex, while European converters scramble to secure certified volumes ahead of EU Green Deal compliance deadlines.
Brazil
Triunfo's integrated fermentation and dehydration complex anchors global commercial output, with sugarcane crushing mills supplying cost-competitive ethanol feedstock. ANVISA bioplastics standards and national biofuel policy reinforce domestic market development. São Paulo state's ethanol infrastructure cluster supports capacity expansion for polyethylene export volumes.
Germany
Packaging converters in the Rhine-Ruhr region are locking three- to five-year offtake agreements to secure polymer-grade bio-ethylene allocation. REACH renewable content thresholds and CSRD disclosure rules compress procurement timelines for brand-owners. Ludwigshafen's chemical industry cluster hosts dedicated biopolymer R&D platforms advancing catalytic polymerization.
United States
California LCFS credits generate parallel revenue streams for ethanol dehydration investments, while Midwest grain ethanol supplies competing offtake demand. EPA renewable fuel standards create regulatory complexity for feedstock allocation decisions. Houston's petrochemical corridor hosts pilot bio-naphtha cracking initiatives leveraging existing steam cracker infrastructure.
India
Textile manufacturers in Gujarat and Maharashtra source certified bio-ethylene glycol to meet BIS bioplastics labeling requirements for export-oriented apparel. Central government PLI schemes for advanced chemicals support domestic capacity buildout. The Delhi-Mumbai Industrial Corridor attracts polyethylene film converters seeking compliance-driven supply chains.
France
Food and beverage multinationals face steep compliance ramps under EU Green Deal packaging mandates, redirecting procurement budgets toward certified polyethylene films. ECHA feedstock certification requirements tighten chain-of-custody documentation standards. The Grand Est region's agricultural residue collectors aggregate cellulosic biomass for emerging gasification platforms.
Bio-Based Ethylene Market Competitive Environment
Capacity expansion dominates the current landscape as established petrochemical majors and specialized biotech firms race to secure feedstock certification ahead of regulatory deadlines. The market structure exhibits tiered concentration, with Brazilian sugarcane-integrated players occupying the cost-efficient base and European refiners piloting thermochemical diversification. Two strategic archetypes predominate: fermentation-based ethanol dehydrators leveraging agricultural supply chains, and gasification-platform operators targeting lignocellulosic residue streams. Competitive moves center on long-term offtake contracting with brand-owners and backward integration into feedstock cultivation or aggregation.
Among Brazilian-integrated producers, Braskem S.A. anchors the first-generation pathway through its captive sugarcane supply and Triunfo complex infrastructure. European diversified energy majors exemplify the thermochemical pivot, with TotalEnergies leveraging refining expertise to pilot bio-naphtha cracking. German chemical conglomerates occupy the R&D-intensive tier, with BASF SE sustaining polymer science leadership through dedicated biopolymer platforms. These three entities represent distinct competitive vectors: agricultural integration, refinery adaptation, and materials science specialization.
| Leading Market Players |
|---|
| SABIC |
| TotalEnergies |
| Braskem S.A. |
| BASF SE |
| Enerkem |
| The Dow Chemical Company |
| Shell Global |
| Cargill |
| LyondellBasell Industries Holdings B.V. |
| Others |
Value Chain & Pricing Dynamics
Brand-owner procurement pre-commitments under EU Green Deal timelines are forcing supply-side capacity decisions before economies of scale materialize, compressing margins for early movers while locking in premium pricing for certified volumes. This demand-pull dynamic rewards backward-integrated producers with captive feedstock and punishes merchant suppliers exposed to spot ethanol volatility.
Pricing Analysis
Volume commitments trade off against margin capture across the value chain. Contract-based long-term offtake dominates, with price differentiation driven by ISCC PLUS certification tier and volume scale. Cost compression in standard-grade bio-polyethylene is intensifying because petroleum-ethylene pricing sets a ceiling that dehydration economics struggle to undercut. Commodity packaging converters exhibit the highest price sensitivity, while healthcare and automotive OEMs tolerate premiums for batch traceability.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian sugarcane ethanol supply, where Braskem's Triunfo complex processes crushing-mill output from São Paulo state's agricultural belt. Feedstock draws from sugarcane bagasse, corn starch from the US Midwest, and emerging forestry residues in Scandinavia. Tariff exposure on cross-border ethanol shipments creates regulatory risk for European and Asian offtakers. Distribution runs through integrated petrochemical complexes and specialized biopolymer distributors serving certified film converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulosic gasification platforms are displacing first-generation fermentation as the technology-transition phase matures, with lignocellulosic pathways unlocking residue feedstocks beyond sugarcane belts. This shift rewards R&D-intensive players while threatening asset-heavy ethanol dehydrators locked into agricultural geographies.
For Market Incumbents: To counter cellulosic technology displacement, Braskem and sugarcane-integrated players should deepen upstream control over crushing capacity in Brazil's Center-South region while piloting hybrid thermochemical units. Certification investment in ISCC PLUS and Bonsucro chain-of-custody documentation preserves brand-owner relationships against emerging gasification competitors.
For New Entrants and Emerging Players: Forestry-residue gasification technology offers the most penetrable wedge for European and North American entrants lacking Brazilian agricultural access. Target Scandinavian and Pacific Northwest biomass aggregation hubs where enzyme cost declines are unlocking C5/C6 sugar economics. A licensing-plus-feedstock-supply go-to-market model bypasses capital intensity of fully integrated production.
For Investors and Strategic Acquirers: The window for entry favors mid-scale gasification-platform operators with proven lignocellulosic yields and offtake relationships with German packaging groups. Long-term viability hinges on demonstrating cost parity with Brazilian ethanol routes within a five-to-ten-year technology maturation cycle. The signal to watch is enzyme cost trajectories and EU ETS carbon price levels that tilt feedstock economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Cultivation | Captive sugarcane supply in São Paulo state secures cost-competitive ethanol for Triunfo dehydration units. |
| ISCC PLUS Certification Investment | Chain-of-custody documentation satisfies ECHA requirements for EU Green Deal packaging compliance claims. |
| Long-term Supply Agreement | Three-to-five-year offtake contracts with Rhine-Ruhr converters lock allocation ahead of capacity buildouts. |
| Cellulosic Gasification Pilot | Forestry residue platforms in Grand Est region diversify beyond Brazilian supply concentration risks. |
| Joint Venture with Enzyme Technology Provider | Pretreatment partnerships reduce C5/C6 sugar production costs for second-generation pathway economics. |
Study Parameters
Multi-period observation of ethanol crush margins, certification scheme adoption rates, and polyethylene offtake contracting patterns anchored the trend analysis, supplemented by interviews with plant managers at dehydration facilities, procurement leads at German packaging converters, distribution channel partners in biopolymer logistics, and technical R&D directors in catalytic polymerization. Secondary validation drew from customs/trade data, ACC and Cefic chemical industry reports, SEC 10-K filings of listed petrochemical majors, and ISCC certification registry databases. Bottom-up capacity buildout tracking and top-down demand segmentation triangulated volume estimates.
The input-output matrix framed projections across feedstock type, derivative grade tier, end-use industry, and regional production hub throughout the forecast period. CAGRs were derived from segmented growth rate modeling calibrated to ethanol economics and regulatory threshold implementation timelines. Industry-specific forecast inputs included sugarcane crush seasonality patterns and EU ETS carbon price trajectory assumptions.
Several conditions sit outside the modeled scope, including abrupt shifts in EPA renewable fuel standard allocation rules, breakthroughs in electrochemical ethylene synthesis, and trade policy disruptions affecting Brazilian ethanol export flows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Pyruvate Market