
 Renewable Fuel Materials Market | 2026-2036
Renewable Fuel Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Fuel Materials Market Insights
Aviation fuel buyers is reorganizing procurement priorities toward hydroprocessed esters and fatty acids, displacing traditional road transport offtake as the dominant demand archetype. POET LLC anchors Midwest production capacity through captive corn sourcing and ethanol infrastructure. Neste Corporation differentiates via proprietary NEXBTL technology leadership in renewable diesel and sustainable aviation fuel. Archer Daniels Midland extends agricultural origination networks into downstream biofuel processing.
Renewable fuel materials encompass biomass-derived feedstocks and intermediates processed into liquid or gaseous fuels meeting specified energy density, cetane, or octane thresholds for combustion engines or turbines. Corn and waste oils dominate current feedstock throughput, though algae cultivation systems promise higher lipid yields per hectare with lower freshwater intensity. Fermentation retains scale leadership in ethanol production, while transesterification captures margin pools in biodiesel refining. Pyrolysis occupies an earlier commercial phase, targeting lignocellulosic conversion where gasification competes for syngas pathways.
The U.S. Environmental Protection Agency administers Renewable Fuel Standard volume obligations that mandate minimum biofuel blending percentages, while California Air Resources Board enforces Low Carbon Fuel Standard carbon intensity scoring that rewards cleaner production pathways. The European Union Renewable Energy Directive establishes sustainability criteria for biomass sourcing and greenhouse gas reduction thresholds. Stakeholders must monitor evolving lifecycle assessment methodologies and regional certification schemes that determine market access and premium capture.
Market Dynamics
Hydroprocessed esters and fatty acids (HEFA) technology is redirecting capital flows from road transport biofuels toward aviation applications, compressing ethanol margins while expanding renewable diesel capacity.
Growth Catalysts
- California LCFS carbon intensity scoring:The California Air Resources Board rewards cleaner production pathways with tradeable credits, incentivizing waste oil feedstock investments over virgin crop oils.
- Aviation sector decarbonization mandates:International Air Transport Association member airlines face binding carbon reduction targets that sustainable aviation fuel uniquely satisfies.
- Brazilian sugarcane ethanol corridor:Mature crushing infrastructure and favorable agroclimatic conditions concentrate cost-competitive cellulosic feedstock development.
Market Restraints
- Feedstock cost volatility:Used cooking oil and tallow prices fluctuate with restaurant sector output and animal processing volumes, compressing refinery margins unpredictably.
- Midwest supply concentration:Iowa and Illinois corn ethanol capacity dominates North American production, creating weather-driven yield risk and logistical bottlenecks.
- Lignocellulosic conversion limits:Pretreatment energy intensity and enzyme costs prevent commercial scale-up of agricultural residue pathways despite technical feasibility.
Strategic Opportunities
- EU Renewable Energy Directive sustainability criteria:Delegated acts on indirect land-use change create premium market access for certified waste-based feedstocks.
- Algae cultivation systems:Closed photobioreactors and open pond hybrids promise lipid yields per hectare an order of magnitude above oilseed crops with brackish water tolerance.
- Marine fuel bunkering:International Maritime Organization sulfur regulations and carbon intensity indicators open renewable diesel demand at Rotterdam and Singapore hubs.
Industry Challenges
- ISCC and RSB certification timelines:Multi-month audit processes for international sustainability and carbon certification delay offtake agreements with obligated parties.
- Biorefinery capex intensity:Hydroprocessing unit investments for renewable diesel and sustainable aviation fuel require billion-dollar commitments with decade-long payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Fuel Materials Market |
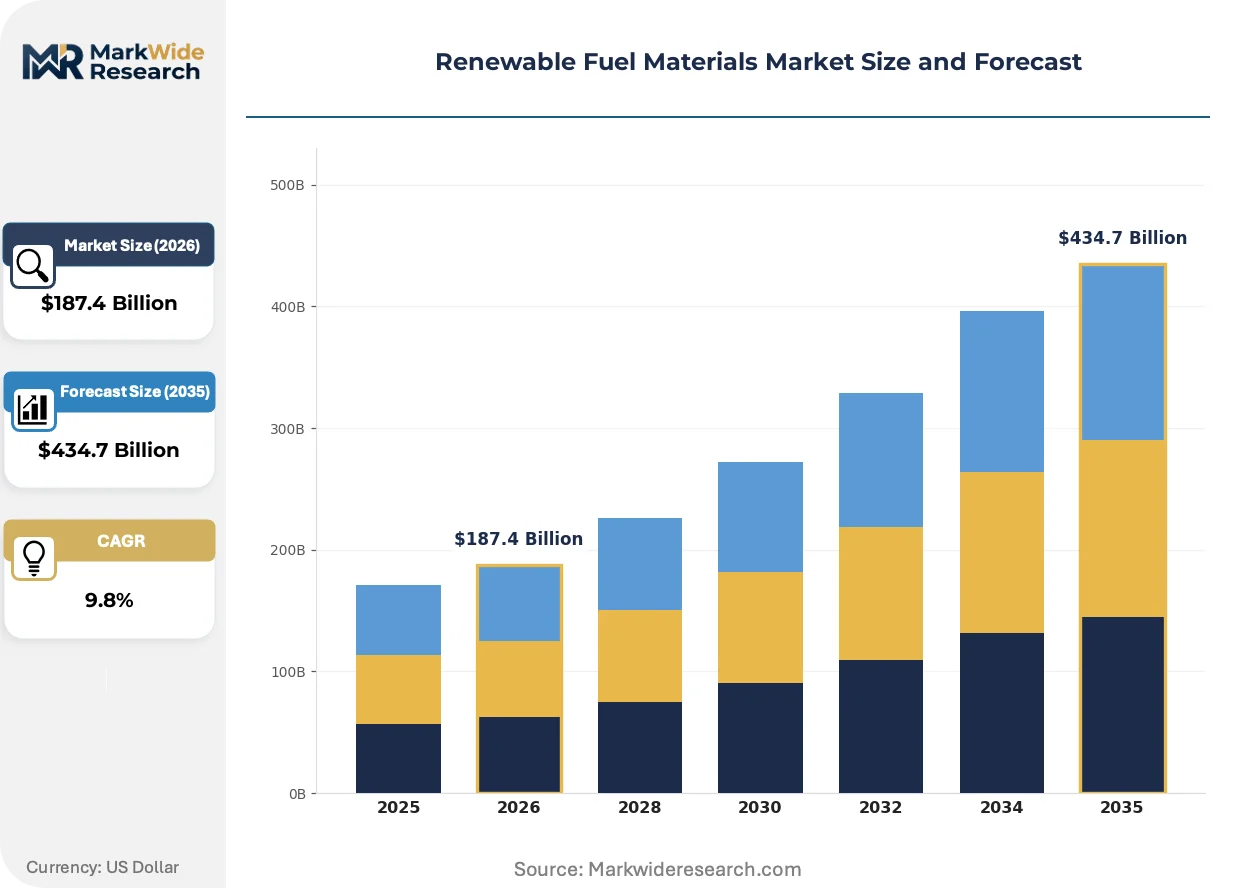
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $434.7 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Corn, Sugarcane, Waste Oils, Algae Production Technology: Fermentation, Gasification, Transesterification, Pyrolysis End Use: Transportation, Power Generation, Heating, Industrial Applications Market Player Type: Producers, Distributors, Equipment Suppliers, Research Institutions |
| Companies Covered | POET LLC, Archer Daniels Midland, Valero Energy, Green Plains Inc., Neste Corporation, Flint Hills Resources LP, Abengoa Bioenergy, TotalEnergies, Renewable Energy Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Fuel Materials Market Trends and Innovations
Technology trajectories in renewable fuel materials are diverging between mature fermentation and hydroprocessing platforms and emerging thermochemical pathways, with regulatory carbon accounting methods determining which platforms attract capital.
Gasification-FT synthesis is bifurcating from pyrolysis as the dominant thermochemical route for lignocellulosic biomass, with commercial projects in Sweden and the Netherlands targeting Fischer-Tropsch waxes for hydrocracker co-feeding. Aviation fuel buyers are underwriting offtake agreements for gasification-derived sustainable aviation fuel at price premiums to HEFA, betting on superior lifecycle carbon scores. This technology is bifurcating project finance between established oil majors with hydroprocessing assets and venture-backed developers pursuing greenfield gasification.
The U.S. Environmental Protection Agency Renewable Fuel Standard volume obligations are tightening advanced biofuel mandates while constraining conventional ethanol growth, redirecting merchant refinery investments toward cellulosic pathways. Industrial consequence includes idled corn ethanol capacity in Nebraska and Kansas as operators await clarity on eRIN eligibility for renewable electricity. The power-to-liquids segment is most affected, with project developers accelerating electrolyzer procurement to secure qualifying renewable electricity pathways.
Long-term offtake contracting is displacing spot market purchases among obligated parties seeking supply security under California's Low Carbon Fuel Standard banking provisions. Fuel marketers and airlines are locking in five- to ten-year purchase agreements with fixed-price escalators, transferring volume risk to producers while capturing carbon credit upside. This shift is most visible in the San Francisco Bay Area and Los Angeles basin, where integrated oil companies are restructuring trading desks around structured biofuel origination rather than traditional petroleum arbitrage.
Renewable Fuel Materials Market Segmentation
Feedstock heterogeneity and technology pathway diversity create distinct margin pools across the renewable fuel materials landscape. Segmentation reveals where capital deployment concentrates and which production configurations align with tightening carbon intensity regulations.
Feedstock Type:
Corn and sugarcane dominate domestic processing volumes, while waste oils and algae attract export-oriented capacity investments seeking premium carbon credit markets.
- Corn:Starch-rich kernels processed via dry-grind fermentation yield ethanol meeting U.S. EPA Renewable Fuel Standard volume obligations. Midwest crushing infrastructure concentrates in Iowa and Illinois, with weather-driven yield volatility creating supply risk for obligated blenders.
- Sugarcane:Brazilian Center-South region leverages established milling infrastructure and favorable agroclimatic conditions for cost-competitive ethanol production. Bagasse co-generation and cellulosic conversion pilots extend value extraction beyond sucrose fermentation.
- Waste Oils:Used cooking oil and tallow feed hydroprocessed ester and fatty acid pathways for renewable diesel and sustainable aviation fuel.
- Algae:Closed photobioreactor systems promise lipid yields per hectare exceeding oilseed crops with brackish water tolerance.
Corn holds the largest share; momentum sits with waste oils as California LCFS credit values reward lower carbon intensity scores.
Production Technology:
Cost tier separation distinguishes mature fermentation platforms from capital-intensive thermochemical routes still seeking commercial scale.
- Fermentation:Yeast-mediated sugar conversion to ethanol operates at full commercial scale with established enzyme supply chains and refinery integration. Corn and sugarcane feedstocks dominate throughput, though lignocellulosic variants face enzyme cost barriers.
- Gasification:High-temperature biomass conversion to syngas enables Fischer-Tropsch synthesis of paraffinic fuels with superior aviation blend properties. Swedish and Dutch projects target wax hydrocracker co-feeding for sustainable aviation fuel offtake agreements.
- Transesterification:Catalyzed reaction of triglycerides with methanol yields fatty acid methyl esters for biodiesel blending.
- Pyrolysis:Thermal decomposition of lignocellulosic biomass produces bio-oil requiring substantial upgrading for fuel compatibility.
Fermentation holds the largest share; gasification is climbing the fastest as aviation fuel buyers underwrite long-term offtake at price premiums to HEFA routes.
End Use:
Application concentration varies sharply by fuel specification requirements and regulatory obligation structures across transport and stationary energy.
- Transportation:Road transport ethanol blending and renewable diesel distribution anchor current volumes, while sustainable aviation fuel offtake agreements redirect procurement priorities. International Air Transport Association carbon targets drive airline procurement restructuring.
- Power Generation:Biogas and biomass co-firing in utility boilers serves renewable portfolio standard compliance in regulated electricity markets.
- Heating:Biodiesel and renewable heating oil substitutions address building sector decarbonization in European district heating networks.
- Industrial Applications:Process heat and combined heat and power systems in food processing and pulp sectors utilize biomass-derived fuels.
Transportation holds the largest share; momentum sits with aviation applications as hydroprocessing capacity expands toward jet fuel specifications.
Market Player Type:
Customer type fragmentation separates asset-heavy producers from trading intermediaries and technology licensors with divergent capital intensity profiles.
- Producers:Integrated agribusiness operators and independent biorefiners control feedstock origination and fuel manufacturing, with POET LLC and Archer Daniels Midland exemplifying Midwest corn ethanol concentration.
- Distributors:Fuel marketers and terminal operators manage blending logistics and carbon credit aggregation for obligated parties under state and federal programs.
- Equipment Suppliers:Engineering firms and technology licensors provide pretreatment systems, hydroprocessing units, and algae cultivation infrastructure.
- Research Institutions:National laboratories and university consortia advance enzyme engineering, catalyst development, and lifecycle assessment methodologies.
Producers hold the largest share; equipment suppliers are gaining share fastest as greenfield renewable diesel and sustainable aviation fuel projects drive billion-dollar hydroprocessing investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian sugarcane ethanol flows to European aviation buyers under EU Renewable Energy Directive sustainability criteria, while U.S. corn-based output supplies domestic road transport blending mandates. Trade corridors now prioritize carbon intensity scores over volumetric proximity.
United States
Iowa and Illinois crush capacity anchors North American ethanol supply, with POET LLC and Archer Daniels Midland controlling origination networks. EPA Renewable Fuel Standard volume obligations tighten advanced biofuel quotas while constraining conventional growth. Midwest biorefineries face idling pressure as operators await eRIN eligibility clarity for renewable electricity pathways.
Brazil
Center-South sugarcane mills supply cost-competitive ethanol to European and Asian buyers seeking low-carbon intensity scores. ANVISA and national biofuel policy frameworks support bagasse co-generation and cellulosic conversion pilots. São Paulo state concentrates crushing infrastructure with favorable agroclimatic conditions extending harvest windows.
Germany
Biogas upgrading facilities and biomass co-firing installations serve building sector decarbonization under EU Green Deal implementation. KBA vehicle certification and REACH chemical registration shape fuel quality specifications. Industrial clusters in North Rhine-Westphalia and Bavaria integrate agricultural residue processing with district heating networks.
Sweden
Gasification-Fischer-Tropsch projects target sustainable aviation fuel offtake agreements with superior lifecycle carbon scores. Government carbon taxation and transport sector emission reduction targets accelerate thermochemical pathway investments. Gothenburg and Stockholm hubs concentrate project development for hydrocracker co-feeding waxes.
Netherlands
Rotterdam marine bunkering infrastructure opens renewable diesel demand under International Maritime Organization sulfur regulations. Port authority carbon intensity indicators and EU Renewable Energy Directive delegated acts create premium access for certified waste-based feedstocks. Integrated oil majors restructure trading desks around structured biofuel origination.
Renewable Fuel Materials Market Competitive Landscape
Listed leaders compete with private specialists across feedstock origination and hydroprocessing technology deployment. Market structure concentrates around integrated agribusiness operators with captive supply chains and independent biorefiners with merchant offtake flexibility. Three archetypes dominate: agricultural originators extending into downstream fuel manufacturing, petroleum refiners retrofitting hydroprocessing assets for renewable output, and technology licensors monetizing proprietary conversion platforms. Competitive moves center on billion-dollar biorefinery capex commitments and multi-year offtake contracting to secure carbon credit banking provisions.
Within the agricultural originator tier, POET LLC and Archer Daniels Midland exemplify Midwest corn ethanol concentration through captive crushing infrastructure and established enzyme supply relationships. Neste Corporation occupies a position representing technology-led differentiation in renewable diesel and sustainable aviation fuel hydroprocessing. These three anchors illustrate how feedstock control, refining scale, and proprietary platform access create divergent margin capture mechanisms across regulatory jurisdictions with tightening carbon intensity scoring methodologies.
| Leading Market Players |
|---|
| POET LLC |
| Archer Daniels Midland |
| Valero Energy |
| Green Plains Inc. |
| Neste Corporation |
| Flint Hills Resources LP |
| Abengoa Bioenergy |
| TotalEnergies |
| Renewable Energy Group Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracting locks in both supply access and price visibility for renewable fuel materials, transferring volume risk from aviation fuel buyers to producers while securing California LCFS credit banking provisions under fixed-price escalators spanning five to ten years.
Pricing Analysis
The hydroprocessing-fermentation pricing gap separates mature corn ethanol platforms from capital-intensive sustainable aviation fuel routes, with gasification-Fischer-Tropsch projects commanding premiums based on superior lifecycle carbon scores. Three-tier pricing structure across certified waste-based, conventional crop-derived, and emerging algae feedstocks reflects carbon intensity differentiation under EU and California regulatory frameworks. Cost compression in conventional ethanol runs through idled Midwest capacity and eRIN eligibility uncertainty, while merchant biorefiners face the sharpest price sensitivity as obligated parties consolidate procurement around integrated producers with captive supply chains.
Supply Chain Analysis
Brazil and the United States anchor feedstock origination, with Center-South sugarcane mills and Iowa-Illinois corn crushing infrastructure supplying distinct regulatory markets. Used cooking oil and tallow feedstocks draw from restaurant sector output and animal processing volumes, creating dependency on volatile waste stream availability. Single-source vulnerability concentrates in Midwest ethanol logistics, where weather-driven yield risk and rail bottlenecks threaten obligated blender compliance. Distribution runs through Rotterdam and Singapore marine bunkering hubs, integrated oil major trading desks, and state-level renewable fuel standard compliance systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from electrification in road transport and power-to-liquids pathways in aviation, as battery-electric vehicle adoption and electrolyzer-based e-fuel development threaten volumetric demand for fermentation-derived ethanol and hydroprocessed esters.
For Market Incumbents: Secure long-term waste oil supply agreements ahead of EU Renewable Energy Directive delegated acts tightening indirect land-use change criteria, locking in premium market access before certification timelines extend. Anchor Midwest capacity through backward integration into corn origination networks, insulating against merchant margin compression from eRIN policy uncertainty and idling pressure in Nebraska and Kansas. For New Entrants and Emerging Players: Differentiate on algae cultivation systems with brackish water tolerance and closed photobioreactor lipid yields, targeting aviation fuel buyers seeking superior carbon intensity scores beyond HEFA route limitations. Penetrate marine bunkering demand at Rotterdam and Singapore under International Maritime Organization sulfur regulations, leveraging renewable diesel specifications as a beachhead before scaling to sustainable aviation fuel offtake. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated biorefiners with captive feedstock origination and multi-year offtake contracts indexed to LCFS credit values, offering visibility absent in merchant operators exposed to spot feedstock markets. Target equipment suppliers with proprietary hydroprocessing technology licenses, watching electrolyzer procurement acceleration as the inflection signal for power-to-liquids project finance viability.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Offtake Contracting | Five-to-ten-year purchase agreements with fixed-price escalators secure California LCFS credit banking provisions for obligated parties. |
| Backward Integration into Feedstock Origination | Captive corn crushing infrastructure in Iowa and Illinois insulates POET LLC and Archer Daniels Midland from merchant margin volatility. |
| Proprietary Hydroprocessing Technology Licensing | Neste Corporation's NEXBTL platform differentiation captures renewable diesel and sustainable aviation fuel premium markets. |
| Algae Cultivation System Scale-Up | Closed photobioreactors with brackish water tolerance promise lipid yields an order of magnitude above oilseed crops. |
| Gasification-Fischer-Tropsch Project Development | Swedish and Dutch commercial projects target hydrocracker co-feeding waxes for aviation fuel buyers underwriting price premiums. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with biorefinery operations managers, aviation fuel procurement officers, renewable fuel standard compliance specialists, and agricultural commodity traders; and secondary validation through EPA Renewable Fuel Standard volume obligation filings, California Air Resources Board LCFS credit transaction data, EU Renewable Energy Directive delegated acts, customs trade records for ethanol and biodiesel flows, and IEA biofuel market reports. Bottom-up capacity and throughput estimates triangulated against top-down regulatory mandate calculations.
Across the projection horizon, the analytical framework modeled feedstock type, production technology pathway, end-use application, and market player type segmentation dimensions. CAGRs were derived from volume obligation trajectories, carbon intensity score evolution, and announced biorefinery capex commitments. Forecast inputs incorporated enzyme cost curves for lignocellulosic conversion, hydroprocessing unit utilization rates, and sustainable aviation fuel blend wall constraints.
Decision-makers should treat outputs as directional under sustained EPA and California LCFS mandate enforcement, EU Renewable Energy Directive sustainability criteria stability, and aviation sector decarbonization commitment durability; material deviation in regulatory stringency or feedstock cost trajectories would warrant model refresh. Recalibration cycles align with material shifts in carbon credit pricing, biorefinery project commissioning timelines, and thermochemical pathway commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Bio-Based Ethylene Market