
 Butyraldehyde Market | 2026-2036
Butyraldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Butyraldehyde Market Analysis
Long-term supply contracts with embedded price-adjustment mechanisms is rebalancing how butyraldehyde volumes transact, shifting risk from spot volatility toward predictable offtake structures. BASF leverages its integrated oxo-alcohol complex in Ludwigshafen to sustain captive feedstock security across European demand nodes. OXEA GmbH anchors its merchant position through dedicated aldehyde distillation trains serving coating resin formulators. Mitsubishi Chemical Group Corporation competes on specification breadth, offering pharmaceutical-grade material alongside standard industrial grades.
Butyraldehyde, a four-carbon aldehyde produced via propylene hydroformylation or n-butanol oxidation, contains a terminal carbonyl group that enables condensation, reduction, and oxidation chemistries for downstream synthesis. The chemical serves primarily as an intermediate for n-butanol, 2-ethylhexanol, and polyvinyl butyral resin production across adhesive and safety-glass applications. Plasticizers as an application dimension lead current volume absorption, with phthalate and non-phthalate ester producers representing the dominant demand pool. Resins as an application category occupies higher margin territory, particularly where optical-grade polyvinyl butyral commands specification premiums for automotive laminated glass. n-Butanol as a product type dominates the derivative chain, though butyric acid output is gaining traction from food-grade and pharmaceutical-grade certification requirements.
EPA oversight of volatile organic compound emissions shapes formulation limits in U.S. coatings and adhesive end uses, while REACH registration obligations in Europe constrain non-compliant import volumes. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for oxo-alcohol production clusters, elevating compliance costs for domestic producers. Stakeholders must monitor how regional carbon border adjustments reshape cost competitiveness between Middle Eastern feedstock-advantaged supply and Asian derivative-integrated operations.
Market Dynamics
Integrated oxo-alcohol complexes are consolidating feedstock security, while REACH purity mandates and China's dual carbon goals are compressing merchant supply margins and reshaping competitive positioning among derivative producers.
Growth Catalysts
- Automotive interior plasticizer demand:Laminated safety glass specifications are tightening across OEM supply chains, pulling higher-purity butyraldehyde into polyvinyl butyral resin formulations.
- REACH registration thresholds:ECHA compliance requirements for downstream chemical intermediates are filtering out non-compliant import volumes, tightening effective supply for registered European formulators.
- Propylene hydroformylation efficiency gains:Low-pressure rhodium-catalyzed processes are displacing cobalt-based systems, improving carbon selectivity and reducing energy intensity per ton of aldehyde output.
Market Restraints
- Propylene feedstock volatility:Crude-linked naphtha cracking margins and PDH unit economics transmit directly into oxo-alcohol cost structures, compressing producer margins during upstream price spikes.
- Merchant supply concentration:Ludwigshafen and Marl production clusters anchor European supply, creating geographic vulnerability to unplanned outages or logistics disruptions.
- Phthalate substitution pressure:Non-phthalate plasticizer chemistries including bio-based esters are displacing conventional formulations in sensitive consumer applications.
Strategic Opportunities
- Pharmaceutical-grade certification pathways:USP and EP monograph compliance for butyric acid derivatives is opening margin premiums in excipient and active pharmaceutical ingredient supply chains.
- Coating resin formulator consolidation:Dedicated aldehyde distillation capacity serving waterborne acrylic and alkyd systems is capturing volume from solvent-borne alternatives under EPA VOC limits.
- China's MEE dual carbon enforcement:Energy intensity benchmarks for oxo-alcohol clusters are accelerating closure of marginal coal-based propylene units, tightening domestic supply and expanding import windows for compliant producers.
Industry Challenges
- Process safety expertise scarcity:Hydroformylation unit operation and rhodium catalyst handling require specialized technical talent that is concentrating at integrated majors.
- Multi-jurisdiction certification timelines:Parallel REACH, TSCA, and China REACH registrations for new derivative grades extend commercialization cycles by 18-36 months.
- Legacy distillation asset retrofit costs:Pharmaceutical-grade purity specifications demand column revamps and analytical infrastructure that strain mid-scale merchant producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butyraldehyde Market |
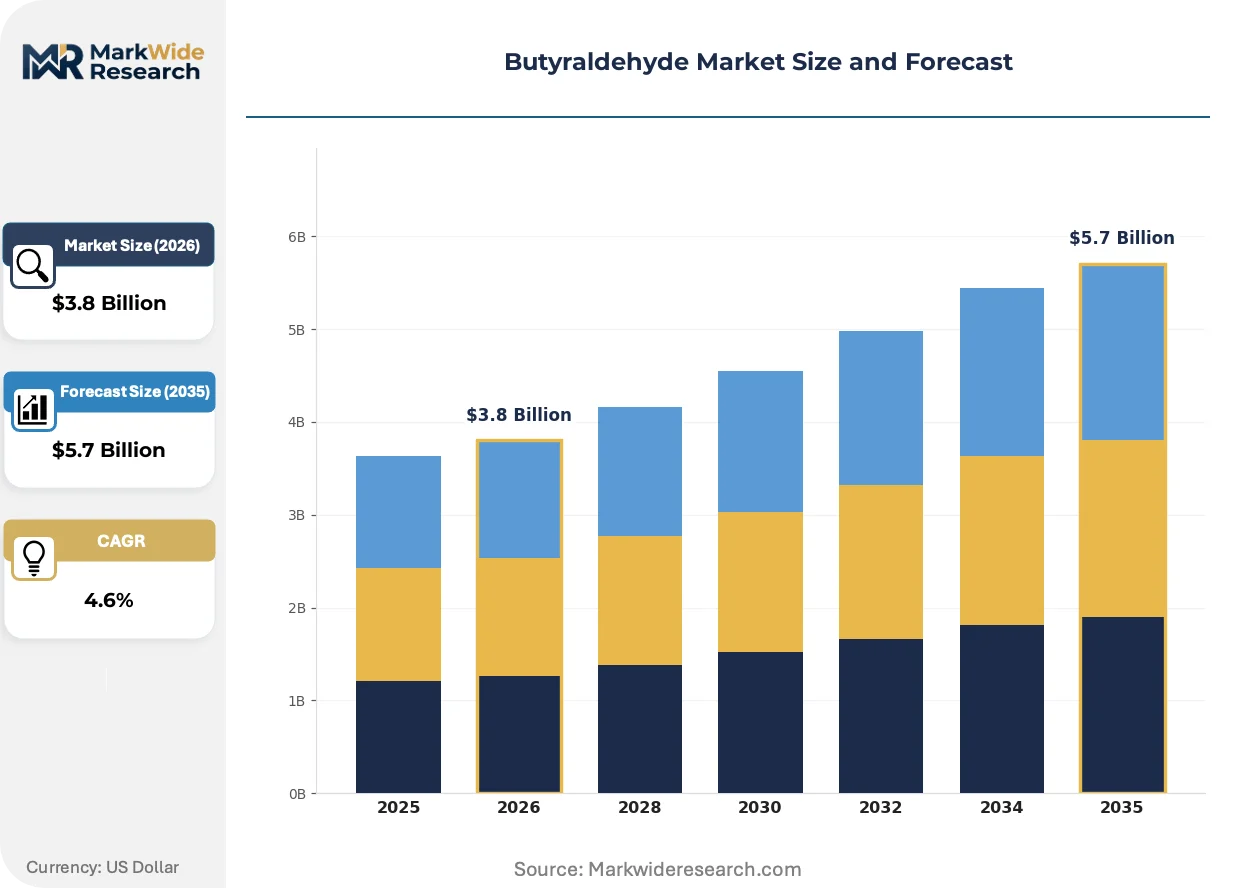
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Butyric Ester, Butyraldehyde Dimers, Butyric Acid, n-Butanol End Use Industry: Agriculture, Automotive, Chemicals, Pharmaceuticals Application: Adhesives, Coatings, Resins, Plasticizers Form: Liquid, Solid, Gas, Concentrate |
| Companies Covered | Eastman Chemical Company, KH Neochem Co., Ltd., BASF, LG Chem, Perstorp, Mitsubishi Chemical Group Corporation, OXEA GmbH, Grupa Azoty, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butyraldehyde Market Emerging Trajectories
Process intensification and regulatory chemistry are compressing traditional production economics while specification breadth is fragmenting demand into tiered value pools.
Membrane separation technology for aldehyde-alcohol purification is expanding into merchant butyraldehyde production, enabling pharmaceutical-grade output without energy-intensive extractive distillation. Coating resin formulators in Germany and the Netherlands are adopting membrane-refined material for waterborne automotive clearcoats. This capability is expanding into new geographic supply nodes previously constrained by distillation train economics.
EPA volatile organic compound emission limits under 40 CFR 59 are forcing adhesive and sealant formulators toward exempt solvent systems, redirecting butyraldehyde-derived plasticizer demand into compliant resin architectures. Laminated glass producers serving the US automotive aftermarket are reformulating interlayers to meet SCAQMD Rule 1168. Safety-glass manufacturers are responding by qualifying higher-purity resin grades that reduce volatile residuals.
Long-term offtake contracting with embedded propylene price-adjustment mechanisms is displacing spot-market volume for derivative producers. n-Butanol and 2-ethylhexanol buyers in China are locking in twelve to twenty-four month supply agreements with integrated oxo-alcohol suppliers. This pattern is most visible in Shandong and Jiangsu provinces where downstream plasticizer capacity is consolidating under fewer large-scale operators.
Butyraldehyde Market Segmentation
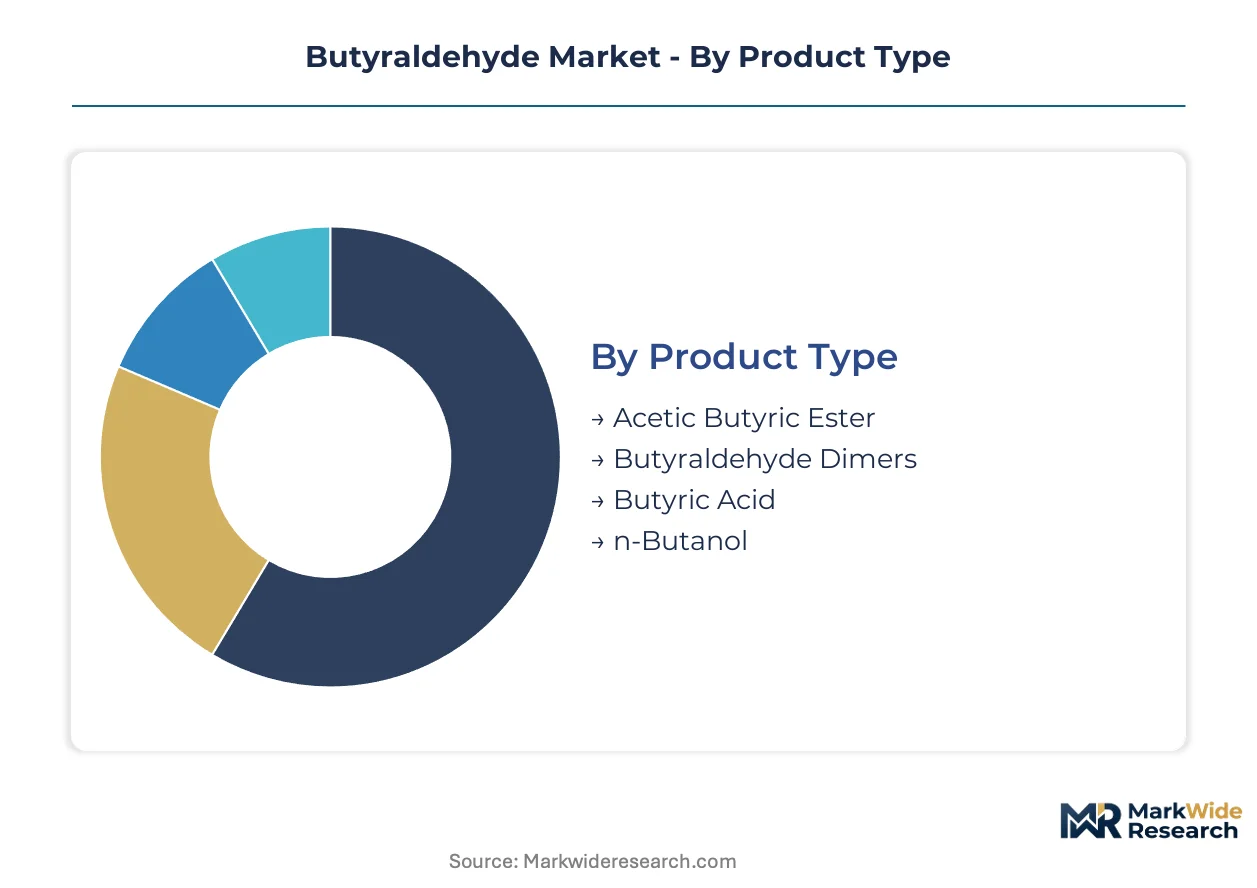
Butyraldehyde derivatives fragment into distinct value pools based on purity thresholds, regulatory certification requirements, and captive versus merchant supply economics. Each segment tier commands different margin structures and technical qualification barriers.
Product Type:
Supply concentration in integrated oxo-alcohol complexes favors derivatives with backward integration into propylene feedstock, while merchant-grade products face margin compression from energy intensity regulations.
- n-Butanol:The four-carbon primary alcohol dominates derivative output from hydroformylation trains, serving plasticizer and coating solvent applications. Demand concentrates in Shandong province plasticizer clusters, where n-butanol feeds phthalate and non-phthalate ester production for automotive interior specifications.
- Butyric Acid:Oxidation of butyraldehyde yields this short-chain carboxylic acid with food-grade and pharmaceutical-grade certification pathways. USP and EP monograph compliance opens margin premiums in excipient supply chains, with specialty chemical producers capturing value from multi-jurisdiction registration expertise.
- Acetic Butyric Ester:Esterification product serving fragrance and flavor applications with moderate volume scale.
- Butyraldehyde Dimers:Condensation derivatives for specialty resin crosslinking with niche demand profile.
Today's leader: n-Butanol. Tomorrow's challenger: Butyric Acid.
End Use Industry:
Cost tier differentiation separates commodity chemical applications from certified pharmaceutical and food-grade supply chains, with regulatory compliance costs creating segmentation barriers.
- Chemicals:Intermediate consumption for oxo-alcohol derivatives, coating solvents, and resin precursors. Ludwigshafen and Marl production clusters anchor European supply to German and Dutch formulators, with REACH registration filtering non-compliant import volumes.
- Automotive:Polyvinyl butyral resin demand for laminated safety glass interlayers drives specification premiums. OEM supply chains in Stuttgart and Wolfsburg pull optical-grade material for windshield applications, with SCAQMD Rule 1168 compliance reshaping US aftermarket formulations.
- Pharmaceuticals:Butyric acid derivatives for excipient and active ingredient synthesis with certification-driven pricing.
- Agriculture:Limited butyraldehyde derivative use in agrochemical intermediates with regional volume concentration.
Volume concentrates in Chemicals. Margin expansion concentrates in Pharmaceuticals.
Application:
Customer type segmentation separates large-scale integrated buyers from specialty formulators with distinct procurement patterns and specification requirements.
- Plasticizers:Phthalate and non-phthalate ester production absorbs the dominant butyraldehyde derivative volume, with n-butanol feeding DOTP, DINP, and bio-based alternatives. Jiangsu province capacity consolidation under fewer large-scale operators is locking in twelve to twenty-four month supply agreements.
- Resins:Polyvinyl butyral for safety-glass interlayers commands specification premiums where optical clarity and volatile residual limits matter. Waterborne acrylic and alkyd coating systems in Germany and the Netherlands are adopting membrane-refined material for automotive clearcoats.
- Adhesives:Solvent-borne and waterborne formulations with EPA VOC limits redirecting demand toward compliant resin architectures.
- Coatings:Automotive and industrial finishes with exempt solvent system qualifications under 40 CFR 59.
Plasticizers represent the fastest-growing trajectory by volume. Resins represent the fastest-growing trajectory by margin.
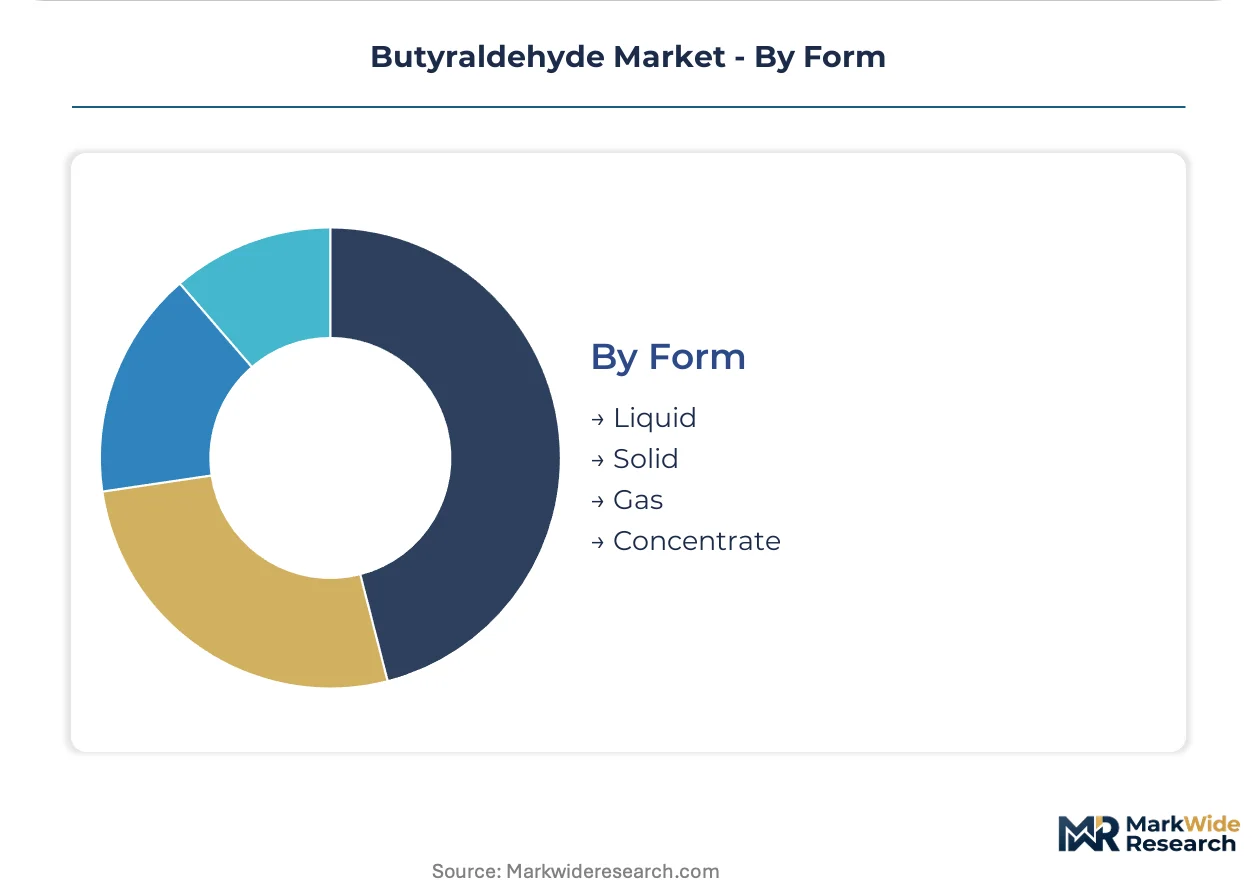
Form:
Maturity-based segmentation separates established liquid handling infrastructure from emerging purification technologies enabling solid and concentrate grades.
- Liquid:Standard industrial grade delivered in bulk tank cars and drums, dominating merchant trade flows.
- Concentrate:High-purity material for pharmaceutical and electronic applications with membrane separation enabling output without extractive distillation.
- Solid:Derivative salts and encapsulated forms for controlled-release applications.
- Gas:Vapor-phase handling for specific reactor feed applications with limited scale.
Liquid maintains infrastructure dominance. Concentrate captures technology-driven premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting butyraldehyde production toward jurisdictions where feedstock security outweighs compliance costs, with integrated complexes in Germany and China capturing margin from REACH-bound European formulators and carbon-constrained Asian competitors respectively.
China
Shandong and Jiangsu province plasticizer clusters absorb dominant n-butanol derivative volumes, with provincial energy intensity benchmarks under MEE dual carbon enforcement accelerating closure of marginal coal-based propylene units. MEE enforcement tightens oxo-alcohol production benchmarks, elevating compliance costs for domestic producers and expanding import windows for compliant Middle Eastern supply. Ningbo and Shanghai port complexes are consolidating merchant butyraldehyde throughput for re-export to Southeast Asian coating resin formulators.
Germany
Ludwigshafen and Marl production clusters anchor European supply to coating resin and automotive safety-glass formulators across the Rhine-Ruhr industrial corridor. ECHA REACH registration thresholds filter non-compliant import volumes, tightening effective supply for registered downstream chemical processors. BASF's integrated oxo-alcohol complex sustains captive feedstock security across German and Dutch demand nodes serving waterborne automotive clearcoat specifications.
United States
Gulf Coast petrochemical corridors leverage ethane-advantaged cracker economics to feed propylene hydroformylation trains, with Texas and Louisiana complexes serving domestic plasticizer and adhesive formulators. EPA oversight under 40 CFR 59 shapes volatile organic compound emission limits in coatings and adhesive end uses, redirecting butyraldehyde-derived demand toward compliant resin architectures. SCAQMD Rule 1168 in California reshapes aftermarket laminated glass formulations, pulling higher-purity material into safety-glass interlayer specifications.
Japan
Kanto and Kansai industrial belts concentrate pharmaceutical-grade butyric acid derivative production, with METI industrial standards governing excipient and active ingredient synthesis certification. PMDA oversight of pharmaceutical intermediates extends commercialization timelines for new derivative grades, creating segmentation barriers against non-compliant import competition. Mitsubishi Chemical Group Corporation operations in the Yokkaichi complex exemplify specification breadth strategies spanning industrial and pharmaceutical-grade material.
Saudi Arabia
Jubail and Yanbu industrial cities leverage feedstock-advantaged ethane cracking to supply propylene derivatives into Asian and European merchant markets, with SABIC-anchored complexes competing on carbon intensity metrics against coal-based Asian supply. The country's national industrial regulator enforces product quality standards for chemical exports, with carbon border adjustment exposure in European destination markets elevating low-carbon production premiums. Red Sea logistics corridors position Saudi supply to capture volume from China's tightening domestic energy intensity benchmarks.
Butyraldehyde Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oxo-alcohol complexes commanding captive feedstock security while merchant aldehyde distillation specialists serve specification-sensitive coating resin formulators. The vendor base stratifies across three archetypes: petrochemical majors with backward integration into propylene feedstock, regional aldehyde specialists with dedicated purification trains, and diversified chemical conglomerates with pharmaceutical-grade certification pathways. Dominant competitive moves include long-term offtake contracting with embedded price-adjustment mechanisms and membrane separation technology licensing for pharmaceutical-grade output.
Among German-based integrated producers, BASF and OXEA GmbH represent contrasting strategic positions—BASF anchoring captive supply security across European demand nodes, OXEA occupying dedicated merchant aldehyde distillation capacity serving coating resin formulators. Mitsubishi Chemical Group Corporation exemplifies specification breadth archetypes, with its operations spanning industrial-grade and pharmaceutical-grade material certification. These three companies illustrate how geographic positioning and purity-tier specialization fragment competitive advantage across derivative value chains.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| KH Neochem Co., Ltd. |
| BASF |
| LG Chem |
| Perstorp |
| Mitsubishi Chemical Group Corporation |
| OXEA GmbH |
| Grupa Azoty |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Propylene price volatility cascades through butyraldehyde value chains, compressing margins for merchant producers while integrated oxo-alcohol complexes capture cost advantages through captive feedstock security. Long-term offtake contracts with embedded price-adjustment mechanisms are displacing spot-market volume, rebalancing risk allocation between derivative buyers and aldehyde suppliers.
Pricing Analysis
Distributor margins for pharmaceutical-grade material run wider than standard industrial grades, reflecting USP and EP monograph compliance costs. Pricing stratifies across premium, standard, and economy tiers based on purity thresholds and certification levels. Cost compression in merchant supply stems from REACH-mandated analytical infrastructure investments. Small-scale coating resin formulators exhibit highest price sensitivity, while automotive OEMs absorb specification premiums for optical-grade polyvinyl butyral.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale plasticizer demand from Shandong and Jiangsu province clusters, while merchant aldehyde distillation specialists serve specification-sensitive coating formulators. Supply concentrates in Germany, China, and Saudi Arabia, with Ludwigshafen, Ningbo, and Jubail anchoring regional throughput. Production draws from propylene feedstocks sourced via naphtha cracking, PDH units, and ethane-advantaged crackers. Single-source vulnerability to unplanned outages at Ludwigshafen or Marl complexes represents structural risk. Distribution runs through integrated oxo-alcohol complexes and dedicated aldehyde distillation trains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Butyraldehyde markets reward margin expansion through pharmaceutical-grade certification pathways and membrane separation technology adoption, with energy intensity regulations accelerating cost-down opportunities for compliant producers.
For Market Incumbents: Deepen backward integration into propylene feedstock to defend against merchant margin compression from MEE dual carbon enforcement. Lock in twelve to twenty-four month offtake agreements with Shandong plasticizer clusters to secure volume against emerging membrane-refined competitors. Prioritize rhodium catalyst efficiency investments over cobalt-based system retrofits. For New Entrants and Emerging Players: Begin with pharmaceutical-grade butyric acid derivatives, where USP and EP monograph compliance creates segmentation barriers against commodity incumbents. Target coating resin formulators in Germany and the Netherlands adopting membrane-refined material for waterborne automotive clearcoats. Lead with analytical infrastructure partnerships rather than distillation asset builds. For Investors and Strategic Acquirers: Asymmetric upside sits with regional aldehyde specialists possessing dedicated purification trains and existing REACH registrations. Five-to-ten year viability favors assets with backward integration optionality into propylene feedstock. Watch for MEE enforcement accelerating domestic Chinese supply rationalization as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive propylene supply insulates margins from naphtha cracking volatility at Ludwigshafen. |
| Membrane Separation Licensing | Pharmaceutical-grade output without extractive distillation captures coating resin premium tiers. |
| Long-term Supply Agreement | Embedded price-adjustment mechanisms reduce spot exposure for Jiangsu plasticizer operators. |
| REACH Registration Investment | ECHA compliance filters non-compliant imports, tightening effective supply for registered formulators. |
| Pharmaceutical-grade Certification | USP and EP monograph compliance opens excipient margin premiums in butyric acid derivatives. |
Methodological Framework
Direct dialogue with oxo-alcohol plant managers, downstream procurement leads at coating resin formulators, distribution channel partners, and technical R&D directors anchored qualitative findings. Secondary validation drew from customs and trade data, Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up volume builds across n-butanol, butyric acid, and derivative product types triangulated against top-down macro chemical consumption trends.
Segment-level outputs across grade tier, end-use industry, and regional production hub informed the analytical framework throughout the projection horizon. CAGRs derived from regression analysis of historical propylene-to-derivative spreads, capacity utilization rates at integrated complexes, and regulatory compliance cost trajectories. Forecast inputs incorporated MEE dual carbon enforcement timelines and REACH registration renewal cycles.
Several conditions sit outside the modeled scope, including unplanned outages at concentrated production clusters, abrupt propylene feedstock price dislocations, and carbon border adjustment implementations. Forecasts reflect documented assumptions around rhodium catalyst efficiency gains and membrane separation adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Green Chemical and Material Market