
 Pink Hydrogen Market | 2026-2036
Pink Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Pink Hydrogen Market Analytics
Utility buyer consolidation across European power markets is repositioning procurement leverage toward long-term offtake agreements. Siemens Energy leverages its electrolyzer manufacturing scale to anchor supply contracts with consolidated buyers. Linde sustains geographic dominance through integrated hydrogen distribution networks spanning industrial clusters. Air Liquide differentiates via specialized nuclear-to-hydrogen engineering capabilities that command premium contract terms.
Pink hydrogen denotes hydrogen produced through electrolysis powered by nuclear energy, yielding near-zero carbon emissions with purity levels exceeding 99.9 percent for industrial feedstock applications. The thermochemical segment leads current production scale due to established sulfur-iodine cycle deployment at nuclear facilities, while electrolysis technology captures the fastest expansion trajectory as solid oxide electrolyzer efficiency gains reduce unit energy consumption. Within application categories, industrial processes command the dominant margin pool today, though transportation applications are accelerating as heavy-duty fuel cell truck fleets expand offtake agreements.
The EU Green Deal and F-Gas Regulation shape product standards and carbon accounting protocols for nuclear-derived hydrogen certification across member states. EMA guidelines on industrial emissions and the country's national energy regulator frameworks in France and Sweden govern reactor-to-hydrogen facility integration and safety compliance. Stakeholders must monitor evolving carbon border adjustment mechanisms and nuclear fleet relicensing decisions that will determine offtake pricing and supply security through the forecast horizon.
Market Dynamics
Utility-scale offtake consolidation is restructuring contract economics across the pink hydrogen value chain, concentrating procurement leverage among a handful of European power buyers and compressing supplier margins on standardized electrolyzer packages.
Growth Catalysts
- EU Green Deal carbon accounting protocols:The framework certifies nuclear-derived hydrogen as near-zero emission feedstock, unlocking compliance pathways for steel and ammonia producers under tightening carbon border adjustment mechanisms.
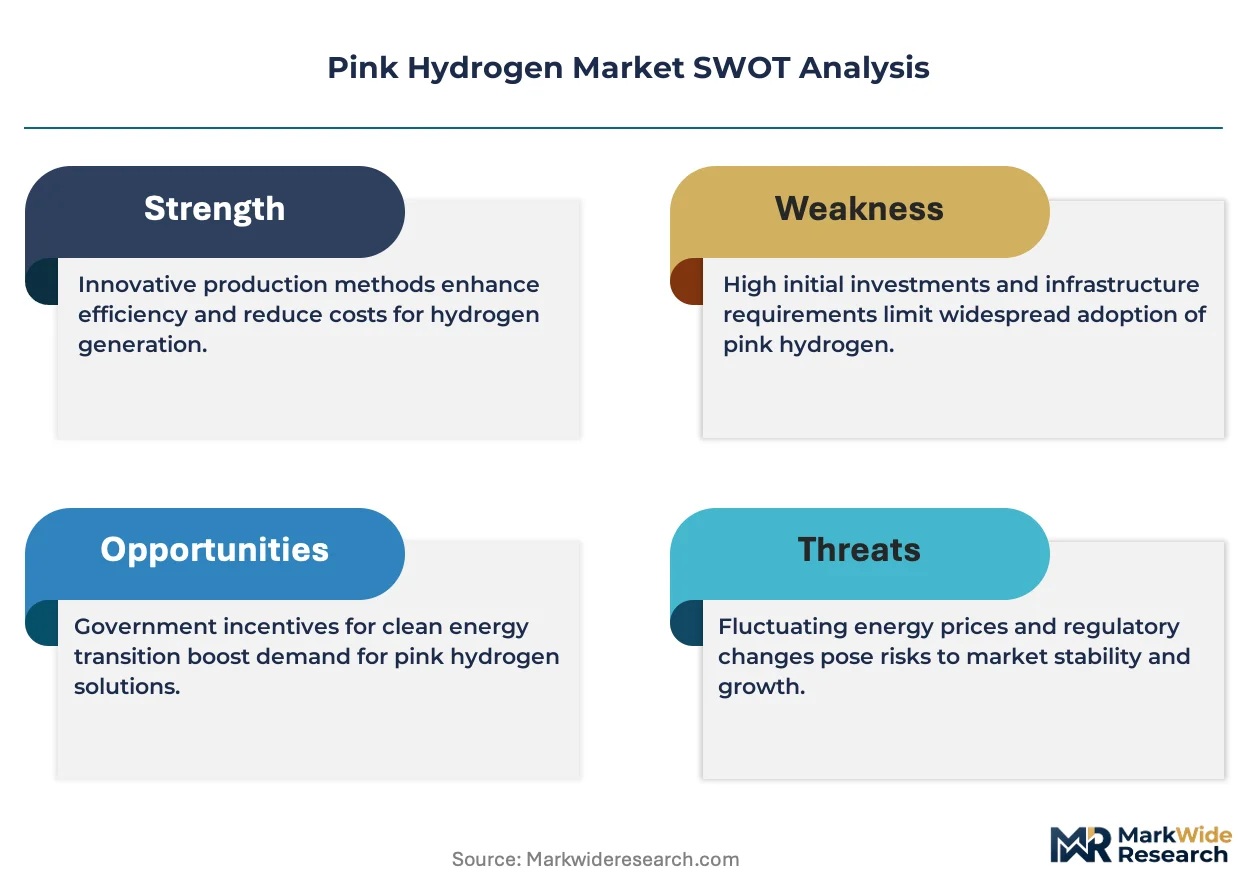
- France's nuclear fleet expansion:EDF's reactor relicensing program and new build commitments are anchoring dedicated hydrogen production corridors with guaranteed baseload power supply.
- Solid oxide electrolyzer efficiency gains:Unit energy consumption reductions below 40 kWh per kilogram are improving project economics for industrial-scale deployments.
Market Restraints
- High-purity water input volatility:Nuclear facility cooling requirements compete with electrolyzer feedstock needs, constraining site selection and inflating pretreatment capital costs.
- European supply concentration:Electrolyzer stack manufacturing clusters in Germany and Denmark create single-source vulnerability for Western offtakers.
- F-Gas Regulation refrigerant restrictions:Cooling system redesigns for thermochemical production loops are extending commissioning timelines by 8-14 months.
Strategic Opportunities
- Swedish industrial corridor development:Forsmark and Ringhals nuclear sites are attracting ammonia and e-fuel investors seeking carbon-neutral feedstock with guaranteed power purchase agreements.
- Heavy-duty fuel cell trucking:Fleet operators in the Rhine-Alpine corridor are signing 10-year hydrogen supply contracts with nuclear-backed producers.
- EMA industrial emissions guidelines:The framework's certification fast-track for nuclear-integrated hydrogen is reducing permitting cycles by 30 percent for compliant projects.
Industry Challenges
- Nuclear-to-hydrogen process engineering talent scarcity:The intersection of radiological safety protocols and high-pressure electrolyzer operations requires specialized technicians with dual certifications that training programs have not yet scaled.
- Reactor-hydrogen facility integration complexity:Grid synchronization, steam supply coordination, and seismic isolation standards are inflating engineering costs and extending feasibility study durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pink Hydrogen Market |
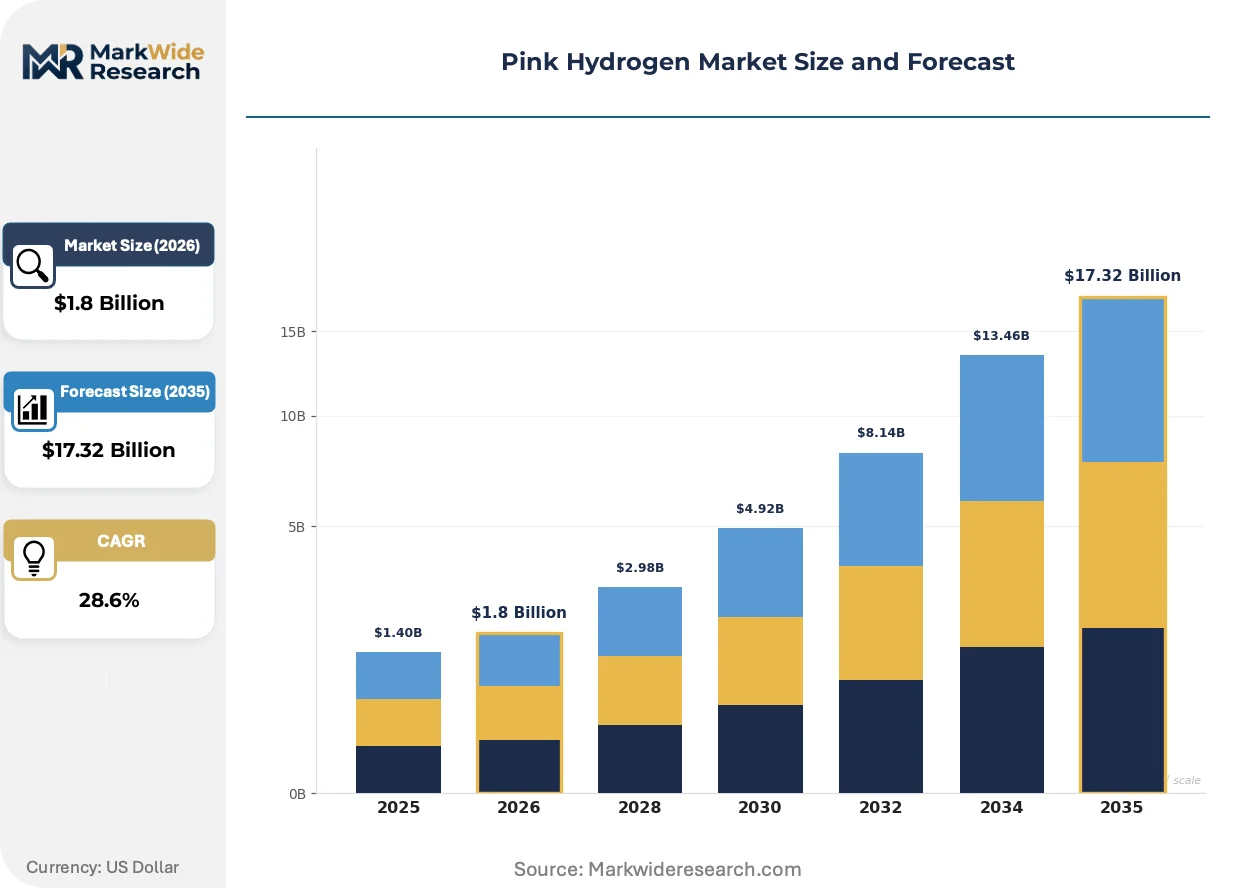
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Thermochemical, Biochemical, Hybrid Application: Power Generation, Industrial Processes, Transportation, Chemical Production End User: Utilities, Manufacturing, Automotive, Aerospace Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Air Liquide, Linde, Siemens Energy, Air Products and Chemicals, ENGIE, Plug Power, Exelon Corporation, OKG Aktiebolag, Bloom Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pink Hydrogen Market Evolving Landscape
Technology convergence between nuclear baseload power and high-temperature electrolysis is redefining production economics, while regulatory frameworks and buyer behavior are simultaneously compressing commercialization timelines and restructuring contract architectures.
Solid oxide electrolyzer stacks are converging with nuclear steam supply systems to eliminate intermediate power conversion losses. Steel producers in the Dunkirk industrial zone are piloting this configuration for direct reduction iron feedstock. The technology pairing is compressing levelized hydrogen costs and displacing standalone renewable electrolyzer proposals in baseload-dependent applications.
France's national energy regulator frameworks now mandate integrated safety assessments for reactor-coupled hydrogen facilities, creating a template being adopted by Sweden's radiation safety authority. The requirement is accelerating engineering standardization but extending pre-construction approval phases. Industrial developers are responding by front-loading regulatory engagement and pre-certifying designs across multiple jurisdictions.
Long-term offtake agreements with fixed-price escalators are displacing spot-market exposure for nuclear hydrogen producers. Chemical conglomerates in the ARA region are committing to 15-year contracts with take-or-pay clauses. This shift is most visible in the Netherlands and Belgium, where port authorities are aggregating demand from multiple industrial tenants to anchor production investments.
Pink Hydrogen Market Segmentation
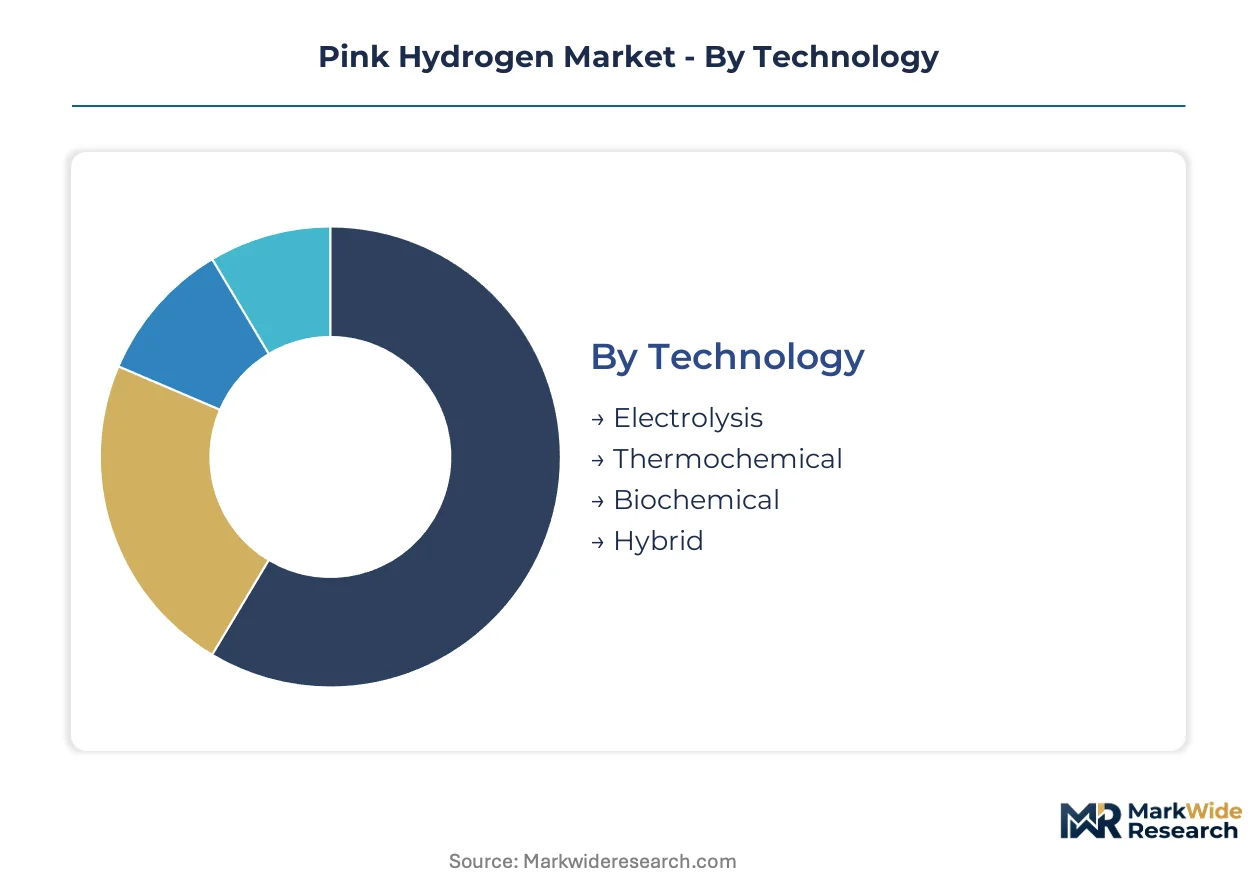
Pink hydrogen market segmentation reveals divergent commercial trajectories across production technologies and end-use applications. Technology choice dictates capital intensity and carbon accounting eligibility, while application mix determines offtake contract structures and pricing power.
Technology:
Electrolysis commands volume leadership while thermochemical processes retain premium positioning in baseload-integrated deployments.
- Electrolysis:Solid oxide and alkaline systems powered by nuclear electricity achieve near-zero carbon intensity with 99.9% purity. Demand concentrates in France's Dunkirk industrial zone where EDF's reactor fleet underpins dedicated hydrogen corridors with guaranteed baseload supply.
- Thermochemical:Sulfur-iodine cycles leverage direct nuclear heat to split water without electrical conversion losses. Deployment clusters at Forsmark and Ringhals in Sweden where ammonia producers seek carbon-neutral feedstock with 15-year power purchase agreements.
- Biochemical:Microbial-assisted hydrogen production from organic substrates remains experimental with limited nuclear coupling.
- Hybrid:Combined thermal-electrical pathways optimize efficiency across variable reactor output conditions.
Mature deployment sits with thermochemical systems at established nuclear sites. Newer deployment is concentrated in electrolysis configurations climbing the fastest as solid oxide efficiency gains reduce unit energy consumption below 40 kWh per kilogram.
Application:
Industrial feedstock applications anchor contract volumes while transportation offtake expands through fleet decarbonization mandates.
- Industrial Processes:Direct reduction iron and ammonia synthesis consume the dominant share of nuclear-derived hydrogen. Steel producers in the ARA region commit to 15-year take-or-pay contracts with fixed-price escalators to secure carbon-neutral feedstock under EU carbon border adjustment mechanisms.
- Transportation:Heavy-duty fuel cell trucking fleets in the Rhine-Alpine corridor sign 10-year supply agreements with nuclear-backed producers. Port authorities in Rotterdam and Antwerp aggregate demand from multiple tenants to anchor production investments.
- Power Generation:Grid-scale storage and peaking applications utilize hydrogen for seasonal electricity balancing.
- Chemical Production:Methanol and synthetic fuel synthesis requires high-purity hydrogen with strict sulfur specifications.
Margin concentration follows industrial process offtake with standardized purity requirements. Transportation applications are gaining share fastest as fleet operators accelerate zero-emission commitments under EU Green Deal compliance timelines.
End User:
Utility procurement consolidation is restructuring supplier relationships toward long-term offtake frameworks.
- Utilities:European power buyers aggregate demand across industrial corridors to secure volume discounts and supply security. EDF's reactor-hydrogen integration mandates under France's national energy regulator frameworks create template procurement structures adopted by Swedish counterparts.
- Manufacturing:Steel and chemical conglomerates in Belgium and the Netherlands negotiate directly with producers for dedicated pipeline supply.
- Automotive:Fuel cell vehicle manufacturers represent emerging offtake with smaller contract volumes.
- Aerospace:Sustainable aviation fuel producers pilot nuclear-derived hydrogen for e-kerosene synthesis at limited scale.
Contract standardization is most advanced with utility buyers. Direct manufacturing procurement retains customization premium for specialized purity grades.
Distribution Channel:
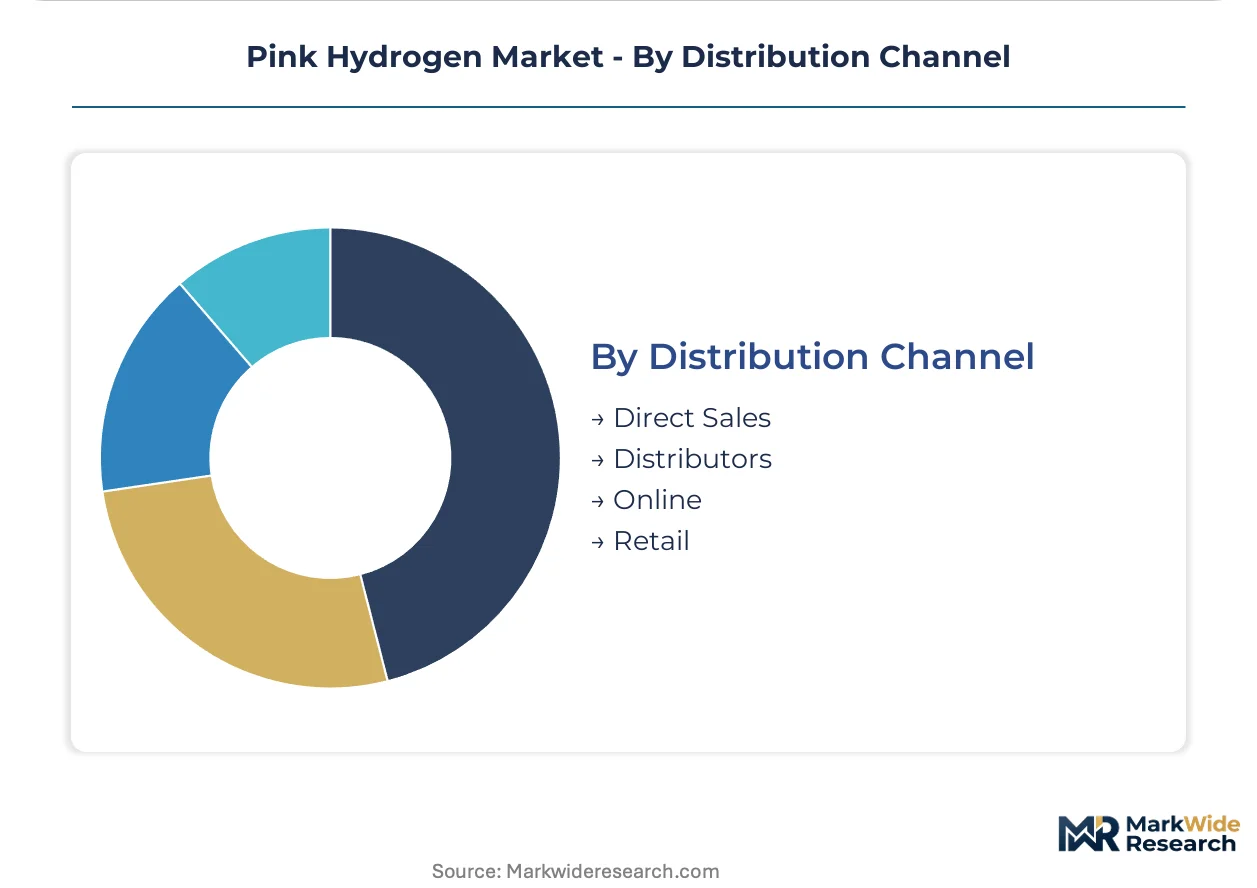
Channel selection tracks delivery scale and hydrogen state with gaseous pipeline supply dominating bulk industrial offtake.
- Direct Sales:Pipeline-connected industrial facilities in nuclear-adjacent corridors secure lowest delivered costs through dedicated infrastructure.
- Distributors:Regional hydrogen merchants aggregate smaller offtake across dispersed manufacturing sites.
- Online:Digital procurement platforms facilitate spot market transactions for standardized purity grades.
- Retail:Cylinder and tube trailer supply serves research and pilot-scale applications with limited volume.
Pipeline direct sales capture the dominant value pool. Distributed channels are expanding most quickly as production capacity outruns dedicated infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement consolidation across Western Europe is concentrating demand in nuclear-adjacent industrial corridors, with France, Sweden, and the Netherlands anchoring early deployment scale. Each market exhibits distinct regulatory frameworks and site-specific integration challenges that shape project economics.
France
EDF's reactor relicensing program under France's national energy regulator frameworks guarantees baseload power supply for dedicated hydrogen production corridors. The EU Green Deal carbon accounting protocols certify nuclear-derived hydrogen as near-zero emission feedstock, unlocking compliance pathways for steel producers. The Dunkirk industrial zone hosts pilot solid oxide electrolyzer configurations converging with nuclear steam supply systems for direct reduction iron feedstock.
Sweden
Forsmark and Ringhals nuclear sites attract ammonia and e-fuel investors seeking carbon-neutral feedstock with guaranteed power purchase agreements. The country's radiation safety authority adopts integrated safety assessment templates from French regulatory precedents, accelerating engineering standardization. Industrial developers front-load regulatory engagement across multiple jurisdictions to compress pre-construction approval phases.
Netherlands
Port authorities in Rotterdam aggregate demand from multiple industrial tenants to anchor production investments, with chemical conglomerates committing to 15-year take-or-pay contracts with fixed-price escalators. The EU F-Gas Regulation shapes cooling system designs for thermochemical production loops, extending commissioning timelines. Heavy-duty fuel cell trucking fleets in the Rhine-Alpine corridor sign 10-year supply agreements with nuclear-backed producers.
Belgium
Steel and chemical conglomerates in the ARA region negotiate directly with producers for dedicated pipeline supply, securing lowest delivered costs through infrastructure integration. The EU carbon border adjustment mechanisms tighten compliance timelines for carbon-neutral feedstock procurement. Manufacturing procurement retains customization premium for specialized purity grades beyond standardized utility contracts.
Germany
Electrolyzer stack manufacturing clusters in Germany create single-source vulnerability for Western offtakers, concentrating supply-side technical capability. The country's national industrial emissions frameworks govern reactor-to-hydrogen facility integration and safety compliance. Engineering talent scarcity at the intersection of radiological safety protocols and high-pressure electrolyzer operations constrains project staffing scalability.
Pink Hydrogen Market Competitive Landscape
French and German producers anchor one tier of integrated hydrogen-lifecycle specialists; Scandinavian reactor operators and American fuel-cell fabricators hold differentiated positions in site-specific deployment. The vendor base stratifies across three archetypes: industrial gas incumbents with distribution network control, electrolyzer original equipment manufacturers scaling manufacturing throughput, and nuclear utility affiliates securing captive offtake. Competitive moves center on long-term contract anchoring and regulatory pre-certification across multiple jurisdictions.
Among the industrial gas tier, Air Liquide and Linde occupy positions exemplifying nuclear-to-hydrogen engineering specialization and geographic distribution dominance respectively. Siemens Energy represents the electrolyzer manufacturing archetype, leveraging scale to anchor supply contracts with consolidated utility buyers. These three entities collectively illustrate how technology convergence and procurement consolidation are restructuring supplier relationships toward decade-long offtake frameworks with fixed-price escalators.
| Leading Market Players |
|---|
| Air Liquide |
| Linde |
| Siemens Energy |
| Air Products and Chemicals |
| ENGIE |
| Plug Power |
| Exelon Corporation |
| OKG Aktiebolag |
| Bloom Energy |
| Others |
Value Network & Pricing Analysis
Utility procurement consolidation across European power markets anchors pricing power with consolidated buyers who negotiate long-term offtake agreements with fixed-price escalators. Contract standardization for electrolyzer packages compresses supplier margins while premium terms persist for specialized nuclear-to-hydrogen engineering capabilities.
Pricing Analysis
High-volume industrial offtake commands standardized pricing with compressed margins, while specialized thermochemical deployments retain premium positioning. Pricing stratifies across premium, standard, and economy tiers based on purity certification grade and integration complexity with nuclear steam supply systems. Cost compression in alkaline electrolyzer packages intensifies as manufacturing scale accumulates in German production clusters. Steel producers and ammonia synthesizers exhibit lowest price sensitivity due to carbon border adjustment compliance requirements, while emerging fuel cell fleet operators negotiate hardest on unit economics.
Supply Chain Analysis
France's national energy regulator frameworks and Sweden's radiation safety authority mandates reshape sourcing patterns toward domestic-content-qualified reactor-hydrogen integration specialists. Electrolyzer stack manufacturing draws from German and Danish production clusters, with iridium catalyst coatings and solid oxide ceramic substrates as critical imported inputs. Single-source vulnerability concentrates in high-purity water pretreatment systems where nuclear cooling requirements compete with electrolyzer feedstock needs. Distribution runs through dedicated pipeline infrastructure in nuclear-adjacent industrial corridors, with tube trailer and cylinder supply serving pilot-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pink hydrogen market sits in a technology-transition phase where solid oxide electrolyzer efficiency gains displace legacy alkaline systems in baseload-integrated deployments. This shift restructures competitive economics toward reactor-coupled configurations.
For Market Incumbents: Lock in long-term offtake agreements with utility buyers before electrolyzer manufacturing commoditization accelerates. Anchor supply security through backward integration into high-purity water pretreatment capabilities. Defend against emerging Scandinavian reactor operators by pre-certifying designs across French and Swedish regulatory jurisdictions simultaneously. For New Entrants and Emerging Players: Port authorities in Rotterdam and Antwerp represent the most penetrable channel partner type for aggregating dispersed industrial demand into anchor contracts. Target Belgian steel producers in the ARA region seeking dedicated pipeline supply with customization premiums beyond standardized utility terms. Pursue regulatory fast-track certification under EMA industrial emissions guidelines to compress permitting cycles against established competitors. For Investors and Strategic Acquirers: The window for entry favors electrolyzer original equipment manufacturers with solid oxide technology pipelines and existing nuclear utility relationships. Long-term viability hinges on reactor relicensing decisions and carbon border adjustment mechanism enforcement trajectories. Watch French reactor fleet expansion commitments as the critical inflection signal for production corridor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | 15-year take-or-pay contracts with EDF-backed producers secure baseload hydrogen supply for ARA steel producers. |
| Technology Licensing | Solid oxide electrolyzer efficiency gains below 40 kWh per kilogram unlock project economics for industrial-scale deployments. |
| Joint Venture | Reactor-hydrogen facility integration partnerships with Forsmark and Ringhals operators accelerate Swedish corridor development. |
| Backward Integration | Captive high-purity water pretreatment capacity mitigates site selection constraints and cooling competition risks. |
| Green Certification Program | EU Green Deal carbon accounting protocols certify nuclear-derived hydrogen for compliance with tightening border adjustments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, electrolyzer manufacturing executives, nuclear facility project developers, and industrial hydrogen procurement leads combined with EDF reactor relicensing disclosures, EU ETS carbon price databases, and national energy regulator frameworks. Bottom-up electrolyzer deployment tracking and top-down industrial feedstock demand modeling provided triangulation across data sources.
Granularity-level modeling addressed production technology, application category, and end-user archetype dimensions across the projection horizon. Solid oxide versus alkaline electrolyzer efficiency curves, thermochemical sulfur-iodine cycle deployment rates, and reactor-to-hydrogen facility integration timelines served as industry-specific forecast inputs. CAGRs derived from capacity buildout pipelines and offtake contract signing velocity.
Caveats apply where nuclear fleet relicensing delays, F-Gas Regulation cooling system redesigns, or carbon border adjustment mechanism scope expansions could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Green Chemical and Material Market