
 Natural L-Lactic Acid Market | 2026-2036
Natural L-Lactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Natural L-Lactic Acid Market Foresight
China is narrowing the cost gap in natural L-lactic acid fermentation capacity through integrated corn-processing corridors in Henan and Anhui provinces. Corbion NV leverages backward integration into sugar feedstocks to sustain margin stability across pharmaceutical-grade output. NatureWorks LLC anchors North American supply for polymer-grade material destined for polylactic acid resin production. Henan Jindan Lactic Acid Technology Co., Ltd dominates captive starch fermentation, controlling raw material flows from provincial corn belts.
Natural L-lactic acid is the levorotatory enantiomer of 2-hydroxypropanoic acid, typically produced via bacterial fermentation of carbohydrate feedstocks at optical purities exceeding 99.5 percent, serving as a chiral building block for biodegradable polymers, food acidulants, and active pharmaceutical ingredients. Food-grade material occupies the largest volume share as processors replace synthetic preservatives in clean-label formulations, while pharmaceutical-grade commands the deepest margin pools due to USP and EP certification requirements for parenteral applications. Biodegradable plastics represent the fastest-expanding application channel as polylactic acid resin producers scale polymerization reactors to serve packaging and textile fiber markets.
FDA food additive regulations and EPA bio-preferred procurement standards shape US market access pathways, while REACH registration and EU Green Deal bioeconomy targets redirect European chemical manufacturers toward fermentation-derived inputs. China's NMPA pharmaceutical excipient standards and GB food safety codes govern import specifications for foreign suppliers seeking access to domestic formulation houses. Stakeholders must monitor feedstock cost volatility, certification timelines for pharmaceutical-grade qualification, and polymerization capacity announcements to align capacity investments with downstream offtake commitments.
Market Dynamics
Biodegradable plastics mandates are compressing polymer-grade lactic acid supply chains, forcing fermentation capacity expansions to synchronize with polylactic acid reactor commissioning timelines across packaging converters.
Growth Catalysts
- EU Green Deal packaging targets:REACH-registered fermentation-derived lactic acid qualifies as bio-based feedstock under single-use plastics directives, redirecting European converters from petrochemical inputs.
- Pharmaceutical-grade certification pipelines:USP and EP excipient standards for parenteral applications create captive demand pools with multi-year offtake contracts and limited supplier qualification.
- Corn-processing corridor density:Integrated starch-to-acid facilities in Henan and Anhui provinces compress logistics costs and raw material procurement cycles for domestic chemical manufacturers.
Market Restraints
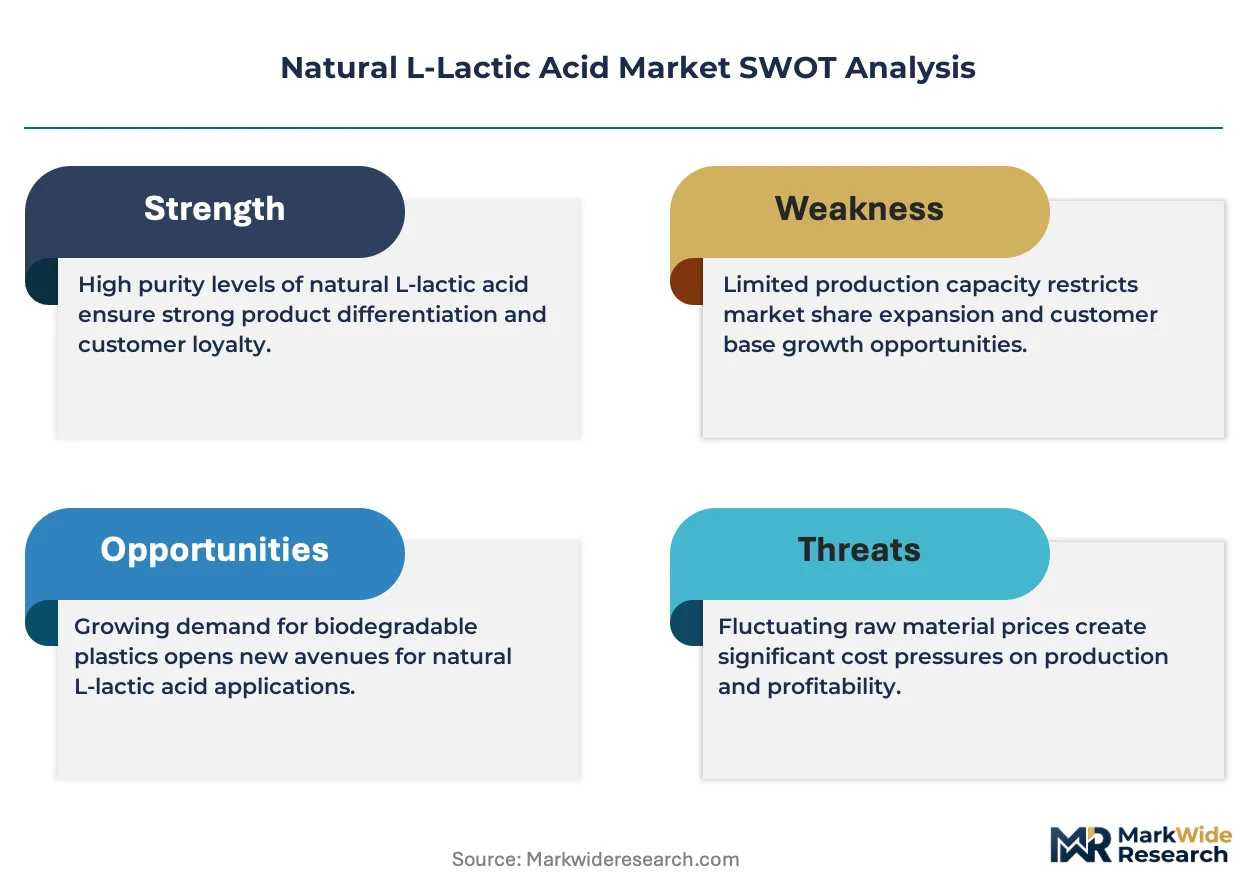
- Feedstock cost volatility:Corn starch and sugarcane molasses prices fluctuate with agricultural commodity cycles, compressing fermentation margins during harvest disruptions or trade policy shifts.
- Optical purity technical ceiling:Bacterial fermentation strains plateau near 99.5 percent enantiomeric excess, requiring costly crystallization steps for pharmaceutical-grade material.
- Polylactic acid substitution threat:Polyhydroxyalkanoates and starch-based blends compete in flexible packaging applications with comparable biodegradability profiles and lower processing temperatures.
Strategic Opportunities
- Cellulosic feedstock conversion:Lignocellulosic biomass hydrolysis is hybridizing with traditional carbohydrate fermentation, enabling agricultural residue utilization outside food-competing starch streams.
- Japan pharmaceutical excipient market:PMDA certification requirements for injectable formulations create underserved demand for GMP-grade natural L-lactic acid with documented supply chain traceability.
- Direct-to-polymer integration:Lactic acid producers are constructing on-site lactide and polylactic acid polymerization units, capturing margin pools previously retained by resin manufacturers.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous USP, EP, and NMPA qualification processes require 18-36 month documentation cycles with divergent analytical method validations.
- Specialized fermentation engineering talent:Industrial microbiology and downstream purification expertise concentrates in regional biotechnology clusters, constraining facility commissioning schedules.
- Polymerization reactor synchronization:Lactic acid capacity additions must align with polylactic acid resin plant startups to avoid intermediate inventory accumulation or offtake contract penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural L-Lactic Acid Market |
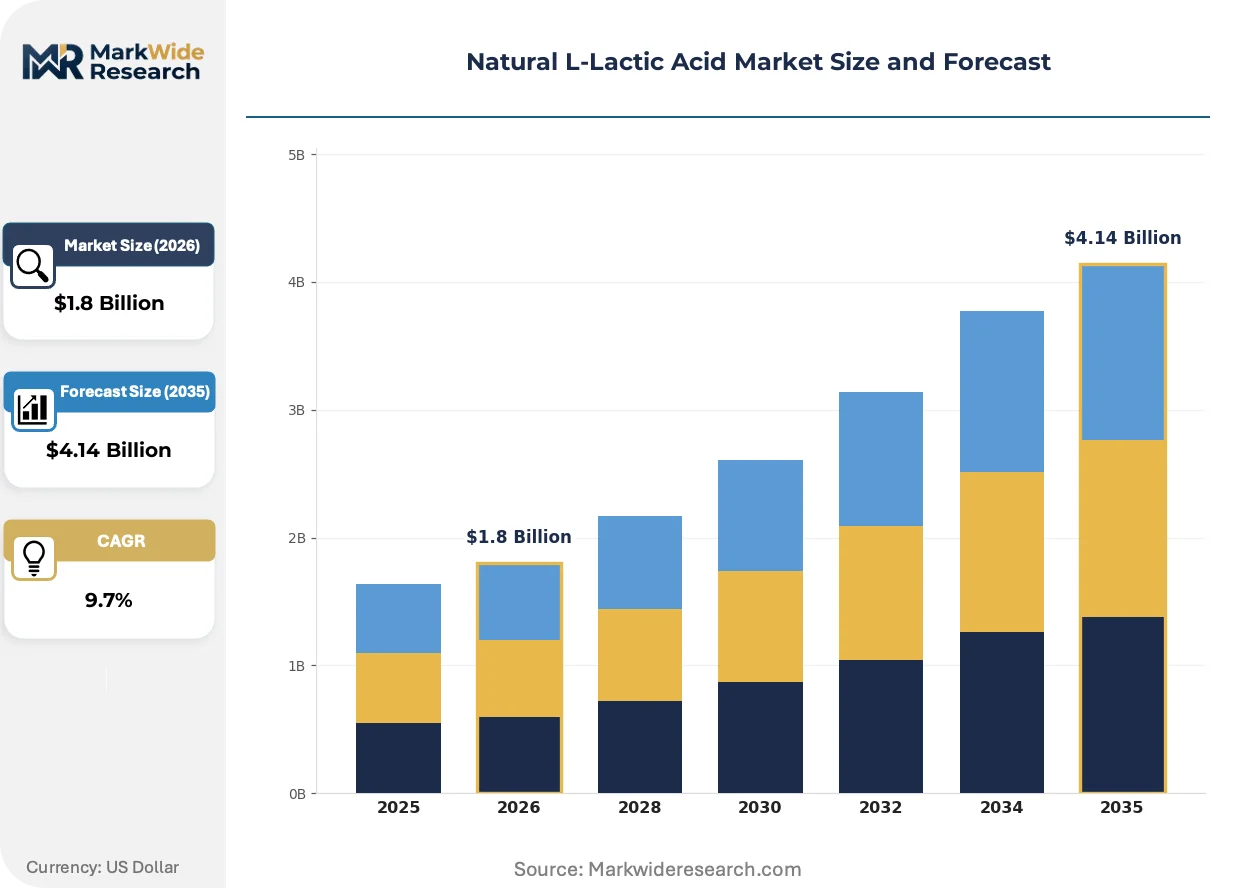
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Cosmetic Grade, Pharmaceutical Grade Application: Food Preservation, Biodegradable Plastics, Cosmetics, Pharmaceuticals End User: Food & Beverage Industry, Healthcare Providers, Personal Care Manufacturers, Chemical Manufacturers Packaging Type: Drums, Bags, Totes, Canisters |
| Companies Covered | Corbion NV, NatureWorks LLC, Galactic S.A., Cargill Incorporated, Jungbunzlauer Suisse AG, Henan Jindan Lactic Acid Technology Co., Ltd, BASF SE, Anhui BBCA Biochemical, Cellulac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural L-Lactic Acid Market Shifts & Advancements
Continuous processing architectures and synthetic biology tools are compressing batch fermentation cycles while elevating optical purity thresholds, redefining capital efficiency benchmarks across pharmaceutical and polymer-grade production tiers.
Cell-free enzymatic conversion systems are hybridizing with traditional bacterial fermentation, enabling direct carbohydrate-to-acid pathways without biomass cultivation overhead. Biodegradable plastics manufacturers in packaging and textile fiber verticals are piloting these systems at 10,000-liter scales. The technology is hybridizing unit operations, collapsing upstream seed train and fermentation into single-reactor configurations with 40 percent footprint reduction.
REACH registration dossiers for polymer-grade lactic acid now require comprehensive substance identity profiles covering oligomer content and residual protein thresholds. ECHA substance evaluation workflows have extended approval timelines for new fermentation facility entrants by 8-14 months. European chemical distributors are consolidating qualified supplier lists to pre-registered manufacturers with completed toxicological endpoint studies.
Formulation houses are unbundling acidulant procurement from traditional chemical distributor networks, establishing direct fermentation partnerships with documented carbon footprint certifications. Food processors in clean-label segments are replacing citric and synthetic lactic acid with fermentation-derived natural L-lactic acid validated under ISO 14064 greenhouse gas accounting protocols. This pattern concentrates in North American and European markets where retailer sustainability scorecards penalize petrochemical-derived acidulants.
Natural L-Lactic Acid Market Segmentation
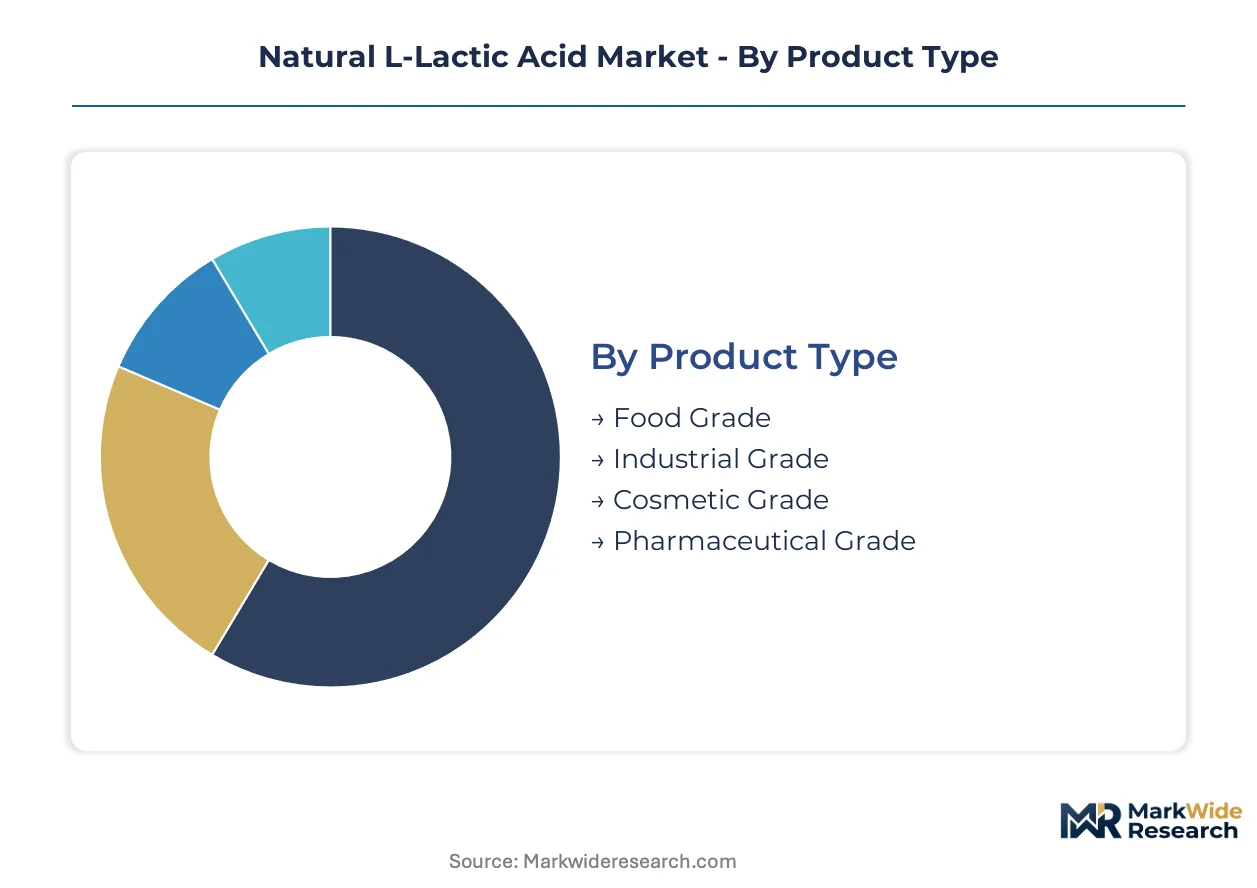
Natural L-lactic acid segmentation reflects divergent purity thresholds, certification requirements, and polymerization readiness across end-use verticals. Grade differentiation determines fermentation strain selection, downstream purification intensity, and margin capture potential.
Product Type:
Cost tier stratification separates commodity acidulants from high-purity pharmaceutical feedstocks with 10-20x price multiples.
- Food Grade:Minimum 80% purity with FDA food additive compliance for acidulant and preservative functions. Clean-label processors in US and European retail chains are displacing synthetic alternatives, though margin compression limits supplier differentiation.
- Pharmaceutical Grade:USP and EP-certified material exceeding 99.5% optical purity with documented endotoxin and heavy metal thresholds. Parenteral formulation houses in Germany and Switzerland lock in multi-year offtake contracts, creating captive demand pools with limited supplier rotation.
- Industrial Grade:Intermediate purity for chemical synthesis and metal treatment applications.
- Cosmetic Grade:Refined for pH adjustment and antimicrobial functions in personal care formulations.
Pharmaceutical Grade holds installed capacity. Food Grade is rotating up the share rankings.
Application:
Application concentration tracks regulatory mandates on single-use plastics and clean-label food formulations across major economies.
- Biodegradable Plastics:Polymer-grade lactic acid serves as feedstock for polylactic acid resin production in packaging and textile fiber markets. EU Green Deal packaging targets and China's dual carbon goals are synchronizing fermentation capacity expansions with polymerization reactor commissioning timelines.
- Food Preservation:Acidulant functions in processed meat, dairy, and beverage applications with synthetic preservative displacement. North American and European processors validate carbon footprint under ISO 14064 protocols to meet retailer sustainability scorecards.
- Cosmetics:pH buffering and gentle exfoliant functions in skincare and haircare formulations.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications requiring multi-jurisdiction certification.
Biodegradable Plastics claims the steepest expansion trajectory. Food Preservation defends volume leadership.
End User:
Customer type determines procurement modality, with chemical manufacturers pursuing backward integration while food processors unbundle from distributor networks.
- Chemical Manufacturers:Polymer-grade offtake for captive polylactic acid resin production. Henan and Anhui province corridors in China compress logistics costs through integrated starch-to-acid facilities serving domestic converters.
- Food & Beverage Industry:Direct fermentation partnerships replacing traditional chemical distributor relationships. Formulation houses demand documented carbon footprint certifications and supply chain traceability.
- Healthcare Providers:Pharmaceutical-grade procurement for parenteral and oral dosage formulations.
- Personal Care Manufacturers:Cosmetic-grade sourcing for pH adjustment and preservation functions.
Chemical Manufacturers anchor polymer-grade capacity. Food & Beverage Industry is deepening direct supplier relationships.
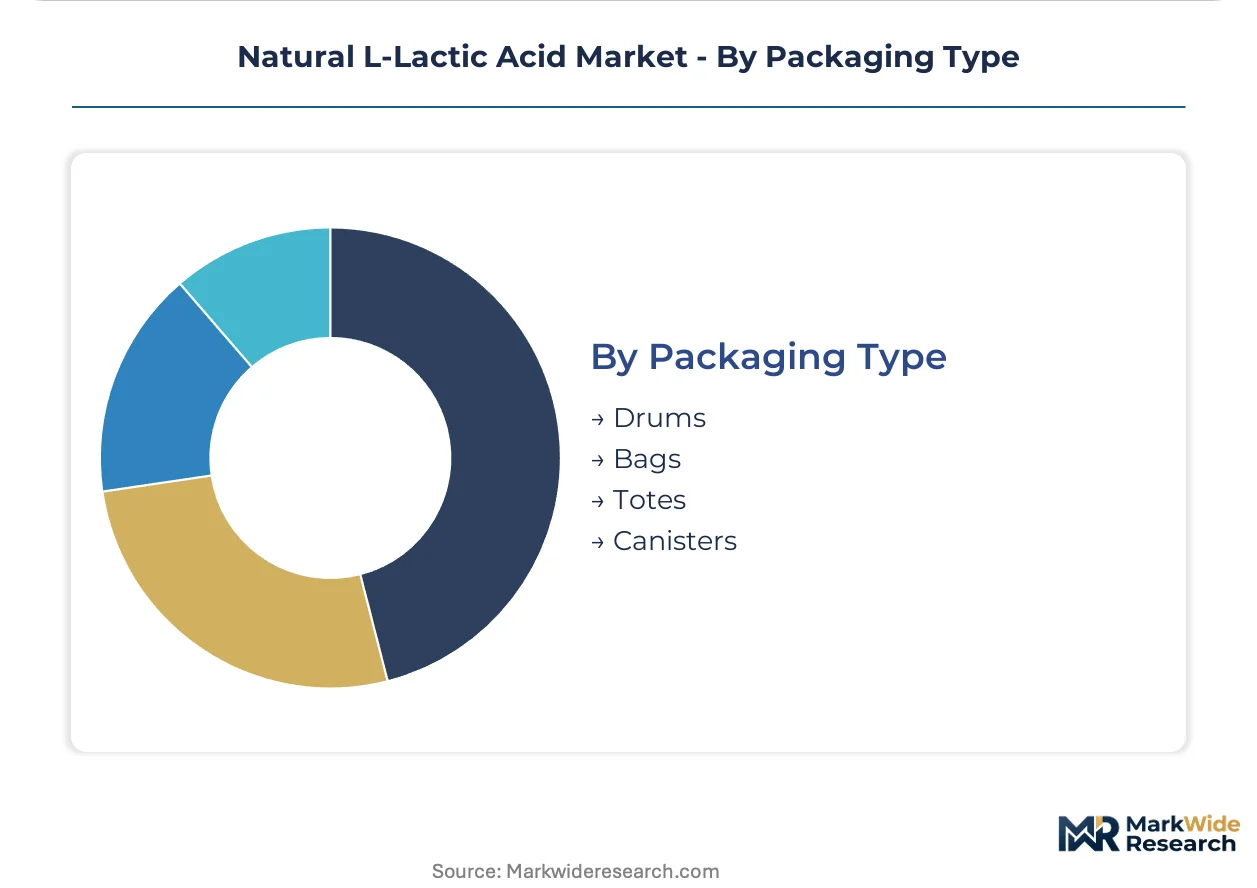
Packaging Type:
Packaging configuration aligns with volume scale, handling automation, and contamination risk thresholds across grade tiers.
- Drums:Standard 200-liter steel or plastic containers for industrial and food-grade bulk distribution. Chemical manufacturers in European polymer supply chains prefer drum formats for intermediate handling before on-site lactide conversion.
- Totes:Intermediate bulk containers for pharmaceutical and cosmetic grade material with reduced handling points. GMP facilities in Japan and Switzerland specify tote formats with sealed liner systems to maintain USP and PMDA compliance.
- Bags:Multi-layer polymer bags for powdered or granular acid variants.
- Canisters:Sealed metal containers for high-purity pharmaceutical and food-grade material.
Drums retain logistics infrastructure dominance. Totes are gaining share in pharmaceutical-grade channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA pharmaceutical excipient standards and GB food safety codes govern import specifications for foreign suppliers accessing Chinese formulation houses. The report examines five countries where fermentation capacity, regulatory frameworks, and polymer-grade demand concentrate.
China
Henan and Anhui provinces host integrated corn-processing corridors serving domestic chemical manufacturers. Dual carbon goals under MEE directives synchronize fermentation expansions with polylactic acid reactor commissioning. Henan Jindan and Anhui BBCA Biochemical operate captive starch fermentation facilities controlling raw material flows from provincial corn belts.
United States
FDA food additive regulations and EPA bio-preferred procurement standards shape market access for fermentation-derived acidulants. NatureWorks LLC anchors North American polymer-grade supply for polylactic acid resin production. Clean-label processors in retail chains validate carbon footprint under ISO 14064 protocols to meet sustainability scorecards.
Germany
REACH-registered fermentation-derived lactic acid qualifies as bio-based feedstock under EU Green Deal packaging targets. ECHA substance evaluation workflows extend approval timelines for new facility entrants. Parenteral formulation houses in Germany and Switzerland lock in multi-year offtake contracts for USP and EP-certified material.
Japan
PMDA certification requirements for injectable formulations create underserved demand for GMP-grade natural L-lactic acid. METI industrial biotechnology programs support cellulosic feedstock conversion pilots. GMP facilities specify tote formats with sealed liner systems to maintain USP and PMDA compliance.
Switzerland
Swissmedic pharmaceutical standards and documented supply chain traceability requirements attract premium-tier excipient procurement. Jungbunzlauer Suisse AG leverages geographic proximity to German and French formulation clusters. Multi-jurisdiction USP, EP, and PMDA qualification processes concentrate expertise in regional biotechnology hubs.
Natural L-Lactic Acid Market Competitive Landscape
Capability concentration sits with pharmaceutical-grade specialists; scale advantage sits with integrated fermentation operators. The vendor base stratifies across three tiers: captives with backward integration into feedstocks, merchant suppliers serving distributor networks, and technology licensors enabling third-party capacity. Strategic moves center on direct-to-polymer integration and cellulosic feedstock conversion partnerships.
Among European-headquartered suppliers, Corbion NV and Galactic S.A. exemplify the merchant-grade tier with REACH-registered dossiers and established toxicological endpoint studies. Henan Jindan Lactic Acid Technology Co., Ltd represents the captive-integrated archetype with provincial corn belt control. These three anchors demonstrate how geographic feedstock access and certification breadth define competitive positioning.
| Leading Market Players |
|---|
| Corbion NV |
| NatureWorks LLC |
| Galactic S.A. |
| Cargill Incorporated |
| Jungbunzlauer Suisse AG |
| Henan Jindan Lactic Acid Technology Co., Ltd |
| BASF SE |
| Anhui BBCA Biochemical |
| Cellulac |
| Others |
Supply & Pricing Matrix
Undercapacity in pharmaceutical-grade fermentation facilities across Germany and Switzerland compresses supplier leverage while forcing buyers into multi-year offtake commitments. This utilization squeeze simultaneously elevates premium-tier pricing power and accelerates backward integration investments by polymer-grade purchasers seeking supply security.
Pricing Analysis
Price spreads between Henan province commodity output and Swiss pharmaceutical-grade material exceed tenfold multiples. Three-tier pricing structure across pharmaceutical, food, and industrial grades tracks certification burden and optical purity thresholds. Pricing pressure stems from corn starch volatility in Anhui and Henan corridors, compressing fermentation margins during harvest disruptions. Chemical manufacturers show lowest price sensitivity due to captive polylactic acid integration, while food processors negotiate aggressively on carbon footprint documentation costs.
Supply Chain Analysis
Tariff exposure between US and Chinese bioprocessing equipment suppliers dominates capital expenditure risk for new fermentation entrants. Supply concentrates in China, the United States, and Germany, with Henan and Anhui provinces anchoring starch-to-acid integration. Raw material flows draw from provincial corn belts, sugarcane molasses streams, and emerging lignocellulosic residue pilots. Single-source vulnerability sits with bacterial strain IP controlled by legacy biotechnology licensors. Distribution runs through chemical distributor networks for food-grade material, while pharmaceutical-grade ships direct to formulation houses under GMP protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyhydroxyalkanoates and starch-based blends threaten polylactic acid offtake in flexible packaging applications, forcing incumbent lactic acid producers to defend polymer-grade positioning through certification lock-in and direct resin integration.
For Market Incumbents: Harden pharmaceutical-grade certification moats by accelerating USP, EP, and PMDA qualification pipelines ahead of fermentation capacity expansions. Secure captive starch supply through provincial corn belt partnerships in Henan and Anhui, neutralizing feedstock volatility that erodes commodity-tier margins. Prioritize on-site lactide polymerization units to capture margin pools previously retained by NatureWorks and domestic Chinese resin manufacturers. For New Entrants and Emerging Players: Pursue cellulosic feedstock conversion partnerships with agricultural residue processors outside food-competing starch streams. Japan's PMDA-certified injectable excipient market offers penetrable white space given documented supply chain traceability requirements. Lead with GMP-grade positioning and sealed liner tote formats to differentiate from established drum-distribution incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a bioeconomy infrastructure play because EU Green Deal packaging mandates and China's dual carbon goals structurally expand polymer-grade demand across the analysis window. Target acquisition candidates with completed REACH dossiers and established toxicological endpoint studies, bypassing ECHA's extended approval timelines. Watch polylactic acid reactor commissioning announcements as the inflection signal for lactic acid capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstocks | Henan Jindan's provincial corn belt control eliminates raw material procurement cycles for domestic chemical manufacturers. |
| Pharmaceutical-Grade Certification Investment | USP and EP qualification pipelines lock in multi-year offtake contracts with German and Swiss parenteral formulation houses. |
| Direct-to-Polymer Integration | On-site lactide conversion captures margin pools previously retained by NatureWorks and Chinese resin manufacturers. |
| Cellulosic Feedstock Conversion Partnership | Lignocellulosic biomass hydrolysis enables agricultural residue utilization outside food-competing starch streams. |
| Long-term Supply Agreement with Packaging Converters | EU Green Deal bioeconomy targets redirect European chemical manufacturers toward fermentation-derived feedstock commitments. |
Research Methodology
A standing panel of fermentation plant managers, pharmaceutical procurement leads at German formulation houses, polylactic acid resin technical directors, and REACH regulatory consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA substance evaluation workflows, NMPA pharmaceutical excipient filings, EPA bio-preferred procurement standards, and SEC disclosures by listed biotechnology operators. Bottom-up capacity assessments across Henan and Anhui provinces triangulated against top-down polymer-grade demand projections from packaging converter announcements.
Scenario-bracketing framed optimistic, baseline, and constrained trajectories across the projection horizon without specifying discrete year markers. Segmentation dimensions modeled included grade tier, end-use application, packaging format, and regional production hub. CAGRs derived from capacity commissioning timelines synchronized with polylactic acid reactor startups, feedstock cost volatility assumptions, and certification pipeline completion rates. Industry-specific inputs incorporated bacterial strain productivity curves, crystallization step yields, and ECHA approval workflow durations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cell-free enzymatic conversion technology developers would shift outcomes beyond modeled boundaries. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Butyraldehyde Market