
 Global Bio-Renewable Chemicals Market | 2026-2036
Global Bio-Renewable Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio-Renewable Chemicals Market Foresight
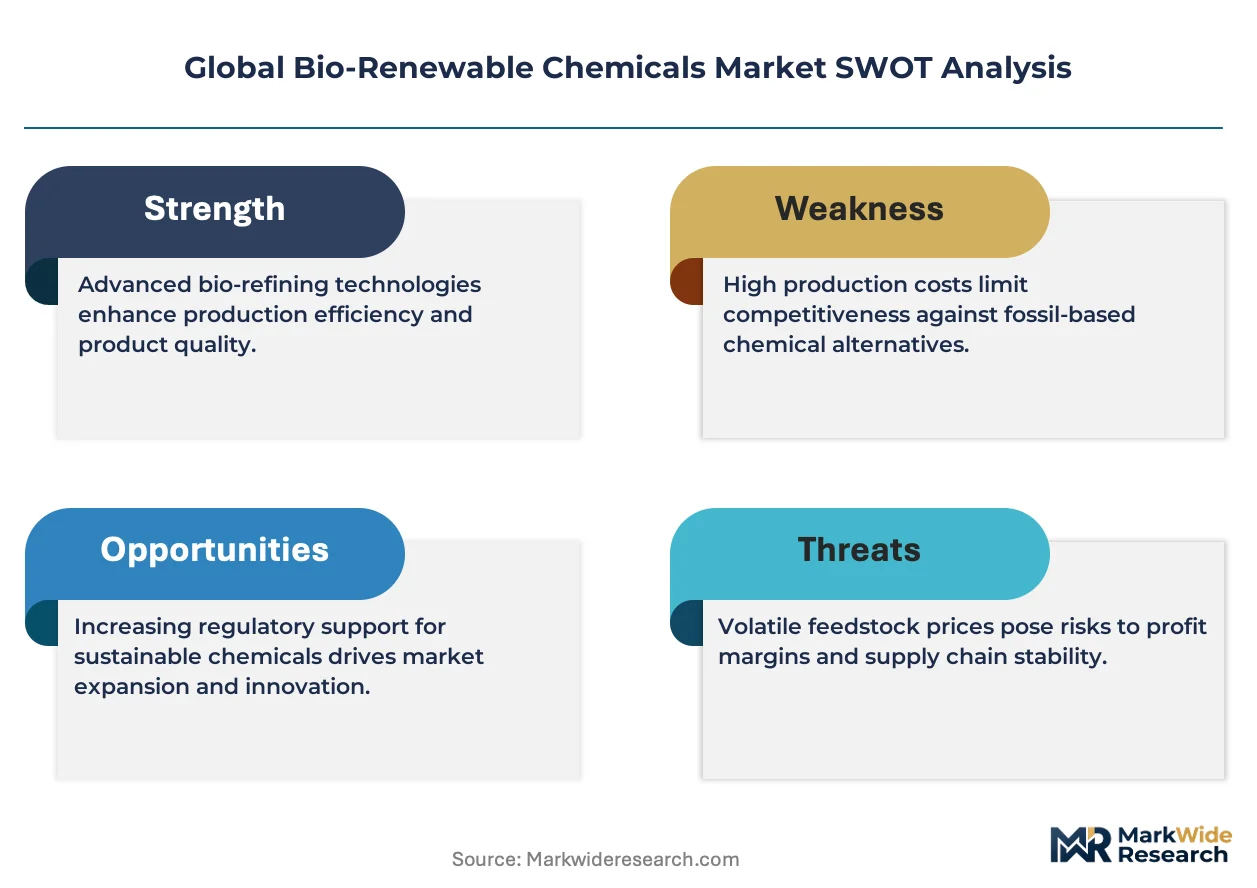
Performance-based offtake contracts and embedded carbon-accounting software is realigning how bio-renewable chemicals are priced and sold. BASF SE leverages its Verbund site network to sustain integrated fermentation and catalytic conversion capacity at scale. Cargill anchors North American feedstock supply through its corn-processing infrastructure and oilseed crush assets. Braskem dominates bio-polyethylene output from its I'm greenTM production platform in Brazil.
Bio-renewable chemicals comprise organic compounds and polymers synthesized from biomass feedstocks such as sugars, lignocellulosic residues, and plant oils rather than fossil hydrocarbons, with fermentation routes typically operating at 30-50°C and pH 4.0-7.0 to achieve selective conversion of glucose to target molecules like bio-butanol or lactic acid. These materials serve as drop-in or differentiated replacements for conventional petrochemicals across packaging films, textile fibers, agricultural formulations, and construction adhesives. Bio-polyethylene and polylactic acid occupy the largest volume positions, reflecting mature fermentation infrastructure and brand-led demand for recyclable packaging. Bio-butanol and bio-phenol represent faster-growing niches, where catalytic conversion and enzymatic synthesis are improving yield economics and expanding addressable solvent and resin markets.
The EPA Renewable Fuel Standard, EU Green Deal packaging regulations, and Brazil's RenovaBio program collectively mandate blending thresholds, carbon-intensity reductions, and sustainable sourcing criteria that shape product specifications and market access for bio-renewable chemical producers. REACH registration requirements and California LCFS carbon-accounting rules further differentiate certified low-carbon products from uncertified alternatives. Stakeholders must monitor feedstock cost volatility, policy durability across electoral cycles, and the pace at which enzymatic synthesis achieves cost parity with catalytic conversion for C5-C6 platform chemicals.
Market Dynamics
Fermentation-based production platforms are compressing capital requirements for C3-C6 building blocks while EU Green Deal packaging mandates force brand owners to reconfigure polymer sourcing contracts around certified low-carbon feedstocks.
Growth Catalysts
- EU Green Deal packaging mandates:Binding recycled-content thresholds for single-use plastics are pulling bio-polyethylene and polylactic acid into European flexible packaging supply chains.
- Brazilian ethanol infrastructure:Existing sugarcane mills and fermentation vessels provide distributed feedstock access that undercuts petrochemical cracking economics for bio-ethylene production.
- Performance-based offtake structures:Carbon-accounting software embedded in procurement contracts is enabling premium pricing for certified low-carbon chemicals against conventional alternatives.
Market Restraints
- Lignocellulosic feedstock volatility:Agricultural residue prices swing with weather patterns and competing uses, compressing margin predictability for second-generation fermentation operators.
- Enzyme supply concentration:Industrial cellulase production clusters in Denmark and the Netherlands, creating single-source vulnerability for biomass pretreatment stages.
- REACH registration timelines:Novel bio-based molecules face multi-year toxicity testing requirements that delay commercial deployment in European coatings and adhesives markets.
Strategic Opportunities
- India's PLI scheme for bio-manufacturing:Production-linked incentives for fermentation-based chemicals are attracting capacity investments targeting domestic agrochemical and textile intermediate demand.
- Construction adhesive applications:Bio-phenol and bio-epoxy resins are penetrating structural bonding markets as LEED v4.1 credits reward embodied carbon reductions in building materials.
- Digital molecule marketplaces:Blockchain-verified carbon accounting is enabling direct contracting between biomass processors and brand owners, bypassing traditional distributor markups.
Industry Challenges
- Metabolic engineering talent scarcity:Strain optimization for non-model organisms requires specialized synthetic biology expertise concentrated in academic and startup ecosystems.
- Downstream purification capex:Crystallization and membrane separation systems for lactic acid and succinic acid represent 40-50% of facility investment, straining project finance structures.
- ASTM certification delays:Drop-in bio-polyethylene must complete extensive pipeline compatibility testing before oil and gas sector offtake, extending commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio-Renewable Chemicals Market |
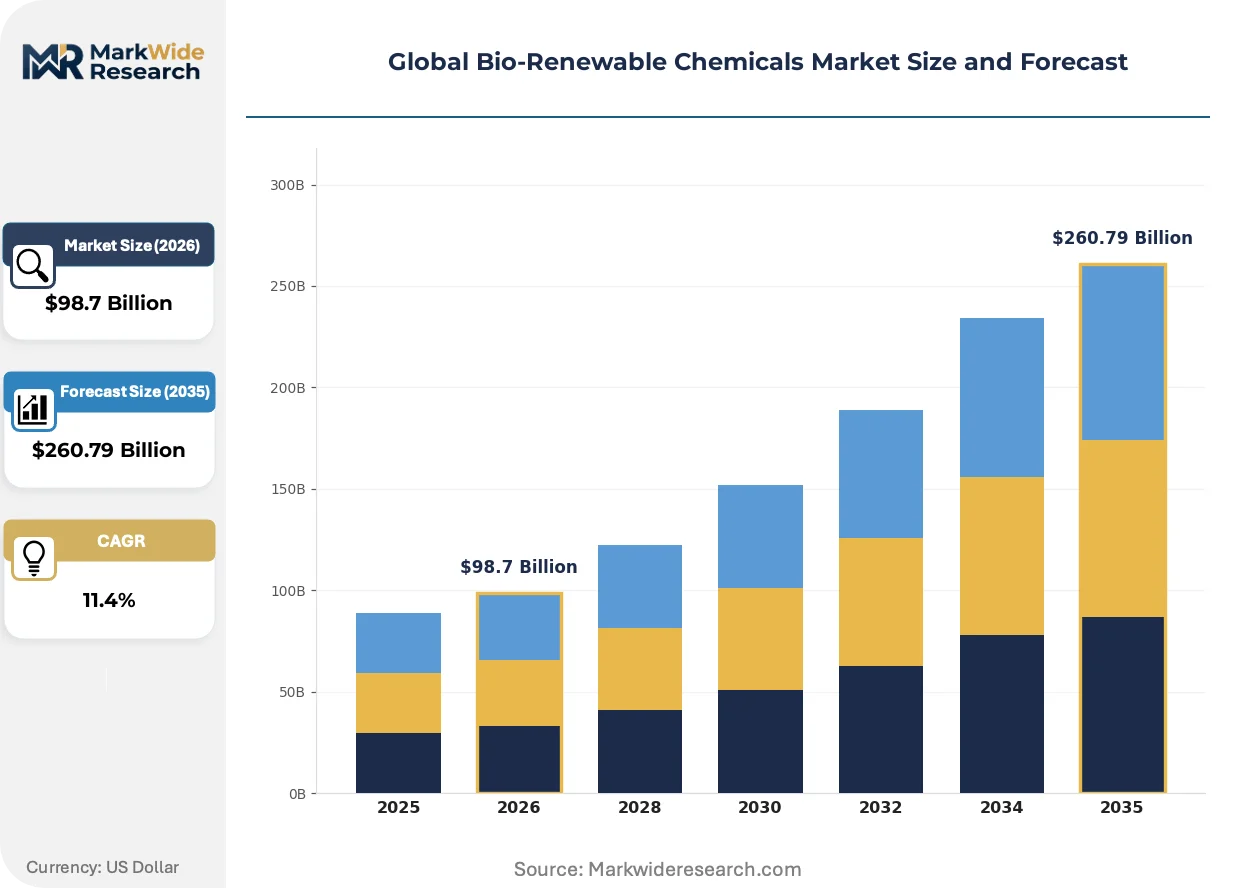
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-Polyethylene, Bio-Polypropylene, Polylactic Acid, Bio-Butanol, Bio-Ethanol, Bio-Phenol Production Technology: Fermentation, Catalytic Conversion, Enzymatic Synthesis, Hydrolysis, Gasification, Pyrolysis End Use Sector: Packaging, Textiles, Agriculture, Adhesives, Personal Care, Construction Distribution Channel: Direct Sales, Online Platforms, Wholesalers, Distributors, Retail Outlets, Exporters |
| Companies Covered | Archer-Daniels-Midland Company (ADM), BASF SE, Amyris Inc., Cargill, Braskem, Solvay, DuPont de Nemours, Gevo, ZeaChem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio-Renewable Chemicals Market Shifts & Advancements
Electrification of thermal process units and enzymatic synthesis convergence are reconfiguring process economics while carbon-accounting standards harden procurement specifications across packaging and construction verticals.
Consolidated bioprocessing technology is electrifying capital efficiency for lignocellulosic ethanol and derivative chemicals by combining enzyme production, biomass hydrolysis, and fermentation in single-reactor systems. Packaging converters in Germany and the Netherlands are piloting these platforms for local bio-ethylene supply. The technology is electrifying distributed production models that bypass centralized petrochemical complexes.
REACH registration requirements for bio-based novel substances are tightening data demands on chronic toxicity and environmental fate endpoints. ECHA's 2023 updated guidance on substance identification for UVCB substances is extending dossier preparation timelines. Specialty chemical formulators in Belgium and France are responding by prioritizing drop-in molecular structures over novel bio-based architectures to accelerate market access.
Brand-led carbon disclosure mandates are compressing supplier qualification cycles for bio-renewable chemicals. Unilever and Nestlé packaging procurement teams now require ISO 14067-compliant product carbon footprints before contract award, displacing traditional specification-based tendering. This pattern is most pronounced in German and Swiss consumer goods supply chains where CSRD reporting obligations cascade down to tier-two chemical suppliers.
Global Bio-Renewable Chemicals Market Segmentation
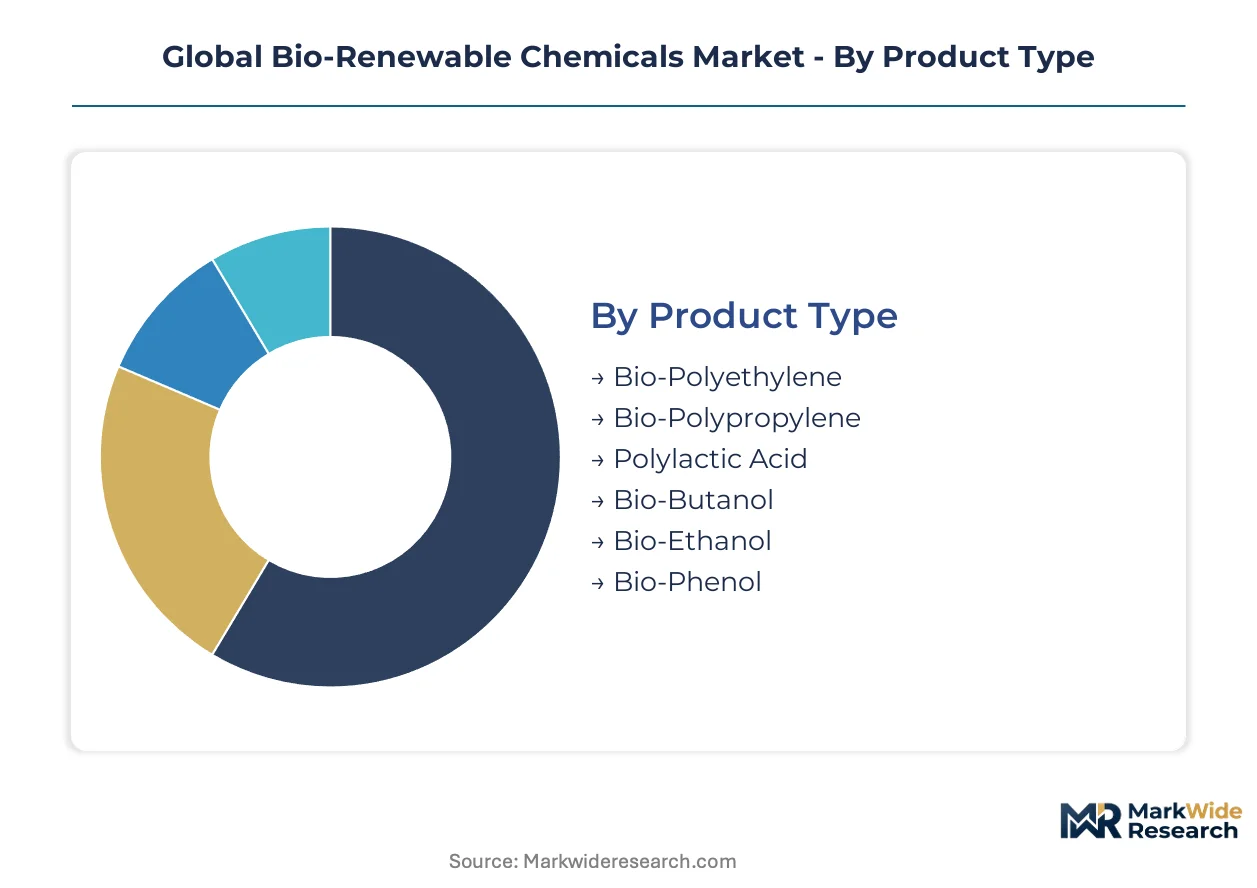
Segmentation in bio-renewable chemicals separates mature commodity polymers from emerging specialty molecules, each demanding distinct fermentation infrastructure, carbon-accounting protocols, and offtake contracting structures. Understanding these divisions reveals where capital efficiency concentrates and where technology premiums command pricing power.
Product Type:
Integration depth varies sharply across product categories, with drop-in polymers slotting directly into existing extrusion equipment while novel bio-based molecules require reformulated processing parameters and customer qualification cycles.
- Bio-Polyethylene:Drop-in replacement for fossil-based PE produced via bio-ethylene dehydration, identical in polymer properties and recyclable within existing waste streams. Demand clusters in German and Dutch flexible packaging supply chains where EU Green Deal recycled-content mandates force brand owners to reconfigure sourcing contracts around certified low-carbon feedstocks.
- Polylactic Acid:Aliphatic polyester derived from corn or sugarcane starch fermentation, offering compostability in industrial facilities but limited thermal stability versus conventional plastics. Textile fiber applications in Italy and Taiwan are expanding fastest as sportswear brands embed carbon-footprint disclosures into supplier scorecards.
- Bio-Polypropylene:Propylene oligomerization from bio-naphtha streams, still scaling commercially with limited capacity outside Braskem's Triunfo complex.
- Bio-Butanol:C4 alcohol fermentation platform gaining traction in solvent and coating applications where VOC regulations tighten.
- Bio-Ethanol:Mature fermentation product serving primarily fuel blending markets with chemical-grade purity upgrades capturing modest premium.
- Bio-Phenol:Lignin-derived aromatic compound penetrating epoxy resin formulations for construction adhesives qualifying under LEED v4.1 embodied carbon credits.
Volume placements concentrate in Bio-Polyethylene; the faster expansion belongs to Bio-Phenol.
Production Technology:
Cost tier stratification separates capital-intensive thermochemical platforms from fermentation systems that leverage distributed agricultural feedstock access.
- Fermentation:Biological conversion of sugars to target molecules operating at ambient temperature and pressure, achieving selective transformation through engineered microbial strains. Brazil's sugarcane mill network provides feedstock integration that undercuts petrochemical economics for bio-ethylene production.
- Catalytic Conversion:Chemical transformation of bio-intermediates using heterogeneous catalysts, enabling continuous processing and higher throughput versus batch fermentation. German chemical parks at Ludwigshafen and Antwerp host integrated facilities where Verbund site infrastructure shares utilities and hydrogen supply.
- Enzymatic Synthesis:Protein-catalyzed reactions achieving stereoselective transformations for pharmaceutical and agrochemical precursors, still scaling from pilot demonstrations.
- Hydrolysis:Acid or enzyme-mediated cleavage of polysaccharides to fermentable sugars, representing critical pretreatment stage for lignocellulosic feedstocks.
- Gasification:High-temperature partial oxidation of biomass to syngas, capital-intensive and concentrated at demonstration scale in Nordic forestry clusters.
- Pyrolysis:Thermal decomposition in oxygen-limited environments producing bio-oil and char fractions, marginally commercial for chemicals with primary output targeting fuel markets.
Capital deployment favors Fermentation; technology premiums attach most strongly to Enzymatic Synthesis.
End Use Sector:
Application maturity determines certification requirements, with packaging and textiles imposing the most stringent carbon-accounting verification while construction and agriculture tolerate longer qualification timelines.
- Packaging:Flexible films, rigid containers, and barrier coatings representing the largest volume outlet for bio-polyethylene and polylactic acid. Nestlé and Unilever procurement teams in Switzerland and Germany now mandate ISO 14067-compliant product carbon footprints before contract award.
- Textiles:Fiber and filament applications where polylactic acid competes with recycled polyester on sustainability credentials. Taiwanese and Italian yarn producers are expanding PLA spinning capacity to serve athletic apparel brands.
- Agriculture:Mulch films, controlled-release fertilizers, and crop protection formulations where biodegradability reduces field plastic accumulation.
- Adhesives:Structural and pressure-sensitive bonding applications where bio-phenol and bio-epoxy resins penetrate through LEED v4.1 embodied carbon reductions.
- Personal Care:Surfactants, emollients, and solvent applications in cosmetics where bio-ethanol and bio-butanol serve as renewable feedstocks.
- Construction:Insulation foams, sealants, and composite matrices where carbon-intensity metrics increasingly influence specification.
Contract volumes aggregate in Packaging; qualification velocity is quickest in Textiles.
Distribution Channel:
Customer scale and carbon-verification requirements reshape channel economics, with direct relationships dominating certified low-chemical procurement and intermediaries retaining relevance for commodity grades.
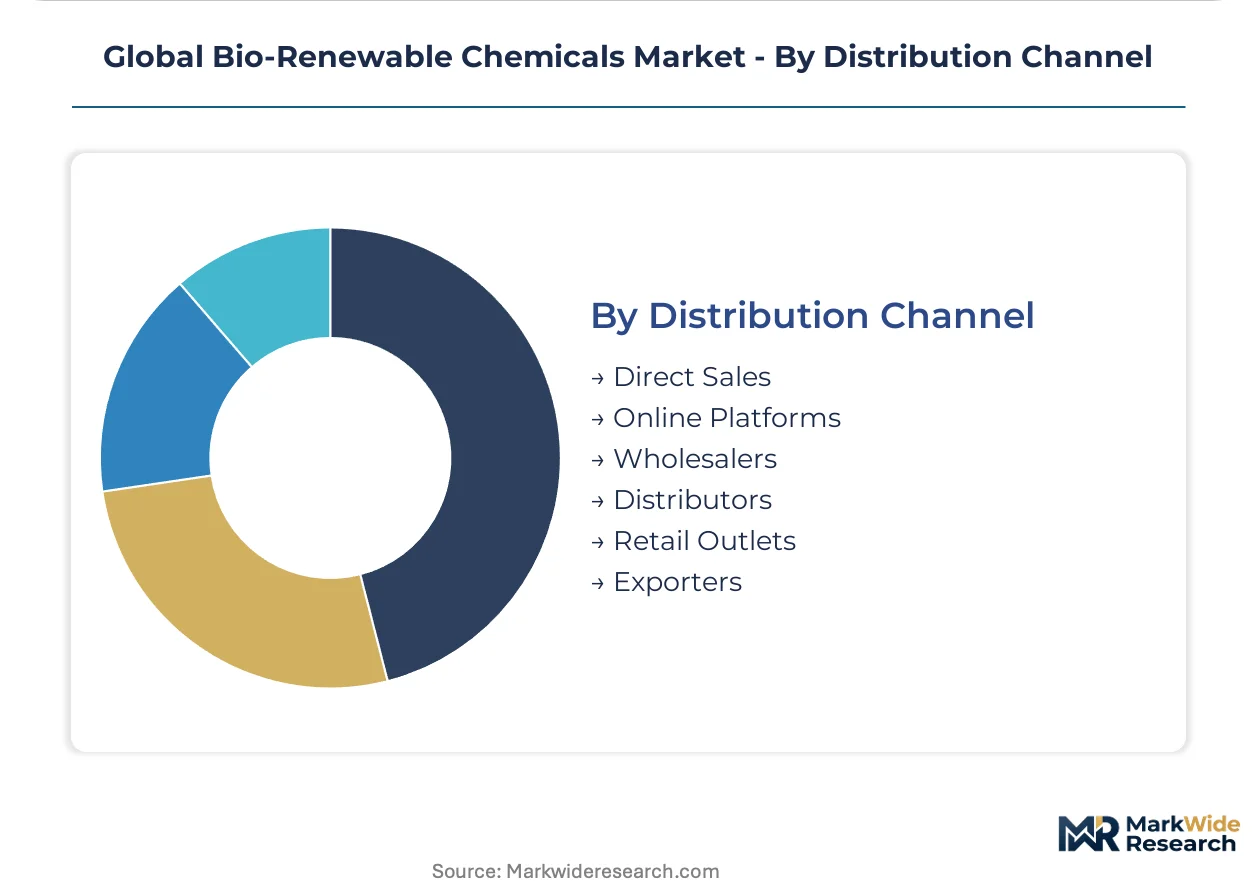
- Direct Sales:Long-term offtake agreements between producers and brand owners embedding carbon-accounting software and performance guarantees. BASF and Braskem leverage direct relationships with European packaging converters to secure volume commitments against EU Green Deal compliance deadlines.
- Distributors:Regional inventory and technical service networks serving mid-scale formulators lacking procurement scale for direct negotiation. Belgian and French specialty chemical distributors are building bio-based product portfolios to capture sustainability-driven specification shifts.
- Online Platforms:Digital marketplaces with blockchain-verified carbon accounting enabling direct contracting between biomass processors and brand owners.
- Wholesalers:Volume aggregation for commodity grades with limited differentiation, concentrated in bio-ethanol fuel blending markets.
- Retail Outlets:Limited relevance for industrial chemicals, emerging only in consumer-facing bio-based product segments.
- Exporters:Cross-border trade facilitation for producers seeking arbitrage between Brazilian feedstock costs and European premium pricing.
Transaction value concentrates in Direct Sales; channel expansion is steepest for Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen anchors European bio-renewable chemical production through integrated Verbund infrastructure that shares utilities and hydrogen supply across fermentation and catalytic conversion units.
Germany
Flexible packaging converters in North Rhine-Westphalia are reconfiguring polymer sourcing contracts around certified low-carbon feedstocks to meet EU Green Deal recycled-content thresholds. ECHA's REACH registration requirements for novel bio-based substances extend dossier preparation timelines for specialty chemical formulators. The Antwerp-Rotterdam-Rhine chemical corridor hosts BASF's integrated fermentation capacity serving brand owners with ISO 14067-compliant carbon footprints.
United States
Corn-processing infrastructure in the Midwest provides distributed feedstock access that undercuts petrochemical cracking economics for bio-ethylene production. EPA Renewable Fuel Standard mandates blend bio-ethanol into fuel markets while chemical-grade purity upgrades capture modest premiums. Cargill anchors North American supply through its oilseed crush assets and fermentation vessels concentrated in Minnesota and Iowa processing corridors.
Brazil
Sugarcane mills in São Paulo state provide existing fermentation vessel networks that displace petrochemical routes for C3-C6 building blocks. RenovaBio program mandates carbon-intensity reductions that shape product specifications for bio-polyethylene output. Braskem's Triunfo complex dominates bio-polyethylene production from its I'm greenTM platform serving European packaging procurement teams.
India
Production-linked incentives for fermentation-based chemicals under the PLI scheme are attracting capacity investments targeting domestic agrochemical and textile intermediate demand. BIS standards for bio-based materials create certification pathways for local formulators. Maharashtra and Gujarat host expanding fermentation infrastructure serving sportswear brands embedding carbon-footprint disclosures into supplier scorecards.
Netherlands
Packaging converters in Rotterdam and Amsterdam are piloting consolidated bioprocessing platforms for local bio-ethylene supply that bypass centralized petrochemical complexes. EU Green Deal packaging regulations force brand owners to reconfigure sourcing contracts around certified low-carbon feedstocks. DSM's biotechnology cluster in Delft-Leiden anchors enzymatic synthesis development for pharmaceutical and agrochemical precursors.
Global Bio-Renewable Chemicals Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology platforms that reshape competitive positioning. Integrated petrochemical majors leverage Verbund site infrastructure and captive feedstock supply to sustain fermentation and catalytic conversion capacity at scale. Specialized biotech firms concentrate metabolic engineering expertise and strain optimization capabilities for non-model organisms. Dominant competitive moves include backward integration into agricultural feedstock processing and strategic partnerships embedding carbon-accounting software into procurement contracts.
Among diversified chemical conglomerates, BASF SE and Solvay occupy positions exemplifying integrated production platforms that share utilities across fermentation and downstream conversion stages. Archer-Daniels-Midland Company (ADM) and Cargill represent agribusiness-origin archetypes anchoring feedstock supply through corn-processing infrastructure and oilseed crush assets. Braskem sits within the petrochemical-derivative tier as a Brazilian producer leveraging sugarcane ethanol infrastructure for bio-polyethylene output.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company (ADM) |
| BASF SE |
| Amyris Inc. |
| Cargill |
| Braskem |
| Solvay |
| DuPont de Nemours |
| Gevo |
| ZeaChem |
| Others |
Supply & Pricing Matrix
Sugarcane feedstock costs in São Paulo state cascade through bio-polyethylene pricing tiers, with Brazilian ethanol infrastructure compressing upstream input expenses while EU Green Deal compliance premiums attach at European flexible packaging offtake points.
Pricing Analysis
Carbon-intensity certification anchors value-based pricing tiers for bio-renewable chemicals, with ISO 14067-compliant product footprints commanding contract premiums against uncertified alternatives. Three-tier pricing structure across premium certified, standard industrial, and economy fuel-grade levels separates brand-led procurement from commodity spot markets. Cost compression in standard fermentation grades is intensifying because lignocellulosic feedstock volatility erodes margin predictability. Small-scale specialty formulators exhibit highest price sensitivity, while Nestlé and Unilever procurement teams absorb certification premiums to secure CSRD-compliant supply chains.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp anchor hub-and-spoke patterns for European bio-polyethylene delivery, bypassing traditional petrochemical complex dependencies. Supply concentrates in Brazil, Germany, and the United States, with São Paulo sugarcane mills, Ludwigshafen Verbund sites, and Midwest corn-processing corridors forming the backbone. Raw material flows draw from sugarcane starch, corn glucose, and lignocellulosic agricultural residues. Single-source vulnerability clusters in Danish and Dutch industrial cellulase production for biomass pretreatment. Distribution runs through direct long-term offtake agreements embedding carbon-accounting software, displacing traditional distributor markups for certified low-chemical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-based production platforms are displacing petrochemical routes for C3-C6 building blocks, compressing capital requirements and reconfiguring competitive positioning across packaging and construction verticals.
For Market Incumbents: Deploy backward integration into agricultural feedstock processing to secure margin control against lignocellulosic price volatility. BASF and Braskem demonstrate this through Verbund site networks and captive sugarcane ethanol supply. Incumbents must also embed carbon-accounting software into procurement contracts to defend pricing power as EU Green Deal mandates tighten supplier qualification cycles. For New Entrants and Emerging Players: Enter via India's PLI scheme for bio-manufacturing, where production-linked incentives attract capacity investments targeting domestic agrochemical and textile intermediate demand. Construction adhesive applications represent penetrable white space, with bio-phenol and bio-epoxy resins qualifying under LEED v4.1 embodied carbon credits. A direct-to-brand digital marketplace approach bypasses traditional distributor markups through blockchain-verified carbon accounting. For Investors and Strategic Acquirers: RenovaBio program carbon-intensity enforcement is the leading indicator that Brazilian bio-polyethylene capacity will command sustained European offtake premiums. Long-term viability frames around fermentation platform standardization and enzymatic synthesis scale-up over the next decade. Acquisition targets should concentrate on metabolic engineering startups with non-model organism strain optimization capabilities. Watch for REACH registration timeline acceleration as the signal for novel bio-based molecule commercialization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Cargill's corn-processing infrastructure anchors North American margin control against agricultural price swings. |
| Carbon-Accounting Software Embedding | Direct procurement contracts with Unilever and Nestlé secure premium pricing through ISO 14067 compliance verification. |
| Consolidated Bioprocessing Scale-Up | Single-reactor systems combining enzyme production and fermentation electrify capital efficiency for lignocellulosic ethanol. |
| LEED v4.1 Certification Alignment | Bio-phenol and bio-epoxy resins penetrate structural bonding markets through embodied carbon reduction credits. |
| Digital Marketplace Platform Launch | Blockchain-verified carbon accounting enables direct contracting between biomass processors and brand owners. |
Research Methodology
Document review covered trade customs databases, SEC 10-K filings, and ECHA REACH registration dossiers, complemented by interviews with fermentation plant managers, procurement leads at European packaging converters, distribution channel partners, and technical R&D directors at biotech firms. Bottom-up capacity assessments triangulated against top-down demand modeling from agrochemical and textile intermediate consumption patterns.
Historical production capacity trends cross-referenced against expert panel input on enzyme supply constraints and policy durability assumptions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use sector, production technology platform, and regional production hub cluster. CAGRs derived from feedstock cost trajectory scenarios and offtake contract velocity indicators, with enzymatic synthesis cost-parity milestones and EU Green Deal compliance deadlines serving as critical forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under electoral policy reversals or breakthroughs in thermochemical conversion economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Renewable Chemicals Market