
 Green Ammonia Manufacturing Market | 2026-2036
Green Ammonia Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Green Ammonia Manufacturing Market Insights
Proton-exchange membrane electrolysis paired with Haber-Bosch retrofitting is reconfiguring capital deployment across green ammonia manufacturing. Siemens Energy leverages its electrolyzer technology leadership to anchor large-scale project development in European industrial corridors. CF Industries competes through its established ammonia infrastructure and strategic pivot toward low-carbon retrofitting of existing Gulf Coast facilities. Nel ASA specializes in compact electrolyzer systems that extend modular production footprints into markets lacking legacy chemical plant networks.
Green ammonia manufacturing denotes the synthesis of NH₃ using hydrogen derived from water electrolysis powered by renewable electricity, typically operating at 15-25 bar pressure and 400-500°C with iron-based catalysts, primarily serving as a zero-carbon energy carrier and fertilizer feedstock. Electrolysis-based production dominates current project pipelines due to its technological maturity and compatibility with variable renewable inputs. Energy Storage applications represent the fastest-growing end user segment as utilities evaluate ammonia for seasonal power-to-power systems. Carbon Capture technology trails in deployment scale but occupies strategic positioning for regions with abundant biomass or industrial CO₂ streams seeking negative-emission pathways.
The EU Green Deal and its associated carbon border mechanism shape demand by penalizing embodied emissions in imported ammonia, while the EPA's evolving hydrogen production tax credits under the IRA influence project economics in the United States. Germany's KBA and federal energy regulators coordinate offshore wind-to-ammonia offtake frameworks that accelerate permitting for integrated facilities. Stakeholders must monitor how certification schemes for renewable hydrogen origin evolve, as these standards will determine which production configurations qualify for premium offtake contracts in maritime and power sector procurement.
Market Dynamics
Electrolyzer cost curves and renewable power purchase agreements are compressing production economics faster than conventional ammonia can adapt, forcing capital reallocation toward integrated wind-to-ammonia facilities.
Growth Catalysts
- EU Green Deal carbon border mechanism:Penalties on embodied emissions in imported ammonia redirect procurement toward electrolysis-based supply chains.
- Maritime shipping operators:Zero-carbon fuel mandates from the International Maritime Organization accelerate offtake contracting for bunkering applications.
- Proton-exchange membrane electrolysis:Compatibility with variable renewable inputs enables direct coupling with offshore wind generation in North Sea industrial clusters.
Market Restraints
- Renewable electricity price volatility:Intermittent wind and solar output creates input cost instability for continuous Haber-Bosch operations.
- Electrolyzer manufacturing concentration:Supply bottlenecks in European and Chinese production capacity constrain project deployment timelines.
- Blue ammonia substitution:Carbon capture-equipped steam methane reforming offers near-term lower-cost alternatives for fertilizer producers.
Strategic Opportunities
- Power-to-power seasonal storage:Utilities in Germany evaluate ammonia cracking for grid-balancing services during renewable curtailment periods.
- US Gulf Coast retrofitting:Existing ammonia infrastructure and IRA hydrogen production tax credits create low-carbon conversion pathways.
- Offshore wind-to-ammonia integration:Floating electrolyzer platforms eliminate transmission constraints for remote renewable resources.
Industry Challenges
- Renewable hydrogen certification complexity:Evolving origin-tracking standards from CertifHy and TÜV create compliance uncertainty for offtake contracts.
- Catalyst degradation under intermittent operation:Iron-based Haber-Bosch systems require steady-state conditions incompatible with variable renewable input.
- Specialized welding and pressure vessel fabrication:Scarcity of certified contractors for high-pressure ammonia infrastructure extends construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Ammonia Manufacturing Market |
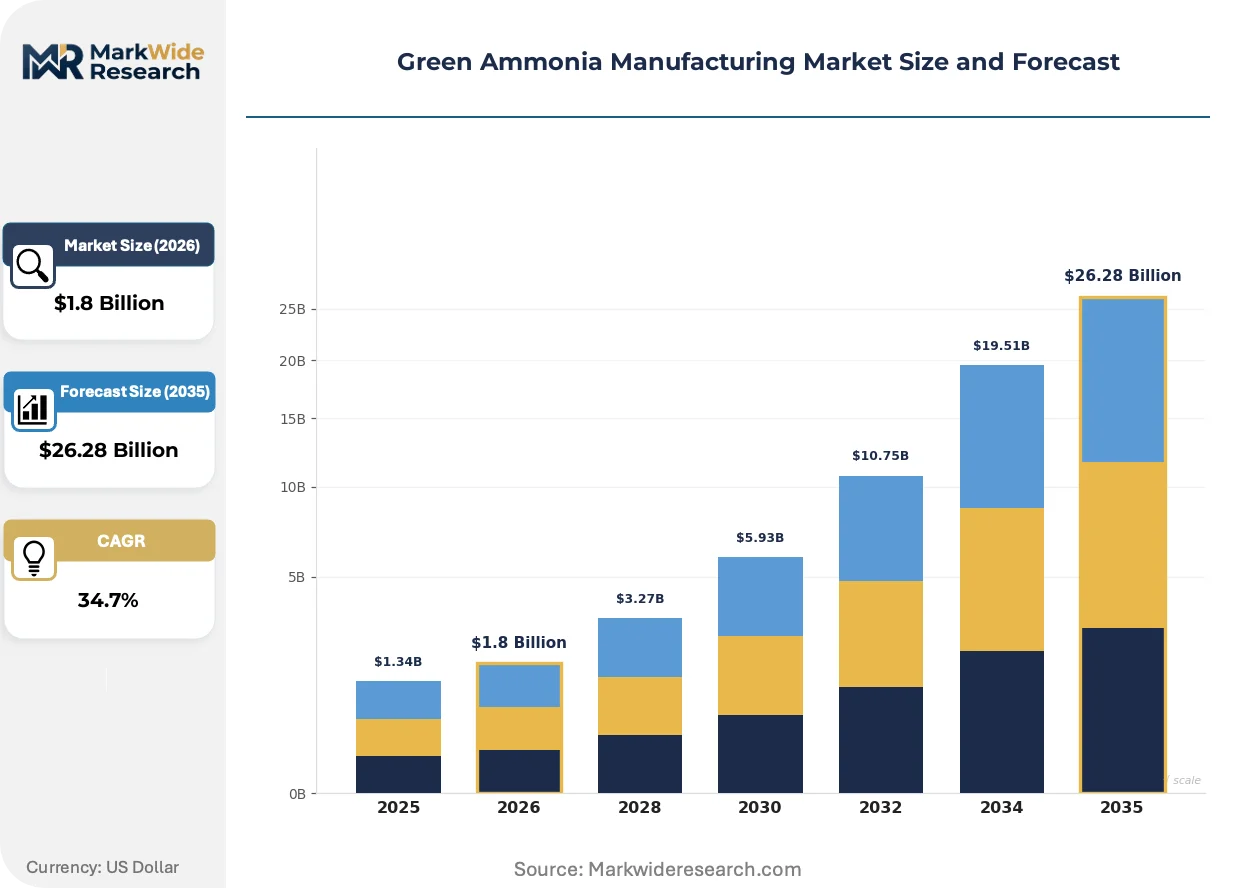
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Electrolysis, Haber-Bosch, Solid Oxide, Plasma Arc End User: Agriculture, Transportation, Energy Storage, Chemicals Technology: Renewable Energy, Carbon Capture, Membrane Technology, Electrochemical Distribution Channel: Direct Sales, Wholesalers, Online Retail, Exporters |
| Companies Covered | Yara International, Siemens Energy, CF Industries, Nel ASA, ACME Group, ThyssenKrupp, Ørsted, ITM Power, OCI Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Ammonia Manufacturing Market Trends and Innovations
Digital twin modeling and modular system architectures are compressing project development cycles while enabling remote operation of distributed production assets.
Solid oxide electrolyzer technology is virtualizing the conventional ammonia value chain by enabling direct nitrogen reduction without separate hydrogen compression stages. Industrial clusters in the Netherlands deploy these systems for integrated nitrate production. The technology is virtualizing capital deployment patterns by eliminating inter-process equipment and reducing footprint requirements.
EPA hydrogen production tax credit guidance under the IRA reshapes project finance structures by requiring hourly matching of renewable generation to electrolyzer operation. Developers reconfigure power purchase agreements to satisfy additionality and deliverability tests. Gulf Coast facilities face the steepest compliance adjustments due to grid interconnection constraints.
Maritime fuel procurement contracts now specify ammonia origin certification and lifecycle emission thresholds rather than commodity-grade specifications alone. Ship operators in Singapore and Rotterdam impose stringency beyond current IMO guidelines. This specification creep fragments supplier tiers between certified and uncertified production sources.
Green Ammonia Manufacturing Market Segmentation
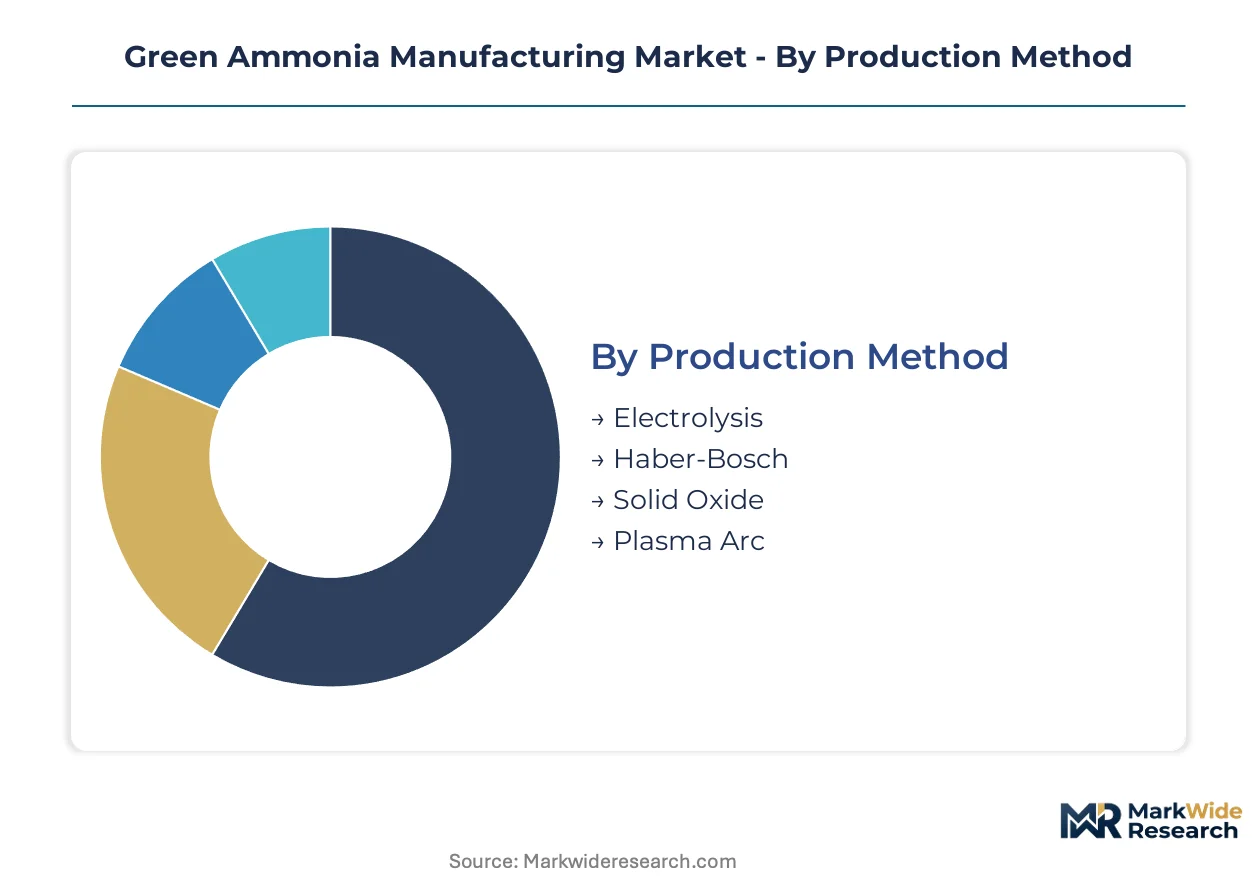
Production pathways and end-use applications segment green ammonia manufacturing into distinct investment and operational profiles. Each dimension carries specific regulatory, technological, and commercial imperatives that shape procurement strategies and project finance structures.
Production Method:
Cost tier differentiation separates established pathways from emerging alternatives, with capital intensity and renewable integration capability determining competitive positioning.
- Electrolysis:Water splitting via proton-exchange membrane or alkaline systems generates hydrogen feedstock for subsequent Haber-Bosch synthesis. Project pipelines in Germany's North Sea clusters concentrate here due to direct offshore wind coupling and EU Green Deal compliance advantages.
- Haber-Bosch:Retrofitted conventional ammonia plants integrate renewable hydrogen into existing synthesis loops at 15-25 bar pressure with iron-based catalysts. US Gulf Coast facilities leverage this pathway under IRA hydrogen production tax credit frameworks.
- Solid Oxide:High-temperature electrochemical cells enable direct nitrogen reduction without separate hydrogen compression stages.
- Plasma Arc:Non-thermal plasma activation of nitrogen at ambient pressure eliminates catalyst dependency.
Electrolysis commands the established base. The steepest expansion runs through Solid Oxide as Dutch industrial clusters demonstrate integrated nitrate production without inter-process equipment.
End User:
Application maturity and emission reduction urgency create divergent demand profiles across fertilizer, fuel, and power sector customers.
- Agriculture:Fertilizer producers constitute the incumbent demand base with established ammonia offtake infrastructure and seasonal consumption patterns.
- Transportation:Maritime shipping operators in Singapore and Rotterdam impose origin certification and lifecycle emission thresholds beyond IMO guidelines, fragmenting supplier tiers between certified and uncertified sources.
- Energy Storage:German utilities evaluate ammonia cracking for seasonal power-to-power grid balancing during renewable curtailment periods.
- Chemicals:Industrial feedstock applications for explosives, polymers, and refrigerants maintain steady demand with lower certification stringency.
Agriculture retains volume leadership. Energy Storage is gaining share fastest as power sector procurement frameworks mature.
Technology:
Supply concentration and integration depth differentiate technology categories, with renewable coupling requirements reshaping capital deployment patterns.
- Renewable Energy:Direct power purchase agreements with offshore wind or solar farms constitute the dominant integration model. EPA guidance under the IRA requires hourly matching of generation to electrolyzer operation, forcing PPA reconfiguration for Gulf Coast developers.
- Carbon Capture:Biomass or industrial CO₂ stream utilization enables negative-emission ammonia production for regions lacking abundant renewables.
- Membrane Technology:Proton-exchange and anion-exchange membranes separate gases without thermal cycles.
- Electrochemical:Direct ammonia synthesis cells bypass separate hydrogen production stages entirely.
Renewable Energy anchors current deployment. Carbon Capture occupies strategic positioning for biomass-rich geographies seeking negative-emission pathways.
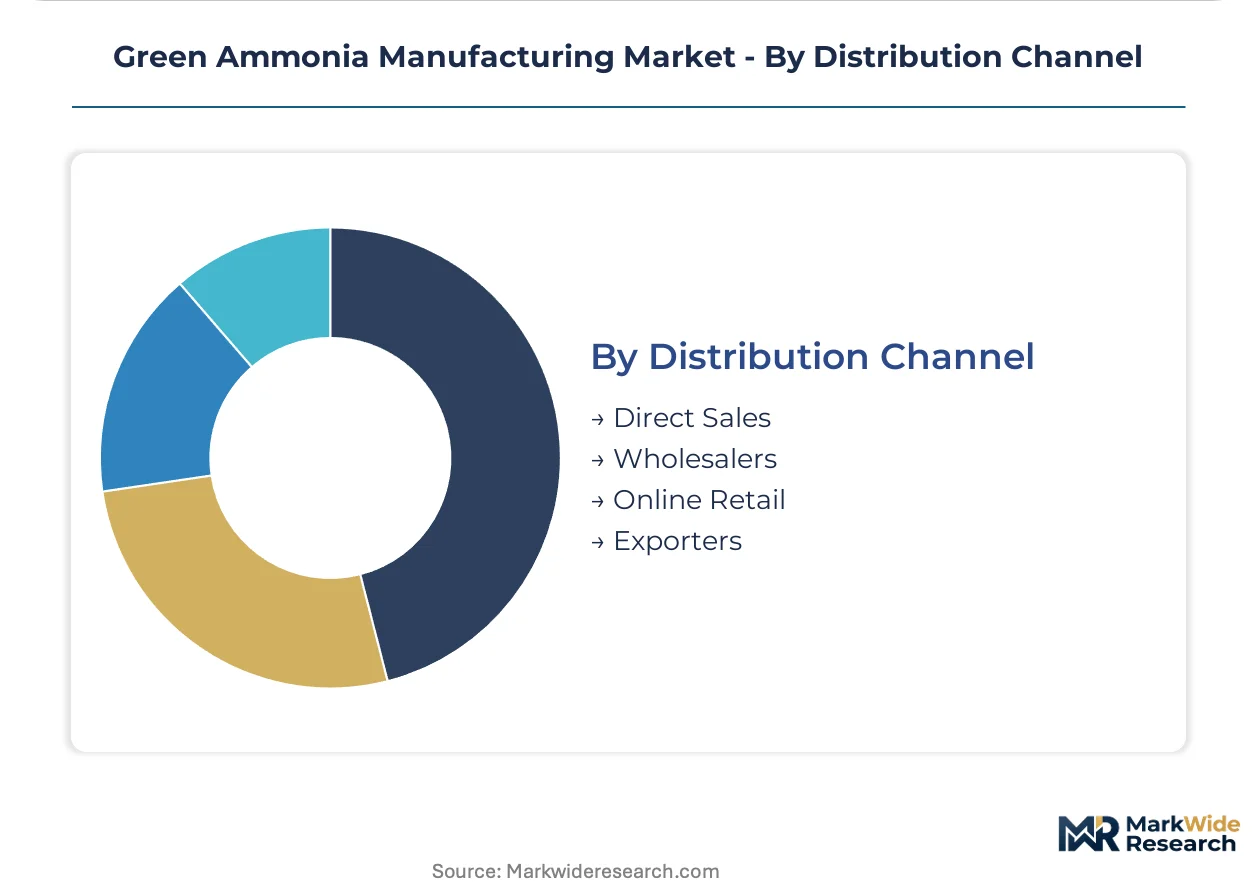
Distribution Channel:
Customer type and volume scale determine channel economics, with maritime bunkering and industrial offtake driving structural divergence.
- Direct Sales:Long-term offtake contracts with maritime operators, utilities, and chemical processors dominate large-volume transactions.
- Wholesalers:Regional distributors aggregate smaller agricultural and industrial demand across fragmented customer bases.
- Online Retail:Digital procurement platforms emerge for specialty chemical and research-grade ammonia volumes.
- Exporters:EU carbon border adjustment mechanisms redirect trade flows toward electrolysis-certified supply chains.
Direct Sales captures premium contract value. Exporters face the steepest compliance adjustments as certification schemes fragment market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import-export imbalances are redirecting capital toward electrolysis-based production in countries with abundant offshore wind resources. The EU carbon border adjustment mechanism penalizes embodied emissions in ammonia imports, accelerating domestic manufacturing investments in coastal industrial zones.
Germany
Maritime shipping operators in Hamburg and Bremen anchor demand for zero-carbon bunkering fuel. The KBA coordinates offshore wind-to-ammonia offtake frameworks with federal energy regulators. Industrial clusters around the North Sea integrate floating electrolyzer platforms with Haber-Bosch synthesis infrastructure.
United States
Existing Gulf Coast ammonia facilities pivot toward low-carbon hydrogen feedstock integration. EPA guidance under the IRA requires hourly matching of renewable generation to electrolyzer operation. Texas and Louisiana project developers reconfigure power purchase agreements to satisfy additionality tests for hydrogen production tax credits.
Netherlands
Rotterdam port authorities impose lifecycle emission thresholds beyond current IMO guidelines for maritime fuel procurement. The national government supports solid oxide electrolyzer deployment for integrated nitrate production. Industrial zones in the Eemshaven and Maasvlakte concentrate direct nitrogen reduction pilot facilities.
China
Dual carbon goals under MEE oversight accelerate renewable hydrogen project pipelines in coastal provinces. The country's national energy administration prioritizes electrolyzer manufacturing scale-up for domestic and export markets. Yangtze River Delta industrial corridors integrate proton-exchange membrane systems with existing chemical plant networks.
Saudi Arabia
NEOM Northwest anchors gigawatt-scale renewable ammonia export projects targeting European and Asian offtakers. The national industrial development program coordinates solar and wind resource allocation for integrated hydrogen-ammonia facilities. Red Sea coastal zones concentrate desalination-coupled electrolyzer installations for merchant chemical production.
Green Ammonia Manufacturing Market Competitive Landscape
On the supply side, the industry is consolidating around technology-integrated project developers with captive electrolyzer capabilities. Established ammonia producers compete against specialized hydrogen technology firms for offtake contracts in maritime and power sectors. Two strategic archetypes dominate: legacy chemical operators retrofitting existing synthesis infrastructure, and renewable energy developers building integrated wind-to-ammonia facilities. Capacity expansion and strategic partnerships represent the dominant competitive moves, with electrolyzer supply agreements anchoring project finance structures.
Within the technology-integrated tier, Siemens Energy and Nel ASA exemplify divergent scale strategies. Siemens Energy anchors large-scale European industrial corridor development through its electrolyzer technology position. Nel ASA occupies a modular systems niche that extends production footprints into markets lacking legacy chemical infrastructure. CF Industries represents the retrofitting archetype among established ammonia producers, leveraging existing Gulf Coast synthesis loops for low-carbon transition pathways.
| Leading Market Players |
|---|
| Yara International |
| Siemens Energy |
| CF Industries |
| Nel ASA |
| ACME Group |
| ThyssenKrupp |
| Ørsted |
| ITM Power |
| OCI Global |
| Others |
Pricing and Supply Chain Analysis
EU carbon border adjustment exposure determines both pricing tier spreads and supply chain shape across green ammonia manufacturing. The mechanism penalizes embodied emissions in imported ammonia, forcing procurement toward electrolysis-certified supply chains while compressing margins for uncertified producers.
Pricing Analysis
Current-generation proton-exchange membrane electrolysis commands premium contract terms against solid oxide next-generation pilots and conventional Haber-Bosch retrofitting. Pricing stratifies across certification grade, volume scale, and geographic delivery cost, with maritime offtakers in Rotterdam and Singapore absorbing the steepest premiums for origin-verified fuel. Cost compression in electrolyzer manufacturing is intensifying because Chinese and European production capacity expansion outpaces project deployment timelines. Agricultural fertilizer buyers exhibit highest price sensitivity, while maritime operators demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Electrolyzer manufacturing concentration in Germany, China, and Norway anchors upstream capacity allocation for project developers. The supply chain draws from iridium catalysts, proton-exchange membranes, and high-pressure vessel fabrication as critical input dependencies. Single-source vulnerability in certified welding contractor pools extends construction schedules for integrated facilities. Distribution runs through long-term offtake contracts with maritime operators and utilities rather than spot commodity trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs through certification-tier bifurcation as maritime procurement specifications diverge from agricultural commodity standards. Origin-tracking mandates from the IMO and EU Green Deal create distinct supplier tiers that reward early certification investment.
For Market Incumbents: Pre-empt blue ammonia substitution by accelerating Haber-Bosch retrofitting with renewable hydrogen feedstock integration at Gulf Coast facilities. Anchor electrolyzer supply agreements with Siemens Energy or Nel ASA to secure project finance structures before manufacturing bottlenecks deepen. Certification investment in CertifHy and TÜV standards represents the critical defensive lever against emerging pure-play hydrogen technology firms.
For New Entrants and Emerging Players: Build out modular electrolyzer footprints in markets lacking legacy chemical infrastructure, targeting German North Sea industrial clusters where floating platform integration eliminates transmission constraints. The most penetrable segment sits in power-to-power seasonal storage applications where utilities evaluate ammonia cracking for grid-balancing services. Go-to-market positioning should emphasize direct nitrogen reduction technology for integrated nitrate production in Dutch industrial zones.
For Investors and Strategic Acquirers: The market sits at a capital-deployment acceleration phase that favors technology-integrated project developers with captive electrolyzer capabilities. Long-term viability across the analysis window hinges on hourly matching compliance for IRA hydrogen production tax credits and EU origin certification frameworks. Acquisition targets should demonstrate secured renewable power purchase agreements with additionality and deliverability tests satisfied. The signal to watch is EPA guidance refinement on hydrogen production tax credit eligibility as an inflection indicator for US project economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Supply Agreement | Siemens Energy and Nel ASA anchor project finance structures for European corridor development. |
| Renewable Power Purchase Agreement | Hourly matching compliance under IRA frameworks determines hydrogen production tax credit eligibility. |
| Maritime Certification Program | Rotterdam and Singapore port authorities impose lifecycle emission thresholds beyond IMO guidelines. |
| Haber-Bosch Retrofitting | CF Industries leverages existing Gulf Coast synthesis loops for low-carbon transition pathways. |
| Offshore Platform Integration | Floating electrolyzer systems in German North Sea clusters eliminate transmission constraints for remote wind resources. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across electrolyzer manufacturers, maritime fuel procurement officers, utility planning directors, and ammonia synthesis plant engineers. Secondary validation drew from EIA energy data, IEA hydrogen project databases, FERC interconnection filings, and EU carbon border adjustment mechanism regulatory texts. Bottom-up project pipeline aggregation was triangulated against top-down macroeconomic demand modeling for fertilizer, fuel, and power sector applications.
Calibration against historical electrolyzer deployment rates and renewable power purchase agreement execution timelines anchored volume projections across the analysis window. Segmentation dimensions modeled include production pathway, end-use application, technology integration depth, and regional regulatory framework. CAGRs were derived from capacity expansion announcements, offtake contract volumes, and policy incentive evolution rather than extrapolated trend fitting. Industry-specific inputs incorporated maritime fuel specification creep and catalyst degradation rates under intermittent renewable operation.
Stress conditions across renewable electricity price volatility, electrolyzer manufacturing bottlenecks, and certification standard evolution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and IRA hydrogen production tax credit guidance stability. Quarterly review of maritime procurement contract specifications and electrolyzer cost curve trajectories is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Renewable Chemicals Market