
 Renewable Chemicals Market | 2026-2036
Renewable Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Chemicals Market Intelligence
Modular biorefinery configurations is pivoting buyer procurement away from single-product contracts toward integrated feedstock-to-chemical service agreements. BASF SE leverages its Verbund site network to sustain captive fermentation capacity across Ludwigshafen and Antwerp. Cargill Inc anchors North American corn-sugar supply chains through backward integration into agricultural origination. Amyris Inc specializes in strain-engineered terpenoid production, differentiating its portfolio from commodity ethanol players.
Renewable chemicals comprise molecules derived from biomass, agricultural residues, or microbial fermentation rather than petroleum feedstocks, with specifications typically requiring minimum biobased carbon content thresholds under ASTM D6866 or equivalent test methods. These chemicals serve as drop-in replacements or performance-advantaged alternatives in plastics, fuels, surfactants, and specialty formulations across industrial supply chains. Bio-based polymers command the deepest margin pools due to brand-owner sustainability commitments in packaging and consumer goods, while biochemicals produced via enzymatic synthesis represent the fastest-expanding production technology category as catalyst specificity improves yield economics. Bioplastics remain supply-constrained relative to demand signals from food-contact packaging regulations in the European Union and select Asian markets.
The EU Green Deal and REACH frameworks mandate progressive reduction of fossil-derived substances in consumer-facing products, while the EPA administers biobased procurement preference programs under the Farm Bill that shape North American demand. FDA food-contact notifications and EFSA safety assessments determine which fermentation-derived molecules gain market access for packaging applications. Stakeholders must monitor regulatory divergence between jurisdictions where biobased carbon accounting methods differ, as these measurement standards will determine which production technologies qualify for preferential treatment.
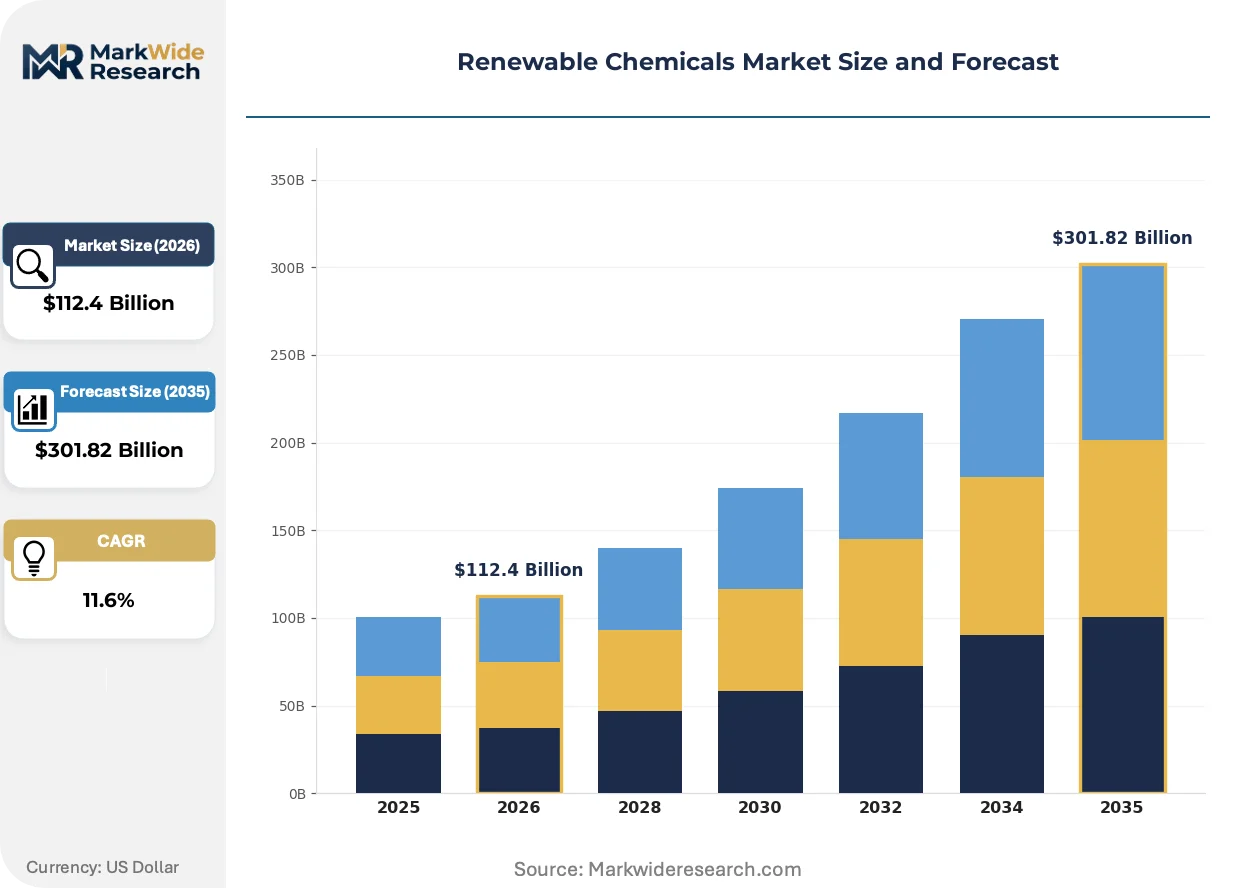
Market Dynamics
Modular biorefinery configurations are pivoting buyer procurement away from single-product contracts toward integrated feedstock-to-chemical service agreements, compressing supplier margins while locking in volume commitments across multi-year horizons.
Growth Catalysts
- EU Green Deal compliance mandates:Progressive reduction requirements for fossil-derived substances in consumer-facing products are pulling bio-based polymers into rigid container and flexible film specifications across member states.
- Enzymatic synthesis yield improvements:Catalyst specificity advances are compressing production economics for biochemicals, expanding addressable applications beyond commodity ethanol into performance-advantaged specialty formulations.
- German industrial biotech clustering:Concentrated fermentation capacity around Ludwigshafen and Antwerp is generating supplier density effects that reduce logistics costs for packaging manufacturers sourcing bio-based inputs.
Market Restraints
- Corn-sugar input cost volatility:Agricultural commodity price swings transmit directly to fermentation economics, squeezing margin stability for North American producers dependent on starch-derived feedstocks.
- Bioplastics supply concentration:Production capacity for food-contact compliant materials remains geographically concentrated in Western Europe, creating allocation risk during demand surges from Asian packaging converters.
- REACH registration timelines:Extended substance evaluation periods for novel fermentation-derived molecules delay market access, extending payback periods for strain-engineering investments beyond typical venture capital horizons.
Strategic Opportunities
- Underpenetrated Indian packaging conversion:FSSAI food-contact regulations are beginning to align with biobased material acceptance, opening procurement channels for rigid container specifications previously locked into petroleum-based supply.
- Agricultural residue valorization:Lignocellulosic feedstock processing technology convergence with existing corn-sugar infrastructure offers pathway to sub-$3 per gallon equivalent production costs for platform chemicals.
- USDA BioPreferred program expansion:Federal procurement preference thresholds are tightening, creating mandated demand pools for biobased surfactants and lubricants in government supply contracts.
Industry Challenges
- Strain engineering talent scarcity:Synthetic biology skill concentrations remain limited to select academic and industrial clusters, constraining scale-up velocity for novel terpenoid production campaigns.
- ASTM D6866 certification bottlenecks:Biobased carbon content verification timelines create inventory holding costs and delay customer qualification for drop-in replacement molecules.
- Legacy petrochemical integration friction:Existing steam cracker and reformer assets require substantial retrofit capital to handle oxygenated bio-intermediates, slowing hybrid facility deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Chemicals Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $301.82 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-based Polymers, Bioplastics, Biofuels, Biochemicals, Biosurfactants Application: Packaging, Agrochemicals, Personal Care, Textiles, Adhesives, Cleaning Agents Production Technology: Fermentation, Hydrolysis, Catalytic Conversion, Enzymatic Synthesis, Pyrolysis End User Industry: Consumer Goods Manufacturers, Chemical Specialties, Agricultural Firms, Cosmetic Producers, Textile Makers |
| Companies Covered | Archer-Daniels-Midland Company (ADM), BASF SE, Cargill Inc, Amyris Inc, Braskem, DSM, Genomatica Inc, Solvay, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Chemicals Market Strategic Shifts & Innovations
Biorefinery process intensification is collapsing the traditional separation between upstream fermentation and downstream purification, enabling continuous-flow configurations that reshape capital deployment patterns across the value chain.
Continuous chromatography systems are unifying product recovery and impurity rejection in single-unit operations. Specialty chemical manufacturers in the Netherlands and Belgium are retrofitting batch facilities with simulated moving bed technology, reducing solvent consumption by half. This unifying architecture is compressing the minimum efficient scale for viable bioproduction, opening entry paths for mid-cap players previously excluded by capex barriers.
REACH authorization requirements for Substances of Very High Concern are accelerating substitution programs for phthalate plasticizers and bisphenol derivatives. ECHA's 2024-2026 rolling action plan targets endocrine-disrupting candidates used in food-contact applications. Packaging converters in France and Germany are responding by qualifying bio-based alternatives ahead of sunset date announcements, building inventory buffers against supply discontinuities.
Brand-owner sustainability scorecards are restructuring supplier selection criteria for polymer procurement. Unilever and Nestlé packaging specifications now embed biobased carbon thresholds alongside mechanical recyclability metrics. This preference compression is most visible in German rigid container markets, where converters report 18-month qualification cycles for new bio-polymer sources versus 6-month cycles for conventional materials.
Renewable Chemicals Market Segmentation
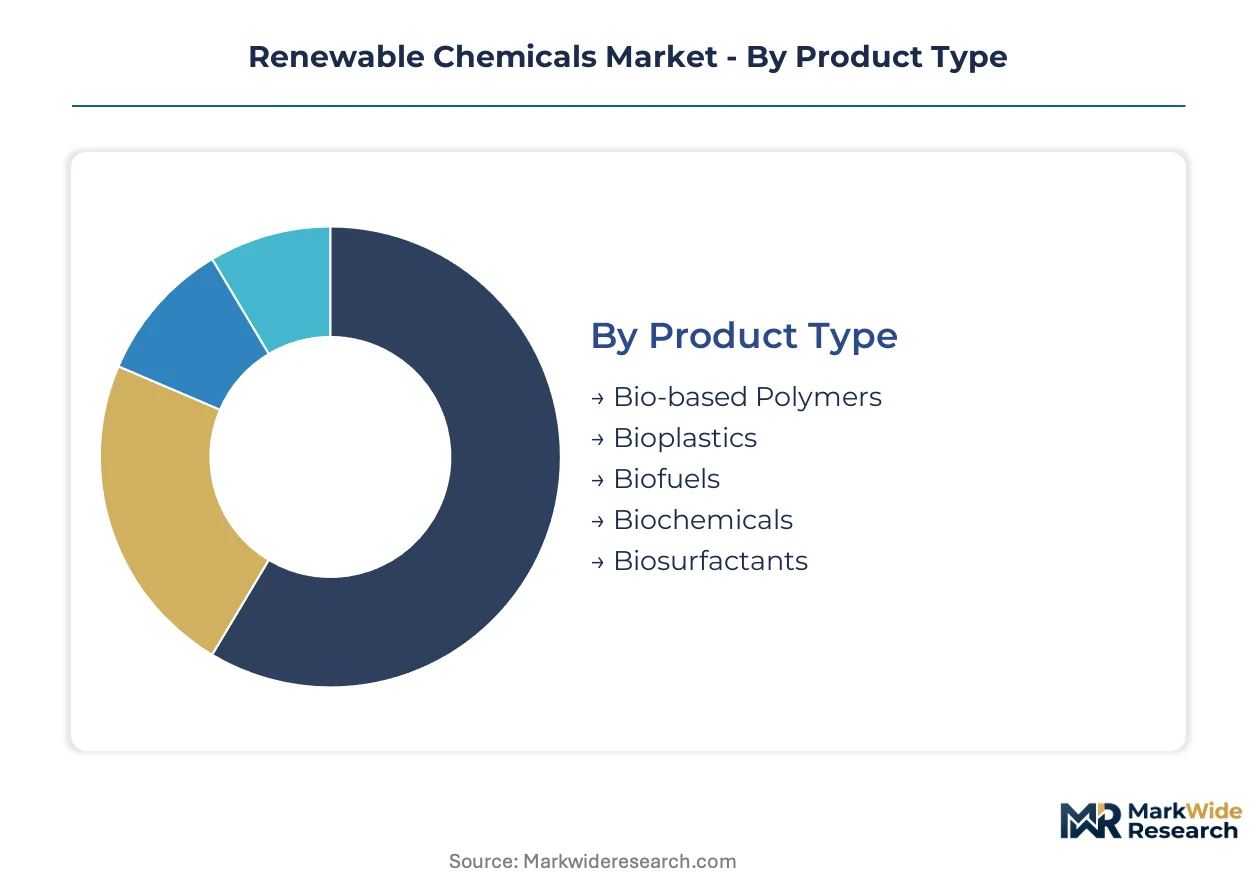
Renewable chemicals demand fragments across incompatible performance specifications and regulatory thresholds that reshape procurement priorities. Each segmentation dimension carries distinct margin structures and qualification timelines that determine supplier selection criteria.
Product Type:
Upgrade cycles in packaging sustainability scorecards are pulling brand owners toward bio-based replacements that meet ASTM D6866 thresholds without mechanical property trade-offs.
- Bio-based Polymers:Long-chain molecules derived from starch or cellulose feedstocks meeting food-contact compliance under FDA and EFSA frameworks. Packaging converters in Germany and France now specify minimum biobased carbon content for rigid containers, driven by EU Green Deal reduction mandates for fossil-derived substances.
- Bioplastics:Thermoplastic resins including PLA and PHA variants processed on conventional extrusion equipment with modified temperature profiles. Supply remains concentrated in Western Europe, creating allocation risk for Asian converters seeking food-contact compliant materials amid REACH authorization timelines.
- Biofuels:Liquid transportation fuels from lipid or sugar fermentation meeting ASTM D6751 or EN 14214 specifications.
- Biochemicals:Platform molecules including organic acids and alcohols serving as petrochemical drop-ins.
- Biosurfactants:Microbially produced surface-active agents with biodegradability advantages in marine environments.
Bio-based polymers sit at the top of the volume ranking, with biosurfactants climbing the fastest as marine discharge regulations tighten.
Application:
Cost tier differentiation separates premium food-contact specifications from industrial grades with relaxed purity thresholds.
- Packaging:Flexible films and rigid containers requiring FDA food-contact notifications or EFSA safety assessments for direct food contact. German and Belgian converters report 18-month qualification cycles versus 6-month cycles for conventional polymers, compressing supplier margins through extended technical service commitments.
- Agrochemicals:Bio-based adjuvants and carrier solvents replacing petroleum-derived formulations in crop protection. Demand concentrates in agricultural origination regions where backward integration into corn-sugar supply chains reduces input cost volatility for North American producers.
- Personal Care:Fermentation-derived emollients and active ingredients meeting cosmetic safety dossier requirements.
- Textiles:Bio-polyester and cellulosic fibers for apparel and technical fabric applications.
- Adhesives:Bio-based tackifiers and resins for pressure-sensitive and structural bonding applications.
- Cleaning Agents:Surfactant and solvent formulations for household and industrial degreasing.
Packaging commands the steepest expansion trajectory, with cleaning agents gaining share fastest as institutional procurement preferences shift.
Production Technology:
Technology maturity determines capital deployment patterns, with established fermentation infrastructure competing against emerging thermochemical routes.
- Fermentation:Microbial conversion of sugars to target molecules in stirred-tank bioreactors with downstream recovery. BASF SE maintains captive capacity across Ludwigshafen and Antwerp Verbund sites, generating supplier density effects that reduce logistics costs for packaging manufacturers.
- Enzymatic Synthesis:Biocatalytic transformations with improved specificity and reduced byproduct formation. Catalyst advances are compressing production economics for biochemicals, expanding addressable applications beyond commodity ethanol into performance-advantaged specialty formulations.
- Hydrolysis:Acid or enzyme-mediated cleavage of polysaccharides to fermentable sugars.
- Catalytic Conversion:Chemical transformation of bio-intermediates using heterogeneous catalysts.
- Pyrolysis:Thermal decomposition of lignocellulosic biomass in oxygen-limited conditions.
Fermentation sits at the top of the volume ranking, with enzymatic synthesis climbing the fastest as yield economics improve.
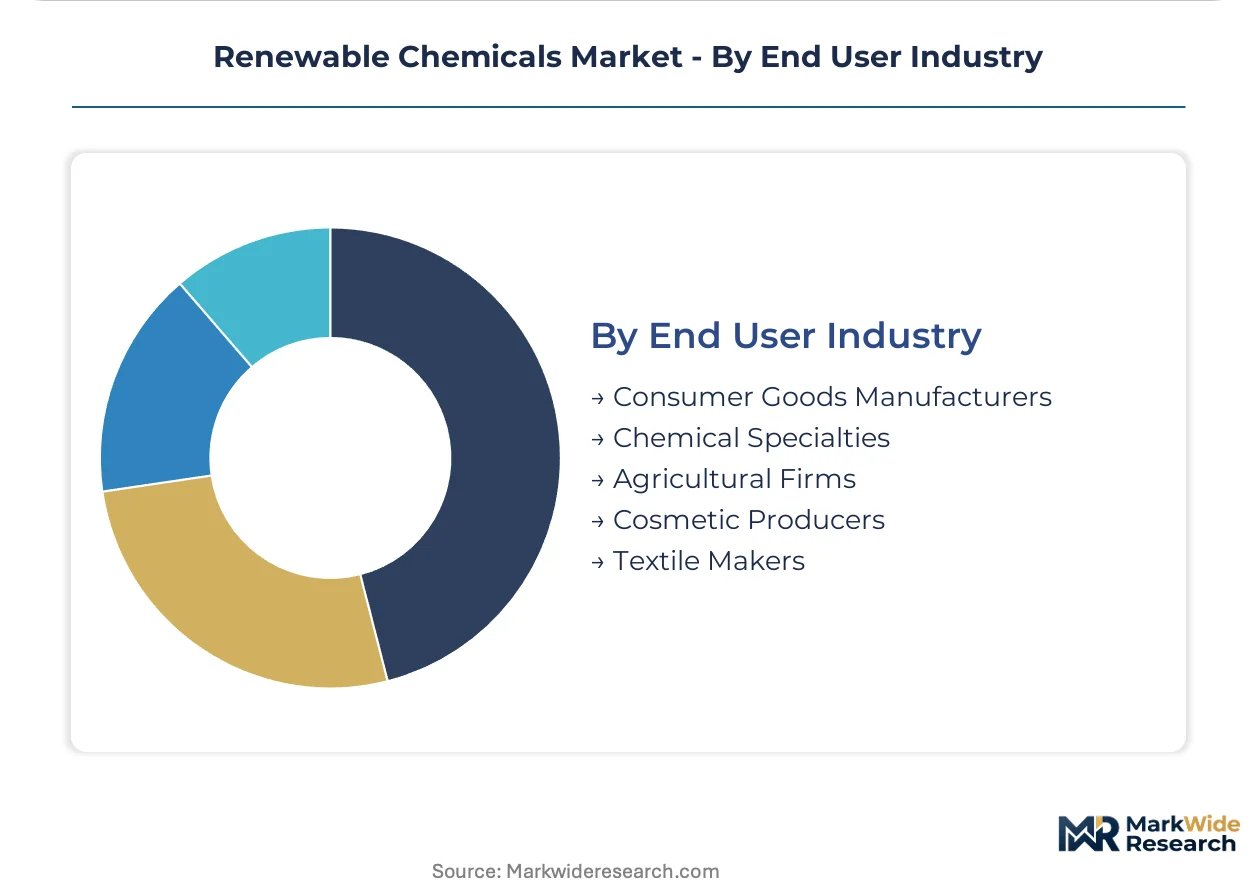
End User Industry:
Customer type determines contract structures, with consumer goods manufacturers demanding multi-year supply commitments versus spot purchasing by industrial processors.
- Consumer Goods Manufacturers:Brand owners embedding biobased carbon thresholds alongside mechanical recyclability metrics in supplier scorecards. Unilever and Nestlé packaging specifications now drive 18-month qualification cycles for new bio-polymer sources in German rigid container markets.
- Chemical Specialties:Formulators integrating bio-based intermediates into surfactant, lubricant, and coating products. USDA BioPreferred program expansion is tightening federal procurement preference thresholds, creating mandated demand pools for biobased surfactants in government supply contracts.
- Agricultural Firms:Crop protection and fertilizer companies seeking bio-based adjuvants.
- Cosmetic Producers:Beauty and personal care brands requiring fermentation-derived actives with cosmetic safety dossiers.
- Textile Makers:Fiber and fabric producers specifying bio-polyester and cellulosic inputs.
Consumer goods manufacturers sit at the top of the volume ranking, with chemical specialties climbing the fastest as federal procurement mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial biotech clusters first achieved scale in Germany's Rhine corridor during the 1990s, establishing the template for integrated fermentation capacity that now spans three continents. Production economics and regulatory stringency have since fragmented leadership across North American corn-belt infrastructure and Asian packaging conversion zones.
Germany
Food-contact packaging specifications from Unilever and Nestlé pull bio-based polymers into rigid container supply chains. EU Green Deal mandates progressively tighten fossil-derived substance thresholds across member states. Ludwigshafen and Antwerp anchor Europe's densest fermentation corridor, where BASF SE maintains captive capacity through its Verbund site network.
United States
USDA BioPreferred program expansion tightens federal procurement preference thresholds for biobased surfactants and lubricants. The Farm Bill administers biobased procurement programs that shape domestic demand pools. Corn-sugar supply chains concentrate in the Midwest, where Cargill Inc leverages backward integration into agricultural origination to stabilize input costs.
India
FSSAI food-contact regulations are beginning to align with biobased material acceptance in rigid container specifications. Central government procurement guidelines increasingly reference biobased carbon thresholds for packaging applications. Maharashtra and Gujarat host emerging conversion capacity as brand owners qualify alternative polymer sources ahead of regulatory sunset dates.
China
Dual carbon goals accelerate substitution programs for petroleum-derived platform chemicals in coastal manufacturing zones. NMPA and MEE frameworks determine which fermentation-derived molecules gain market access for domestic packaging applications. Yangtze River Delta converters are building inventory buffers against bioplastics allocation risk from Western European supply concentration.
Brazil
Sugarcane bagasse valorization programs create feedstock cost advantages for lignocellulosic platform chemical production. ANVISA food-contact safety assessments determine qualification timelines for bio-based polymer alternatives. São Paulo state anchors South American fermentation infrastructure, with Braskem leveraging captive ethanol chemistry for bio-polymer scale-up.
Renewable Chemicals Market Key Industry Players
The competitive structure tilts toward integrated conglomerates with captive feedstock access and fermentation capacity. BASF SE and Evonik Industries AG anchor German industrial biotech clusters through Verbund site networks that compress logistics costs. Three archetypes dominate: agricultural processors with origination-to-chemical vertical control, diversified chemical conglomerates with modular biorefinery configurations, and strain-engineering specialists focused on terpenoid and specialty molecule production. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with multi-year feedstock-to-chemical service agreements replacing single-product contracts.
Within the agricultural processor archetype, Archer-Daniels-Midland Company and Cargill Inc exemplify backward integration into corn-sugar supply chains that stabilizes fermentation economics against commodity volatility. Among strain-engineering specialists, Amyris Inc occupies a position distinct from commodity ethanol players through its focus on engineered terpenoid production. BASF SE represents the diversified chemical conglomerate model, leveraging Ludwigshafen and Antwerp site density to serve packaging manufacturers with integrated bio-based polymer supply.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company (ADM) |
| BASF SE |
| Cargill Inc |
| Amyris Inc |
| Braskem |
| DSM |
| Genomatica Inc |
| Solvay |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
EU Green Deal procurement mandates for bio-based polymers in rigid containers are forcing packaging converters to qualify multiple fermentation-derived suppliers simultaneously, compressing supplier margins through extended technical service commitments while fragmenting volume across qualified sources rather than concentrating purchasing power.
Pricing Analysis
Three-tier pricing structure across premium food-contact, standard industrial, and economy commodity grades shapes transaction economics. Premium tiers command spreads based on EFSA safety dossier completion and ASTM D6866 certification status, while standard grades compete on corn-sugar input cost pass-through mechanics. Cost compression in commodity biochemicals is intensifying as enzymatic synthesis yield improvements expand supply availability. Consumer goods manufacturers exhibit lowest price sensitivity due to sustainability scorecard requirements, whereas industrial formulators prioritize input cost stability over certification premiums.
Supply Chain Analysis
Dual-sourcing requirements from Unilever and Nestlé packaging specifications mandate converters maintain qualified supplier relationships across Germany, Belgium, and the United States simultaneously. Raw material dependencies center on corn-sugar feedstocks from Midwest agricultural origination regions, lignocellulosic agricultural residues, and strain-engineered microbial cultures. Single-source vulnerability concentrates in food-contact compliant bioplastics capacity located in Western Europe. Distribution runs through integrated feedstock-to-chemical service agreements replacing conventional spot purchasing, with BASF SE and Evonik Industries AG anchoring captive logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal progressive reduction mandates for fossil-derived substances generate structurally expanding demand pools for compliant bio-based alternatives.
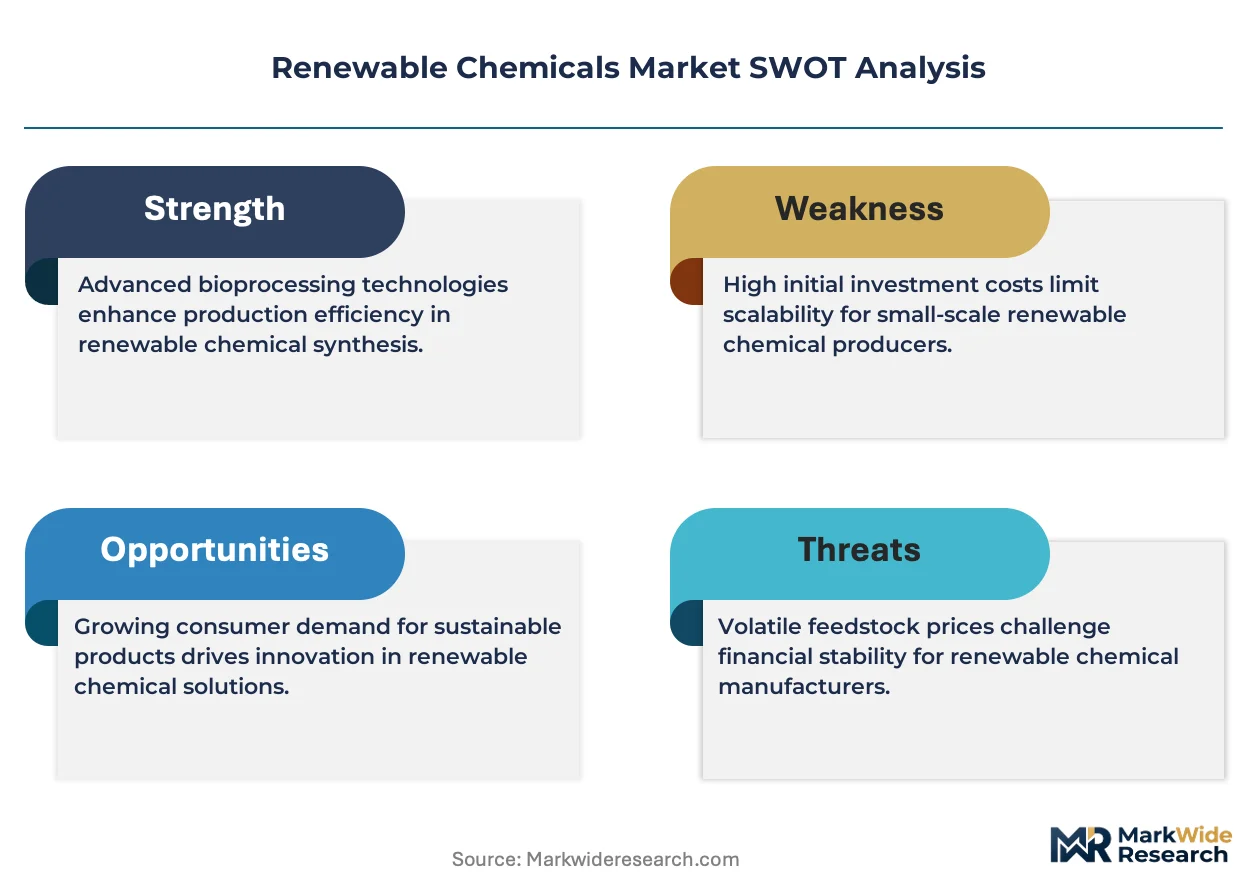
For Market Incumbents: Deepen backward integration into agricultural origination to stabilize corn-sugar input cost volatility against margin compression from modular biorefinery service agreements. Expand captive fermentation capacity at Ludwigshafen and Antwerp Verbund sites to defend logistics cost advantages against emerging Indian packaging conversion capacity. Prioritize REACH registration completion ahead of authorization timelines to secure first-mover qualification status. For New Entrants and Emerging Players: USDA BioPreferred program expansion in the United States opens a window for biobased surfactant and lubricant qualification ahead of tightening federal procurement thresholds. Target FSSAI-aligned food-contact specifications in Maharashtra and Gujarat rigid container markets where incumbent qualification cycles lag demand growth. Pursue strain-engineering specialization in terpenoid production to differentiate from commodity ethanol competition. For Investors and Strategic Acquirers: Asymmetric upside sits with agricultural processors possessing origination-to-chemical vertical control and modular biorefinery configuration capabilities. Long-term viability hinges on regulatory enforcement durability across EU Green Deal and REACH frameworks rather than feedstock cost cyclicality. Monitor ASTM D6866 certification bottleneck resolution as inflection indicator for customer qualification velocity and inventory holding cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Origination | Cargill Inc stabilizes corn-sugar supply costs through captive origination infrastructure. |
| Modular Biorefinery Configuration | BASF SE compresses logistics costs across Ludwigshafen and Antwerp Verbund site networks. |
| REACH Registration Investment | Novel fermentation-derived molecules gain market access ahead of sunset date discontinuities. |
| Strain Engineering Specialization | Amyris Inc differentiates terpenoid portfolio from commodity ethanol production economics. |
| Long-term Supply Agreement Structuring | Integrated feedstock-to-chemical contracts lock volume commitments across multi-year horizons. |
Research Approach
Direct dialogue with plant managers at German and Belgian fermentation facilities, procurement leads at packaging converters, distribution channel partners in North American corn-belt regions, and technical R&D directors specializing in enzymatic synthesis grounded qualitative assessments. Secondary validation drew from ECHA substance evaluation databases, EU Green Deal implementation progress reports, USDA BioPreferred program procurement disclosures, and SEC filings from listed chemical conglomerates. Bottom-up volume estimates from individual production facility capacities triangulated against top-down demand projections from end-use industry consumption patterns.
Segment-level value outputs across the projection horizon reflect modeled interactions between product type tiers, application specifications, production technology maturity curves, and end-user industry contract structures. The analytical framework incorporated bio-based polymer grade differentiation, food-contact compliance status, fermentation versus thermochemical route economics, and regional regulatory cluster stringency. CAGRs derived from regression analysis of historical capacity expansion rates against regulatory mandate implementation schedules, with strain engineering yield improvement curves and enzymatic synthesis catalyst cost trajectories as key forecast inputs.
Revisions become necessary when EU Green Deal enforcement intensity shifts, REACH authorization timelines extend beyond modeled durations, or corn-sugar agricultural commodity price volatility exceeds historical bands. Deviation in ASTM D6866 certification standard adoption rates across jurisdictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Natural L-Lactic Acid Market