
 Global Green Chemicals Market | 2026-2036
Global Green Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Green Chemicals Market Analysis
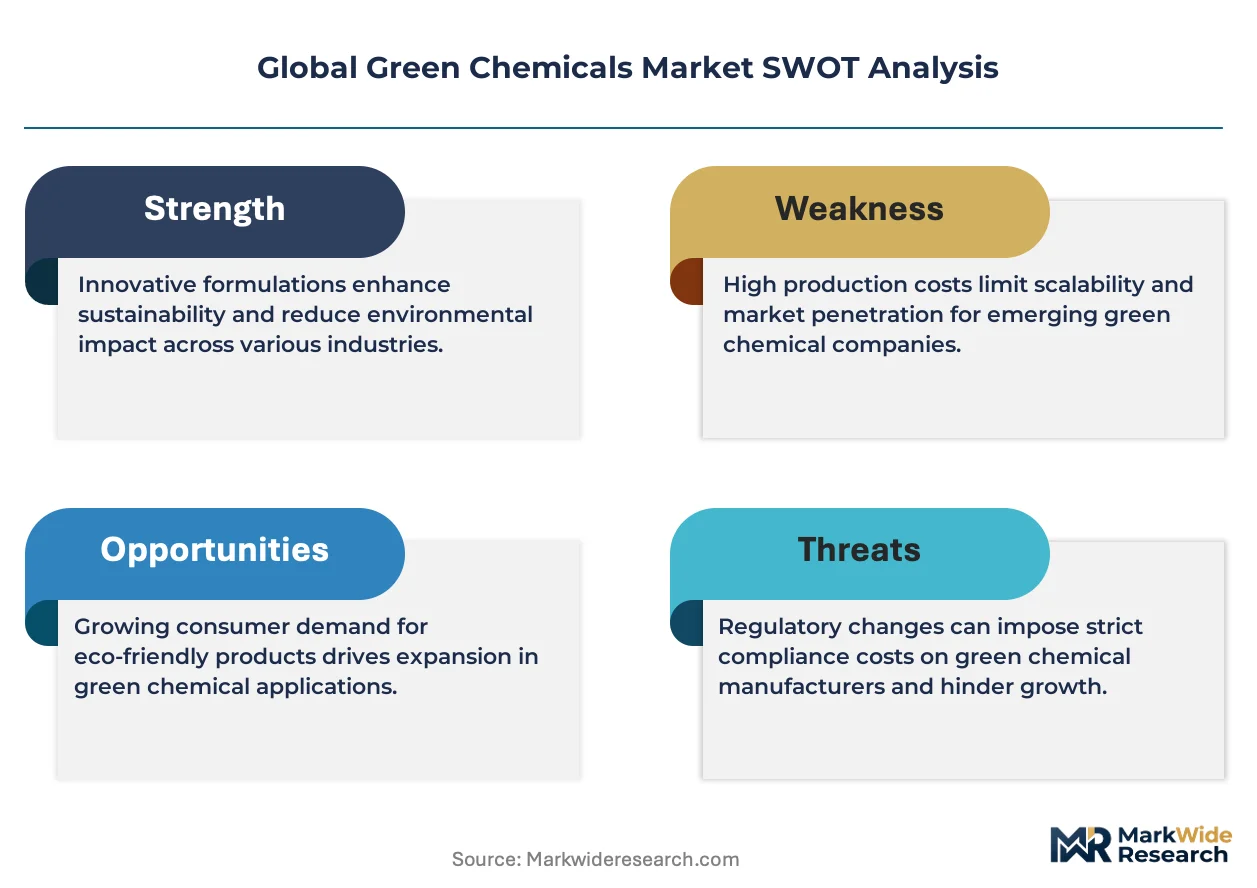
ISO 17021 certification for sustainable chemical verification is collapsing the supplier base eligible for premium procurement contracts. BASF SE leverages its Ludwigshafen integrated biorefinery complex to sustain captive supply of bio-based polyamides. Braskem dominates South American ethanol-to-ethylene output, while Corbion N.V. specializes in fermentation-derived lactic acid for PLA bioplastics.
Green chemicals comprise molecules derived from renewable biomass, agricultural residues, or captured carbon rather than fossil feedstocks, typically meeting minimum bio-based carbon content thresholds measured through ASTM D6866 radiocarbon analysis. Their primary purpose is to replace petrochemical intermediates in polymers, solvents, fuels, and specialty formulations without sacrificing performance specifications. Bioplastics currently anchors the largest value pool, though biofuels competes for capital as aviation blend mandates tighten. Surfactants navigates margin pressure from palm oil volatility, while organic solvents positions for electronics-grade purity requirements.
REACH registration deadlines in Europe, EPA renewable fuel standards in the United States, and China's MEE dual carbon enforcement collectively reshape feedstock sourcing rules and product qualification pathways. The EU AI Act and CSRD disclosure rules will soon extend liability to chemical supply chain emissions reporting. Stakeholders must monitor which certification schemes achieve cross-border reciprocity before committing to capacity expansion.
Market Dynamics
ISO 17021 certification requirements for sustainable chemical verification are collapsing the eligible supplier base for premium procurement contracts, concentrating purchasing power among integrated biorefinery operators and fermentation specialists with captive carbon accounting capabilities.
Growth Catalysts
- REACH Phase-Down Schedules:ECHA's tightening petrochemical restrictions in Germany and France are compelling personal care formulators to expand bio-based surfactant procurement.
- Aviation Blend Mandates:EPA renewable fuel standards and EU ReFuelEU Aviation obligations are redirecting capital toward fermentation-derived alcohol-to-jet pathways.
- East Asian OEM Procurement Rules:Electronics and automotive manufacturers around Shanghai and Seoul now mandate renewable feedstock certificates in supplier contracts.
Market Restraints
- Palm Oil Price Volatility:Surfactant margins compress when Malaysian and Indonesian feedstock costs spike, undermining bio-based cost parity with petrochemical alternatives.
- Feedstock Concentration Risk:Brazilian sugarcane ethanol and US corn starch dominate carbohydrate feedstock supply, creating geographic single-point vulnerabilities.
- ASTM D6866 Testing Bottlenecks:Limited radiocarbon analysis laboratory capacity delays product qualification timelines for mid-scale producers seeking bio-based certification.
Strategic Opportunities
- Captured Carbon Utilization:Power-to-liquid and gas fermentation technologies are opening synthetic biology pathways for producers in regions with stranded renewable electricity.
- Electronics-Grade Solvent Purity:Semiconductor fabs in Taiwan and South Korea are qualifying bio-based N-methyl-2-pyrrolidone alternatives for photoresist stripping applications.
- EU CSRD Supply Chain Liability:Extended emissions reporting obligations create first-mover advantages for chemical producers with verified Scope 3 data infrastructure.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Industrial biotech process engineers with commercial-scale experience command premium compensation, constraining capacity expansion timelines.
- Legacy Petrochemical Asset Stranding:Integrated refiners face write-down risks as EU Green Deal timelines accelerate feedstock transition requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Green Chemicals Market |
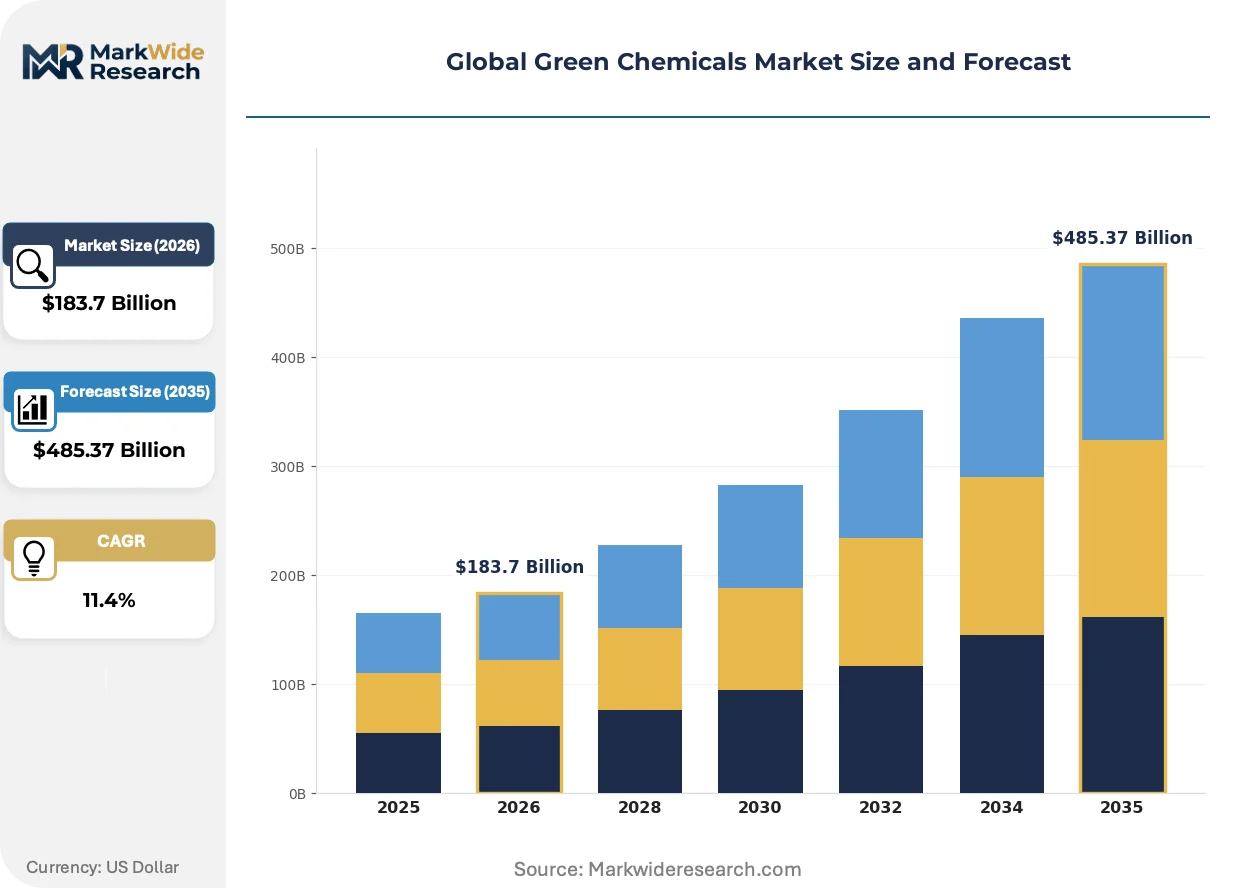
| Market Size in 2026 | $183.7 Billion |
| Market Size in 2035 | $485.37 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioplastics, Biofuels, Surfactants, Organic Solvents Application: Agriculture, Food & Beverage, Personal Care, Pharmaceuticals End User: Manufacturers, Retailers, Distributors, Consumers Technology: Biosynthesis, Fermentation, Chemical Processing, Photocatalysis |
| Companies Covered | BASF SE, Dow Chemical, DSM, Evonik Industries AG, Cargill Incorporated, DuPont de Nemours, Arkema, Braskem, Corbion N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Green Chemicals Market Emerging Trajectories
Biological manufacturing platforms are crossing cost thresholds that enable molecule-for-molecule substitution of commodity petrochemicals, while digital verification systems reshape how sustainability claims are authenticated and traded.
Continuous fermentation and cell-free enzymatic catalysis are displacing batch bioprocessing in platform chemical production. Specialty polymer manufacturers in Germany and the Netherlands are adopting these systems to reduce capital intensity and improve titer consistency. The shift is compressing minimum efficient scale thresholds, enabling regional distributed production models that reduce feedstock transport costs.
China's MEE dual carbon enforcement mechanism now mandates provincial-level carbon intensity reductions for chemical producers above specified output thresholds. This regulatory architecture is accelerating coal-to-biomass feedstock switching in Shandong and Jiangsu provinces. Domestic producers are responding by securing long-term agricultural residue supply contracts previously dominated by papermaking applications.
Certificate-of-origin purchasing is supplanting traditional spot-market chemical procurement among automotive OEMs and consumer electronics assemblers. Tier-1 suppliers in South Korea and Japan now maintain segregated inventory systems for bio-attributed versus fossil-origin feedstock lots. The practice is most visible in battery separator and flexible electronics substrate supply chains, where end-brand sustainability disclosure requirements cascade through multi-tier supplier networks.
Global Green Chemicals Market Segmentation
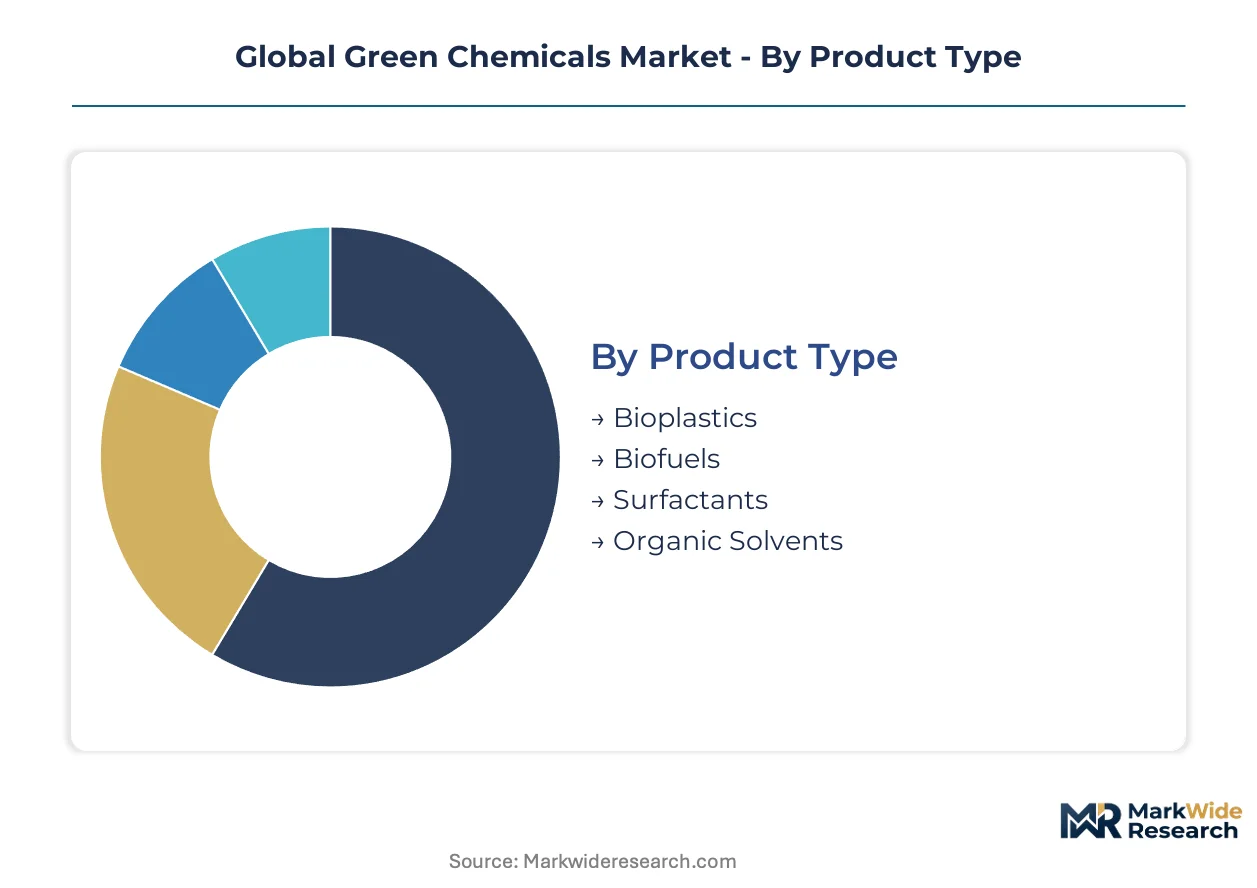
Segmentation in green chemicals reveals how regulatory thresholds, feedstock certification requirements, and end-use performance specifications fragment procurement pathways. Each dimension carries distinct compliance burdens and margin structures that reshape competitive positioning across supplier tiers.
Product Type:
REACH bio-based content thresholds and ASTM D6866 certification tiers create divergent qualification costs across molecular categories, concentrating contract eligibility among integrated producers with captive laboratory infrastructure.
- Bioplastics:Polylactic acid and polyhydroxyalkanoates dominate durable goods substitution, with PLA from fermentation-derived lactic acid capturing food packaging demand in Germany and France where single-use plastic bans have tightened. ECHA registration deadlines for petrochemical alternatives accelerate brand owner procurement of certified bio-attributed grades.
- Biofuels:Aviation alcohol-to-jet and renewable diesel pathways compete for limited carbohydrate feedstock pools. EPA renewable fuel standards and EU ReFuelEU Aviation obligations redirect capital toward commercial-scale fermentation capacity, though palm oil price volatility constrains fatty acid methyl ester margins.
- Surfactants:Alkyl polyglucosides and rhamnolipids face Malaysian and Indonesian feedstock cost swings.
- Organic Solvents:Electronics-grade bio-based N-methyl-2-pyrrolidone alternatives qualify for photoresist stripping in Taiwan and South Korea semiconductor fabs.
Established volume favors bioplastics; emerging adoption favors biofuels.
Application:
End-use performance specifications determine which green chemistry platforms achieve molecule-for-molecule substitution at acceptable unit economics.
- Agriculture:Biopesticides and biostimulants from agricultural residue fermentation displace synthetic agrochemicals where EU Farm-to-Fork targets restrict active ingredient loads.
- Food & Beverage:Edible coatings and natural preservatives face FSSAI and FDA food contact compliance layers that extend qualification timelines beyond industrial chemical pathways.
- Personal Care:Bio-based surfactants and emollients navigate REACH restriction schedules in Germany and France where formulators face petrochemical phase-down deadlines.
- Pharmaceuticals:Fermentation-derived active pharmaceutical ingredients and excipients command premium pricing where EMA quality guidelines mandate chiral purity unattainable through petrochemical synthesis.
Personal care and food & beverage applications expand most quickly; pharmaceutical qualification timelines extend commercialization horizons.
End User:
Procurement sophistication varies sharply across buyer tiers, with certificate-of-origin requirements cascading differently through contract structures.
- Manufacturers:Automotive and electronics OEMs around Shanghai and Seoul mandate renewable feedstock certificates in supplier contracts, forcing tier-1 chemical suppliers to maintain segregated inventory systems for bio-attributed versus fossil-origin lots.
- Retailers:Private-label sustainability disclosure obligations drive spot purchasing of certified bio-based grades for consumer-facing product lines.
- Distributors:Inventory pooling across multiple certification tiers compresses margins unless volume concentration justifies dedicated handling infrastructure.
- Consumers:Direct purchasing remains limited to specialty niches where price premiums align with visible sustainability claims.
Manufacturer concentration favors integrated biorefinery suppliers; retailer fragmentation creates openings for specialty distributors with certification expertise.
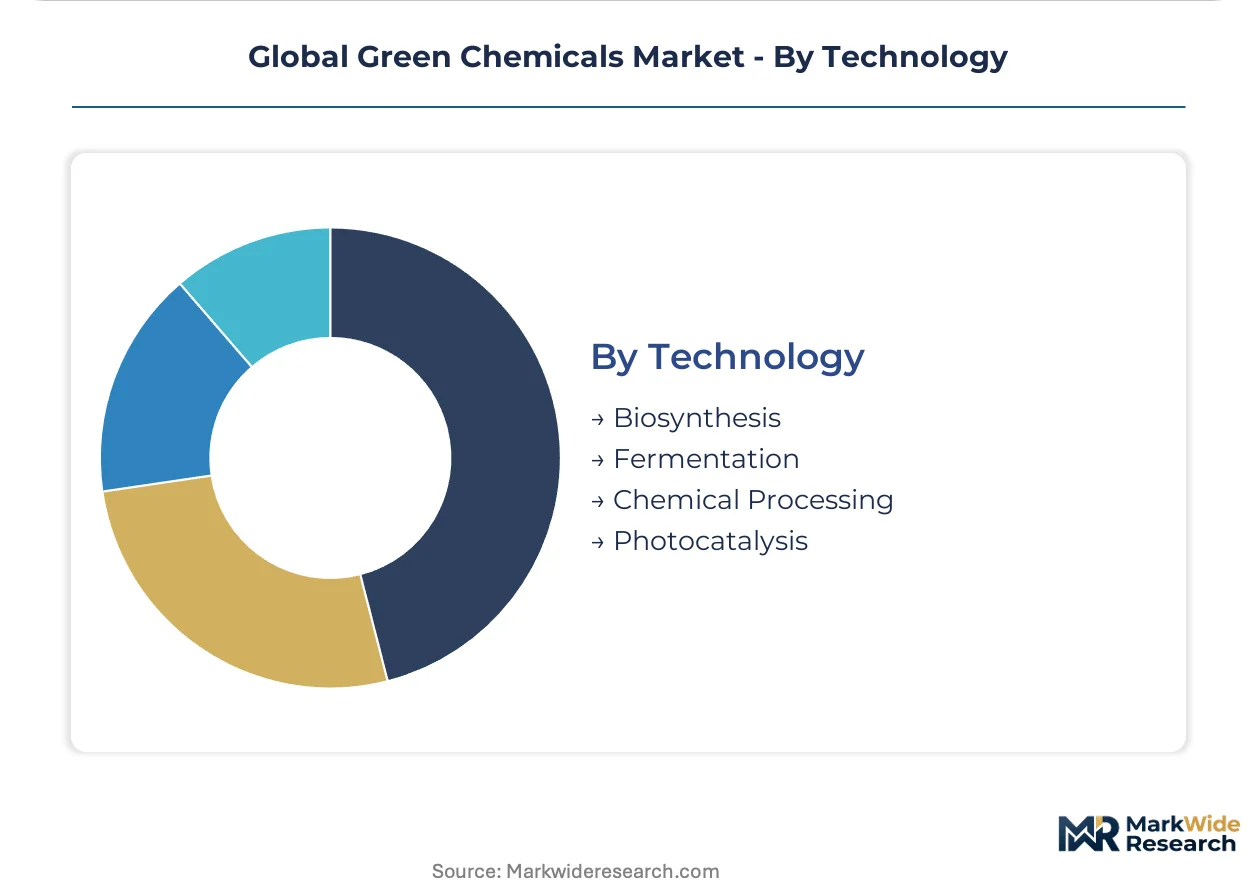
Technology:
Capital intensity and scale thresholds separate platform technologies, with continuous processing gains displacing legacy batch infrastructure.
- Biosynthesis:Engineered microbial chassis produce complex molecules from simple sugars, with synthetic biology advances reducing titer variability in Germany and Netherlands specialty polymer applications.
- Fermentation:Commercial-scale ethanol and lactic acid output dominates South American and European supply, though industrial biotech process engineer scarcity constrains capacity expansion timelines.
- Chemical Processing:Catalytic upgrading of bio-intermediates bridges fermentation output to performance-equivalent petrochemical specifications.
- Photocatalysis:Solar-driven carbon dioxide reduction remains pre-commercial, with power-to-liquid pathways dependent on stranded renewable electricity economics.
Fermentation holds established scale; biosynthesis gains share fastest as continuous processing reduces minimum efficient scale thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Botlek pipeline corridor underwrites Northwestern Europe's biorefinery integration, while the Yangtze River Delta's grid interconnects enable East Asian electrolytic hydrogen feedstock switching.
United States
EPA renewable fuel standards redirect Midwest ethanol capacity toward aviation alcohol-to-jet pathways. The Inflation Reduction Act's clean fuel production credits accelerate fermentation infrastructure deployment in Iowa and Nebraska. Houston's petrochemical corridor hosts power-to-liquid pilots leveraging stranded Texas wind generation.
Germany
REACH bio-based content thresholds compel Ludwigshafen and Leverkusen formulators to secure ASTM D6866-certified feedstock lots. The EU Green Deal's feedstock transition timelines strand legacy naphtha crackers in North Rhine-Westphalia. BASF's integrated biorefinery complex sustains captive polyamide supply for automotive OEMs.
China
MEE dual carbon enforcement mandates provincial carbon intensity reductions for Shandong and Jiangsu chemical producers above output thresholds. Agricultural residue supply contracts shift from papermaking to fermentation applications. Shanghai's electronics assemblers mandate renewable feedstock certificates in battery separator procurement.
Brazil
Sugarcane ethanol-to-ethylene output dominates South American bio-intermediate supply. ANVISA's bio-based pharmaceutical excipient guidelines extend qualification timelines for fermentation-derived active ingredients. São Paulo state's industrial biotechnology cluster attracts synthetic biology talent from European mid-cap specialists.
South Korea
Seoul-based automotive and electronics OEMs enforce segregated inventory systems for bio-attributed versus fossil-origin feedstock lots. MFDS pharmaceutical quality guidelines create premium pricing for chiral-pure fermentation-derived APIs. Busan-Ulsan's semiconductor fabs qualify bio-based N-methyl-2-pyrrolidone alternatives for photoresist stripping.
Global Green Chemicals Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure and captive feedstock access. The supplier base concentrates among integrated biorefinery operators with in-house ASTM D6866 laboratory capacity and fermentation specialists with verified Scope 3 data systems. Three archetypes dominate: diversified chemical conglomerates with backward integration into agricultural supply, pure-play fermentation technology licensors, and regional ethanol-to-olefins processors. Competitive moves center on strategic partnerships for feedstock security and technology licensing to compress qualification timelines.
Within the diversified chemical tier, BASF SE and Dow Chemical exemplify integrated biorefinery operators with captive laboratory infrastructure. Braskem anchors the regional processor archetype. Corbion N.V. occupies a position among pure-play fermentation specialists.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical |
| DSM |
| Evonik Industries AG |
| Cargill Incorporated |
| DuPont de Nemours |
| Arkema |
| Braskem |
| Corbion N.V. |
| Others |
Supply Flow & Price Mechanics
ISO 17021 certification requirements gate both supply qualification and price differentiation simultaneously, concentrating contract eligibility among integrated biorefinery operators while forcing mid-scale producers toward lower-margin uncertified tiers. ASTM D6866 radiocarbon testing bottlenecks compound this bifurcation, elongating qualification timelines and compressing pricing power for fermentation specialists without captive laboratory infrastructure.
Pricing Analysis
Certification level creates the primary spread between premium ASTM D6866-verified grades and uncertified commodity alternatives. Contract-based long-term offtake dominates, with pricing stratifying across premium certified, standard transitional, and economy fossil-origin tiers. Cost compression in surfactant segments is intensifying because Malaysian and Indonesian palm oil volatility undermines bio-based cost parity. Distributors and spot-market buyers exhibit highest price sensitivity; automotive OEMs with mandated renewable feedstock certificates show lowest.
Supply Chain Analysis
Strategic stockpiling of agricultural residue feedstocks prevails over just-in-time approaches, with producers securing multi-year supply contracts to hedge against papermaking competition. Supply concentrates in Brazil, the United States, and Germany, with carbohydrate feedstock anchored in Brazilian sugarcane ethanol and US corn starch. Raw material dependencies include sugarcane bagasse, corn starch, and Malaysian crude palm oil. Single-source vulnerability runs through Brazilian ethanol-to-ethylene output. Distribution feeds from integrated biorefinery complexes toward segregated OEM inventory systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certificate-of-origin verification services and Scope 3 emissions auditing represent expanding recurring-revenue layers growing faster than base chemical production, as EU CSRD disclosure obligations cascade through multi-tier supply chains.
For Market Incumbents: Fortify captive ASTM D6866 laboratory infrastructure to collapse qualification timelines for tier-1 OEM contracts. Deepen backward integration into agricultural residue supply through long-term offtake agreements in Shandong and Jiangsu provinces, preempting Chinese domestic producers. This counters emerging pure-play fermentation specialists with synthetic biology platforms.
For New Entrants and Emerging Players: Lead with electronics-grade solvent purity qualifications for Taiwan and South Korea semiconductor fabs, where photoresist stripping applications command premium pricing and incumbent penetration remains limited. Target white-space in captured carbon utilization pathways for regions with stranded renewable electricity. Pursue technology licensing partnerships to compress regulatory qualification timelines.
For Investors and Strategic Acquirers: EU ReFuelEU Aviation obligations reshape the acquisition landscape toward fermentation-derived alcohol-to-jet pathway operators with commercial-scale capacity. Long-term viability across the projection horizon favors integrated biorefinery operators with verified Scope 3 data infrastructure over pure commodity processors. The signal to watch is cross-border reciprocity achievement among certification schemes, which would unlock capacity expansion capital commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Long-term agricultural residue contracts in China preempt papermaking competition for fermentation capacity. |
| Green Manufacturing Transition | Continuous fermentation systems in Germany and the Netherlands reduce capital intensity for specialty polymer output. |
| Capacity Expansion | Commercial-scale alcohol-to-jet pathways in Iowa and Nebraska capture EPA renewable fuel standard credits. |
| Long-term Supply Agreement | Segregated inventory systems for bio-attributed feedstock lots satisfy Shanghai electronics OEM mandates. |
| Joint Venture | Synthetic biology partnerships with São Paulo industrial biotechnology clusters access fermentation engineering talent. |
Methodological Framework
The analysis maps bioplastics, biofuels, surfactants, and organic solvents, each validated through procurement leads at automotive and electronics OEMs, fermentation plant managers, biorefinery technical directors, and distribution channel partners. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up capacity and production estimates triangulated against top-down demand aggregation from end-use sector consumption patterns.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology platform, with additional granularity on certification tier and regional production hub. CAGRs derived from regression analysis of historical capacity deployment correlated with regulatory milestone timing. Forecast inputs incorporated aviation blend mandate trajectories and provincial carbon intensity enforcement thresholds.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of bio-based content thresholds would require recalibration. Forecasts reflect assumptions on certification scheme reciprocity achievement and feedstock supply security. Revision becomes warranted when palm oil price volatility or carbohydrate feedstock concentration risk crosses thresholds that undermine cost parity assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Pyruvate Market
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market